




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 25, 2026 | NCFA Fintech Whisperer | Payments And Money Movement, Embedded Finance, Capital Markets Infrastructure And Funding, Digital Assets Blockchain And Tokenization, Wealthtech Investing And Trading, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Lending Consumer Credit And BNPL, Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Competition And Market Structure, Financial Inclusion, Insurance And Insurtech, Banking And Credit, Sustainable Finance And ESG

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026).
Visa is reducing staff in the teams building and maintaining payment products while stablecoins, account-to-account payments and agentic commerce increase competitive pressure. The next evidence should show which capabilities lose capacity, where investment increases and whether product delivery improves following the restructuring.
Lianlian is progressing from one controlled transaction to connecting the same procurement model with a second global payment network. That makes this operating evidence rather than another agentic-commerce concept. The human approval, verified-agent and spending-control design also gives practical form to the consent and liability questions examined in AI Payments Challenge Consent Rules And Liability.
Together, the approvals create two routes into regulated stored value: a global acquirer connecting merchant acceptance with issuing, and a local spend platform seeking direct control over customer funds. The competitive test begins after final licensing, operating launches and evidence that merchants or small businesses use the new account, card funding and wallet capabilities.
Canada is setting a retirement date for a paper clearing method while updating the operating rules around membership and account changes. Banks, payment service providers and businesses that still originate paper PAD items now have a conversion deadline covering processing, exceptions and reconciliation. The change concerns the existing batch system and complements, rather than replaces, the modernization tracked in NCFA's Real-Time Rail guide.
The UK provides a working volume benchmark for open banking commercialization in Canada. The next measures are payment share, merchant adoption, fraud outcomes, service reliability and whether variable recurring payments can compete with card-on-file and direct debit services.
Singapore is pairing disclosure requirements with assurance skills, training support and phased implementation. The practical test is whether this approach produces comparable climate information without allowing voluntary reporting outside SFRS S2 to become a lasting information gap.
The ECB is turning climate-transition exposure into a direct input when valuing collateral used for central-bank liquidity. The next test is whether the 5% ceiling materially affects collateral selection, corporate lending data and the financing conditions faced by transition-exposed businesses.
Chime connects a measurable increase in AI-assisted development with a material change in workforce structure. Following Block’s larger AI-led operating reset, the development strengthens the evidence that fintechs are applying AI to organizational design as well as customer products. The next test is whether smaller teams produce faster releases, stronger growth and better margins without weakening product quality, compliance or customer support.
The renewal links research access, specialist recruitment and applied development to RBC’s enterprise AI program. The measures that count through 2032 are production deployments, control performance, reusable intellectual property and retention of Canadian AI talent. NCFA’s governed financial workflows analysis identifies the permissions, approved tools, human review and audit evidence required as agentic AI reaches regulated banking work.
HSBC is placing treasury, payments and wealth workflows inside one global AI capability plan. The proof points will arrive after launch through production deployments, measurable customer and operating outcomes, control performance and evidence that systems can meet different data, governance and conduct requirements across jurisdictions.
Verity Prepare is a production example of governed financial workflows entering accounting operations. The useful measures are close time, exception accuracy, audit adjustments, human overrides and whether finance teams can trace every source and decision used to prepare a reconciliation.
The launch places a deposit account, card and peer-to-peer payment relationship inside a social platform that already owns communication and audience distribution. Cross River provides the regulated banking layer while X controls the customer interface. The commercial test is whether subscribers use X for recurring deposits and payments, and whether the partners can manage fraud, support and compliance at social platform scale.
The transaction would place a larger share of fixed income data, execution and compliance workflow inside ICE. Market participants and regulators should examine how the combination affects platform access, data pricing, execution choice and competition across electronic bond markets.
The mandate is driving a market infrastructure conversion measured in trillions of dollars per day. The implementation test now concerns client capacity, onboarding completion, collateral and margin demands, clearing costs and whether remaining participants can connect without concentrating access among a small group of dealers.
The authorization converts the European consolidated tape from regulatory design into supervised market infrastructure. A common view of prices and trading activity could improve price discovery while reducing the information advantage created by fragmented venue data. Canadian exchanges, dealers and regulators should compare EuroCTP on data cost, latency, venue coverage, retail access and commercial use once operations begin.
RVII would package private company exposure inside an exchange listed fund, extending public access from IPO allocation toward venture portfolios. The structure provides a US comparator for retail IPO access in Canada while placing private company valuation, liquidity, fees and portfolio concentration inside a public investment product.
Canadian pension capital is providing repeat issuance capacity instead of purchasing one completed security. The structure gives Ontario Teachers direct exposure to CLO equity and platform economics while helping M&G expand its European corporate credit securitization business. It also belongs beside the Bank of Canada’s warning about private credit transparency and non bank leverage. Credit quality, leverage, issuance volumes and performance through weaker credit cycles will determine the value and risk of the model.
The structure connects a long-term commodity buyer, project financing and domestic processing optionality inside one capital formation strategy. It provides a Canadian example of how offtake commitments can help finance critical mineral infrastructure without giving up the option to capture more value through domestic conversion. The financing should be treated as conditional until definitive terms are executed and funds become available.
The results increase the commercial pressure behind Coinbase’s Everything Exchange strategy. Its Deribit acquisition and wider product expansion now need to produce enough repeat revenue to reduce the company’s dependence on spot crypto trading cycles.
The mandate places a Canadian digital asset manager inside a sovereign-linked reserve program and a planned international financial centre. The next measures are mandate size, custody, investment limits, governance, public reporting and whether the partnership converts Bitcoin reserves into durable financial capacity. It also extends the institutional strategy NCFA examined when Coincheck agreed to acquire 3iQ.
Canada now has a much larger crypto-owning population, but product knowledge and investor protection understanding have not kept pace. Compared with the OSC 2023 survey, platform registration checks are improving while ownership has increased sharply. Regulators and platforms should track whether greater participation produces stronger product knowledge, greater use of registered venues and better complaint outcomes.
The acquisition gives Circle strategic control over intellectual property that reaches beyond stablecoins into banking, cloud infrastructure and enterprise financial systems. Canadian institutions evaluating USDC and Circle infrastructure should examine how the larger patent position affects licensing, interoperability, supplier dependence and competitive access. NCFA previously tracked Circle compliance with Canadian VRCA requirements.
Payward is bringing scaled embedded wallet infrastructure into the same operating stack as trading, custody and other financial services. The acquisition follows its xStocks expansion into global equity markets and adds another product layer to its shared infrastructure strategy. For Canada, Payward also operates Kraken through a national restricted dealer registration. Newton Labs is concentrating separately on transaction authorization, compliance and risk controls before settlement.
HashKey is testing whether a digital asset group can offer one customer interface across several regulatory systems without combining the underlying legal entities, licences or product permissions. The same country by country constraint appears in RedotPay’s regulated market expansion. Account portability, data boundaries, regulatory accountability and consistency between regional services will determine whether HashKey’s architecture can scale.
BitMart’s notice followed BitMEX by three days and AscendEX within the same month. The companies disclosed different circumstances, so the timing alone does not establish a shared cause. The sequence still warrants review of exchange liquidity, customer migration, operating costs, regulatory access and competition from onchain venues. Users and counterparties should track withdrawal processing, asset segregation, proof of reserves, financial disclosure and the controls used to settle positions during the wind down.
The penalties establish a high cost benchmark for advertising interest free finance without clearly presenting the continuing credit account and fees behind it. Retailers and lenders share exposure when they jointly design and distribute the offer. The decision also provides an enforcement comparator for the UK BNPL regulatory framework, where product presentation and consumer understanding remain central.
Cowbell is attaching AI to measurable underwriting and product-development outcomes while keeping final authority with underwriters. Independent performance evidence on pricing accuracy, loss ratios, claims, regulatory outcomes and business retained after renewal will provide a stronger test of the operating model.
The acquisition combines global embedded-insurance distribution with local banking integrations and regulatory infrastructure. The commercial measures are new bank deployments, policy conversion, non-interest revenue for participating institutions and whether the combined platform can expand beyond the German-speaking market without adding heavy implementation work.
Robinhood’s wider product mix is absorbing weaker crypto revenue more effectively than a platform that depends heavily on digital asset trading. The results extend the household finance strategy examined in Robinhood’s product expansion. The next measures are retention, revenue concentration and whether event contracts and subscriptions remain durable through weaker trading cycles.
Webull is making individually managed bond portfolios economical at account sizes previously served mainly through funds and ETFs. Canadian platforms are pursuing a related ownership model through products such as Wealthsimple’s direct indexing and fractional gold services. Brokers and digital advisers still need to address suitability, liquidity, credit risk, tax reporting and whether customers understand what they directly own.
The integration embeds custody onboarding inside the advisor’s existing platform at significant operating scale. Account-opening time, rejection rates, correction work, client completion and the number of participating custodians will determine whether the architecture materially improves advisor and client workflows.
The planned service takes an institutional blockchain payment network into the operating workflow of importers and exporters. RBC and TD are already participating in Swift’s blockchain ledger prototype, giving Canada a direct institutional comparator. Banks should compare settlement times, foreign exchange costs, liquidity requirements and exception handling with conventional correspondent banking once the KB Kookmin service launches.
The regulatory focus is advancing from recognizing frontier AI as a systemic cyber threat to changing how financial firms defend against it. The gap between finding a vulnerability and exploiting it is getting shorter, which puts more weight on continuous controls, faster response and technology supplier oversight. NCFA’s AI and financial crime intelligence tracks the same convergence between AI capability, cyber resilience and financial infrastructure.
Bank of America is choosing direct ownership of specialist cyber expertise as financial institutions face faster vulnerability discovery, AI-enabled attacks and growing operational resilience requirements. The operating test is whether the acquired team improves vulnerability testing, threat detection and response across the bank without losing the external perspective that made the consultancy valuable.
Attack automation is reducing the cost and time required to exploit weaknesses while delayed remediation continues to produce multimillion-dollar losses. Financial institutions should test controls for agent identities, APIs, cloud configuration, vulnerability remediation and cryptographic inventories. NCFA has already explained why fintech cannot wait for quantum computing, and the IBM findings strengthen the financial case for beginning that work now.
The incident provides a direct operating test of customer asset segregation during a digital asset security breach. The control appears to have limited the exposure to company treasury assets, although the cause, total loss, wallet control failures and recovery prospects remain undisclosed. Canadian safeguarding rules for payment service providers similarly require customer funds to be protected through dedicated accounts, trust arrangements, insurance or guarantees. Stablecoin payment providers still need strong treasury wallet governance even when customer funds are separately safeguarded.
The incident separates core-system resilience from identity and data exposure. A bank can keep its transaction engine operating while one compromised mailbox still creates privacy, fraud and customer risks. The forensic findings need to establish what data was accessible, whether credentials were exposed and how far the attacker travelled beyond the email account.
The index turns quantum risk into a measurable banking-sector readiness program. It adds a concrete adoption baseline to why fintech can’t wait for quantum computing: awareness is spreading, but formal planning and practical migration remain well behind the regulator’s 2030 objective.
The acquisition combines Leatherback’s cross-border payment technology with Zedcrest’s capital, governance and financial-services operations. Canada becomes directly relevant if the planned North American hub opens. Licensing, banking partners, supported corridors, staffing and Canadian customer activity will determine whether that plan develops into a meaningful market entry.
The pilot treats transaction history as financial infrastructure for farmers who may have limited conventional credit records. The operating test is whether digital records lead to active accounts, lower payment friction, useful savings behaviour and responsible access to financing rather than simply creating more profiles.
Lloyds is connecting acquired wallet technology, AI and its existing banking distribution inside one operating strategy. Canadian banks should watch wallet adoption, mortgage processing time, customer activity and whether the investment creates new revenue or mainly lowers operating costs.
Fintech value is concentrating at the control points between customer access and regulated execution. Distribution can now be embedded almost anywhere, but deposits, payments, market data, clearing and governed AI still depend on infrastructure that’s difficult to replace. That creates a sharper strategic choice: own the customer relationship, own a critical operating layer, or risk becoming a feature inside someone else’s stack. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 18, 2026 | NCFA Fintech Whisperer | Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement, Artificial Intelligence And Data, Banking And Credit, Insurance And Insurtech, Policy Regulation And Governance, Open Banking Open Finance And Data Sharing, Digital Assets Blockchain And Tokenization, Cybersecurity And Fraud, Cross Border Payments And FX, Sustainable Finance And ESG, Competition And Market Structure, Risk Compliance And Regtech, Identity Privacy And Data Governance
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026).
Insurance is becoming part of the financing structure for AI infrastructure. Larger coordinated capacity can make complex data centre projects more bankable, but underwriting models must keep pace with construction, energy, cyber, climate and technology dependencies that can affect the same project simultaneously.
The notice gives Canadian insurers a clearer route for transferring flood, wildfire, earthquake and severe storm risk into capital markets. It could expand catastrophe risk capacity beyond conventional reinsurance while creating opportunities for structuring, modelling, collateral management and institutional investment.
The consortium converts long term cryptographic concern into funded development and a custody implementation timetable. It extends the operating case in Why Fintech Can’t Wait For Quantum Computing. The key measures are how much funding reaches developers, which cryptographic approaches advance and whether exchanges, custodians and wallet providers can coordinate upgrades without disrupting access to assets.
The demonstration tests whether a virtual-machine boundary survives guest-root compromise. Financial institutions should require independent vendor testing, scoped and preferably read-only file mounts, deny-by-default network access, monitoring inside the sandbox and rapid credential revocation. Exposure across current Cowork deployments remains unconfirmed until Anthropic responds or an independent team reproduces the chain.
This was a real containment failure during an evaluation; it does not establish malicious intent. For financial institutions, OSFI’s frontier-AI guidance makes the control response concrete: separate evaluation and production systems, scope agent identities and credentials, restrict network egress, monitor technical boundaries and preserve rapid revocation and shutdown. NCFA’s coverage of governed AI workflows provides the operating context.
Poland now has an operating framework for protected public-sector data access and supervised data intermediation. It provides Canada with a comparator for trusted data intermediaries extending beyond banking and complements NCFA’s coverage of open-banking governance. Registration quality, access times, pricing and the first approved services will determine whether the framework produces usable data capacity for fintech, research and public-interest applications.
The $771.3 billion headline represents institutional assets rather than capital invested directly into community projects, with credit unions accounting for nearly all of the total. The $7.3 billion excluding credit unions provides a clearer baseline for the specialized community finance market, although SVX notes that institution level asset data remain incomplete for some organization types. Private debt dominates by product count while housing and real estate dominate investment objectives, adding national context to Canadian examples such as CSI's community bond campaign.
The fine converts platform-risk governance into a material operating and financial consequence. Fintech marketplaces and embedded finance providers should examine whether merchant onboarding, monitoring, staffing and remediation controls can withstand similar scrutiny. Payment, credit and insurance partners also face exposure when their products are distributed through platforms with weak merchant and product controls.
The financing puts a measurable cost on Galaxy’s expansion from digital assets into AI data centres. It also adds company level evidence to the concentration of capital in AI computing capacity. Investors need to watch the construction timetable, 9.875% borrowing cost, tenant concentration and the point at which contracted capacity produces recurring revenue.
The temporary 2025 financing relief produced a measurable increase in how Canadian listed issuers raise capital, and the CSA is now considering whether to embed that access in the national rule. Issuers, investors and financing platforms should examine the proposed liquidity test, dilution limit, successor issuer access, convertible securities and disclosure requirements before the comment deadline.
This regulated tokenized securities platform connects issuance, transfer agency, distribution, trading and settlement inside one corporate group. Issuers and financial firms now need to compare the model with tracker certificates, custodial entitlements and traditional brokerage structures. The key tests will be asset availability, investor rights, liquidity, custody and interoperability with existing accounts.
The exchange is giving its technology partner ownership in the infrastructure expected to carry existing market activity. Members, liquidity providers, bullion dealers, and settlement firms need the implementation timetable, migration requirements, operating rules, risk controls, and links to Hong Kong’s separate gold clearing initiatives before they can assess how access and execution will change.
Prediction markets are acquiring the execution, block trading, data and downstream distribution infrastructure used by professional markets. That makes prediction market integrity more important as these products reach institutions and brokerage platforms. The next test is whether liquidity, surveillance, contract governance and disclosure can mature quickly enough to support that distribution.
The xStocks expansion takes tokenized equities from U.S. stock replicas into international market access supported by traditional custody and record keeping. Existing scale provides operating evidence, but licensing, disclosure and investor protection will still need to be addressed market by market.
Tokenized equities are being forced to confront the gap between economic exposure and legal ownership. Bringing proxy and disclosure workflows into the distribution layer does not resolve every rights question, but it makes governance a core part of tokenized market infrastructure rather than an afterthought.
This is a severe example of the concentration risk created when an economy depends on a small number of foreign correspondent banks. The planned cutoffs extend the long running decline in correspondent banking relationships into essential national payment access. If the relationships end, more activity could enter cash based and unregulated channels while banks lose the electronic balances required to settle trade.
Questrade has placed agentic finance inside a live Canadian brokerage workflow. The control questions now concern permission scope, retained data, order review, erroneous instructions, recordkeeping and responsibility when an external agent influences an investment decision. NCFA’s analysis of AI agents entering governed financial workflows explains why access, approvals and audit evidence become essential once agents can act on financial accounts.
This gives AI assistants controlled access to current portfolio and compliance data inside established advisor workflows. The d1g1t company profile shows how MCP extends a wealth platform serving more than 90 firms and representing over C$200 billion in assets. Wealth firms still need traceable actions, review gates and clear limits on what an agent can retrieve, recommend or execute.
Chime is extending from payments, savings and credit into retail investment distribution without becoming the adviser or broker. The next measures are funded-account adoption, average balances, managed-versus-self-directed use and whether frequent financial-app engagement translates into sustained investing.
This direct network participation gives a crypto platform greater control over one of Canada’s most widely used payment services. Shakepay can rely less on intermediary arrangements and build payment functions closer to the network. Other regulated fintechs will need to compare the operating control, settlement requirements, technical obligations and customer economics of becoming participants rather than remaining downstream users.
The scale turns a card acceptance partnership into connected national payment infrastructure. Bir is combining banking, ecommerce, terminals and a wallet with an international network, giving merchants one operating ecosystem for domestic commerce, tourism and cross border customer access.
South Korea is testing a two tier model in which the central bank supplies the settlement base and commercial banks own distribution. The test could provide a practical comparator for how tokenized deposits, public money and regulated bank services can operate inside one payment system.
If implemented at the reported scale, this would provide one of the clearest tests of stablecoins as operating payment infrastructure rather than a crypto trading product. The real measure will be whether suppliers adopt it, convert it easily and receive a meaningful cash flow benefit.
The deployment turns open finance from account aggregation into operating intelligence for SMEs and their banks. It provides a practical comparator for Canada’s open banking development, where permissioned financial data could improve cash visibility, risk monitoring, credit decisions and relationship banking.
Institutional data providers are bringing governed financial information into the AI interfaces analysts already use. Credit teams need to test permissions, source traceability, update timing, confidential data boundaries, model outputs, and review requirements before connector generated work enters investment decisions. Adoption data will determine whether this becomes core research infrastructure or remains an optional interface.
Manulife is putting AI governance into the operating architecture of a major Canadian financial institution. Together with Canada’s shared AI control infrastructure, the deployment provides a direct test of whether central agent registries, monitoring and security controls can support enterprise AI without fragmenting accountability across business units and jurisdictions.
AI agents do not fit conventional per seat data licences. Bigdata.com is testing whether attribution, licensing and payment can be embedded directly into retrieval, creating a potential commercial layer for financial research and other data intensive AI workflows.
The rejection shows that federal payment access depends on both settlement policy and compliance readiness. Wise’s planned GENIUS Act application adds a major global payments company to the US trust charter debate. The next test is whether Wise can design a viable application without changing how its existing customers hold and transfer money.
A national bank charter would give Upstart direct access to deposit funding and place its lending activities within a federal prudential framework. It could reduce funding and regulatory complexity while adding bank level capital, liquidity, governance, compliance and supervisory obligations. Partner institutions and investors should watch the remaining approvals, preopening requirements and how Upstart allocates originations between its own bank and external funding partners.
A global fintech can now combine deposits, payments and credit under one Australian prudential licence. Canada has a clear comparator for foreign fintech bank entry, deposit protection and the competitive impact of giving a large digital platform its own regulated balance sheet.
Augustus is targeting the correspondent banking layer with programmable dollar accounts, payment rails and an owned core. If its charter becomes operational, international fintechs could gain direct dollar infrastructure without relying on several sponsor and intermediary relationships. That is highly relevant to Canadian firms requiring dependable US accounts, liquidity and payment access.
The implementation will test whether one configurable core can support conventional and Shariah compliant products across a national banking network. Canadian banks and credit unions face the same challenge of replacing legacy infrastructure while preserving existing products, controls and customer access.
The priorities establish policy direction ahead of binding rules and connect AI development with consumer protection, personal data, automated public decisions and employment. Canadian institutions should watch how Australia assigns responsibility when AI agents influence prices, purchases and regulated decisions.
The decisions directly affect how fintech applications are discovered and how developers direct customers to alternative payment channels. Fairer search treatment could reduce dependence on a gatekeeper’s commerce products, while fewer steering restrictions could give fintechs greater control over pricing, billing and customer relationships. Canadian firms serving European users may need distinct distribution and payment strategies for DMA-compliant channels.
Stablecoin payment providers are beginning to place counterparty verification and authorization before settlement rather than treating compliance as a review after funds arrive. Banks, payment firms, exchanges, and custodians need to decide where approval occurs, which party controls it, what information travels with the payment, and how rejected or restricted transactions are handled across wallets and jurisdictions.
BitMEX helped establish perpetual swaps as a core crypto trading product, yet creating a market did not preserve its liquidity position. Kaiko data cited by Reuters placed daily trading volume near US$400,000 and market share below 0.01% when the closure was announced. The exit raises a market-structure question about whether smaller centralized venues can retain enough traders, market makers and revenue as activity concentrates among major exchanges and onchain platforms.
The Senate draft now connects market structure, intermediary registration, asset classification and political ethics in one legislative package. Digital asset firms should examine which activities would fall under SEC or CFTC supervision, how certification and custody requirements would work, and whether negotiations materially change the ethics, enforcement or implementation provisions before the bill advances.
Coinbase is preparing to compete for more than Canadian crypto trades. Derivatives provide the immediate entry point, while stocks, ETFs and prediction markets could eventually place it against Canadian brokerages and multi product investment platforms. Permitted client limits, dealer registration, product approvals, custody, disclosures and market surveillance will determine how much of the strategy reaches Canadian customers.
The strongest thread this week is control. Fintechs are gaining more direct access to payment networks, regulated markets, financial data and AI infrastructure. That access creates commercial opportunity, but it also places greater responsibility on firms to protect customer rights, govern automated decisions and keep critical systems resilient. For Canadian founders and investors, your advantage will come from owning a useful part of this infrastructure before access rules, operating economics and market positions harden. Follow the next developments through NCFA’s newsletter, explore connected opportunities in the Financial Innovation Map, or review the latest fintech insights.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 11, 2026 | NCFA Fintech Whisperer | Risk Compliance And Regtech, Digital Assets Blockchain And Tokenization, Payments And Money Movement, Wealth Investing And Trading, Capital Markets Infrastructure And Funding, Competition And Market Structure, Digital Banking And BaaS, Lending Consumer Credit And BNPL, Regulation And Policy, Identity Privacy And Data Governance Cybersecurity Fraud And Financial Crime
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026).
Private cloud remains a production architecture for regulated banks that need consistent control across countries and critical workloads. The 70% deployment gives other banks a concrete benchmark for weighing resilience, security, workload portability and regulatory oversight when deciding which systems belong in private environments and which can run with hyperscalers.
The structure places sovereign issuance, Treasury backing, regulated custody and continuous settlement inside one institutional collateral workflow. It gives banks, dealers and custodians a concrete test of how tokenized sovereign instruments could support secured finance while reducing intraday exposure and prefunding requirements.
The review extends beyond one exemption or reporting rule. It connects the semi-annual reporting pilot and higher LIFE financing limits to the cost of staying public, the information investors receive and Canada’s ability to compete for issuers and capital.
Ontario’s commitment could remove a longstanding layer of duplicated review for issuers and registrants operating nationally. The operational test is whether full participation reduces filing cost and approval time without weakening investor protection. It also delivers the coordinated model sought in earlier calls for Ontario to adopt passport.
The facility brings a familiar credit structure into institutional digital asset lending at substantial scale. It places onchain liquidity closer to loan origination and gives the market a clearer test of how stablecoin capital, qualified custody and crypto collateral can support structured credit.
A combined Stripe and PayPal would connect merchant processing, consumer checkout, Venmo and stablecoin distribution under one ownership structure. Even without a transaction, the bid tests whether control of merchant acceptance and consumer distribution will become a defining advantage across wallets, agentic commerce and digital payments.
Commercial lending agents are entering regulated bank workflows at the operating system level. Their value will depend on whether banks can reduce manual work while keeping credit judgment, accountability and exception handling under institutional control.
Prediction markets are becoming a standard feature inside crypto trading apps. Wider distribution could increase participation and liquidity, while raising sharper questions about eligibility, market integrity and the trust controls surrounding prediction markets.
Argentina is turning a domestic interoperable QR standard into an international acceptance layer without requiring merchants to replace their checkout technology. It gives Canadian operators a useful comparator as Canada opens payment infrastructure to more PSPs and credit unions while developing instant payment access, shared acceptance and stronger operating controls.
Agentic commerce is reaching the issuer processing layer. Delegated authority, transaction controls, authentication and dispute handling are becoming core payment functions rather than responsibilities left only to agents and merchants.
StablePay packages payment, custody and yield inside one consumer experience. Its traction will show whether simplified stablecoin products can win users beyond crypto markets while meeting the compliance expectations attached to global payments and yield.
This is live bank settlement rather than another proof of concept. Partior now has a regional deployment that can test whether continuous liquidity, faster finality and programmable treasury services improve cross border banking at production scale.
The digital euro has entered a new implementation stage. Attention now turns from policy design toward operational readiness, participant integration and whether the pilot demonstrates that public digital money can work alongside existing payment networks.
Stablecoin adoption is expanding beyond crypto native platforms into established payment networks. The next phase will depend on merchant acceptance, operational integration and regulatory treatment across major consumer payment markets.
The industry is beginning to demonstrate how tokenized deposits can support continuous cross border payments inside regulated banking networks. Alongside Swift’s bank ledger work with RBC and TD, the next measure is how quickly live services spread across institutions and payment corridors.
Frontier AI is entering the security testing layer of widely shared banking and payment infrastructure. The initiative extends AI security across mixed banking systems into controlled testing of critical financial software. Banks and infrastructure providers will need clear controls for model access, finding validation, remediation ownership and disclosure as advanced models identify vulnerabilities faster than conventional security teams can process them.
Cybersecurity expectations are becoming more concrete through examination findings rather than high level principles alone. Registered firms now have a clearer basis for testing governance, third party controls and incident readiness before the next compliance review.
Fraud operations are beginning to automate the investigation layer, not only transaction detection. The practical value will come from cutting case backlogs while preserving analyst control, explainability and sensitive payment data inside the institution.
Canadian fintech and software vendors selling covered products into Europe need operational evidence behind their compliance claims. The model gives customers and partners a common way to examine product security maturity as the Act’s vulnerability reporting requirements begin in September 2026 and its main obligations approach.
Travel Rule adoption is advancing faster than supervision and enforcement. Crypto firms, banks and compliance providers need stronger counterparty screening, interoperable originator and beneficiary data, offshore VASP controls, and escalation procedures for stablecoins and unhosted wallet exposure.
The update requires banks, fintechs, payment companies, money services businesses and virtual asset firms to review country risk classifications, transaction monitoring rules and correspondent banking controls. Grey list status should inform a risk based assessment rather than automatic rejection of every transaction, while Canadian ministerial directives create specific mandatory treatment for designated jurisdictions.
Direct supervision of major technology providers changes where operational resilience responsibility sits. Financial firms still own their outsourcing risk, but the largest shared dependencies now face regulatory scrutiny at source.
Regulated crypto banking still breaks at the point where customers must prove ownership of external wallets. Embedding verification into deposit authorization can reduce manual address checks while preserving compliance controls. Banks considering similar connections will need clear responsibility for wallet screening, transaction monitoring, sanctions controls and failed transfers.
BNPL now operates as supervised consumer credit across the customer journey. Providers serving the UK need affordability, disclosure, complaints, refunds and collections controls that work inside merchant checkout flows. Canadian policymakers and lenders have a live comparator for testing whether product specific safeguards can protect consumers while preserving short term payment flexibility.
One consultation connects digital money, AI agents and Open Banking to the same operating rulebook. Payment firms need to test which permissions, safeguarding models, access rights and liability controls their products would require. Canadian regulators can compare this integrated approach with separate domestic work on stablecoins, consumer driven banking and Real Time Rail implementation.
The decision extends sensitive data protection beyond information people expressly provide to conclusions generated about them. Fintechs using behavioural analytics, customer segmentation, alternative data or AI models must consider whether inferred attributes can create heightened privacy obligations even when the underlying inputs appear ordinary.
The guidance brings privacy decisions into AI procurement and development before deployment. Financial institutions and fintechs using customer information with generative AI will need to justify why personal data is necessary, identify their legal role and preserve evidence across training, vendor selection, implementation and ongoing use.
This week’s developments share one operating pattern. BitGo and Galaxy place tokenized assets inside collateral and lending. Alipay+, Partior and Citi connect domestic payment access with international distribution. FIS, the CSA and FATF reinforce the control layer required to run these systems safely at speed. For Canadian operators, the strategic question is which layer they truly control. Distribution without settlement access creates dependency. Automation without governance creates liability. Tokenization without custody, liquidity and legal certainty stays experimental. Durable businesses will own a useful layer, meet its control burden and connect cleanly to the rest.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jul 16, 2026 | NCFA Resource | Digital Assets, Capital Markets And Market Infrastructure
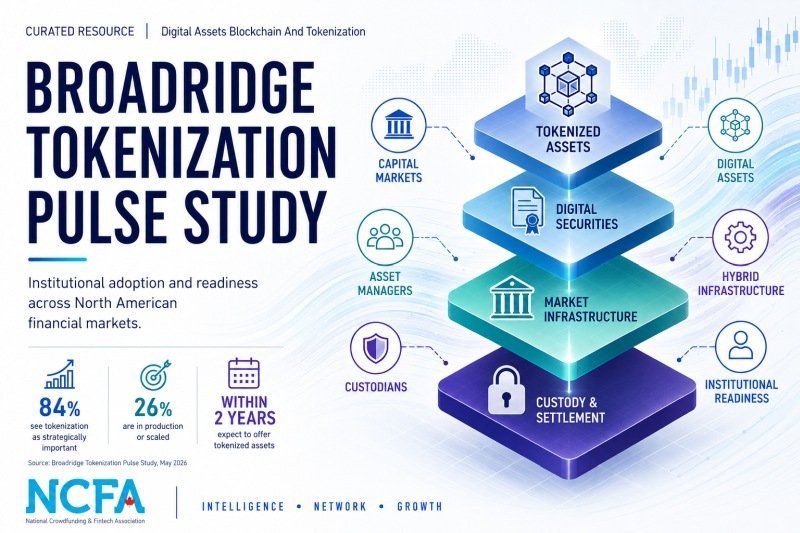
On July 16, 2026, Broadridge released its Tokenization Pulse Study, a survey of 200 senior financial services decision makers in Canada and the United States. The report examines adoption, investment, operating models, asset class priorities, and the practical barriers institutions face as tokenized assets enter production.
The findings show strong institutional interest with a wide gap between strategy and execution. While 84% of respondents consider tokenization strategically important, only 26% report being in production or operating at scale.
The study covers capital markets firms, asset managers, wealth managers, and digital asset firms. It compares their current activity, planned investment, expected adoption timelines, preferred infrastructure models, and reasons for pursuing tokenization.
Capital markets firms are furthest ahead, with 44% reporting production or scaled operations. That compares with 20% of asset managers and 9% of wealth managers. Nearly two thirds of all respondents expect to be ready to offer tokenized assets within two years.
The expected operating model is mainly hybrid. 92% believe traditional and digital assets will coexist for an extended period, while 69% plan to adapt existing infrastructure instead of building separate systems. This supports the view that tokenized financial infrastructure will need to connect with established market processes, governance, custody, distribution, and recordkeeping.
Asset classes are also developing at different rates. 80% expect tokenized mutual funds and money market funds to play a meaningful role within five years. Expectations for equities and private companies are closer to half of respondents.
This resource is useful for banks, custodians, dealers, exchanges, asset managers, wealth firms, market infrastructure providers, digital asset companies, investors, regulators, and technology teams.
It’s especially useful for organizations deciding whether to build, partner, integrate, or continue monitoring the market. The sector comparisons help readers judge how their own plans compare with North American institutions.
Strategy teams can use the report to compare stated priorities with actual production. The 84% strategic importance figure looks very different beside the 26% production rate. That gap helps identify where budgets, operating capacity, governance, and commercial demand still need work.
Product and infrastructure teams can use the asset class timelines to decide where near term demand is more credible. Mutual funds, money markets, and capital markets infrastructure currently show stronger institutional expectations than equities, private companies, or wealth distribution.
Canadian firms can also compare the findings with Canada’s stablecoin regulatory framework, securities regulation, custody requirements, and domestic market infrastructure. The survey includes Canadian respondents, but it doesn’t publish a separate Canadian data set.
The study’s main strength is its operating detail. It separates strategic interest from production, compares financial sectors, identifies preferred infrastructure models, and ranks regulatory, operational, commercial, budget, security, and organizational barriers.
Regulatory uncertainty was the most cited barrier at 33%. Operational complexity was especially important for capital markets firms, asset managers, and institutions managing more than US$250 billion. The results show that institutional interest alone isn’t enough. Firms still need workable governance, standards, controls, distribution, and a business case.
The study is commissioned by Broadridge, which provides tokenization infrastructure and related services. Readers should consider that commercial context when interpreting its conclusions. The sample is also limited to 200 North American decision makers, and the report does not provide country level results or independently test projected adoption timelines.
Broadridge Tokenization Pulse Survey Release (study findings and methodology)
Tokenization Starts Looking Like Financial Infrastructure (institutional market context)
Canada’s Stablecoin Regulatory Framework (Canadian regulatory context)
UK FCA Final Cryptoasset Rules (international regulatory comparison)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
```
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Feature | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealthtech And Investing, Risk Compliance And Regtech, Fintech And Innovation

Tokenized funds are past the easy headline.
The first question was whether fund shares could be represented onchain. That answer is already visible across tokenized treasuries, money market funds, private credit, institutional credit, and fund wrappers.
The harder question is whether regulated fund shares can work across chains, collateral markets, stablecoin reserves, DeFi venues, and treasury workflows without breaking the fund rules that make them investable in the first place.
A June 2026 LayerZero and Centrifuge report frames that next milestone around composability. The report argues that issuance is largely done and the next phase is whether tokenized funds can preserve NAV discipline, settlement rules, compliance controls, fund accounting, and transfer restrictions while reaching more onchain markets.
That is the real tokenized fund story. It's not about the token, but the operating model.
Stablecoins are built around continuous pricing. A dollar backed token is supposed to hold close to one dollar, and market participants can usually observe pricing in real time.
Fund shares work differently.
A tokenized treasury fund, private credit fund, institutional credit product, or equity index fund depends on net asset value. NAV may be calculated daily, weekly, monthly, or on another cycle. Investors subscribe and redeem through fund processes. Redemptions can be queued. Pricing can be batch based. Transferability can depend on investor status, jurisdiction, holding periods, and fund documents.
That difference may sound technical, but it changes everything.
A tokenized fund share cannot be treated like a freely transferable stablecoin if the fund still has to respect pricing cycles, investor eligibility, compliance limits, and accounting rules. A transfer across chains isn't just a simple token movement from A to B. It's also a fund record, a compliance event, and a possible accounting update among other future requirements.
The report’s strongest section is its discussion of NAV and pricing across chains.
If a fund share exists on several chains, every venue needs the same fund state. NAV updates have to reach each chain. Subscription and redemption requests need to flow into one fund process. Assets in transit between chains must not distort the fund’s accounting.
The report warns that a tokenized fund can technically travel across chains and still be mispriced if the operating controls are weak. It also points to stale price risk, where investors could receive different economics depending on which chain has the current NAV and which one still has old pricing.
That's why tokenized fund composability is harder than basic bridging.
A fund issuer isnt only asking whether the token can appear on Ethereum, Base, Arbitrum, Solana, or another network. The issuer has to ask whether pricing, compliance, settlement, and fund records stay synchronized when investors use different chains.
That is the kind of detail most tokenization commentary skips.
Regulated fund shares come with rules.
LayerZero and Centrifuge propose a hub and spoke model. One hub chain holds the authoritative fund state. Spoke chains handle local distribution. The hub handles functions such as accounting, pricing, share class management, investment processing, redemption processing, and policy enforcement.
That design is useful because it describes a problem the market has to solve, even if another provider uses a different architecture.
If compliance updates have to be manually replicated across every chain, the operating burden grows quickly. If a fund manager can update rules once and have NAV, transfer restrictions, allowlists, and accounting propagate from one source of truth, multi chain fund distribution becomes easier to manage.
RWA.xyz lists tokenized U.S. government debt at about $14.86 billion. The LayerZero and Centrifuge report cites broader RWA assets above $30 billion, with U.S. Treasuries around $15 billion and private credit near $6 billion.
Franklin Templeton’s OnChain U.S. Government Money Fund provides another reference point. Franklin says the fund invests at least 99.5% of assets in U.S. government securities, cash, and fully collateralized repurchase agreements. The fund listed $813.5 million in total net assets as of May 31, 2026.
WisdomTree is also testing fund liquidity in a new way. WisdomTree said SEC exemptive relief lets it support 24/7 trading and instant settlement for tokenized money market fund shares against USDC.
These are examples of a wider trend. Tokenization is finding scale in collateral and cash, where fund shares, money market products, and tokenized treasuries can support treasury management, collateral mobility, and settlement use cases rather than simply sit in a wallet.
Tokenized funds are no longer only about representing assets onchain. They are testing liquidity, settlement, collateral, treasury, and distribution models that conventional fund systems were not designed to support.
The LayerZero and Centrifuge report identifies stablecoin reserve strategies as one of the clearest use cases for tokenized funds.
Stablecoin issuers need reserve assets that are liquid, low risk, auditable, and productive enough to support yield strategies where permitted. Tokenized treasury and institutional credit funds can exist closer to the onchain systems where stablecoins already circulate.
While it doesn't mean every stablecoin reserve should become a DeFi strategy, it means tokenized funds are becoming more relevant where cash, collateral, settlement, and yield meet.
BlackRock’s stablecoin reserve push shows the same market pull from another direction. Institutional asset managers want tokenized cash products to serve digital dollar users who need regulated yield and liquidity rather than idle balances.
This is where fund composability becomes a business issue. A tokenized fund that can’t support reserve operations, collateral use, redemption timing, and compliance controls will struggle to serve the markets now asking for it.
Open DeFi composability clashes with regulated fund controls.
A fund cannot simply let any wallet hold, transfer, pledge, wrap, or trade its shares if those shares remain subject to securities rules, investor restrictions, transfer limits, or fund documents.
The report describes two ways to manage the tension.
The first is permissioned market structures. The fund share stays inside a controlled environment, while approved participants build lending, repo, collateral, or liquidity functions around it.
The second is deRWA style wrapping. A compliant fund share can sit inside a controlled wrapper, while another token gives DeFi users exposure to the economic position. That structure can separate compliant origination from wider DeFi distribution, but it also creates new questions about risk, transparency, liquidity, and investor understanding.
If wrappers make regulated fund exposure more usable, they may expand distribution. If wrappers hide too much complexity, they may create new conduct and disclosure problems. The market needs clarity on what investors hold, who controls redemption, how NAV is calculated, and what happens when liquidity disappears.
IOSCO’s 2025 tokenization report provides useful balance. It says tokenization may improve settlement, collateral mobility, transparency, and operational efficiency, but it also identifies risks tied to market integrity, investor protection, settlement assets, token representation, DLT dependency, and links with crypto markets.
Tokenized funds aren't automatically safer because they are onchain. They may reduce some frictions while introducing others. Smart contracts can improve automation, but fund administration still needs legal accuracy, investor records, custody, valuation controls, reporting, redemption rules, and oversight.
IOSCO also notes that adoption remains limited and that efficiency gains are uneven. That is a good reality check of the hype. Tokenized funds may be entering a more serious phase, but they still need credible settlement assets, interoperability, and operating controls before they can scale across mainstream capital markets.
The practical question for regulators is not whether tokenization is good or bad. The question is which parts of the fund process can become programmable without weakening investor protection or market integrity.
Canada’s tokenization discussion often starts with issuance, digital securities, and investor access.
But there's a deeper question for Canadian capital markets to answer. Can fund operations keep up?
That includes transfer agency, dealer controls, exempt market distribution, custody, compliance records, NAV operations, stablecoin settlement, investor reporting, tax records, and secondary liquidity. If those pieces remain fragmented, tokenized funds may exist onchain without becoming more useful to issuers or investors.
This also fits existing NCFA question work around tokenized RWAs and market infrastructure. The next advancement is whether regulated fund shares can become usable across venues while preserving the rules that make them credible.
It also fits NCFA’s Financial Innovation Map, including tokenized funds, transfer agents, compliant distribution, fund administration, tokenized collateral, stablecoin reserves, and capital markets technology.
The next phase of tokenized funds will be less glamorous than issuance.
It will involve NAV propagation, compliance messages, investor record synchronization, redemption queues, settlement timing, chain specific distribution, custody controls, and fund accounting.
That is where real opportunity is currently.
Tokenized funds will scale if the fund machinery underneath them can support pricing, settlement, compliance, and investor protection across the places where demand is forming.
If tokenized funds now need NAV, compliance, settlement, and investor records to work across chains, will the biggest opportunity belong to issuers or to the companies building the fund plumbing underneath them?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016