




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 2, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure

NCFA has published a comprehensive guide to stablecoin regulations in Canada. It brings together the Stablecoin Act, Bank of Canada supervision and the related requirements administered by FINTRAC, Canadian securities regulators, OSFI and FCAC.
The guide explains how Canada’s framework may affect stablecoin issuance, reserve management, redemption at par, governance, data security, trading platform access, payment activity, custody and consumer protection.
Canada has enacted the Stablecoin Act, but its substantive requirements are not yet in force. Supporting regulations, registration mechanics and Bank of Canada implementation materials remain under development.
The resource organizes Canada’s stablecoin requirements as a connected regulatory framework.
A single stablecoin business model may involve several legal and supervisory layers. Depending on its activities, a firm may need to assess issuer registration, money services business obligations, payment service provider requirements, securities rules, custody controls and prudential treatment.
The guide covers:
This resource is designed for stablecoin issuers, fintech founders, crypto platforms, custodians, payment companies, banks, compliance teams, investors, policymakers and market infrastructure providers.
It is particularly useful for teams assessing:
The guide’s principal strength is its integrated view of Canada’s regulatory structure. Readers can identify which authorities are involved, what Parliament has enacted and which implementation questions remain unresolved.
It also connects regulation with market development. Clear rules for reserves, redemption, custody and compliance could support tokenized financial infrastructure, stablecoin payments and institutional settlement services.
Firms can use the guide to begin preparing legal perimeter assessments, issuer control maps, reserve policies, governance models, data security plans, redemption procedures, AML files and Bank of Canada engagement materials.
Canada’s stablecoin regime is still under development. The guide provides regulatory intelligence and planning support, but it is not legal, financial, investment, compliance or professional advice. NCFA will update the Regulatory Intelligence page as regulations, supervisory materials and implementation dates are confirmed.
Stablecoin Regulations In Canada (primary NCFA Regulatory Intelligence guide)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Finance Canada Stablecoin Framework (primary government source)

The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking, funding opportunities and services to thousands of community members. NCFA works with industry, government, partners and affiliates to support a vibrant and innovative fintech and funding industry in Canada.
Decentralized and distributed, NCFA engages with global stakeholders and supports projects and investment across fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets, tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech.
Join Canada’s Fintech & Funding Community free, or become a contributing member to receive additional benefits. Visit NCFA Canada for more information.
 |  |  |
|---|---|---|
 |  |  |
Canada has now published proposed operating rules for its federal stablecoin regime. The Stablecoin Act received Royal Assent on March 26, 2026, but its substantive requirements are not yet in force. The proposed Stablecoin Regulations were published in Canada Gazette Part I on October 24, 2026 and remain under consultation.
This guide explains what is already established in legislation, what the proposed regulations would add, who may be covered and how the framework affects issuance, registration, reserves, redemption, custody, payments, trading and market access.
Coverage includes issuer scope, Bank of Canada registration, national security review, Canadian reserve custody, redemption at par, interest and rewards, governance, data security, FINTRAC obligations, RPAA payment activity, CSA value referenced crypto asset treatment, OSFI prudential rules and consumer protection.
Finance Canada has published the proposed Stablecoin Regulations and related RPAA amendments. The package now specifies issuer registration information, national security review periods, reserve assets and Canadian custody, redemption timing and fees, transaction rewards, policy requirements, reporting, cost recovery and the treatment of stablecoin payment functions.
Consultation closes December 23, 2026 at 11:59 p.m. Eastern
The proposal is not final and the regime is not yet operational. The government intends the regulations and Stablecoin Act to come into force in fall 2027 on a date or dates fixed by the Governor in Council.
Yes. Existing payments, AML, securities, prudential and consumer protection requirements can apply. The Stablecoin Act is enacted, and detailed federal regulations are now proposed, but the new issuer regime is not yet in force.
The Bank of Canada will register and supervise covered issuers under the federal framework.
The proposed regime covers registration, reserves, Canadian custody, redemption at par, governance, risk management, data security, reporting, recovery planning and restrictions on interest or yield.
Yes. Domestic and foreign non-financial institution issuers may be covered when they make fiat-backed stablecoins available to Canadians, subject to the Act, proposed regulations and any exemption based on substantially similar regulation.
No. Treatment depends on the stablecoin, issuer, activity and distribution model, including whether securities, derivatives, payments, AML or prudential rules apply.
Canada has progressed from interim securities treatment to an enacted Stablecoin Act and a detailed Canada Gazette proposal. The current phase is consultation. Final regulations, Bank of Canada guidance and legal commencement remain ahead.
Navigate the main authorities, obligations and implementation layers that make up Canada’s stablecoin framework. This reference supports the regulation-to-market pathway below by giving readers a deeper view of each regulatory component.
Canada’s federal framework now consists of an enacted Stablecoin Act and proposed Stablecoin Regulations. The new issuer regime is not yet in force. Existing securities, AML, prudential and payment rules continue to apply where relevant.
Firms should map the activity first. Issuing a stablecoin, operating a wallet, processing a stablecoin payment, trading a value referenced crypto asset and safeguarding reserve assets can trigger different regulatory layers.
The October 24 proposal makes Canada’s market entry model much more concrete. The key commercial distinction is now between becoming an issuer with reserve, custody and redemption obligations, and participating through payment, wallet, custody or compliance infrastructure.
The Stablecoin Act was enacted through Bill C-15 and received Royal Assent on March 26, 2026. Its substantive requirements are not yet in force. Once commenced, the Act would regulate domestic and foreign non-financial institution issuers that create a fiat-backed stablecoin and make it available for purchase, directly or indirectly, by persons in Canada.
The October 24 proposal supplies much of the operating detail the Act delegates to regulation, including definitions of creation and distribution control, outstanding stablecoins, closed-loop arrangements, registration information, reserve assets, custody, redemption timing and fees, policy content, significant change notices and supervisory assessment fees.
The proposal defines “create” as control over the stablecoin’s properties, including design and generation, and “make available” as control over distribution. For the definition of an outstanding stablecoin, “purchased” would mean purchased by a person whose usual residence, head office or principal place of business is in Canada.
A closed-loop stablecoin would fall outside the SCA where it can only be used within a specified merchant or merchant-group network, including transfers for use in that network, and can be redeemed in fiat only from that merchant, a member of the merchant group or a person affiliated with the issuer.
Issuer policies would need to cover governance, risk management, data security and recovery and resolution. The governance policy would also need a complaint process with a web complaint form, acknowledgment within seven days and resolution within 30 days. Risk management and data security policies would require independent review at least every three years, and all required policies must be supported by adequate human and financial resources.
Publication in Canada Gazette Part I starts consultation. It does not make the proposed regulations final or bring the Stablecoin Act into force. Final regulations would need to be published and commencement would occur on a day or days fixed by the Governor in Council.
The legal anchor was established in March. The October proposal now gives firms enough detail to begin serious entry modelling, but not enough certainty to treat fall 2027 as a fixed legal commencement date.
Applicants would use a Bank of Canada electronic system and provide detailed information about ownership, structure, stablecoin design, reserve assets, qualified custodians, third parties and technology locations. Foreign applicants without a Canadian place of business would need a person in Canada authorized to accept service.
The Minister of Finance would have 60 days to decide whether to conduct a national security review, with possible additional 60-day extensions. A review, once launched, would have a 180-day period that can also be extended in additional 180-day periods. This is separate from the Bank of Canada’s ordinary registration process.
The proposal would allow an issuer already operating immediately before commencement to continue temporarily if it applies within 30 days after the Stablecoin Act comes into force. New entrants would generally need registration before issuing.
Registration is now a market access process, not only a disclosure exercise. Ownership, reserve design, outsourcing, data location and national security review can all affect timing and entry planning.
The Bank of Canada would register and supervise covered issuers, maintain the issuer registry, monitor compliance, request information and use enforcement powers where obligations are not met. The Bank says its supervision will focus on full backing, par redemption and safe, reliable issuance.
The Stablecoin Act requires the Bank to recover its stablecoin supervision costs from registered issuers. The Gazette estimates those costs at about C$2.5 million annually. The proposed base assessment uses an issuer’s average monthly value of outstanding stablecoins: C$750,000 for C$1 billion or more, C$350,000 for C$500 million to under C$1 billion, and C$25,000 below C$500 million, subject to CPI adjustment. Tier 1 and Tier 2 issuers would also share 75% and 25%, respectively, of remaining recoverable costs; Tier 3 has no variable amount.
The Regulatory Impact Analysis estimates annualized incremental costs of the proposed Stablecoin Regulations at C$88,521 across affected issuers, or C$17,704 per regulated issuer on average under its assumptions. That estimate is distinct from Bank supervision assessments and from the broader operating cost of reserves, custody, governance and technology. Proposed administrative monetary penalties range from C$1 to C$1 million for serious violations and C$1 to C$10 million for very serious violations, subject to the detailed provisions and penalty criteria.
For smaller issuers, the important cost question is not the Gazette’s narrow incremental compliance estimate by itself. It is the combined cost of supervision, reserve operations, Canadian custody, governance, reporting and technology controls.
At the end of each day, reserve assets would need a market value equal to or greater than the par value of outstanding stablecoins and would need to be denominated in the reference currency.
Reserve assets would have to be held with a qualified custodian incorporated or formed under federal or provincial Canadian law. This would exclude financial institutions that are not incorporated in Canada from acting as the qualified custodian for these reserve assets.
The Act requires segregated, bankruptcy remote reserve assets that are protected from claims by the issuer’s or custodian’s other creditors except for claims of stablecoin holders. Issuers could withdraw reserve returns only while the reserve remains fully backed.
Canadian custody is one of the proposal’s clearest infrastructure choices. It could create domestic demand for custody, reserve banking, reconciliation and attestation services while adding an operating requirement for foreign issuers serving Canadians.
Issuers would have to redeem stablecoins one to one in the reference fiat currency and publish a clear redemption policy in both official languages.
The proposed rules also prohibit representations that a stablecoin is legal tender, a deposit or proof of deposit, publicly insured or government guaranteed. Stablecoin redemption should not be described as equivalent to deposit insurance.
Redemption is now measurable. Timing, fee ceilings, payment methods and liquidity exceptions give users and firms a much clearer standard for comparing issuer models.
The Stablecoin Act prohibits issuers from paying interest or yield tied to holding a stablecoin. The proposed regulations clarify that issuers also could not use indirect arrangements that fund payments designed to encourage holders to maintain larger balances or hold for longer periods.
Rewards programs will need to be designed around actual transaction use rather than time or balance held. Firms should assess the economic substance of arrangements rather than relying on the label attached to a reward.
The proposal draws a deliberate boundary between payment incentives and deposit-like returns. The broader international debate over stablecoin rewards and banking competition belongs in separate strategic analysis rather than being collapsed into this rule guide.
FINTRAC has stated that stablecoin issuers will be required to register as money services businesses dealing in virtual currency once the relevant changes come into force. AML obligations therefore sit alongside Bank of Canada issuer supervision rather than replacing it.
Issuers and platforms should connect issuance, reserve and redemption controls to customer due diligence, wallet monitoring, sanctions screening, transaction reporting and escalation processes.
Stablecoin use can operate at payment speed, so the compliance layer needs to be equally operational. That remains a material opportunity for Canadian regtech and blockchain analytics providers.
The October 24 package proposes amendments to the Retail Payment Activities Regulations so PSPs that perform payment functions using prescribed stablecoins can fall within the RPAA. This is separate from regulation of the issuer under the Stablecoin Act.
The proposed RPAR definition excludes closed-loop stablecoins. It would cover stablecoins issued by entities on the Bank of Canada’s stablecoin issuer list and stablecoins issued by financial institutions subject to federal, provincial or foreign requirements that are substantially similar to specified Stablecoin Act protections.
Where a PSP holds stablecoins on behalf of an end user, the proposal adds a safeguarding option using a separate entity whose sole purpose is holding end-user funds. The entity would be the registered holder on the distributed ledger, and the stablecoins and associated rights must not form part of the PSP’s estate. Safeguarding frameworks would also need procedures to give end users access to funds without delay if the stablecoin issuer becomes insolvent, including procedures for redemption into the reference fiat currency.
Covered PSPs would be subject to applicable Bank of Canada registration, operational risk management, incident response, safeguarding, reporting and national security requirements. Safeguarding frameworks are independently reviewed every three years under the RPAR. The RPAA also contains exemption mechanisms intended to reduce overlap with substantially similar regimes and securities transactions.
This creates a clearer service layer around stablecoins. A wallet, processor or infrastructure company can participate in stablecoin payments without necessarily taking on the reserve and redemption obligations of becoming the issuer.
The CSA’s interim approach applies to value-referenced crypto assets, commonly called stablecoins, on crypto asset trading platforms. The CSA has permitted certain fiat-backed crypto assets to continue trading where platforms and issuers meet terms and conditions.
Platforms should maintain VRCA due diligence files, issuer undertaking records, reserve disclosure links, risk disclosures, product monitoring, halt and suspension playbooks and client-facing stablecoin risk language.
The securities layer won’t disappear just because Canada now has a federal stablecoin framework. Trading, distribution and platform access will remain important parts of the Canadian stablecoin operating model.
OSFI’s cryptoasset exposure guideline sets regulatory capital and liquidity treatment for banks, federal credit unions, bank holding companies, federally regulated trust companies and federally regulated loan companies. Separate insurance guidance applies to insurers. The banking guideline took effect on January 1, 2026.
Banks and regulated financial institutions should assess direct and indirect stablecoin exposures, custody arrangements, issuer relationships, tokenized asset products, capital treatment, liquidity implications and OSFI notification triggers.
OSFI’s layer matters because stablecoin infrastructure may rely on banks for custody, settlement, treasury and institutional distribution. Prudential treatment can affect how quickly incumbents participate.
FCAC research shows stablecoin awareness and understanding are still policy issues. It also noted that stablecoins and cryptoassets were not covered by federal or provincial deposit insurance at the time of the research. Consumer understanding matters because stablecoins may sound safer than they are.
Issuers and platforms should test consumer disclosures, avoid deposit-like language unless legally accurate, explain insolvency and redemption risk, and make sure users understand who is responsible for each part of the product.
Consumer trust can’t be built on the word stable. It has to be earned through reserve transparency, redemption rights, clear platform roles and language people can understand.
The October 24 package is a proposal. Comments are open for 60 days. The Gazette states that representations, including attachments, will be published on the Canada Gazette website subject to its terms of use. The most decision-useful issues are those delegated to regulation rather than requirements fixed directly in the Stablecoin Act.
Registration information, transitional treatment, supervisory assessments and how requirements scale for smaller issuers.
Canadian custodian eligibility, reserve flexibility, redemption timing, liquidity exceptions and the 1% fee ceiling.
RPAA scope, foreign issuer recognition, transaction rewards, regulatory overlap and international interoperability.
Deadline: December 23, 2026 at 11:59 p.m. Eastern. Use the official Canada Gazette consultation. Changes to the Stablecoin Act itself would require legislative amendment rather than this regulatory consultation.
Canada’s framework is easier to understand beside other mature stablecoin regimes. Select a jurisdiction to compare implementation status, primary authority, regulatory model and strategic relevance for Canada.
Canada now has a detailed proposed operating model for fiat-backed stablecoin issuance by non-financial institutions. The proposal adds registration information, Canadian reserve custody, redemption timing and fees, policy requirements, reporting, cost recovery and RPAA treatment for prescribed stablecoin payment functions.
The regime is still not operational. Consultation closes December 23, 2026 and final regulations and Bank guidance remain ahead.
Stablecoin Act issuer framework with Bank of Canada supervision, Finance Canada policy direction and parallel FINTRAC, CSA, RPAA and OSFI requirements.
Canada’s key market design question is now whether the combined issuer, custody, supervision and payment requirements provide enough certainty for new entry without concentrating activity in the largest firms.
The UK has final FCA rules for non-systemic qualifying stablecoins covering issuance, backing assets, redemption, safeguarding and disclosures. Systemic payment stablecoins sit in the Bank of England perimeter.
This gives Canada a useful comparison for issuer design, backing assets, custody, redemption and how to separate retail-market and systemic payment oversight.
FCA stablecoin issuance rules inside the wider UK cryptoasset regime, with separate treatment where payment stablecoins become systemic.
The UK separates stablecoin issuance from broader cryptoasset activity while tying stablecoins to custody, disclosure and conduct rules.
MiCA creates a harmonized EU regime for cryptoassets, including asset-referenced tokens and e-money tokens. The stablecoin elements were among the earliest parts of MiCA to apply.
For Canada, the EU is the strongest example of a large market using a passportable stablecoin and cryptoasset framework across multiple member states.
Single-market cryptoasset regulation with specific stablecoin categories for ARTs and EMTs.
MiCA gives Europe an integrated market structure advantage. Canada does not have equivalent passporting, so interoperability and provincial coordination matter more.
The U.S. framework now has a final OCC rule covering payment stablecoin issuer activities, reserves, redemption, risk management, custody, applications, supervision and foreign issuers under OCC jurisdiction.
For Canada, the comparison is increasingly practical rather than theoretical because the U.S. regime is scheduled to take effect months before Canada’s intended fall 2027 implementation.
Federal payment stablecoin legislation with permitted issuer categories, federal and state supervision and separate treatment for foreign issuers.
Canadian interoperability will depend on whether the Bank of Canada eventually recognizes substantially similar foreign regimes and which Canadian obligations continue to apply after recognition.
Singapore’s framework focuses on single-currency stablecoins pegged to the Singapore dollar or G10 currencies and issued in Singapore, with strong emphasis on reserve backing, redemption and disclosure.
It is useful for Canada because it shows how a smaller financial centre can set a high-trust stablecoin regime without trying to cover every possible cryptoasset activity at once.
MAS single-currency stablecoin framework connected to Payment Services Act amendments and digital payment token oversight.
Singapore’s approach is narrow and trust-centred. Canada can use a similar discipline while accounting for securities and federal-provincial overlays.
Hong Kong has an active licensing regime for fiat-referenced stablecoin issuers, with HKMA supervision and a policy objective tied to virtual asset market development and financial stability.
For Canada, Hong Kong is a useful comparison because it connects stablecoin licensing with a broader digital asset market strategy and clear issuer licensing.
Dedicated stablecoin issuer licensing under the Stablecoins Ordinance.
Hong Kong is treating stablecoins as part of financial centre strategy. Canada’s framework will need a clearer market-development lane if it wants domestic issuance, not only control of foreign tokens.
Japan permits stablecoin issuance through regulated channels such as banks, trust companies and fund transfer service providers, with stablecoins treated through payment services and electronic payment instrument rules.
The Japanese model anchors stablecoin issuance in regulated financial institutions and payment functions rather than a broad open issuer perimeter.
Payment Services Act and related rules for electronic payment instruments, with issuance through regulated financial channels.
Japan offers a more institution-led comparison. Canada’s non-financial issuer mandate is broader, so its controls need to be clear enough for market trust.
The FSB’s global stablecoin recommendations seek consistent regulation, supervision and oversight of global stablecoin arrangements while allowing jurisdictions to implement domestic approaches.
This is important for Canada because cross-border stablecoin use depends on compatible standards for governance, risk management, redemption, reserve assets, data sharing and regulatory cooperation.
High-level recommendations rather than domestic law. They set a baseline for authorities designing local frameworks.
Canada’s framework should be easy for other authorities to recognize. That matters for cross-border use and domestic credibility.
The main difference between leading jurisdictions is not whether stablecoins, payments, AML, digital assets and consumer protection are regulated. Most serious markets are building rules across those areas. The practical difference is how clearly those rules connect. Jurisdictions with coordinated rulebooks, visible implementation timelines and clear supervisory entry points give firms a better path from compliance planning to market launch.
Market structureStablecoin regulation is converging around reserve quality, redemption rights, issuer governance and disclosure. The strategic difference is market design. The EU offers passporting, Hong Kong and Singapore connect licensing to financial-centre strategy, Japan limits issuance to regulated financial channels, and the U.S. focuses on dollar stablecoin scale.
Canada’s coordination challengeCanada’s October 24 proposal now specifies many of the operating requirements firms were waiting for. The remaining coordination challenge is how Bank of Canada issuer supervision, RPAA payment oversight, FINTRAC registration, CSA cryptoasset treatment and OSFI prudential rules work together in practice.
Cross-border useCanadian users and platforms will likely interact with USD stablecoins regardless of domestic issuance. The framework therefore needs rules for foreign stablecoins made available in Canada, not only rules for Canadian issuers.
Market opportunityThe opportunity is compliant settlement infrastructure. If Canada can make reserves, redemption, custody and AML controls clear, stablecoins can support programmable payments, tokenized settlement and cross-border transaction flows without relying entirely on foreign operating models.
Major jurisdictions are converging around high-quality reserves, redemption rights, issuer governance, disclosures and AML controls. They continue to diverge on market access, supervisory structure, passporting, foreign issuer treatment and how directly stablecoin policy connects to national competitiveness.
Canada’s challenge is now implementation quality. Final rules, Bank guidance, recognition decisions and practical coordination across the federal, securities, payments, AML and prudential layers will determine how easy it is for firms to launch or participate.
NCFA’s regulation-to-market pathway shows how Canada’s stablecoin framework can move from policy and supervision into market capabilities and innovation opportunities. The visual is not a legal hierarchy. It is a market-development map showing how regulatory functions connect to the operating capabilities firms need to build trusted digital money infrastructure.
These opportunity areas align with the capabilities in the pathway above. Only the published NCFA Opportunity Brief receives a primary call to action; the other nodes show where future research or Innovation Map coverage can expand.
Use these links to go deeper into the adjacent regulations, market evidence and infrastructure themes connected to Canada’s stablecoin framework.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Crypto, Wealthtech, Capital Markets And Funding, Fintech And Innovation

On June 30, 2026, Webull Canada Crypto announced it will begin offering cryptocurrency trading after receiving approval from the Canadian Investment Regulatory Organization.
The approval gives Webull another asset class inside its Canadian investing platform, which already supports U.S. and Canadian stocks, ETFs, options, margin accounts, cash accounts, TFSAs, and RRSPs through Webull Securities Canada.
Beta access for selected clients is expected to start soon, with a wider rollout planned in the coming weeks. Webull says the crypto experience will include 24/7 trading for assets such as Bitcoin, Ethereum, Solana, XRP, Cardano, and Litecoin.
This is another regulated online brokerage aligning digital assets among the same customer experience as traditional investing.
Webull Canada Crypto Limited is regulated by CIRO. Webull Securities Canada Limited is also regulated by CIRO and is a member of CIPF.
That structure is important because crypto trading and traditional securities accounts don't carry the same investor protections. Webull's disclosure says crypto assets are not protected by CIPF, although CIPF protection may be available for eligible cash held in a crypto trading account, subject to applicable limits and policy terms.
The approval arrives after Canadian regulators spent several years moving crypto platforms toward dealer registration and CIRO membership, custody expectations, risk disclosure, and stronger client asset controls.
Regulated access is becoming the path for retail crypto distribution in Canada.
When Webull expanded brokerage services to Canada in early 2024, the initial story was low cost access to Canadian and U.S. listed equities.
The platform has since expanded around commission free trading, advanced charting, market data, options access, registered accounts, and now crypto.
Webull is building toward a multi asset retail investing platform where users can fund accounts, monitor portfolios, review reporting, and trade across asset classes without leaving the ecosystem.
Crypto increasingly looks less like a standalone destination and more like another investing capability inside regulated financial apps.
Canadian online brokers used to compete heavily on commissions, execution, research tools, and account access. In 2026, competition is about platform depth as investors want fewer disconnected accounts. Platforms want more customer activity, better retention, more data, and a wider share of the investor relationship, and eventually more personalized portfolio features.
Webull is entering a market where Wealthsimple already combines investing, crypto, cash, tax, and other financial services. KOHO adding regulated crypto trading inside its money app flashing the same pattern from a consumer finance angle.
The Canadian crypto market has gone through enforcement, registration pressure, custody scrutiny, stablecoin restrictions, and platform exits. Yet regulated distribution keeps expanding.
Canada hasn't treated retail crypto as an unregulated free for all. It also hasn't eliminated retail access. Oversight of the market is evolving toward regulated firms, clearer disclosures, tighter custody controls, and platforms that can operate within securities rules.
Webull's entry adds another regulated access point for Canadian investors and increases pressure on every platform that wants to be a primary investing destination.
The approval gives Webull permission to compete, but it doesn't guarantee adoption.
Crypto also brings higher volatility, suitability questions, security expectations, and investor education demands. A smooth user experience can't hide the risk profile of the asset class.
The advantage for Webull is that crypto can now be offered alongside the rest of its investing platform. The challenge is that investors will compare the experience not only with crypto exchanges, but with every brokerage and fintech app trying to become the main place Canadians manage investments.
Crypto trading platforms moving toward CIRO oversight shows how Canadian regulation is reshaping digital asset distribution.
Crypto custody rules are becoming a core operating issue for dealer members and digital asset platforms.
KOHO's regulated crypto rollout shows digital assets moving into broader consumer finance platforms.
Tokenization becoming a measurable business shows how digital assets are moving deeper into regulated capital markets infrastructure.
NCFA's Financial Innovation Map tracks digital assets, wealthtech, brokerage competition, capital markets infrastructure, custody, and investor access opportunities.
If every major investing platform eventually offers stocks, ETFs, options, registered accounts, and crypto, what becomes the next competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 29, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy

NCFA has published a practical guide to the UK cryptoasset regulations and FCA final rules. It helps firms, platforms, issuers, custodians, compliance teams, investors and policymakers understand how the UK framework applies across regulated digital asset activities.
The primary Regulatory Intelligence guide organizes the rule package by authorisation, scope, stablecoin issuance, custody, trading platforms, disclosures, market abuse, prudential requirements, Consumer Duty, governance, operational resilience, financial crime, reporting and implementation readiness.
The resource gives readers a structured entry point into the UK cryptoasset regime without treating the rulebook as one long regulatory document. It directs readers to the detailed Regulatory Intelligence explorer, where each rule area separates requirements, implementation work, consultation outcomes and NCFA analysis.
That distinction is important because firms need to prepare for more than registration. They may need to assess permissions, governance, safeguarding, disclosures, capital, operational controls, market integrity, customer communications, reporting and senior management accountability.
The framework also gives Canadian and global readers a useful comparison point as tokenized financial infrastructure, stablecoins and regulated digital asset markets develop. The central question is which firms can meet regulated market standards while continuing to build useful products and services.
This resource is designed for crypto trading platforms, custodians, stablecoin issuers, digital asset infrastructure firms, fintech founders, compliance teams, securities lawyers, investors, policymakers and market participants comparing global crypto regulatory models.
It is especially relevant for organizations assessing FCA authorisation, custody controls, stablecoin infrastructure, consumer disclosures, market abuse controls, governance, prudential requirements and operational readiness.
The strength of the resource is its practical structure. It turns a large regulatory package into a clear intelligence layer that readers can use to identify obligations, implementation dependencies and areas requiring specialist legal, compliance, technology or operational work.
It also supports jurisdictional comparison. Canadian and global market participants can use the UK rules to compare approaches to crypto authorisation, custody, stablecoins, disclosures, platform conduct, market integrity and consumer protection.
The guide is not a substitute for legal advice. Regulatory treatment depends on the facts, firm structure, permissions, product design and activities performed in or into the UK. Readers should use it for ecosystem intelligence and planning, then review the FCA primary materials and consult qualified advisers.
UK Cryptoasset Regulations And FCA Final Rules
Primary NCFA Regulatory Intelligence guide with the full rule explorer, implementation analysis, timeline and source links.
Tokenization Starts Looking Like Financial Infrastructure
Market infrastructure context for tokenized cash, custody, settlement and regulated digital asset rails.
Deloitte And Stablecorp Bring QCAD To Banks
Canadian stablecoin infrastructure context for banks and regulated financial institutions.
FCA Final Crypto Rules Announcement
Official FCA source announcing the final UK cryptoasset rule package.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure
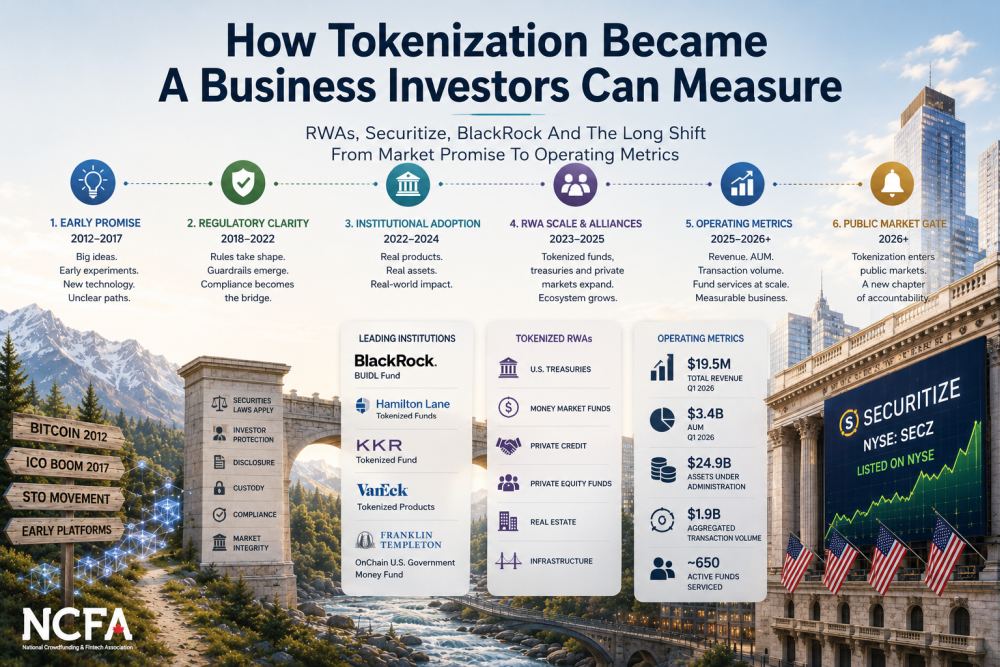
Tokenization promised to change capital markets for more than a decade.
The promise is still attractive. Put ownership on chain. Reduce paperwork. Automate compliance. Improve access. Speed up settlement. Make private assets easier to distribute, manage, and transfer.
But markets don’t run on promises. They run on operating models, regulation, distribution, controls, liquidity, and trust.
That’s why Securitize’s expected NYSE listing is the trigger. The listing isn’t the whole story. It’s the latest chapter in a longer path from tokenization as a market idea to tokenization as a business investors can measure.
The first wave sold a powerful idea. Security tokens, STOs, fractional assets, real estate tokens, private shares, and blockchain based markets promised to bring traditional securities into programmable digital form. The early security token field was framed as a more regulated answer to the ICO boom.
The market didn’t overhaul itself. Early security token projects ran into the same walls: unclear regulation, thin liquidity, limited distribution, custody questions, fragmented platforms, investor eligibility rules, and the simple reality that a tokenized security still has to behave like a security.
The hard work was never only technical. A tokenized fund still needs investor onboarding, KYC, AML, transfer rules, custody, servicing, reporting, distributions, tax records, corporate actions, and permissioned secondary transfers. Those aren’t marketing features. They’re the boring parts that make markets work.
Regulators kept reminding the market that labels don’t change obligations. Hester Peirce’s point that tokenized securities still have to follow securities laws captured the practical boundary. Faster settlement and automation don’t remove investor protection, disclosure, and market integrity requirements.
Real world assets changed the packaging. The market stopped asking whether everything should become tokenized and started asking which assets actually benefit. Treasuries, money market funds, private credit, private equity funds, and alternative assets became more practical test cases than vague claims about digitizing every market.
Private markets gave tokenization a clearer job. Citi, Wellington Management, and WisdomTree tested private market tokenization in 2024, showing how smart contracts could support operating efficiency in traditionally manual private market processes.
Hamilton Lane used tokenization to lower access friction. In 2022, Hamilton Lane and Securitize said qualified US investors would gain access to tokenized feeder funds tied to direct equity, private credit, and secondary transaction strategies.1 Securitize later said one Hamilton Lane fund reduced the minimum investment from about $5 million to $20,000.2
KKR showed that major alternatives managers would test the model. Securitize launched a tokenized fund offering exposure to KKR’s Health Care Strategic Growth Fund II in 2022, framing the product around broader access to alternative investments through digital ownership.3
BlackRock changed the market’s confidence level. BlackRock launched BUIDL, its first tokenized fund, on Ethereum in March 2024. The fund was backed by cash, US Treasury bills, and repurchase agreements, with BNY Mellon enabling interoperability between digital and traditional markets.4
BUIDL became a measurable adoption signal. In March 2025, Securitize said BUIDL surpassed $1 billion in AUM and identified itself as the tokenization provider for the fund.5 BlackRock’s BUIDL launch became one of the clearest institutional signals that tokenization was entering regulated asset management.
Securitize turned the thesis into operating data. In Q1 2026, Securitize reported $19.5 million in total revenue, up 39% year over year, $3.4 billion in AUM at quarter end, $24.9 billion in assets under administration, $1.9 billion in aggregated transaction volume, and roughly 650 active funds serviced through Securitize Fund Services.6
Those numbers change the conversation. Investors can ask normal operating questions: revenue mix, servicing fees, client concentration, transaction volume, fund growth, margins, profitability, operating leverage, customer retention, regulatory execution, and how much tokenization demand converts into durable revenue.
The listing is the trigger. Securitize and Cantor Equity Partners II said the business combination was expected to raise approximately $400 million in gross proceeds, close after shareholder approval and customary conditions, and list on the NYSE under ticker SECZ.7
The listing doesn’t settle the thesis. It exposes the thesis to market discipline. A listed tokenization company has to explain growth, losses, expenses, institutional demand, regulatory risk, competitive pressure, and whether tokenized fund adoption can become a durable public company business.
Canada has a practical watchlist. The opportunity isn’t to copy a US listing. Canadian firms can look across the tokenization value chain: custody, transfer services, fund administration, compliance, exempt market distribution, private market platforms, digital identity, investor onboarding, reporting, and secondary trading.
Regulated product design may decide the next chapter. The OSC’s long term asset fund project pointed to possible retail exposure to traditionally inaccessible assets and raised the opportunity for tokenized long term funds with embedded compliance, transparent records, fractional access, and guardrails.
Tokenization didn’t become measurable overnight. It moved through years of big claims, stalled experiments, regulatory pushback, operating layer buildout, institutional product design, and real world asset packaging before public markets had a company they could evaluate with ordinary business questions.
That may be the clearest test. The first tokenization wave asked investors to believe in a technology. The next wave will ask investors to evaluate execution. Revenue. Margins. Assets. Transactions. Clients. Losses. Retention. Market share. Operating leverage. That is a much harder test, and a much more useful one.
For Canada, the lesson is practical. The next winners may not be the firms issuing the tokens. They may be the firms solving everything around them: custody, compliance, investor onboarding, fund administration, reporting, liquidity, and regulated distribution. That’s where durable businesses are often built, and where Canada’s capital markets innovation map can help identify opportunities that are still taking shape.
What operating metric would convince you that tokenized markets have moved beyond promise?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 26, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Risk Compliance And Regtech, Payments And Market Infrastructure, Regulation And Policy, Treasury Liquidity And Cash Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026, Jun 13-19, 2026).
Credit unions now have a clearer way to test stablecoins, tokenized deposits and digital asset accounts inside member owned financial institutions. Banks, core providers, payments firms, fintechs and regulators should watch whether these early programmes become production deployments for real time settlement, deposit tokens and broader member access to digital assets.
Stablecoin issuer regulation is becoming an AML and identity control issue, not only a reserve or redemption issue. Issuers, banks, custodians, wallets, exchanges and compliance teams should prepare for customer identification, verification, recordkeeping and risk controls as payment stablecoin frameworks mature.
Stablecoin regulation is moving from policy design into operating rules for payment infrastructure. Issuers, banks, custodians, payment firms, exchanges, and fintechs should watch how reserve design, redemption rights, safeguarding, and systemic supervision shape market access for regulated digital money.
Tokenization platforms are entering public capital markets. Asset managers, broker dealers, transfer agents, custodians, exchanges and investors should watch how public company access, regulated ATS infrastructure and cross border digital securities permissions shape the next phase of tokenized fund and real world asset distribution.
Event contract markets are facing a sharper boundary test. Exchanges, brokers, prediction market platforms, sports leagues, tribal gaming authorities and regulators should watch whether Congress narrows the line between federally regulated event contracts and state regulated gambling.
Private market trading infrastructure needs audit rules that firms can apply before transactions scale. Companies, auditors, advisers, venues and investors should watch how PISCES treatment affects independence checks, audit committee planning, transaction readiness and the operating model for periodic private share trading.
Canadian issuer disclosure is becoming more digital by default. Public companies, transfer agents, investor relations teams, legal advisers and compliance staff need to adjust delivery controls, SEDAR+ workflows, investor notices and request handling before the new access model takes effect.
Canadian equity market structure remains tied to US implementation timelines. Trading venues, brokers, market makers, and technology teams need more time to adjust routing logic, fee models, tick increments, compliance controls, and systems that support trading in interlisted securities.
Tokenization is moving closer to regulated market infrastructure. Exchanges, brokers, clearing firms, custodians, digital asset platforms, and regulators should watch how traditional market operators and crypto venues build permissioned pathways for tokenized securities, futures access, custody, execution, and compliance. Similar infrastructure questions are also emerging in event contract markets as new regulated venues, distribution channels, and contract frameworks develop.
Bank AI adoption is moving from pilots to operating metrics. Financial institutions, fintech vendors, compliance teams, investors, and regulators should watch how large banks measure AI value, scale employee access, govern automation agents, and connect AI deployment to fraud control, onboarding, productivity, risk operations, and compute infrastructure markets.
Cross border payments are becoming a regulated corridor strategy. Exporters, payment firms, banks, compliance teams and fintechs should watch how RPAA registration, money services business obligations, local payout capability and bank account connectivity affect competition in Canada India payment flows.
Digital euro policy is becoming payment infrastructure design. The next test is how offline use, privacy controls, holding limits, fees, PSP distribution, and cash protection fit into a system that has to work across public money, private payment providers, and existing rails.
Mortgage distribution is becoming a stronger fraud, licensing, and consumer protection issue. Brokers, lenders, fintech mortgage platforms, compliance teams, and investors should watch how higher penalties, clearer licensing rules, and stronger supervision reshape risk controls in mortgage services.
Financial crime detection no longer depends only on what individual institutions can see. Banks, credit unions, payment service providers, securities dealers, fintechs and other reporting entities can now strengthen risk detection by sharing designated information, creating new opportunities for collaborative fraud controls, network analysis and anti money laundering investigations.
Regulatory enforcement is becoming more incentive driven. Banks, insurers, investment firms, credit unions and compliance teams should review how early investigation strategy, breach assessment, remediation evidence and senior accountability affect enforcement outcomes.
Audit reporting is becoming more focused on useful disclosure, controls evidence and investor readability. Companies, audit committees, auditors, governance advisers and compliance teams should prepare for updated report content, Provision 29 controls statements and revised audit workflows before the December effective date.
Firms need to know where encryption is used, which vendors are exposed, which systems protect high value data, and how long migration will take. Crypto inventory, procurement language, vendor assurance, and roadmap planning should start before compliance dates become delivery pressure.
A regulated operating company is using a tokenized money market fund for its own liquidity rather than presenting it as a future client product. That moves tokenization into daily treasury operations, where continuous access, settlement speed, custody controls and balance-sheet utility can be tested against conventional cash-management infrastructure.
Approval processes are becoming more transparent and predictable for eligible applicants entering or expanding within Canada's federally regulated financial sector. Banks, fintechs, federal credit union applicants and regulated financial institutions should watch how the framework affects application timelines, market entry, organizational changes and future supervisory expectations. For background, see NCFA's earlier coverage of the Streamlined Approvals Framework proposal.
Manitoba has put AI governance and cybersecurity inside the same statutory control structure for the public sector. The next test is implementation. Regulations will determine how far the province goes on human oversight, technical standards, incident reporting and vendor procurement, and whether those requirements become a practical benchmark for other Canadian governments.
Every week brings hundreds of announcements. Only a small number signal meaningful change. This week's developments point to new opportunities across payments, digital assets, AI, capital markets and regulation that could influence where innovation accelerates, investment flows and new business models emerge next.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 20, 2026 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data

On June 18, 2026, IOSCO published a Supervisory Tech (SupTech) report called 'Mapping the Use of Technology in Financial Supervision', a global survey of 49 authorities on how regulators are using technology to improve financial supervision. The report maps where SupTech is already being used, what is driving adoption, and which barriers are slowing progress.
SupTech is becoming part of regular ongoing supervision, and is no longer an experiment. Regulators are using technology to improve efficiency, receive and analyze information faster, and strengthen oversight across investor protection, market conduct, capital markets, and emerging areas such as digital assets.
The report gives regulators, fintech firms, and regtech providers a global benchmark for how supervisory technology is being adopted. It covers strategy, budgets, leadership, data, cloud infrastructure, AI, cybersecurity, digital assets, cooperation, and workforce planning.
IOSCO found that efficiency is the main driver of SupTech adoption, followed by faster access to information and stronger supervisory capabilities. AI applications, improved data access, and cloud infrastructure are the leading technology enablers.
Consumer and investor protection and capital markets supervision are the most developed use cases. Digital assets are less mature today, but interest is rising. That gap matters because market activity is moving faster than many supervisory tools.
The report also shows why implementation is hard. Cyber risk, third party dependencies, operational risk, funding gaps, and skills shortages remain major constraints. Many authorities have strategies under way, but full implementation is still uneven.
This resource is useful for securities regulators, policy teams, regtech firms, fintech compliance teams, financial institutions, digital asset platforms, market surveillance teams, and researchers tracking regulatory modernization.
It is especially useful for organizations building or assessing tools for market monitoring, fraud detection, complaints analysis, digital asset oversight, supervisory analytics, data collection, and AI enabled supervision.
The strength of this resource is its global scope. The survey covers authorities across all IOSCO regions and gives readers a baseline for comparing SupTech maturity, priorities, and constraints.
It is also useful because it avoids hype. The report shows that many regulators are still using mid level technologies and practical tools. Advanced analytics and machine learning are important ambitions, but funding and implementation capacity remain real limits.
The limit is that it's survey based, not a product guide. It doesn't rank vendors, provide implementation playbooks, or prove which tools produce the best supervisory outcomes. Its value is in the benchmark, the use cases, and the policy signals.
IOSCO SupTech Report (primary report)
IOSCO SupTech Media Release (announcement summary)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
MIT AI Risk Repository For Fintech Governance (AI risk taxonomy resource)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016