





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 5, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Funding
On May 5, 2026, a16z crypto announced Crypto Fund 5, a $2.2 billion fund for startups building crypto infrastructure and products. a16z isn’t waiting for another hype cycle. It's putting capital behind the parts of crypto that already look useful, including stablecoins, tokenized assets, on chain lending, payments, and AI agents.
The stablecoin thesis carries the most weight currently. Trading activity still rises and falls with crypto markets, but stablecoins keep gaining use in saving, cross border transfers, and payments. That’s the fintech read. Stablecoins aren't just trading tools. They're becoming payment, treasury, and settlement infrastructure.
Fund 5 also points to a capital markets build. Perpetual futures, prediction markets, on chain lending, stablecoin credit markets, and tokenized real world assets push crypto closer to financial workflows that run continuously and settle faster than legacy systems. The opportunity is infrastructure that reduces friction where money, collateral, data, and ownership move.
The Canadian market is perking up too, with a practical example in Canada’s first financial institution issued CAD stablecoin, while bank technology providers are building toward bank issued digital money. The next test is volume growth. Stablecoins and tokenized cash only matter if they improve settlement, treasury, lending, compliance, and payment workflows for real customers (while at the same time servicing robot customers too? Here's Google says to build for agents And humans).
And then there's AI that makes the fund more of everything all at once. a16z links crypto networks to software agents that can decide, act, and transact on behalf of users. Agent driven commerce needs payment rails, permissions, identity, auditability, digital property rights, and settlement that works without banking hours. Crypto infrastructure may become one way machines pay for compute, data, services, and financial access.
Where's the risk? A large fund can finance infrastructure, but customers still need simple products, trusted custody, clear rules, strong compliance, and measurable cost savings. The market has already punished crypto projects that don’t turn tech novelty into customer value. Fund 5 allocation will need to ensure builders can turn crypto infrastructure into everyday financial products that work better than the old rails.
If global venture capital is backing crypto infrastructure for payments, tokenization, and AI agents at scale, can Canada turn regulated digital asset rails into products that win real settlement, treasury, and financial services volume?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 4, 2026 | NCFA Fintech Insight | Digital Assets Blockchain And Tokenization

On Apr 29, 2026, NCFA published a resource post on crypto adoption data across 11 European markets, based on the ARI10 Report Cryptocurrency Adoption in Europe 2026. The data points to a market that's moved past early awareness but hasn’t yet settled into consistent daily use just yet. That gap is where the next phase of competition starts.
The study surveyed 11,068 respondents across 11 countries between Jan 9 and Jan 15, 2026:
Roughly four in ten respondents have already researched, owned, or traded crypto. Just over three in ten qualify as investors. People know what crypto is, and many have already touched it. Crypto is by far no longer fringe.
However, Poland’s 47.10% exposure rate and France’s 30.41% rate describe very different market conditions. Norway, Spain, and Romania also show stronger engagement than the overall average. For operators, that means Europe has different adoption curves. It breaks into local markets depending on income, education, age, product trust, and financial habits.
Single broad brushed strategies may miss the mark. A wallet, exchange, payment product, or tokenized asset platform needs to match how users actually behave in each market, not how the regional average looks in a slide deck.
Investors still participate primarily for financial gains. Nearly half point to potential value growth, and more than two thirds cite financial motives overall. That makes crypto adoption look less like daily payment adoption and more like investment market participation.
This actually strengthens the crypto infrastructure story. Exchanges, custodians, payment firms, banks, and tokenization platforms keep investing because they’re trying to move crypto from access to daily utility. But user behaviour still leans toward buying, holding, and trading. The next stage of growth and adoption depends on how useful crypto becomes inside regular financial workflows, not just easier to purchase.
Risk and volatility rank at 33.3%. Lack of funds follows at 32.1%. Technical knowledge comes in at 31%. Lack of trust in exchanges reaches 28.6%. Regulatory uncertainty ranks much lower at 9.3%.
Regulation supports trust and scale, especially for institutions. But regulation alone doesn't turn interest into everyday use. Users need clearer entry points, better risk explanations, stronger platform trust, and products that make participating in crypto feel normal and useful.
This is where the current market opportunity is in Europe. Not in chasing generic adoption, but by turning curiosity into confidence, and confidence into repeat and useful behaviour.
Crypto adoption has reached a point where awareness and regulation are no longer the main constraints (at least in Europe and based on this study). The next iteration depends on whether the industry can turn interest into trusted, useful, everyday financial behaviour. Access the full report on Crypto adoption in Europe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 4, 2026
The ability to hire the best available talent regardless of geography has become a baseline expectation for competitive companies. Engineering teams, creative departments, and commercial roles are increasingly filled by professionals located in countries where the hiring company has no operational presence. The problem is not identifying those candidates; it is employing them legally. Establishing a local legal entity in a foreign market typically takes three to six months, requires ongoing administrative maintenance, and creates permanent compliance obligations that are difficult to unwind if the market does not develop as planned.
For companies that need to hire now rather than after completing a multi-month incorporation process, this gap between hiring intent and legal readiness represents a real cost, in delayed product development, lost candidates, and competitive disadvantage. That's why global EOR services have moved from a niche HR solution to a standard tool in the international workforce strategy of companies across sectors.
An employer of record (EOR) is a third-party company that legally employs workers on behalf of a client organization in a foreign jurisdiction. The EOR holds the employment contract, processes payroll, withholds taxes, administers benefits, and maintains compliance with local labor law. The client company directs the employee's work on a day-to-day basis, while the EOR carries the legal employer liability in the local market.
Global EOR services extend this model across multiple countries simultaneously. In other words, a single provider can serve as the legal employer of record for employees located in dozens of different countries, managing the distinct compliance requirements of each jurisdiction through one coordinated service relationship. Thanks to this, companies can build internationally distributed teams without replicating the legal and HR infrastructure of each target market internally.
This is materially different from working with a staffing agency, which supplies candidates but does not assume ongoing employer liability. It is also distinct from a professional employer organization (PEO), which typically operates as a co-employer in markets where the client already has a legal presence. An EOR operates in markets where the client has no entity at all.
Here's when a global EOR model can enter the game: when the company's hiring needs outpace its legal infrastructure, and the cost or complexity of establishing entities in every relevant market is disproportionate to the hiring volume.
You should attentively analyze whether the following scenarios describe the organization's current situation:
The majority of companies that adopt global EOR services report that the model significantly reduces time-to-hire in new markets and eliminates the compliance overhead that previously made international hiring prohibitively complex for teams without dedicated global HR functions.
Understanding the operational mechanics helps companies set realistic expectations and structure the engagement effectively.
When a company engages an EOR provider, the worker signs an employment contract with the EOR entity in their country. That contract reflects local employment law requirements, including probationary period terms, notice periods, mandatory benefits, and severance entitlements. The client company signs a separate services agreement with the EOR, defining the commercial terms, IP ownership provisions, and the scope of the employer's day-to-day direction of the worker's activities.
The worker operates functionally as a member of the client's team. They follow the client's processes, use the client's tools, and report to the client's management structure. The EOR handles the payroll cycle, tax filings, benefits enrollment, and any HR administrative processes required by local law.
Compliance management is the core value of the EOR model. Labor laws vary significantly across markets, including mandatory minimum wages, statutory leave entitlements, public holiday requirements, employer social security contribution rates, and termination procedure rules. What is also important here is that these regulations change; a provider that was compliant twelve months ago needs ongoing legal monitoring to remain compliant today.
What reliable global EOR services should have from a compliance standpoint:
Modern EOR services are supported by software platforms that consolidate workforce administration across all active countries. These platforms typically cover employee onboarding and document collection, payroll processing and payslip delivery, benefits enrollment and management, time and expense tracking, and reporting dashboards that give HR and finance teams consolidated visibility across markets.
Pay attention to the self-service capabilities available to employees. A well-designed platform allows workers to access their own employment documents, view payroll history, submit expenses, and track leave without routing every request through an HR intermediary. This reduces administrative volume and improves the employee experience for distributed team members.
A large number of companies that engage global EOR services do so initially to regularize an existing contractor workforce. This transition is operationally straightforward when managed systematically.
We recommend completing this process market by market rather than attempting a simultaneous global conversion, which reduces coordination complexity and allows the HR team to verify that each country's transition has been executed correctly before moving to the next.
Not all EOR providers operate with the same model or coverage quality. The most highly demanded options in the enterprise segment typically offer their own in-country legal entities rather than relying entirely on sub-vendor networks, which produces more consistent compliance standards and clearer accountability.
From a financial perspective, pricing structures vary considerably across providers. Per-employee per-month flat fees are the most predictable and easiest to budget. Percentage-of-salary models become significantly more expensive at higher compensation levels, which matters particularly for senior technical and commercial roles. Apart from this, setup fees, country activation fees, and offboarding costs should be evaluated as part of total cost of ownership rather than ignored in favor of the headline monthly rate.
It will be helpful to request references specifically from companies with similar workforce profiles, including comparable team sizes, comparable countries of employment, and comparable roles. An EOR that performs well for a twenty-person team in Western Europe may not have the operational depth to support a two-hundred-person distributed team across Asia-Pacific, Latin America, and Africa simultaneously.
Typical integrations that a mature EOR platform should support include HRIS systems, finance and ERP platforms, expense management tools, and time tracking applications. A platform that cannot connect to the client's existing HR infrastructure will create parallel data workflows that increase reconciliation risk and administrative overhead.
Global EOR services remove the primary operational barrier to international hiring: the requirement to establish a local legal entity before employing anyone in a foreign market. First of all, they allow companies to hire compliantly in new geographies within days rather than months, which translates directly into faster team assembly and competitive advantage in markets where talent is scarce. Secondly, they transfer the ongoing compliance burden of cross-border employment to a specialized provider, freeing internal HR and legal teams to focus on workforce strategy rather than regulatory administration.
The organizations that use this model most effectively treat it as a long-term infrastructure decision rather than a temporary workaround. Selecting a provider with genuine in-country expertise, transparent pricing, and robust technology will determine whether the EOR relationship enables growth or simply adds a new administrative layer.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 1, 2026 | NCFA Market Activity | Payments And Market Infrastructure

On Apr 30 2026, Santander confirmed Ebury secured about £550M in funding led by Centerbridge Partners, with Santander, Vitruvian Partners, and 83North reinvesting. Santander will retain a 55% stake and positions Ebury as its core SME cross-border payments platform.
Ebury was founded in 2009 in London and focuses on cross border payments, foreign exchange, and trade finance for small and mid sized businesses. According to Santander, the platform serves more than 27,000 businesses, operates in over 160 countries, supports 140 currencies, and is active across more than 30 regulated markets. The company has delivered more than 30% annual revenue growth since 2020, reflecting sustained demand for SME-focused global payment infrastructure.
The model is built around consolidation of fragmented workflows. Businesses use Ebury to move funds, manage FX exposure, and access working capital in one system instead of relying on multiple banks and intermediaries. That reduces settlement friction, improves pricing transparency, and shortens execution time across cross border transactions.
This competitive positioning targets a structural gap. Large banks tend to focus on multinational corporates, while many fintechs focus on consumers or small merchants. Ebury sits in the middle, serving companies that operate internationally but lack access to sophisticated treasury and FX tools. By combining payments and FX, it captures both transaction volume and margin, which are often separated in traditional models.
The funding supports further expansion and investment in automation and AI across payment processing and compliance workflows. Santander places Ebury within its Payments Solutions division, which targets more than 15% annual revenue growth through 2028, showing that cross border SME payments are being treated as a core growth segment rather than an adjacent business line.
Worth noting that Santander recently received approval to operate in Canada through a Canadian banking licence. Combining that regulatory presence with Ebury’s platform creates a path to serve Canadian SMEs engaged in global trade, particularly those that require faster payments, integrated FX, and access to international liquidity.
For Canadian fintechs and financial institutions, this news raises the competitive bar. Cross border payments are becoming integrated infrastructure platforms rather than standalone services. Competing requires deeper integration into business workflows, specialization in trade corridors, or partnerships that extend global reach.
If banks control fintech platforms like Ebury, cross border payments stop being a service and become infrastructure. The open question is whether independent fintechs can compete at global scale or whether access to capital, licensing, and distribution will concentrate that control inside bank backed networks.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 30, 2026 | NCFA Insight | Capital Markets And Funding
Image: Unsplash/John McArthur
On Apr 30, 2026, FrontFundr released its 2025 Community Capital Report with the following top line figures:
These numbers reflect FrontFundr platform activity across multiple exempt market channels in 2025, including startup crowdfunding, offering memorandum, accredited investor, FFBA, and private market financial products such as MICs, REITs, and funds.
FrontFundr’s 2025 performance shows strong growth in both capital and usage. The platform facilitated $83.2M across 8,064 investments, marking a 23% increase in capital and a 91% increase in investment transactions year over year.
Noticeably, participation is scaling faster than capital. Average investment size declined, while the number of investors per campaign increased. That means broader access and more distributed capital formation rather than larger individual allocations.
Financial products continue to drive the majority of platform volume, accounting for 84% of total capital raised. This reflects ongoing demand from accredited investors for income oriented products such as MICs, REITs, and funds, and reinforces that the headline $83.2M figure is not purely startup funding.
At the same time, platform growth is supported by increased engagement across sectors. Technology, manufacturing, and consumer facing companies continue to attract strong investor participation, particularly where companies already have an engaged audience or customer base.
Several campaign examples highlight how the model operates at scale. Edison Motors raised $6.8M from 2,667 investors. Blossom Social raised $1.93M from 1,028 investors in approximately six hours. Gander Social raised $2.0M from 2,517 investors. These campaigns reflect a shift toward high participation rounds where capital comes from large numbers of individual investors.
The equity crowdfunding under National Instrument 45-110 is growing quickly, but remains small relative to overall private markets activity. FrontFundr reported $4.79M raised from 4,320 investors under the exemption, representing 93% market share and growth of 181% in capital and 187% in participation year over year.
Early stage capital formation is becoming more distributed, with more investors participating through smaller allocations. Campaign success increasingly depends on community engagement, distribution, and trust rather than traditional investor networks alone.
At the same time, regulatory issuer limits are starting to be hit. Several campaigns approached the $1.5M annual cap under NI 45-110, including Edison Motors and Blossom Social. When demand reaches these limits, issuers must align with other exemptions to continue raising.
Globally, the ceiling is higher than what Canada currently allows. In the United States, Regulation Crowdfunding allows eligible issuers to raise up to US$5M in a 12 month period (and there's been many petitions to increase the cap to US$20M). In Europe, policymakers are pushing to increase platform thresholds toward €12M, while the UK has removed structural barriers to larger public raises under new platform rules.
Canada’s lower cap now stands out. If investor participation continues to scale, the current limit may constrain companies with strong demand and push larger raises toward more complex and costly structures.
Early stage investing still remains illiquid and uncertain. Platform structure, disclosure quality, and regulatory oversight remain essential as participation expands.
Peter-Paul Van Hoeken, Founder and CEO, FrontFundr:
“2025 was a defining year for Canada’s private capital markets and for FrontFundr. The scale and pace of growth we saw reflects a clear shift in how capital is being formed in Canada. Community capital is no longer a niche channel—it’s becoming a core part of how companies raise and how Canadians participate in private market investing.”
FrontFundr had a solid 2025 result with expanding platform activity driven by higher participation and broader investment access. Equity crowdfunding continues to grow albeit from a small base. Community capital plays an important role in Canada's early stage private markets. The next phase of growth will depend on how well regulation, infrastructure, and investor protection evolve alongside rising participation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
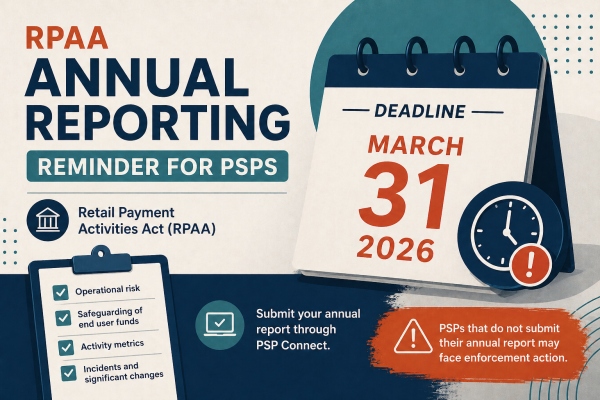
On Apr 27, 2026, the Bank of Canada reminded PSPs under the Retail Payment Activities Act that annual reports were due by March 31, 2026. PSPs registered after March 30, 2026 are not required to submit an annual report for 2025.
PSPs that missed the deadline should submit their report as soon as possible or face potential enforcement action.
The reporting framework is detailed. PSPs must follow the Bank’s annual reporting policy, which requires annual reports by March 31 each year, and its retail payment metrics policy, which covers the value of end user funds held, EFT volume and value, end users served, and other PSPs served. This turns reporting into an operating discipline (to avoid a year end scramble).
The Bank’s reporting guide shows that PSPs must report across operational risk, incident management, end user funds safeguarding, significant changes, incidents, activity metrics, financial information, and record keeping.
The form also asks about cyber security controls, third party service providers, agents, mandataries, safeguarding accounts, shortfalls, and independent reviews.
For operators, (1) data infrastructure must support audit ready reporting, (2) governance must match supervisory expectations, and (3) product design must account for regulatory visibility from day one.
For investors and partners, reporting compliance is a useful test of execution quality. Firms that can operate inside regulated environments with clean reporting, strong controls, and reliable evidence will have an advantage as oversight expands.
The Bank’s information session walks PSPs through annual reporting requirements, including required data fields, operational risk disclosures, activity metrics, and submission through PSP Connect.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Insight | AI, Fintech And Productivity

AI Image: Jobs vs Compute
AI layoffs are becoming a capital allocation story. In April 2026, large firms across technology, retail, media, and financial services kept cutting roles while at the same time spending more on AI, automation, cloud infrastructure, and operating efficiency.
That doesn’t mean all layoffs are as a result of AI, but boards are asking a harder question now as they divert capital from labour to compute: where does the next dollar produce more output, people, platforms, or compute?
The numbers are getting harder to ignore. Big Tech AI spending could reach about $600 billion in 2026. Meta plans to cut about 10% of its workforce while guiding to $115 billion to $135 billion in capital spending driven largely by AI infrastructure. Microsoft is offering a voluntary employee buyout as it manages rising AI and cloud costs. Snap is cutting about 16% of full time staff. Nike is cutting about 1,400 jobs, with technology roles taking most of the impact.
The decision has been made in the boardroom. AI investment is competing with payroll, product teams, operations, and layers of management. Every job and role now has to show where it adds judgment, customer trust, regulatory knowledge, risk control, or revenue that automation can’t easily replace.
A fintech that can process more volume and scale without adding the same number of people has a better margin story. A fintech cost structure that needs a new team every time revenue grows will be under pressure fast.
AI usage and early labour strain is already appearing before every company announces formal cuts. Entry level roles in AI exposed fields are tightening first. That’s where the next generation of operators and compliance talent usually starts.
A recent Armstrong Economics commentary on AI costs raises a useful counterpoint: AI can reduce headcount pressure, but it doesn't remove cost. For example, the cost of compute, vendor fees, data cleanup, cybersecurity, audit trails, , human review and workflow redesign are all part of real ROI calculations. For fintechs and financial institutions, the acid test is whether the full process costs less, runs faster, and keeps risk under control.
That makes unit economics more important than AI headlines. If those metrics improve, AI is creating operating leverage. If they don't, the company may end up moving cost from payroll to infrastructure in the end.
Nike may be a clearer signal for Canada than Meta. Canada has fewer Meta sized AI infrastructure bets, but it has many established firms that added apps, data projects, digital teams, and customer platforms during the low rate years. Some of that work created real value. Some became expensive to maintain, hard to scale, or too slow to justify.
As a result, many companies are replacing older internal builds with leaner AI enabled stacks, vendor platforms, and automation tools that reduce operating cost. That’s the opening for fintech infrastructure. Companies still need modern payments, identity, credit, fraud controls, compliance tools, treasury, and customer finance.
They just don't want every capability built and staffed internally. Easier said than done but the option is goals and motivations are to buy proven tools, connect them faster, and reduce cost without adding another large costly operating layer. It’s removing friction from financial workflows. Faster onboarding. Cleaner risk checks. Less manual reconciliation. Better fraud detection. More useful cash flow data. Compliance that costs less to run.
The economics are are already visible. AI agents and return on intelligence in finance shows that 77% of financial institutions report positive ROI from AI, while nearly half plan to allocate more than half of their AI budgets to agent driven systems.
Productivity gains are now the baseline expectation, not the upside case. That changes how financial services teams are built and what gets funded.
There are limits, though. If companies eliminate too many junior roles, they risk weakening the talent pipeline. Financial services can’t automate accountability (can they?). Someone still needs to understand the customer, the regulation, and the risk.
Founders and investors should monitor operating metrics to understand where leverage is. Revenue per employee. Gross margin. Onboarding cost. Support cost. Compliance cost per customer. Fraud loss rates. A fintech that grows without adding headcount at the same pace stands out. One that talks about AI without showing better unit economics doesn’t.
Canada is earlier in this cycle, but the friction is starting to show. Statistics Canada reports that about 6% of AI adopting businesses say they've reduced employment due to AI, which suggests the adjustment is underway but not yet widespread. Firms are not always announcing large AI driven layoffs (publicly), but they are slowing hiring, tightening teams, and pushing more output through automation.
That pressure is also showing up in large Canadian incumbents, even when AI isn't named as the cause. Rogers is offering voluntary departure packages to about half of its workforce as it looks to reduce costs.
Canada also won’t follow the US pattern exactly. The country has fewer hyper-scaleup companies and less direct exposure to massive domestic AI infrastructure spending. Canadian companies are more likely to buy AI capability through partners than build it internally. That creates a different risk. The US may adjust faster. Canada may carry this margin and efficiency friction longer.
It's important because productivity remains a concern. Statistics Canada reports that business labour productivity declined in late 2025.
The labour story is not about pure job cuts but whose rebuilding their operating model and productivity structure. If large US firms trade headcount for compute, Canadian firms need to trade manual work and fragmented systems for better infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
