




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Tech Ecosystem | June 6, 2025
Image: Freepik/travelscape
Web Summit Vancouver 2025 ran from May 27-30 2025 at the Vancouver Convention Centre attracting 15 727 attendees and with 1 108 startups from 117 countries, creating an electric atmosphere of discovery and deal making. Exhibiting startups spanned innovations in AI and machine learning, fintech and financial services, healthtech and wellness, and sustainability and cleantech.
Fintech solutions ranged from digital banking apps to blockchain payment rails, with Koho introducing a new international transfer service at the event. Founders pitched ideas, investors scouted opportunities, and conversations ranged from regulation to real-time fraud detection, confirming Canada’s growing role in global fintech innovation.
In the “Brands in Uncertain Times” session, Angus Reid of Angus Reid Group shared that nearly 50% of Canadians “vote at the cash register” by choosing brands aligned with their values. FCB Global CEO Tyler Turnbull added that Canadian consumers will pay 20-30% more for products produced and sourced in Canada, the premium on authenticity. For fintech companies, transparent fee structures and clear brand messaging are key to building consumer trust and loyalty.
AI dominated most panels, hallway discussions, and featured prominently across multiple stages. Sunny Madra, COO of Groq, announced Groq is now the exclusive inference provider for Bell Canada’s sovereign AI network, including two new data centres in British Columbia designed to bring AI processing closer to Canadian users. This new AI infrastructure will benefit fintech startups seeking access to low-latency, secure AI inference capabilities for real-time applications like fraud detection and compliance.
Sustainability and cleantech stood out alongside AI. Sessions highlighted how technology is driving environmental, social, and governance (ESG) goals, such as using AI to identify and price climate risks. Partners like OVHcloud showcased energy efficient cloud offerings, illustrating how infrastructure providers integrate ESG criteria into their services. For fintechs, embedding ESG considerations into product design and investment decisions is key for long term success. Not to mention the Competition Bureau's final rules on greenwashing that companies need to comply with.
4. Fintech Innovations and Cross-Border Payments
Financial technologies and services was one of the top represented verticals, with companies demoing solutions from digital banking apps and blockchain payment rails to regtech platforms. Toronto-based challenger bank Koho introduced its international money transfer service to over 190 countries, promising most transfers would arrive within 30 minutes during beta. By addressing opaque rates and slow settlement times, Koho’s launch shows how fintechs who listen to consumer issues can earn trust and turn these insights into new products/services that resonate with both Canadian and global markets.
5. Inclusive Entrepreneurship and Diverse Teams
44% of startups at Web Summit Vancouver were founded or co-founded by women. Beyond fintech, local firms such as Doubl, Revol Cares, and Aruna Revolution showcased solutions for women’s health and wellness.
Within financial services, fintech teams highlighted embedded credit services for underbanked populations and regtech platforms that serve diverse small-business owners. It's really diverse founding teams that drive not just inclusive entrepreneurship but solutions that resonate with underserved markets, strengthening innovation overall.
Technology is no longer judged only by what it can do, but by who it includes, what it protects, and how it earns trust. For fintechs and founders alike, this is the real edge of innovation and frontier.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Regulation | June 6, 2025
Image: Freepik
On June 5 2025, the Competition Bureau of Canada released final guidelines for greenwashing rules. The new rules apply to any business making environmental claims when selling products or promoting business activities including financial tech companies, ESG platforms, green loan providers, carbon credit startups, and any firm using green language in advertising, websites, or investor materials.
These updated guidelines reflect changes to the Competition Act which began on June 20, 2024. The law now clearly defines when green claims are allowed and what kind of evidence is needed to support them. The Bureau says they developed the final rules after reviewing over 400 public submissions, and are now in force. Now any firm that makes an environmental claim about it's product or business must be ready to prove it with fact-based evidence and proper documentation.
There are two provisions in the new Competition Act about greenwashing, (1) one about environmental benefit claims of individual products; and (2) another about environmental claims about a company and its business activities.
If a fintech makes a green claim about a product (i.e., protects the environment or reduces harm), it must be backed by suitable testing before the claim is made. Anecdotal evidence such as customer reviews or sales figures are not proper testing.
If a fintech claims that the company is environmentally responsible or heading toward net zero, then the claim must meet a reliable standard or an accepted protocol in Canada and internationally, including frameworks like ISO 14064 or GHG Protocol.
The Bureau makes it clear that companies must not exaggerate environmental benefits. Can't be vague or use 'feel good' language like 'eco-friendly' or 'sustainable' unless the claim is backed by specific evidence. For example, a product that uses 20% recycled packaging cannot advertise itself as 'environmentally neutral' unless the rest of the product has been tested to meet that standard.
Claims about future benefits, such as achieving carbon neutrality by 2030, require a clear and verifiable plan with interim targets and real progress tracking towards that goal.
There are numerous green financial products from lending products tied to home retrofits, solar energy or electric vehicles to 'low carbon' investment portfolios that will be impacted. If these products are being advertised as good for the environment or tied to climate goals then firms must now have data/documentation to support those claims or face enforcement.
The Bureau expects to see testing evidence before any green claim is made. What was the methodology used to support the green claim and is it internationally recognized and suitable in the Canadian context.
Penalties for corporations can reach up to $10 million for the first violation and $15 million for every violation thereafter. Also, if the value derived from the green claim benefit cannot be accurately measured, then the penalty can be up to 3% of the corporation's global gross revenue. The Bureau has already taken enforcement action in previous greenwashing cases, including against Keurig and Volkswagen.
Also as of June 20, 2025, individuals and private organizations can apply directly to the Competition Tribunal to challenge misleading green claims, opening the door for private sector oversight and potential legal action from investors, competitors, and consumer advocates.
There is however one safeguard for companies, which is a due diligence defence. If a fintech can show that it took reasonable steps to verify its claims and they followed recognized practices, it may help them avoid fines. Going forward, the pressure and burden is on companies to have robust compliance and documentation from engineering product development teams to marketing.
The bar is raised. For fintechs operating in Canada, green language can no longer be used for branding and promotion without properly being supported as it's a legal risk. Having said that, Canadian fintechs that can back up their green claims and properly document them will improve credibility with customers, regulators and global partners alike. Now how many of the banks will back off from their environmental claims?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 28, 2025
Image: Freepik
As digital innovation continues to transform how we live, the concept of connected homes is no longer futuristic, it's a growing reality. From energy management to enhanced safety, technology is reshaping the expectations homeowners have from their living spaces.
In this evolving landscape, many are turning to intelligent home automation for future-proofing systems. By deploying smart electrical devices and equipment that can learn, adapt, and self-optimise, homeowners are not just improving convenience but actively preparing their homes to meet long-term functional and sustainability goals.
One of the most compelling advantages of home automation and its capacity to enhance operational efficiency makes it a valuable asset. By employing programmable schedules and smart sensors, home systems can adjust temperature settings, lighting levels, and appliance usage.
These automated adjustments reduce wastage, extend the life of electrical devices, and contribute to lower utility bills. Its ability to manage Moreover, the ability to remotely monitor and manage systems adds an extra layer of convenience and resource optimisation.
The move towards sustainable building practices is gaining momentum, and home automation plays a central role in this transition. Advanced automation systems can integrate with renewable energy sources like solar panels and smart meters to track consumption patterns and shift usage to off-peak hours.
This not only supports national sustainability goals but also enables homeowners to make more informed decisions regarding their energy use. Homes equipped with smart systems can reduce energy consumption.
Incorporating home automation also enhances safety and security. From motion-sensor lighting and automated door locks to surveillance systems and smoke detectors, these devices can be programmed to alert homeowners and emergency services instantly in case of suspicious activity or hazards.
The feature to receive real-time alerts and control safety systems remotely ensures that occupants are protected, whether they are at home or away. This level of proactive security management makes home automation in smart homes a crucial component of modern living.
Another critical feature of home automation is its scalability. As technologies evolve and user needs change, these systems can be updated or expanded without requiring significant infrastructure changes. This modularity supports future innovations such as AI integration, voice control, and interoperability with new devices or platforms.
For example, integrating Human-Machine Interfaces HMIs with home automation systems allows users to interact more intuitively with their home environment, improving usability and accessibility.
The data collected by automated systems offers valuable insights into user behaviour and equipment performance. Analysing this data can help identify inefficiencies, predict maintenance needs, and inform system upgrades.
By incorporating predictive analytics and machine learning capabilities, home automation can evolve into a self-optimising ecosystem.
The success of any home automation setup relies not just on innovation, but on the reliability and quality of the systems integrated. High-grade electrical equipment and smart devices ensure that automation delivers consistent results, even as household demands evolve.
Well-engineered systems are more likely to:
In today's fast-paced and energy-conscious world, home automation in connected living environments is more than a convenience; it's a long-term investment. It enhances energy management, boosts safety, supports sustainability, and adapts to technological change.
By deploying the right systems and partnering with a reputable electrical brand, homeowners can create efficient, future-proof spaces that evolve with their lifestyles. Such collaboration ensures that the electrical devices incorporated into the home automation setup are not only of high quality but also compliant with the latest safety and energy standards.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Data Research and Strategy | May 25, 2025

Image created by AI, Personas based on real data from 2024 Financial Lives, FCA
Four FCA personas reveal where fintech innovation must go next
On May 16, 2025, the Financial Conduct Authority (FCA) published one of the richest datasets ever on UK consumer financial behaviour, resilience, and preferences called, "Financial Lives 2024 survey". It's an annual snapshot taken ever 2-3 years and offers valuable benchmarks and insights into how financial institutions, fintechs and financial engineers can translate this data into strategy.
There are 18 excel sheets with various tabs covering survey responses for almost 1300 survey questions pertaining to a wide range of topics such as attitudes and product/service ownership of payments, retail banking, consumer investments, general insurance and protection, mortgages, credits and loans, assets and debts, cash savings, advice/guidance and pension. There's also tracker data tables for comparing and analyzing changes over time across 2017, 2020, 2020 and 2024 surveys.
Drawing directly from the FCA 2024 Financial Lives survey results, we created 4 personas that reveal who is underserved, gaps in the ecosystem, and where fintechs, banks, and credit unions should consider focusing on to rebuild trust and relevance.
Amira is a young adult struggling with inconsistent income from various gigs, rising living costs, and a heavy reliance on credit. She is digitally active but financially stretched and uncertain as to who she can trust. Survey data shows:
Fintechs should build real-time tools that show all credit and BNPL use in one place, including spending limits, that help users like Amira avoid taking on more debt than they can handle. Adding clear, user-led budgeting flows into existing BNPL workflows can help bridge shortfalls and help build trust with transparency.
Stella is an older consumer who likes to avoid debt, prefers analog channels, and feels underserved by digitally native services. She values trust and simplicity highly and struggles to access new tools. Survey data shows:
Financial institutions should consider creating hybrid formats that combine print materials with digital access points, such as QR codes linking to audio summaries. ESG and pension tools can be made more accessible with phone helplines and in-branch tutorials to help consumers who lack confidence to gain confidence and fill in comprehension gaps.
Rohan is a confident, digitally native, and actively manages savings, investments, and often finds himself switching providers to maximize value. He expects clarity, ESG transparency, and integrated experiences.
Rohan needs a unified dashboard that lets him integrate his finances across pension, savings, and ESG investments. Fintechs can lead here by offering smart comparison tools that verify impact metrics, automate vendor switching, and offer ESG guidance within the same experience.
John is a middle-aged adult that is juggling aging kids, debt, complex commitments, and low financial resilience. He is time-poor, questions everything, and is stuck with outdated, fragmented financial tools. The survey shows:
Institutions must prioritize credit and debt consolidation tools for this segment by offering personalized paths and support towards financial recovery. Embedding phone or online chat support into their digital journeys can help reduce friction, while demonstrating quick wins to build confidence and encourage engagement.
We've come up with the following table that matches the 4 personas with specific fintech strategies tailored to their behaviours, needs, and gaps, all based on the FCA's 2024 financial lives data, and to support product design, channel strategy, and business model decisions.
| Persona | Product Opportunity | Channel Strategy | Business Model Insight | Ecosystem Gap |
| Amira – Young Borrower | BNPL budgeting + affordability | Mobile-first, embedded in BNPL apps | Freemium with affiliate links to trusted debt tools | Risk-aware BNPL integrations |
| Stella – Conservative Saver | Print-to-digital ESG education | Branches, phone, community agents | Subscription or pay-per-use legacy planning tools | Print-digital pension guidance |
| Rohan – Digital Builder | ESG + switch optimizer dashboard | Self-serve, in-app investing hubs | B2C SaaS with optional robo-advice tier | ESG decision confidence |
| John – Overloaded Middle | Modular savings + credit coach | Web app + human phone fallback | Hybrid subscription + nonprofit partnership model | Blended digital advice models |
Each of the 4 personas created actually represents thousands of real individuals and their financial lives in 2024, caught between fragmented services and changing financial needs.
The profiles above are designed to help fintechs and institutions develop a targeted roadmap based on clearly defined, data-driven groups with targeted solutions, to help provide responsible and more inclusively designed financial products/services for underserved groups in need. A similar survey in Canada would probably produce similar results.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | May 20, 2025
Image: Deloitte 2025 Gen Z and Millennial Survey
The 14th edition of the annual 2025 Deloitte Global Gen Z and Millennial Survey provides a global snapshot of generational attitudes towards work, money, technology and values, offering fintech founders, banks, credit unions, and policymakers core insights into what's driving the new economy and markets.
By 2030, Gen Z and millennials will represent nearly 75% of the global workforce. These generations are not just using financial technologies. They are building it, and reverse engineering what problems they should solve while establishing new expectations for how financial service tools operate.
The self-administered online survey data was collected from October 25 and December 24, 2024, gathering responses from a total of 23,482 respondents including 14,751 Gen Zs (born 1995 - 2006) and 8,731 millennials (born 1983 - 1994) across 44 countries, including regions such as North America, Latin America, Western Europe, Eastern Europe, the Middle East, Africa, and Asia-Pacific.
Young workers are very anxious about money.
- 48% of Gen Zs and 46% of millennials say they do not feel financially secure
- 52% of both groups live paycheck to paycheck, and over 33% struggle with basic monthly expenses
- 41% of Gen Zs and 44% of millennials are unsure whether they’ll be able to retire with financial comfort
These data points highlight the need for fintech products go well beyond basic budgeting dashboards. Gen Z and millennials need fintech tools to help them achieve financial resilience, such as income stabilization or smoothing, flexible savings tools, automated rent/bill buffers, and fair access to emergency funds. Financial service providers that can help reduce voltaility, and not just optimize credit scores, have an opportunity to earn trust and loyalty.
Adoption of generative AI tools is already a daily routine for young professionals.
- 57% of Gen Zs and 56% of millennials use GenAI tools in their daily work
- About 30% of each group use AI most or all of the time
- 74% of Gen Zs and 77% of millennials believe AI will significantly change how they work within the next year
These users are engaging with and building fintech products through an AI-first lens. They expect tools to respond in natural language, deliver almost instant relevant insights without friction, and adapt quickly. Static interfaces and dated workflows will lose ground quickly.
Fintech platforms in particular need to integrate GenAI not just in the back-end system but into product design and customer experience because these cohorts are fluent in AI which is quickly becoming the standard in how they source, think and consume.
Gen Z and millennials care less about climbing corporate ladders and more about doing work that aligns with their values.
- Only 6% of Gen Zs say their main career goal is to reach a leadership role
- 44% of Gen Zs and 45% of millennials have left jobs that lacked purpose
- 41% of Gen Zs and 40% of millennials have rejected employers due to ethical or values misalignment
For fintech employers, this creates both risk and opportunity. A strong mission with aligned values can attract high performers but the opposite will scare talent away quickly. To attract and retain the next generation of fintech talent, companies must offer more than good compensation. They need clear values, meaningful impact, and room for personal growth.
Formal degrees are no longer the default path into the fintech sector.
- 31% of Gen Zs and 32% of millennials chose not to pursue higher education.
- 70% of Gen Zs and 59% of millennials are building career skills at least once a week.
- The majority are doing this on their own time, outside of work hours.
There's more acceptance and shift now towards non-traditional education from bootcamps and peer networks to self-teaching, which has huge implications for hiring, funding, and human capital development. This means founders, operators and technical resources, may not originate from familiar backgrounds. Fintech leaders and investors need to adapt recruitment and due diligence models to focus more on traction, experience, and skills - and not just degrees.
Environmental and ethical values are a key part of how decisions are made.
- 65% of Gen Zs and 63% of millennials say they are willing to pay more for environmentally sustainable services
- 23% of Gen Zs and 22% of millennials have researched a company’s environmental practices before accepting a job offer
- Almost 50% say they’ve left or declined work that didn’t match their personal ethics
Social and environmental alignment is becoming a core user expectation, not a brand differentiator. Fintechs must design for transparency and shared impact from day one.
Fintech companies and financial institutions must design and deliver intelligent products with purpose and transparency that meet the moment of Gen Z and millennials who are under financial stress, fluent in AI, and prioritize values and ethics. The opportunity is to not just help these generations but to earn their trust and grow with them to create the next iteration of smart, modern, and purposeful finance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Signal | May 2, 2025
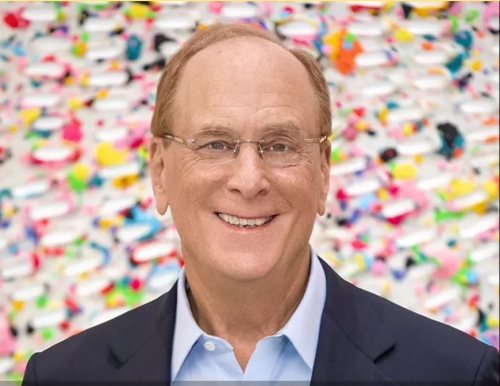
Image: Larry Fink, Chair of BlackRock (Website, 2025 letter to investors)
Last month, Larry Fink the Chairman of BlackRock delivered his vision for unlocking private markets and the future of capital markets innovation in his 2025 annual letter to investors. His letter essentially outlines a strategy and roadmap that fintech players, especially in Canada can see it as a call to action. In his own words, Fink discusses areas of focus that have the potential to democratize private markets that traditionally have been seen as opaque and harder to value with less liquidity, less regulation and limited participation by institutional and high-net worth individual investors.
Below are five direct quotes that should excite fintech builders and investors and signals a turning point and window of opportunity, especially when they hear it from the head of the world's largest asset manager directly.
1 “Private markets don’t have to be as risky, or opaque, or out of reach. Not if the investment industry is willing to innovate.”
Fink says private markets need to become easier for more people to access. In the past, only large funds and institutions could invest in things like private equity or credit (loans), but that is starting to change. New tools are helping to open the door with automated data platforms, risk analysis engines, and tokenization infrastructure that turn investments into digital tokens that are easier to buy and sell.
In practical terms, this means fintech firms that can bring transparency, indexing, or fractional access to private assets will gain investor and consumer interest. BlackRock itself acquired Preqin, a leading private markets data provider to drive this data led transformation.
According to McKinsey's 2025 private equity (PE) report, global private equity AUM remains well above $13 trillion and 2024 deal values rebounded by 14% to $2 trillion, for the third highest year on record for PE activity.
2. “Every stock, every bond, every fund—every asset—can be tokenized.”
This may sound speculative but it's not. Fink is laying down the gauntlet for a future where asset ownership is digitized and real time. Why? Because the big unlock here is yield. If tokenization allows $100 investment plays of private equity or infrastructure deals, then platforms can create products that serve both retail and institutional climates using much of the same structure.
Boston Conulsting Group's 2024 whitepaper "Tokenized Funds: The Third Revolution in Asset Management Decoded" forecasts that tokenized funds could reach over $600 billion AUM by 2030, especially if the growth pattern is similar to exchange-traded funds (ETFs).
3. “Artificial intelligence will transform how we understand markets and allocate capital.”
This isn't about chatbots. Finks talking about artificial intelligence (AI) as a capital allocation engine. Using AI to assess and predict risks, identify high potential assets, and help funds build and maintain more resilient portfolios. AI is already being used to evaluate startups, monitor compliance, and optimize the underwriting of private credit.
In February, the World Economic Forum wrote that only 2% of private equity firms will realize significant value from AI investments in 2025, however 93% anticipate moderate to significant benefits within a three to five year outlook.
The opportunity is clear at this point, such that Canadian platforms that integrate AI to automate deal flow and optimize investor matching will have a competitive offering and advantage in the near future.
4. “We're great at extending people's lives, yet we hardly spend any effort helping them afford those extra years.”
Fink knows that retirement is a crisis waiting to happen. In Canada by way of an example, the 2023 Canadian Retirement Survey by the Healthcare of Ontario Pension Plan (HOOPP) unveiled that 44% of non-retired Canadians between 55 and 64 had less than $5,000 in savings, and 75% had $100,000 or less saved for retirement.
Fink’s answer is a to help retirees by providing a predictable retirement paycheck model, which BlackRock is launching with their LifePath product in the U.S.
This is an area that fintechs can build on by creating digital retirement wallets with automated income streams. How about a syndicated annuity structure or micro investment portfolio that can mimic a steady paycheck. With a proper structure, these models could scale to serve the self-employed and gig economy workers who need retirement planning options, and the earlier the better.
5. “Capitalism did work—just for too few people.”
Fink is talking about allowing more investors into the tent, more geographic and social inclusion. Capital markets must be both global and local at the same time, and talks about enabling global partnerships like their joint venture Jio-BlackRock India, to help them scale their own capital markets.
For Canadian fintechs, this means working to provide smart and modern solutions for underserved regions, including Indigenous communities, rural investors, and newcomers to Canada. Prosper Canada's learning hub cites approx 15% of over 5 million Canadians are underbanked or without access to traditional financial services. That's why it makes initiatives like Koho's postal banking partnership with Canada Post exciting and important at the same time.
BlackRock led by Larry Fink is investing real money and a long term focus on financial technology innovation in capital markets, including tokenization, AI decisioning tools, and an expansion of private capital markets that is already afoot. Fintechs and investment platforms that align with these opportunities stand to benefit from the next iteration of financial infrastructure that will be more inclusive, more data driven, and more robust to deliver long term value for more people.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
ESG | April 30, 2025
Image: Freepik
Retuers reports that Royal Bank of Canada has stepped back from its $500 billion sustainable finance target, which was originally pledged in early 2021.
In its 2024 sustainability report (152 page PDF), RBC wrote that it would no longer publish several climate-related metrics because of the recent changes to Canada’s Competition Act that now require firms to fully support environmental claims with evidence. The Competition Bureau of Canada also published a companion link outlining their perspective on deceptive marketing and views on environmental claims and greenwashing in Canada.
An example of one of the metrics that RBC is no longer reporting is the energy supply ratio, which compares financing of low carbon projects to fossil fuel ones. RBC used to report the metric in past disclosures under shareholder pressure, such as from the New York City Comptroller. However, RBC now says it cannot share it publicly due to the updated laws. It's worth noting that RBC still tracks these metrics internally but it simply stopped reporting them to avoid legal risk.
RBC is part of a larger trend with several major Canadian banks recently exciting the Net Zero Banking Alliance and walking back similar commitments. In addition to the legal risk of 'greenwashing', these decisions are being made following increased scrutiny from regulators, investors, and advocacy groups.
All environmental or climate claims need to be backed by clear evidence, including proof of how the data was calculated (not just the result). Companies must also use internationally recognized standards or methods of calculation like ISO or the Task Force on Climate-Related Financial Disclosures (TCFD). So when a company says it's funding green projects or working towards net zero, it MUST be able to show exactly how with verifiable evidence. The Competition Bureau explains the changes here.
This is surely a turning point in Environmental, Social, and Governance (ESG) and climate reporting in Canada. Institutions must now take climate statements, especially financial ones, more seriously as they have to be accurate, verified, and legally on the right side.
For fintechs and banks that rely on reporting ESG data as either a competitive advantage or primary part of their model, they must strengthen internal tracking and reporting systems if disclosing. Any vague promises about green initiatives is no longer enough, and the cost of getting it wrong is now legal exposure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016