




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Fintech | Oct 3, 2025
Image: Freepik/newelement
On September 26, 2025, the Globe and Mail released its 2025 Report on Business ranking of Canada’s Top Growing Companies. The annual list tracks Canadian firms based on three-year revenue growth, offering a quick snapshot of where innovation is scaling fastest (think revenue, headcount, growth).
This year’s ranking features a great group of fintech and digital finance firms that are impacting how Canadians borrow, pay, invest, insure, and embed financial services into everyday life.
| Rank | Company | Sector | Description |
| #3 | Gearlay | Web3 / Blockchain | Blockchain-based enterprise financial software |
| #4 | Float | Lending & Embedded Finance | SME finance and corporate card platform |
| #5 | veritree | ESG & Green Finance | Digital carbon credits and reforestation finance |
| #11 | Novisto | ESG & Green Finance | ESG disclosure, data, and reporting platform |
| #24 | FundMore | Lending & AI | Automated mortgage underwriting |
| #32 | Quandri | AI & Automation / Insurtech | Insurance automation bots |
| #39 | Autocorp.ai | AI & Lending | AI-powered auto retail finance |
| #44 | Helcim | Payments | Merchant payment processing |
| #57 | CapIntel | WealthTech | Digital platform for advisors and wealth managers |
| #62 | PomeGran | Digital Infrastructure | Broadband and connectivity backbone |
| #65 | BOXX Insurance | Insurtech | Cyber insurance and protection |
| #72 | SWTCH Energy | Payments Infra / Energy | EV charging + payments integration |
| #86 | Makeship | Alternative Finance / Crowdfunding | Creator crowdfunding platform |
| #108 | Fintel Connect | Web3 / Marketing | Performance marketing for fintechs and crypto |
| #110 | Justwealth | WealthTech | Robo-advisor portfolio management |
| #112 | HONK | Payments | Contactless mobility/parking payments |
| #119 | Merchant Growth | Lending & SME Finance | Working capital financing |
| #129 | MindBridge | AI & Regtech | AI anomaly detection and audit |
| #137 | Loans Canada | Lending & Alt Finance | Loan marketplace and credit scoring |
| #140 | PolicyMe | Insurtech | Digital-first life insurance |
| #149 | Zum Rails | Open Banking & Payments | Open banking and payments APIs |
| #158 | Trolley | Payments | Global payouts and compliance |
| #204 | FundThrough | Lending & Alt Finance | Invoice financing and cash flow optimization |
While the Globe and Mail ranking provides a valuable view of Canadian fintech growth, it is far from exhaustive. Many high-growth firms remain absent because they operate in stealth mode, choose not to disclose financial data, or do not meet eligibility thresholds. Early-stage innovators, companies with holding structures abroad, and ventures acquired by larger incumbents also fall outside the ranking.
For NCFA’s community, this means the list represents only part of the country’s dynamic ecosystem of fintech, Web3, AI, alternative finance, and digital-first ventures that are scaling globally. For a broader view of Canada’s financial tech innovation landscape, see NCFA’s fintech directory at https://fintechcanada.io/.
Canadian fintech companies are excelling in lending, payments, Web3, insurtech, ESG, AI, digital infrastructure, and many other subcategories. These companies mirror how regulation, access to capital, and collaboration between industry and government is critical to ensure Canadian fintechs continue to thrive in an increasingly globally competitive landscape.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Crowdfunding | Oct 1, 2025
Image courtesy of AI
On March 7, 2025, Rugby Canada announced a bold public campaign to fund its women’s high performance team to England 2025. The campaign laid out a $1 million shortfall to cover the full season's program that costs $3.6 million (but the union's budget fell short). So to close the funding gap, they opened the doors to fans, alumni, and corporate donors and launched a dedicated donation portal for this effort: Mission: Win Rugby World Cup 2025 donation portal.
That night, the campaign thermometer sat at zero. By morning, it was alive as part financing tool and part storytelling engine that sparked a national movement in Canadian sport.
Rugby Canada needed more than dollars. They needed narrative. The early campaign push did three essential things well:
They didn't just ask for support but described the exact dollars missing and how each contributed dollar would map to camps, nutrition, recovery, and test matches.
Supporters weren’t just donors but they were treated as 'partners' in getting the Canadian Women's Rugby team ready for the World Cup 2025, a massive global sporting event.
Independent rugby media tracked progress. In April, RugbyPass ran a report noting the still‑open funding hole and provided key updates in how far along the drive had come, and how much further they still needed to go to achieve their mission.
As the 2025 Women's Rugby World Cup (hosted in England) drew closer and closer, media narratives framed Canada not just as underfunded underdogs but as gritty, scrappy, and deserving contenders. Sky Sports ran a feature titled “How non‑professional Canada crowdfunded its way to the final push,” saying pledges “reached 95 percent.”
Meanwhile, ESPN ran a narrative piece under the banner “Canada crowdfunded their way to the World Cup” juxtaposing the team’s funding shortfall with their on‑field ambitions.
Kudus to participating media that helped raise awareness for such an important Canadian funding drive. It really shows what's possible when the full ecosystem gets behind an initiative and drives momentum forward. There's a natural connection between executing a well timed and focused financing campaign and executing a key sports performance, and the public knows it. #ElbowsUp
When England 2025 kicked off, Canada stepped onto the pitch motivated by even greater purpose, not a team suffering by funding shortfall anxiety.
In pool play they went undefeated, carving out physical, disciplined performances that turned heads.
In the quarter final, they defeated a powerful Australia squad.
In the semi final, they shocked the rugby world by defeating New Zealand (perennial favourites) to reach their first Women’s Rugby World Cup final.
On September 27, before a packed Twickenham, Canada faced hosts England. They lost but not meekly. In the aftermath, coach Kevin Rouet and captain stressed that the match was decided on performance, not excuses, a point that resonates in Reuters’ coverage of the final.
Crowdfunding bought the players the chance to compete on equal footing, free of resource excuses. The lesson for Canada as a sporting nation was significant. When supports and fans step in to close gaps, institutions can't ignore the demand for sustainable, professionalized backing of women’s rugby.
Players adjusted their off season budgets and personal spending to show they were all in on the campaign narrative.
Coaching staff scheduled extra camps contingent on fundraising milestones, keeping the team in lockstep with the thermometer.
Each media checkpoint (50%, 80%, 95%) became a moment of drama as the story unfolded. Would the final stretch succeed or stall? That tension made the campaign itself a parallel storyline to the competition.
Critics wondered whether public fundraising blurred lines between sport and fandom but supporters embraced the risk, seeing their dollars as equity in national ambition at a time when Canada needs to buckle down and drive through the line.
When everyone's in the same boat, the winds will sail.
This was more than just a funding story. If you want one of those, feel free to read the real story of access to capital. It was about turning a resource gap (a modern day limitation) into shared ownership.
Canada’s women made their financial constraints visible, linked every dollar to performance outcomes, and invited supporters to become backers in the journey. That transparency changed how Canadians see women’s sport funding not as charity, but as investment with real returns.
The campaign also created accountability. Once the thermometer went public, the team owed backers results, not just thanks.
The story will not always be this dramatic, but the connections and motivations are real, and crowdfunding amplifies that blueprint. Define the gap, own the narrative, attach every contribution to a tangible outcome, and treat supporters as true partners.
Collaboration was at the core! Players, fans, alumni, sponsors, and media all carried their share of the work. As Canada’s women look beyond 2025, the responsibility now shifts to institutions, national sport bodies, sponsors, and public agencies to ensure future generations no longer need to crowdfund their path to the world stage, or maybe they should! #GoCanada
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
M&A | Oct 1, 2025
Image: Freepik
On September 18, 2025, US-based fundraising solutions provider RaiseRight announced the acquisition of Toronto-based FlipGive, a Certified B Corporation known for cashback shopping combined with community fundraising tools. Terms of the deal were not disclosed.
RaiseRight is based in Grand Rapids, Michigan and best known for scrip and gift card fundraising programs that direct spending power to local groups. The company cites more than $900 million raised with over 750 brand partners across 30 years of operations.
FlipGive first went public in 2013, self-described as a retailer-driven fundraising model for schools, sports teams and communities. When they first launched, the National Crowdfunding & Fintech Association of Canada listed FlipGive on it's original crowdfunding directory (not maintained since Jan 2019, as NCFA hosts a new fintech directory in Canada here. as crowdfunding for non profits through product sales and donations, a model that merged a crowdfunding ethos with shopping rewards and donations.
The focus evolved from one time pledges to everyday shopping that earns cash back for teams and community groups. Retailers and restaurants share a percentage of transactions, which turns routine purchases into a steady funding stream.
FlipGive later scaled embedded rewards and reported strong growth, including a $4 million Series B financing round in 2023 in an funding roundup mentioning FlipGive.
According to FlipGive’s own platform data, teams have raised more than $56.6 million through the service, converting everyday purchases into direct support for youth sports and community groups. This total reflects contributions generated from more than 50,000 teams (including my kids hockey team fundraisers!) via $425 million in sales across 900 brands, serving more than 900,000 FlipGive members.
These numbers clearly confirm the demand and impact of the cashback model and how it's grown into a significant funding source for local teams.
Nick Lee, Co-founder of FlipGive:
"From day one, our goal has been to support families and make team fundraising simple and effective. Joining RaiseRight, who shares our mission and values, ensures a future where even more families can benefit."
FlipGive’s brand and Canadian operations will continue while its technology integrates into RaiseRight’s broader platform. The combination adds white label rewards, scrip gift cards, online shopping, dining, and travel into one stack that organizations can use to fund sports, schools, and community programs.
Lou Agnese, CEO of RaiseRight:
"FlipGive has played a valuable role in shaping how communities approach fundraising through its technology and platform. We are excited to expand into the Canadian market and thrilled to welcome the FlipGive brand and team into the RaiseRight family. We will continue to build on FlipGive's innovations to deliver even greater value to the communities we serve across Canada and the United States."
This deal connects two complementary funding rails. FlipGive’s commerce driven crowdfunding roots evolved into cashback infrastructure with RaiseRight’s long running gift card model built to scale. Together they offer a cross-border platform that monetizes everyday spending for community funding while maintaining a social mission. For Canadian fintech and nonprofit stakeholders, the main questions are how will RaiseRight's acquisition steward FlipGive’s B Corporation identity and how integration will affect service for Canadian teams.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
European Fintech | Sep 8, 2025
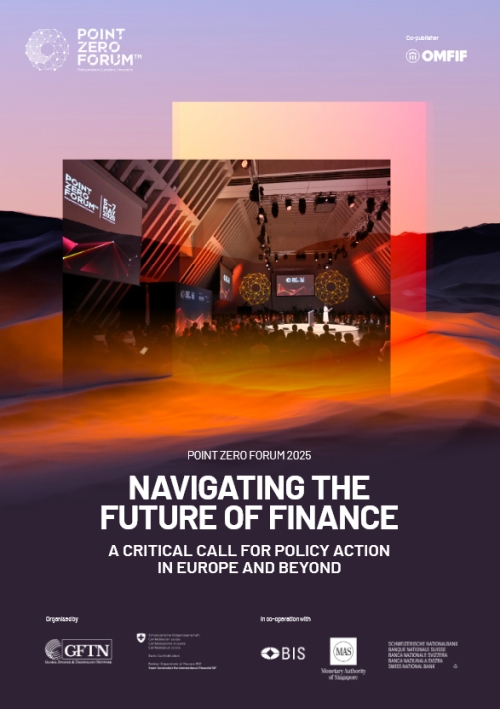
Image: Navigating the Future of Finance magazine (Point Zero Forum)
The 2025 Point Zero Forum (Jun 24-26) in Zurich drew 1,350 participants from 66 countries, including over 20% from public sector institutions. Across 121 sessions spanning 95 hours, 329 speakers explored the future of finance and technology. These numbers matter because the forum is where central banks, regulators, and institutions compare notes on what is implementable now, not just what's aspirational.
For Canadian fintechs, the conversations in Zurich are a warning and an opportunity. Europe is moving quickly to reset its financial infrastructure. Canada risks lagging unless it adapts. Read the post 2025 Point Zero Forum magazine, "A Critical Call for Policy Action in Europe and Beyond" (24 page PDF)
Offline payments and infrastructure security were considered a matter of national sovereignty, not just technology. Danmarks Nationalbank warned: “Without power, many offline payments methods aren’t viable,” linking payments directly to energy security.
The world’s largest stablecoin Tether confirmed it will leave Europe because of reserve and regulatory requirements. This shows that Europe is treating payments, AI, and data as part of its sovereignty strategy.
Canada has its own domestic payment systems operated by Payments Canada, but Canada still doesn't have live operating real-time retail payment rails. In cloud services, Canadian banks and fintechs are still dependent on American providers like AWS, Microsoft, and Google.
Central banks are now focused on tokenized settlement. The Swiss National Bank said: “Price stability is our main focus also in challenging times,” while the European Central Bank stressed that central bank money must remain “available and useful” in tokenized markets.
The Bank of England suggested that oversight of stablecoins may evolve as the “singleness of money” assumption is tested.
The Bank of Canada paused it's digital dollar research initiative. Europe and the U.K. are moving faster. Canadian fintechs should design tokenized solutions that can connect to global settlement networks, not just domestic payment systems.
The Basel framework assigns a 1,250% risk weight to exposures on public blockchains compared to standard weights for permissioned systems. That number explains why institutions are cautious about public chains even as liquidity scale requires them.
Solana’s Lily Liu argued that “the 5.5bn people on the internet” can only be reached through open infrastructure, while regulators noted that immutability makes reversals and sanctions enforcement difficult. The likely outcome is a dual architecture with permissioned networks for issuance and compliance, and public networks for liquidity and settlement.
Canadian institutions face the same Basel capital rules as peers in other markets. Without clear guidance on the use of public versus permissioned networks, Canadian fintechs may find it harder to connect to global liquidity pools.
68% of EU businesses say they struggle to understand their obligations under the EU AI Act, holding back investment. Global wealth manager, Julius Baer’s COO estimated that customer focused AI tools could generate revenue within 6 to 12 months.
At the forum, agentic AI systems were demoed handling insurance claims with observability features allowing human review. The key issue is still accountability with policymakers worrying about loss of control as AI systems become more autonomous.
Canada has not finalized its AI regulation but offers a voluntary AI code of conduct, giving fintechs some near term flexibility. But any deployment that scales internationally will need to comply with EU and U.S. standards. The strategic opportunity is to pilot auditable AI now while preparing for global regulatory alignment.
S&P projects global private equity will grow from $15 trillion in 2025 to $18 trillion by 2027. Citi and SIX Digital Exchange announced tokenized access to late-stage pre-IPO equities on SDX, launching in Q3 2025.
Tokenization will improve collateral usability and ownership visibility, but not resolve fundamental illiquidity or opaque valuations.
Canada has a growing private capital market but no regulated digital exchange on the scale of SIX. Canadian fintechs could position themselves as infrastructure providers for tokenized funds and secondary liquidity, complementing global platforms instead of competing directly.
At the forum, speakers pointed out that some carbon credits were issued for projects expected to reduce emissions over 30 years, even though the land rights lasted only 10 years. That kind of mismatch reduces trust in the market.
Bringing carbon credits into mainstream finance could help spread risk and attract more investment. But for the market to work, credits must be backed by strong certification, insurance to cover project failures, and common standards that everyone follows.
Canada has compliance carbon pricing systems, but its voluntary carbon credit market is smaller and less standardized compared to Europe and Asia. Canadian fintechs could carve out a leadership role by building platforms that prioritize data integrity and risk coverage.
Canada must decide whether to keep pace with progressing markets in Europe and Asia or risk being shut out of global settlement networks. If Europe can move from pilots to architecture, Canadian fintechs must not stand still.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Standards | Aug 4, 2025
Image: Freepik
Canada chooses how it measures its economy but if it wants to be part of the global system, it needs to follow the updated rules. The System of National Accounts (SNA) is a global reporting framework developed and published jointly by the UN, IMF, OECD, World Bank, and European Commission to measure and compare economies across borders, including GDP, investment, and national wealth. Canada has followed it for decades, along with almost every other economy in the world, so we can expect change is coming.
Now, for the first time since 2008, the SNA has been updated. It gives countries the option to include intangible assets like AI systems, datasets, software, cloud infrastructure, and crypto in their official economic reporting. SNA 2025 is the new data reporting standard.
Statistics Canada currently uses SNA 2008 to compile GDP, capital formation, trade, and household income. Finance Canada and the Bank of Canada rely on that data to make major policy decisions. Because Canada aligns with the international system, it will be expected to transition to SNA 2025, and include a new measured view including intangibles, which NCFA has reported and advocated for the inclusion of intangibles for years. See this great report dating back 6 years ago now in 2019 called, " A New North Star: Canadian Competitiveness in an Intangibles Economy".
The new SNA 2025 includes formal categories for AI tools, machine learning models, digital platforms, tokenized assets, and data used in production. These can now be classified as fixed capital and included in investment statistics.
The framework also includes crypto assets such as Bitcoin in national wealth reporting. While countries are not required to adopt every element immediately, SNA 2025 sets the boundaries for what is allowed. If Canada continues using the SNA—and it will—these options are now on the table.
SNA 2025 does not show that digital or intangible assets are driving growth nor does not include statistics. What it does is give countries the structure to count what was previously invisible. Until now, if a Canadian fintech trained a large AI model, built infrastructure for a payments network, or developed a data engine for fraud detection, none of that was guaranteed to show up in national accounts. It was often treated as a cost, not an investment.
That matters because what gets counted drives policy.
When Statistics Canada does not report digital capital formation, Finance Canada cannot target it. When platform services are excluded from output figures, regulators and funders underestimate their value.
SNA 2025 also introduces new tools to reflect sustainability. It promotes the use of Net Domestic Product (NDP), which subtracts both depreciation and natural resource depletion from GDP. This is critical for a country like Canada, where growth often comes from extractive sectors. Using NDP can help the government better understand how much of that growth is truly lasting.
The new framework also supports clearer tracking of ESG finance, public sector innovation, and economic activity by multinationals that operate across borders. It aligns with global changes in how governments view risk, resilience, and value creation.
This is a global accounting and reporting change with deep consequences. SNA 2025, the updated global standard now recognizes intangibles, and so will the data that influences budgets, tax design, economic forecasts, and investment strategy. Canada is already committed to using the SNA, so the only question is how fully and how quickly we adopt the 2025 version.
NCFA urges Statistics Canada and federal decision makers to prioritize early implementation of the most relevant components of SNA 2025. These include digital capital assets, crypto asset recognition, and intangible production by fintech and AI firms.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Banking | June 25, 2025
The National Crowdfunding & Fintech Association of Canada (NCFA) is deeply saddened by the sudden passing of Andrew Moor, President and CEO of Equitable Bank, (EQB) over the weekend of June 21–22, 2025 per the Financial post. Moor was a bold and thoughtful leader who believed in making Canada’s financial system more innovative, digital, and inclusive.
As CEO since 2009, Moor led Equitable Bank’s transformation into a technology-forward institution known for its direct-to-consumer offerings and fintech partnerships. EQ Bank, the digital arm of Equitable, became one of Canada’s most trusted alternatives to traditional banking under his leadership. His forward-looking vision earned admiration across the financial sector, including from those of us at NCFA.
Moor supported open banking frameworks, digital infrastructure reform, and meaningful collaborations between regulated banks and emerging fintechs. He served on the board of the Canadian Bankers Association and consistently advocated for innovation that benefits Canadian consumers.
His leadership helped create new paths for collaboration between incumbents and innovators, something that NCFA has long supported.
Andrew Moor’s contributions advanced financial innovation in Canada. His sudden passing is a loss to all who care about the future of finance, technology, and inclusion. NCFA extends heartfelt condolences to his family, colleagues, and the entire team at EQB.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Canada-Africa | June 24, 2025
Image: Freepik AI
Canada’s development finance institution, FinDev Canada, has partnered with DEG (Germany), OeEB (Austria), and ILX (Netherlands) to provide a USD 100 million syndicated loan to Access Bank in Nigeria. This investment will directly support micro, small and medium-sized enterprises (MSMEs) and promote women’s economic empowerment.
MSMEs provide about 86% of jobs in Nigeria but still face major financing challenges. This loan facility will allow Access Bank to expand financial and non-financial services to underserved groups, including rural businesses, agribusinesses, and women-led enterprises. FinDev Canada is contributing $25 million USD towards this initiative to help increase access to credit, training, and market opportunities.
At least 30% of the loan proceeds are earmarked for women-owned businesses. Access Bank will offer reduced interest rates, business education, and networking support. This is FinDev Canada’s second investment in Access Bank (their first was a $50M loan facility in July 2024) and is fully aligned with the 2X Challenge, an international framework launched at the G7 Summit in 2018 promoting women’s participation in economic growth.
Lori Kerr, CEO of FinDev Canada:
“We can empower women entrepreneurs, develop underserved markets, and support job creation."
Launching the first ever global Canada-Africa strategy in early March, and now this follow-on loan facility is a clear signal that Canada is expanding it's financial presence in Africa by supporting fintech infrastructure, sustainable finance, and inclusive business frameworks and models. Access Bank currently operates in 24 countries serving over 60 million customers and has a large digital footprint and a track record of innovation.
Recent data from the 2025 Nigeria FinTech Survey Report by Column confirms this growth: over 23% of young Nigerians now use fintech apps for saving, with digital platforms like Opay, Palmpay, and Kuda seeing wide adoption. The 18 to 44 age bracket reports more than 56% saving consistently (most use multiple apps), indicating demand for integrated financial services. This tech-savvy generation is actively budgeting and planning for their financial futures despite economic instability, making Nigeria a high-potential market for digital finance investment.
This deal is aligned with one of the key impacts of the inaugural Canada-Africa Fintech Summit (CAFS) 2025 taking place in Toronto from August 5-8, 2025 to drive practical collaboration between Canadian and African partners across finance and innovation. Nigeria accounts for 28% of Africa’s fintech activity and remains one of the highest growth digital finance markets on the continent.
Mobilizing Canadian capital to support financial infrastructure and innovative start-ups can unlock commercial opportunity. NCFA and CAFS participants attending sessions like “Purpose, Profit, Planet” or “From Strategy to Scale” can use this as a live case study of what cross-border investment looks like when it combines capital, digital access, and market growth at scale. Tickets on sale now
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016