




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Dec 17, 2025 | NCFA Fintech Market Activity | Payments and Financial Inclusion

Image: Freepik/wirestock
On December 17 2025, as reported by the Guardian, the Marshall Islands rolled out a national universal basic income program that includes a stablecoin delivery option, alongside bank deposits and paper checks. The program targets quarterly payments of about US$200 per eligible resident citizen as part of a cost of living response.
The government is using a government backed digital wallet to move stablecoin payments across a geographically dispersed set of islands where traditional delivery can be slow and costly. The story is not crypto for novelty. It is a live test of public sector payments infrastructure under real constraints.
The numbers highlight where the adoption friction sits. The Guardian reports the Marshall Islands has a population of about 42,000. The Marshall Islands Social Security Administration reports about 60% of the first round of payments went to bank accounts, with the remainder paid by paper checks, while only about 12 people had signed up for the digital wallet option at the time of reporting.
This development also lands as Canada moves toward formal rules for stablecoin issuance and oversight, with federal policymakers outlining requirements around reserve backing, governance, and consumer protection in the first draft of the Stablecoin Act.
Talking Point
This program treats stablecoins as a distribution rail for routine public payments, not a speculative asset. If even a small country faces low opt in at first, what will it take for digital wallet based public payments to earn trust fast enough to matter at scale?
David Paul, Minister of Finance, Marshall Islands:
“We the government want to make sure no one is left behind,”
The financing structure also matters. The Guardian reports the program is financed through a trust fund established under a long-standing compact agreement with the United States, which provides financial support to the Marshall Islands in exchange for strategic and economic cooperation. The fund holds more than $1.3bn in assets, with the U.S. committing a further $500m through to 2027. That structure puts a hard spotlight on governance and oversight, because payment distribution is only one part of the risk picture.
For founders and investors, the takeaway is practical. Stablecoins do not win because they sound modern. They win when they reduce cost, reduce delay, and survive messy real world conditions like limited connectivity, uneven device access, and low initial confidence. The early channel mix in this rollout suggests that trust, onboarding, and usability will define outcomes more than the underlying token mechanics.
This is the kind of public sector experiment that can quietly set expectations for digital wallet rails, stablecoin backing standards, and compliance design. If the program proves reliable and expands wallet uptake without compromising oversight, it will give fintech builders a real benchmark for what production grade stablecoin payments need to look like.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Crypto Mining | Dec 1, 2025
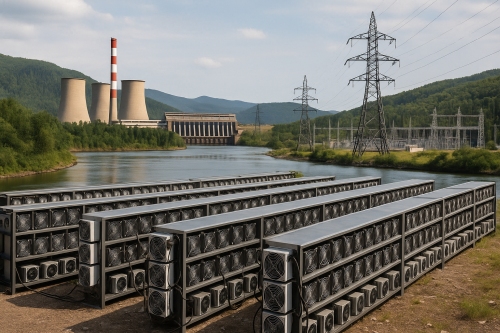
AI generated image
On November 28 2025, the Financial Post reported that the Newfoundland and Labrador Court of Appeal issued a ruling involving Blockchain Labrador Corporation (BLC) that confirmed NL Hydro can limit firm electricity service for new crypto mining operations.
BLC originally applied for 20 megawatts of guaranteed power service for a site in Wabush but NL Hydro declined to commit to that level because it needed to protect capacity for industrial, household and export priorities. Instead, NL Hydro will supply 7.75 megawatts to the company on an interim basis.
The ruling outcome confirms that NL Hydro has set boundaries on clean electricity when new digital workloads (ie. crypto mining, AI processing) add pressure to a constrained system.
Canada was once a notable player in global Bitcoin mining with national activity reaching close to 10% of global hashrate in 2021 but it's participation has since declined. Hashrate Index estimated that Canada held about 4% to 5% of global hashrate in their 2023 Canadian mining review, and then in a recent Q4 2025 global hashrate heatmap update benchmarked the country near 2.9%.
Canada's reduced footprint reflects a sector now concentrated in a few established companies. This smaller group of operators (see below and note, not exhaustive) also gives provinces more room to manage clean electricity across many competing needs.
Several provinces with hydro based systems have taken steps to manage electricity access for mining and other high demand digital activities.
British Columbia's clean electricity announcement enabled restrictions on new mining connections. The province later confirmed a permanent limit in the 2025 energy release, and the Court of Appeal supported provincial authority to set these boundaries in the Conifex ruling summary.
Manitoba adopted a pause on new mining activity when the utility raised concerns about the scale of new load requests. The province issued this direction in the 2022 guidance on electricity connections and extended the pause through 2026 in the 2024 directive on cryptocurrency operations.
New Brunswick took a more restrictive position. The provincial Electricity Act prevents a distribution utility from extending electricity to a new crypto mining business, which appears in the current consolidation of the Act and adopted through Bill 10.
Quebec continues to serve existing projects but limits new load and uses a dedicated rate class for this sector. A review commissioned by Hydro Québec found that mining produces fewer jobs for each megawatt consumed compared to data centres and industrial users, which encouraged ongoing limits.
Alberta remains an outlier, operating a deregulated, competitive market for electricity that allows mining companies and compute operators to negotiate directly for supply, supported by broader generation options.
Global research from the Cambridge Centre for Alternative Finance (CCAF) offers insight into energy use for digital mining. Cambridge estimates that Bitcoin mining draws about one hundred thirty eight terawatt hours of electricity per year, as described in CCAF's update on sustainable energy use and detailed further in a Cambridge digital mining report.
The research shows that more than half of global mining electricity comes from sustainable sources such as hydropower, wind and nuclear.
Low cost clean electricity attracts miners, data centres, industrial electrification and long term export contracts. Provinces build policies that protect available capacity for the users that advance their long term economic priorities.
Crypto mining can contribute value when it aligns with provincial priorities but utilities now apply stronger criteria when making decisions about supplying consistent clean energy.
The ruling involving Blockchain Labrador Corporation is an example of how a province evaluates new digital load against industrial development, household reliability and export duties. Informative for any Canadian fintech leaders following the developments in digital finance, compute infrastructure and national (global) ambitions for clean energy growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Strategic Planning | Nov 28, 2025

Image: Freepik/rawpixel.com
2026 is approaching and fintechs are entering the new year with clear signals on how capital is being deployed, how financial institutions are investing in automation and AI driven capabilities and which policies will shape financial infrastructure. Markets place a higher premium on efficiency, governance and resilience as financial institutions modernize data access and digital settlement. Retail investor participation also expanded as equity crowdfunding set new records in Canada, strengthening another channel of capital formation.
United States tariffs and interest rate expectations continue to influence capital costs and enterprise demand across North America. Singapore FinTech Festival 2025 recently wrapped and outlined what global leaders expect over the next decade. This article provides an overview of how these forces intersect and will impact 2026 conditions, helping fintechs define runway, product plans and investor alignment for the year ahead.
Global investors concentrated capital into fewer fintech companies through 2025. KPMG tracked $44.7B across 2,216 global fintech deals and reported stronger momentum in digital assets and AI powered platforms. The global fintech funding review for 2025 notes uneven performance across payments and infrastructure and continued strength in digital asset investment. AI influence extends across every funding stage and drives the clearest premium in investor behaviour.
Canadian fintechs raised about $1.62B across 60 deals. KPMG data reported by Lexpert shows a steep decline from record 2024 levels as investors became more selective and disciplined. KPMG’s H1 2025 report confirms the trend toward fewer large cheques and more careful deployment.
CVCA reported $2.9B across 254 Canadian VC deals with average cheque sizes near $11.4M. The VC deployment across Canada in H1 2025 reported that early stages represented more than half of deal count but only 10% of dollars. NCFA’s seed review shows AI companies raising about $24M across 12 early stage rounds and fintech attracting about $9M across pre-seed and seed combined in the seed investing trends in H1 2025.
Canadian founders also turned to retail investors through regulated equity crowdfunding channels. FrontFundr, a leading Canadian investment crowdfunding platform, enjoyed a banner year raising CAD $68.3M across 66 campaigns in 2024 with 4,226 individual investments, its strongest year on record. This growth in community capital raising speaks volumes that diversified sources of early stage capital can complement VC allocations during selective cycles. For fintechs, retail participation can help extend runway, validate demand and reduce dependence on a small number of institutional investors.
AI remains the strongest source of valuation strength across the fintech sector. NCFA’s analysis shows that AI fintechs attract a 242 valuation premium compared with non AI peers. This tells fintechs that investors reward automation, accuracy and data advantage even during slower deployment cycles. AI's impact will continue to drive product development strategy, unit economics and growth planning for 2026.
Open banking moves into implementation. Budget 2025 commits to a consumer driven banking framework that designates the Bank of Canada as the supervisor for accredited participants and sets rules for data access, liability, security and technical standards. The consumer driven banking framework in Budget 2025 changes data mobility from one off arrangements to regulated data rails. These data rails also support AI adoption because models require secure access to high quality data. Fintechs that prepare for accredited access and safe data workflows will gain an advantage as institutions deploy AI into risk, compliance and customer operations.
Fintechs should expect accreditation activity, testing and early stage integrations as technical standards move toward production readiness through 2026.
Retail Payment supervision is operational and supports future access to real time settlement. Under the Retail Payment Activities Act, the Bank of Canada supervises payment service providers to ensure operational resilience and safeguarding of client funds. This oversight creates the regulatory foundation required for participation in core payment systems. Payments Canada continues development of the Real Time Rail (expected Q2 2026), while the Bank’s commentary on cashing in on payments innovation explains how regulation strengthens competition and prepares the foundation for modernized settlement. It also sets the operational standards that AI systems must meet for real time fraud detection, liquidity monitoring and compliance automation. Fintechs should plan for higher compliance expectations in 2026 and a clearer pathway into national payment systems once real time settlement becomes available.
Stablecoin regulation advances. Canada released the first draft of its federal stablecoin legislation which sets out rules for high quality reserves, custody, redemption, disclosures and prudential oversight. NCFA’s summary of the first draft of the Stablecoin Act outlines a government framework that brings fiat backed stablecoins into a supervised environment. As tokenized settlement expands, AI will move deeper into treasury, reconciliation, fraud control and settlement routing. Fintechs that design early AI enabled settlement workflows will operate more efficiently under these rules. Fintechs involved in digital money, cross border payments or tokenized settlement should expect stronger regulatory clarity across 2026.
Climate and sustainability disclosure remains paused. CSA halted its mandatory climate disclosure rule in April 2025 and signalled the pause will continue. Although the rule is on hold, enterprise buyers and investors still assess climate and transition risk data during diligence. The CSA climate disclosure update notes that existing materiality rules and OSFI Guideline B-15 still apply through 2026. AI plays a growing role in climate analytics and transition planning, which means fintechs that use AI for risk scoring and scenario work will offer enterprise buyers more actionable intelligence during diligence. Fintechs should assume voluntary disclosure is expected even without a formal mandate.
Competitiveness pressure remains. Bank of Canada leadership warns that slow progress on open data, payment modernization and digital infrastructure affects productivity and innovation. Reuters coverage of the warning on over regulation and competitiveness highlights the need to accelerate foundational reforms. AI impacts that competitiveness gap because institutions deploy AI into fraud detection, lending, treasury and customer workflows. Fintechs that use AI with strong governance will operate more efficiently, support regulated environments and scale faster when data access and payment rails modernize.
For fintechs, these signals point to regulated data access, modern payments and digital assets becoming the highest value infrastructure themes for 2026..
Fintechs operating in the North American economy are being impacted by United States tariffs, rate decisions and political volatility. United States imposed tariffs cut Canada’s projected GDP growth to about 1.4% in 2025 and 1.6% in 2026, according to IMF linked projections. These estimates reflect weaker demand and reduced investment appetite across export dependent sectors. Fintechs should treat tariffs as a structural constraint for 2026, not a short term shock.
Markets now expect the Federal Reserve to cut rates in December. Polymarket shows an 87% chance of a 25 point rate cut, based on more than $183M in trading volume, which reflects strong real time sentiment. Economists still expect only small rate cuts through 2026, with United States growth around 2% and inflation near 2.6%. Fintechs may receive some cost of capital relief but investors will continue to expect efficient spending, strong revenue performance and clear evidence of product viability at today’s cost structure.
Canadian monetary authorities modeled the tariff impact and warned that trade friction could reduce investment by about 12% and lower output by almost 3% over two years. The Bank’s scenario work on tariffs and structural change supports planning for lower investment and slower recovery.
Fintechs should prepare for slower enterprise procurement cycles and more selective purchasing behavior.
Global growth projections dropped to about 2.8% in 2025 as tariffs spread and trade tensions widened. Export Development Canada’s global economic outlook for 2025 and 2026 forecasts Canadian growth around 0.8% in 2025 and 1.1% in 2026. Fintechs should expect slower demand, higher operating costs and more uncertainty across key trading regions.
An MIT study released in 2025 shows that about 12% of United States jobs could be automated using current AI tools today. As AI pressure intensifies it drives enterprise demand for automation, cost control and compliance. It also accelerates talent scarcity and raises expectations for governance and model transparency across financial services.
Global regulatory fragmentation expands. The EU AI Act, United Kingdom digital regulation, Singapore AI governance frameworks and China data sovereignty rules all diverge. If fintechs want to scale internationally in 2026, they must build modular compliance, auditability and data governance into core architecture.
SFF 2025 provided a clear view into the next cycle of fintech infrastructure and the capabilities that institutions expect. The SFF 2025 blueprint for the next decade of finance placed AI, tokenized settlement, quantum readiness and talent at the centre of global financial transformation for the coming years.
AI moved into production across onboarding, monitoring, underwriting and support. Financial institutions showed mature applications that reduce fraud, improve accuracy and accelerate customer workflows. Tokenized finance advanced as central banks and major institutions tested tokenized settlement assets, wholesale CBDCs and regulated stablecoins. These experiments are clear move from demos towards infrastructure design.
Quantum readiness entered strategic planning as banks prepared for post quantum cryptography and assessed their high value data inventory.
Talent emerged as one of the most constrained resources, with strong demand for cybersecurity, data and AI capabilities.
2026 will reward fintechs that integrate AI into their core stack, design products that support tokenized workflows, build quantum safe readiness and hire for digital infrastructure skills that support resilience and scale.
| Canada Policy Shifts That Drive 2026 Strategy | ||
|---|---|---|
| Open Banking Readiness | Canada moves to regulated data rails with accreditation and Bank of Canada oversight. | Build accredited data access readiness now. This creates a major advantage when banks and credit unions adopt regulated data sharing in 2026 and gives fintechs a lead when institutional partners demand safe integration. |
| Payment Supervision Alignment | Retail Payment Activities Act supervision is active and PSPs prepare for Real Time Rail participation. | Raise operational standards to meet supervision requirements. This clears the path for Real Time Rail access when available and strengthens partnership credibility with banks that expect higher resilience from PSPs. |
| Stablecoin Compliance Design | Canada released the first draft of the Stablecoin Act with rules for reserves, custody and redemption. | Design compliance into digital money products now. This avoids costly retrofits when rules finalize and positions fintechs for early participation in tokenized settlement experiments that banks support across 2026. |
| Transition And Climate Disclosure | CSA paused mandatory climate disclosure but investors still expect transition data in diligence. | Maintain credible voluntary disclosure. This reduces diligence friction with investors and large institutions that rank climate and transition data as core risk inputs even without a mandate. |
| Capital Conditions For Canadian Fintechs | ||
| Runway Discipline | Canadian funding normalizes with more selective deployment and fewer large rounds. | Plan 18 to 24 months of runway. This protects valuations and gives Canadian fintechs flexibility during slower deployment cycles and longer diligence timelines. |
| Revenue Quality First | Investors reward revenue durability as rates in the United States and Canada change slowly. | Increase margins, retention and customer lifetime value. This strengthens funding outcomes and signals that the business performs at today cost of capital. |
| Diversified Capital Routes | Equity crowdfunding reached record levels with rising retail participation in Canada. | Use investment crowdfunding to extend runway and validate market demand. This reduces reliance on a small number of venture investors and supports growth during selective funding cycles. |
| AI As The Primary Driver Of Competitiveness | ||
| AI As Core Infrastructure | SFF 2025 showed AI runs onboarding, risk, fraud and support in production. | Automate core work and improve accuracy. This reduces cost, raises product reliability and strengthens enterprise trust when selling into Canadian banks and credit unions. Remember, AI fintechs receive a valuation premium because automation and accuracy improve economics at every growth stage. |
| Model Governance Strength | Institutions expect clear model behaviour and explainability before integration. | Document lineage and monitoring with precision. This increases procurement success and accelerates enterprise adoption when institutions face rising AI governance requirements. |
| AI Driven Efficiency | Canadian enterprises invest in automation as budgets remain tight. | Replace manual workflows with AI to lower operating cost. This strengthens margins during slower growth and improves investor confidence. |
| Tokenized Settlement And Security Readiness | ||
| Tokenized Settlement Readiness | Banks and central banks test tokenized deposits and wholesale CBDCs. | Design workflows that support tokenized settlement. This prepares Canadian fintechs for early pilot participation when infrastructure tests expand in 2026. |
| Quantum Safe Architecture | Institutions begin planning for post quantum encryption. | Inventory sensitive data and adopt cryptographic agility. This protects long term assets and reduces future migration cost for Canadian fintechs selling into regulated environments. |
| Trade, Tariffs And Canadian Procurement Conditions | ||
| Adjusted Sales Cycles | Tariffs reduce Canadian investment and slow enterprise buying. | Extend sales cycle assumptions and build conservative forecasts. This improves cash planning and prevents burn surprises when procurement slows across regulated sectors. |
| Cost And Risk Value Propositions | Global growth slows and Canadian enterprises protect budgets. | Lead with measurable savings and risk reduction. This increases purchase probability in cost constrained environments and improves sales success during slow demand cycles. |
As the close of 2025 nears, fintechs operate in a world where capital rewards evidence first, and where AI driven performance gains receive premium valuation only when they improve accuracy, automation or margins. Fintech policy advancement in Canada moves forward on open banking, payments and stablecoins and these developments create new regulated rails to build on. Tariffs, interest rates and slower global growth increase the need for financial discipline and durable revenue streams. Retail investors also became more active in 2025 as equity crowdfunding set new records, giving Canadian fintechs another way to raise capital when venture funding is more selective. SFF 2025 highlighted the technologies that will shape financial infrastructure for the next decade.
Fintechs that align their strategy with the forces that matter, including AI, regulated data access, modern payments, tokenized settlement and stronger governance, will be better positioned to raise capital, win enterprise partnerships and scale through uncertainty.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Greeneashing Rules | Nov 24, 2025
On November 18 2025 the federal government introduced proposed changes to Canada’s environmental claim and greenwashing rules through Bill C-15, building on the November 4 2025 federal Budget. These proposals respond to concerns from businesses that the original 2024 framework increased uncertainty and cost. For financial technology firms that use climate related data or sustainability linked claims, these adjustments have important implications.
The original greenwashing provisions came into force through Bill C-59, which received royal assent on June 20 2024. See NCFA's fintech focused overview of the original green claim rules.
When the Competition Bureau released the June 2025 environmental claims guidance, firms received clearer detail on what regulators expected for forward looking climate statements, evidence standards and internal documentation. Even with that guidance, companies found the requirements strict and often unclear, particularly around which international standards qualified.
Bill C-15 proposes to adjust parts of the greenwashing rules that came into force in 2024. The government introduced these changes because many companies, including financial institutions, said the original rules were too unclear and made it difficult to speak openly about their environmental plans.
Bill C-15 responds to those concerns by removing the requirement that business level environmental claims must follow an internationally recognized methodology, which was one of the main sources of confusion. Businesses would still need evidence to support any environmental claim they make but they can focus on internal logic and documented methods.
Bill C-15 also proposes to change how greenwashing complaints are handled. Under the rules introduced in 2024, private parties such as advocacy groups, competitors or individuals can file applications directly with the Competition Tribunal for business environmental claims. This direct access was part of broader competition law reforms and became a significant concern for companies. Bill C-15 would remove that direct pathway and require private parties to bring their concerns to the Competition Bureau instead. The Bureau would then decide whether a case should proceed. The government introduced this change because many firms said the threat of direct Tribunal applications increased uncertainty and could discourage them from sharing legitimate climate related information.
The proposed changes aims to preserve protections against misleading claims while reducing the risk of unnecessary or strategic litigation.
| Consideration | Original 2024 Rules | Updated 2025 Rules (Bill C-15) | What This Means For Fintechs |
| How Environmental Claims Are Justified | Required adequate testing and alignment with an internationally recognized methodology | Requires substantiation but allows firms to use documented internal methods | More flexibility in climate data modelling, ESG scoring and analytics tools |
| Interpretation Burden | High. Firms struggled to interpret which global frameworks counted | Lower. Evidence judged on internal consistency | Clearer expectations reduce risk of misinterpretation |
| Documentation Expectations | Documentation needed to show alignment with international frameworks | Firms must document data sources and assumptions but no external alignment is required | Focus on internal logic and auditability |
| Future Oriented Climate Claims | Long term claims required alignment to global pathways | Claims still require evidence but internal pathways may be used | Forecasts need realistic milestones rather than matching global models |
| Risk of Challenge | Higher due to methodology disputes | Lower for methodology disputes but misleading advertising rules still apply | Risk shifts toward evidence quality |
| Enforcement Pathway | Private parties could bring cases to the Tribunal | Complaints routed through the Competition Bureau | Fewer activist driven cases but oversight continues |
| Practical Impact on Companies | Some firms paused climate commitments due to uncertainty | More predictable expectations support climate initiatives | More predictable environment for climate product development |
| Compliance Costs | Higher due to ambiguity around methodology | Moderate. Costs remain but ambiguity decreases | Less need for external validation. More need for strong internal controls |
| Innovation and Competitiveness | Rigid framework slowed innovation | Flexible system encourages innovation | Fintechs gain room to differentiate through credibility |
| Investor Signal | Uncertainty signalled regulatory volatility | Clear expectations reduce perceived friction | Fintechs become more attractive to investors |
Fintech firms need strong and reliable data infrastructure to support any environmental claims made in their products or services. While the updated rules remove the pressure to match a specific international framework, but they do not lower the expectation for clear evidence. Fintechs must be able to show how their data is collected, how their models work and why their outputs are reasonable.
Internal logic, consistency and transparent documentation matter more than ever because the assessment standard focuses on whether a claim can be substantiated using the firm’s own methods. This means the credibility of a fintech product depends heavily on the quality of its data foundations and (environmental) claims.
Any statement about future emissions, climate pathways or long term environmental outcomes requires realistic modelling and measurable steps.
This risk was highlighted when the Royal Bank of Canada pulled back its sustainable finance commitment after saying it could not confidently measure progress under the current rules.
Fintech tools that produce projections, risk curves or carbon estimates must demonstrate how the assumptions behind those outputs were chosen and how progress will be tracked. Future oriented claims remain high risk unless methods, milestones and supporting records are clear.
The updated framework may reduce the cost that came from interpreting international standards, but meaningful compliance work remains. Fintechs still need controlled data environments, version tracking, testing protocols and maintained audit trails.
Firms that use verification as a core part of product design can position themselves ahead of competitors because customers and investors will expect transparency in climate related data. Strong internal controls also help firms defend claims if they are questioned by regulators or partners.
Removing direct access to the Competition Tribunal lowers the chance of activist driven cases, but environmental claims will continue to be reviewed under misleading advertising rules.
The Competition Bureau remains the main decision maker and it can act where evidence is weak or claims are overstated. For fintechs this means that scrutiny continues but will be more predictable and clearer process. Firms should expect oversight to focus on accuracy and evidence rather than whether a specific global methodology was used.
Fintech teams should review the environmental claims used in products, marketing or investor materials and ensure the evidence behind those claims is complete and easy to explain.
Internal methodologies should be clear so product, compliance and technical teams can show how calculations and scores are produced. Future oriented statements need documented assumptions, milestones and data sources.
Firms should also monitor the progress of Bill C-15 and upcoming Competition Bureau guidance so they can adjust their documentation and product practices as expectations evolve.
Environmental credibility impacts how investors and partners evaluate opportunities in sustainable finance and climate technology ventures. The updated rules aim to keep protections against misleading claims while reducing uncertainty that can slow down innovation. Fintechs that build strong and transparent verification systems can strengthen their competitive position, support customer confidence and contribute to a more trusted and transparent sustainable finance ecosystem in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Social Finance | Nov 3, 2025
Image: Freepik
The Centre for Social Innovation (CSI) confirmed in its August 2025 update that its 2025 Community Bond campaign, targeting $6 million in total investment, was nearly full following strong participation since launch in May. The funds are being raised to transition CSI to 100% community financing, retire remaining bank debt, and strengthen ownership of its 192 Spadina Avenue property, ensuring long-term stability for its social innovation mission.
CSI’s 2025 Community Bond offering includes three verified bond options as listed on its official campaign page: Series L (4.25% annual simple interest, 3-year term), Series M (5% annual compound interest, 5-year term), and Series N (6% annual compound interest, 5-year term).
Minimum investments range from $1,000 to $25,000. According to CSI’s 2025 Offering Statement, the bonds are secured by registered charges on CSI’s Toronto properties, and the organization states it has “never missed an interest payment” since the first issuance.
Community bonds occupy a growing space in Canada’s impact-finance ecosystem. They allow individuals and institutions to earn predictable returns while funding community-owned infrastructure and social enterprises.
For Canada’s fintech and alternative finance community, CSI’s community bond initiative dates back years and provides a verified model of how mission-aligned investors can contribute to measurable social and economic outcomes. It also complements national efforts to broaden retail investor participation through investment crowdfunding and exempt-market modernization.
It demonstrates that capital formation and public benefit can work together when accountability, collateral, and investor confidence are clearly defined. As policymakers explore pathways to inclusive capital access, the community-bond structure is a practical example of responsible innovation in finance. Those interested in learning more about the model and its broader impact can visit socialinnovation.ca.
This article is for informational purposes only and does not constitute an offer to sell or a solicitation to buy any security. Readers should consult the official issuer documents for full details.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | Oct 22, 2025
Image: Freepik
On October 20, 2025, the Government of Canada announced a renewed investment of $189 million in the Black Entrepreneurship Program (BEP), continuing its commitment to helping Black entrepreneurs start, scale, and strengthen businesses nationwide. The announcement was made in Toronto by the Honourable Rechie Valdez, Minister of Women and Gender Equality and Secretary of State (Small Business and Tourism), as part of Small Business Week.
The BEP was first launched in 2021 to expand access to capital, mentorship, training, and data for Black business owners. Since then, it has supported more than 24,000 Black entrepreneurs across Canada, while the Loan Fund has delivered over $70 million in approved financing through 801 loans.
With this new five-year commitment running from 2025 to 2030, the program will continue supporting inclusive economic growth through three core pillars: the Loan Fund, the Knowledge Hub, and the Ecosystem Fund.
Under the renewed investment:
Minister Valdez highlighted that empowering Black entrepreneurs contributes to job creation, innovation, and community development across the country.
“The strength of Canada’s economy comes from the talent and tenacity of our people. When Black entrepreneurs can access capital, mentorship and reliable data, they turn ideas into jobs and community prosperity,”
The renewed program will also continue supporting the federal government’s Black Justice Strategy by addressing systemic barriers and advancing anti-racism efforts through economic participation. By deepening collaboration between government, lenders, and ecosystem partners, the initiative aims to strengthen Canada’s inclusive business landscape and ensure equitable access to opportunity for Black entrepreneurs nationwide.
The renewal of the Black Entrepreneurship Program reflects Canada’s commitment to inclusive growth and aligns with NCFA’s work to expand access to capital and opportunity. Through the Canada Africa Fintech Summit, NCFA and its partners promote collaboration between Canadian and African innovators, helping entrepreneurs build sustainable businesses and strengthen economic ties. The program’s focus on capital, research, and networks supports the same goals driving NCFA’s efforts to advance a fair and competitive financial innovation ecosystem.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Social Enterprise | Oct 7, 2025
Image: Freepik/creativeart
As reported by Devex on October 3, 2025, RemitHope is redefining how diaspora remittances fund local impact across Africa. A fintech-powered social enterprise and new digital giving platform founded by philanthropist Tsitsi Masiyiwa is transforming how remittances and local donations flow into African community development.
The platform’s launch follows the July fire at Mount Selinda Orphanage in Zimbabwe, which became RemitHope’s first campaign. In less than three weeks, over 1,000 donors from ten countries contributed $40,000, instantly doubled through matching funds to more than $81,000 to rebuild the orphanage, proving the platform’s model. Donations currently sit at over $81,500.
According to verified data from the World Bank, global remittance flows reached $685 billion in 2024, surpassing both foreign direct investment and overseas development assistance. The rise of platforms like RemitHope demonstrates how fintech can turn personal remittance flows into community scale development capital.
Founder Masiyiwa, who is also the co-founded Higherlife Foundation and Delta Philanthropies, described the goal as channeling diaspora generosity toward self sustaining, African led impact. As she said at launch:
“Now, as the aid from the Global North dwindles, we are stepping up. My audacious goal? $50 million in the next five years.”
RemitHope blends crowdfunding, remittance technology, and philanthropic matching. Each donation from diaspora or local givers is instantly doubled by partner foundations, currently Delta Philanthropies based in Zimbabwe (UK registered) and Higherlife Foundation.
This creates a direct incentive for micro giving, where even a $5 contribution becomes $10 expanding reach and impact. The platform enables donors to give through mobile payment channels such as EcoCash and is exploring integration with everyday transactions like ticket purchases or mobile top ups.
Every partner organization is vetted for transparency, governance, and measurable outcomes. Campaigns typically target around $10,000 per project, ensuring funds go directly to specific community priorities. It reframes remittances as an alternative finance mechanism bridging charity and investment.
The first wave of users includes grassroots community groups from thirteen countries, many in rural areas that typically fall outside formal aid pipelines. These organizations gain visibility through the platform, bypassing grant bureaucracy and connecting directly to diaspora and domestic donors.
The funding mix in the Mount Selinda case is revealing: about 900 local donors used EcoCash for small contributions, while around 100 diaspora donors contributed larger amounts, often over $50. This blend of micro local and macro diaspora support shows how new models of digital trust and peer giving are forming across borders.
Masiyiwa’s five year, $50 million target is backed by a vision that goes beyond charity. RemitHope is building infrastructure for African led giving that turns remittance networks into sustainable impact capital. The platform’s long term plan includes integrating data driven impact tracking, digital identity verification, and traceable giving records to strengthen accountability and transparency.
The founders see it as a catalyst for regional collaboration, a model of Africans funding Africans that redefines philanthropy as investment in capacity and innovation.
As operational head Musa Muleya said, “The question was what can we do as Africans to solve African problems.” That ethos aligns with NCFA’s advocacy for inclusive, technology driven financial ecosystems that bridge public trust with private initiatives.
For Canadian context, diaspora focused fintechs such as LemFi, which raised $53 million in January 2025, are expanding remittance and mobile finance infrastructure for African immigrants.
Platforms such as CAF Canada and Myriad Canada provide cross border philanthropic frameworks that could integrate similar matching or community led approaches. These examples show how Canadian fintech and charitable infrastructure could help scale Africa led innovation responsibly, aligning with Canada’s Africa Strategy for inclusive growth.
Many similar conversations could be overhead at the inaugural 2025 Canadian-Africa Fintech Summit where NCFA partnered to help support the development of a Canada-Africa fintech bridge that fosters cross-border collaboration, innovation, economic development and investment.
RemitHope remittances are a collaborative funding mechanism for social innovation. It's part of a new movement in Africa towards self-reliance and inclusive, locally-led social enterprise that strengthens trust and transparency between donors and recipients.
For Canada’s fintech and social finance ecosystem, it's a powerful model of cross border collaboration that merges technology, accountability, and community empowerment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016