





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 29, 2025

The Ripple vs. SEC lawsuit has been one of the most closely watched legal battles in the cryptocurrency industry. After nearly five years of uncertainty, the U.S. Securities and Exchange Commission (SEC) reached a settlement with Ripple Labs in August 2025. Ripple agreed to pay a $125 million fine, ending a prolonged dispute over whether XRP should be classified as a security. For investors, institutions, and regulators alike, this decision marked a turning point for the digital asset.
In the wake of the settlement, XRP surged above $3.30 before stabilizing slightly lower, with trading volumes and institutional interest spiking sharply. With regulatory clarity now in place, the market is assessing whether XRP is poised for sustained growth or if short-term speculation is fueling most of the momentum.
This article explores the post-settlement price action, institutional adoption trends, technical analysis, and the risks investors should keep in mind when considering XRP’s market outlook.
The legal battle began in December 2020 when the SEC accused Ripple Labs of conducting an unregistered securities offering through sales of XRP. Ripple countered that XRP was a digital asset designed for payments, not an investment contract. For years, this uncertainty suppressed investor confidence and limited XRP’s integration into mainstream financial institutions.
On August 8, 2025, the SEC and Ripple reached a final settlement. Ripple agreed to pay a $125 million fine, without admitting or denying wrongdoing. Crucially, the deal provided regulatory clarity: XRP is not classified as a security when traded on secondary markets, removing a major barrier for U.S. exchanges, institutional investors, and payment providers.
This resolution immediately influenced market sentiment, driving a strong rally in XRP and opening the door for broader adoption.
Following the announcement, XRP surged above $3.25, peaking near $3.32 before stabilizing in the $3.14–$3.22 range. Trading volumes spiked more than 200% in 24 hours, surpassing $12 billion. This surge reflects renewed confidence from both retail and institutional investors.
For investors tracking digital assets, monitoring real-time benchmarks such as XRP price USD provides valuable insight into ongoing volatility and market sentiment. The legal clarity appears to have removed a key ceiling that previously capped XRP’s growth potential.
Additionally, derivatives markets saw a 15% increase in open interest, reaching nearly $6 billion. This suggests traders are positioning for further moves, with many anticipating bullish continuation.
One of the most significant outcomes of the settlement is the restoration of institutional confidence in XRP. For years, major U.S. exchanges delisted the token due to regulatory risk. Now, with clarity from the SEC, institutions are showing renewed interest.
Trading firms and liquidity providers have increased exposure, and some payment service providers are considering XRP as a cross-border settlement tool once again. This institutional momentum mirrors broader trends in the crypto market, where regulatory clarity often leads to higher participation. For context, comparing digital benchmarks such as Bitcoin price USD against XRP can provide perspective on how investors weigh opportunities between established leaders and high-upside altcoins.
Financial institutions are particularly interested in XRP’s utility as a bridge currency for remittances and international payments. With legal uncertainty resolved, the token could see renewed integration into enterprise-level payment solutions.
From a technical standpoint, XRP faces a critical resistance zone near $3.35. Analysts argue that if the token can establish this level as new support, the next upside target could reach between $4 and $5. Several market strategists point to bullish fractal patterns reminiscent of XRP’s rally during the 2017 bull market, which saw exponential gains.
Some analysts even project medium-term targets of $8, with long-term possibilities of $10 or more, provided XRP maintains strong momentum and adoption growth. These forecasts, however, remain speculative and depend on broader crypto market conditions, including Bitcoin’s trajectory and macroeconomic factors such as interest rates and regulatory policies.
Key technical indicators to watch include:
Several factors are contributing to XRP’s momentum:
With the SEC settlement finalized, U.S. exchanges can now list XRP without fear of litigation. This regulatory green light has major implications for liquidity and adoption.
Data shows a sharp increase in institutional trading volume, with open interest in derivatives markets climbing steadily. This suggests long-term players are taking positions rather than short-term speculation alone.
XRP’s rally is occurring in a context where Bitcoin and Ethereum continue to dominate the sector. If Bitcoin remains strong, it often sets the tone for altcoin performance, providing XRP with a favorable environment.
Unlike many altcoins driven purely by speculation, XRP has practical use cases in cross-border payments and settlement. This differentiates it from tokens that rely solely on hype cycles.
While optimism is high, it is important to recognize potential risks:
Investors should view XRP’s rally with cautious optimism and remember that cryptocurrency markets carry significant risk. This analysis is for educational purposes only and does not constitute investment advice.
The conclusion of the Ripple vs. SEC lawsuit marks a watershed moment for XRP. The settlement removes years of legal uncertainty, reigniting institutional interest and sparking renewed confidence in the token’s role as a payment-focused digital asset.
In the near term, XRP’s ability to hold support above $3.35 will be critical to sustaining momentum. If successful, analysts see the potential for XRP to target $4–$5, with more ambitious projections aiming for $8–$10 in the coming months or years.
For long-term adoption, regulatory clarity could pave the way for XRP’s deeper integration into the global payments industry, aligning with Ripple’s original vision. However, investors should remain mindful of the risks associated with crypto markets, particularly volatility and regulatory changes across different jurisdictions.
In summary, while the lawsuit’s end represents a significant milestone, XRP’s next chapter will be defined by market resilience, institutional adoption, and the broader trajectory of the digital asset ecosystem.
Always conduct independent research and consult financial professionals before making investment decisions. Cryptocurrency markets are volatile and carry substantial risks.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Crypto | Aug 28, 2025
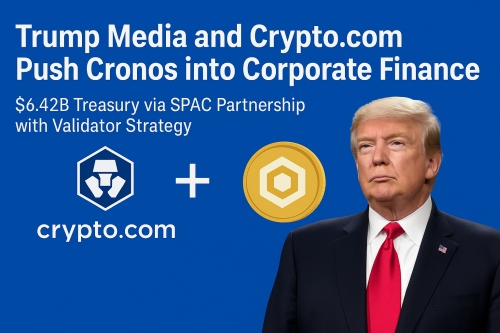
On Aug 26, 2025, the Trump Media & Technology Group, Crypto.com and Yorkville Acquisition Corp (SPAC). announced the launch of Trump Media Group CRO Strategy Inc., a new treasury firm designed to acquire, hold and actively manage large reserves of the Cronos token (CRO).
Devin Nunes, CEO of Trump Media, said:
“We continue to be bullish on cryptocurrency, and we are excited to be partnering with a leading global cryptocurrency platform and namesake of its industry in Crypto.com and one of the most sophisticated investor groups in Yorkville for this strategic initiative.”
The company will go public on Nasdaq under the ticker MCGA. The venture combines 6.3 billion CRO tokens valued at $1 billion (approx 19% of supply)+ $200 million in cash + $220 million in warrants + $5 billion equity line of credit from a Yorkville affiliate YA II PN. In total,$6.42 billion in committed resources.
Trump Media will also buy $105 million worth of cronos for its balance sheet, and Crypto.com has agreed to invest $50 million into Trump Media stock.
All told, the deal will be the first and largest publicly traded CRO treasury company and what is being described as the largest deal ever when compared to the total size of the token’s market. The business combination is being reinforced by a mandatory 1 year lock-up and 3 year release schedule on founding shares. See Form 8-K filing.
Kris Marszalek, CEO of Crypto.com, said:
“The sheer size and structure of this project will encompass more than the entire current market capitalization of CRO … this, combined with share lock-ups by each party and the treasury’s validator strategy, make it a unique and compelling offering compared to all other digital asset treasuries.”
Markets reacted immediately. Cronos spiked nearly 30% in the hours after the news (currently trading at $0.3205 on CoinGecko), while Trump Media’s stock rose 5% to $18.11. Yorkville shares fell 2.4% on the day of the announcement. This is another massive deal for crypto and boost for corporate crypto treasury strategies.
One of the most distinctive aspects of the venture is its validator strategy. Trump Media Group CRO Strategy will establish and operate a validator node on the Cronos network, delegating CRO under management to that node. This allows the company to directly participate in the security and governance of the blockchain while generating native staking rewards that will be reinvested to grow CRO holdings and offset operational expenses.
AP reported that “the Trump family is expanding its crypto empire,” adding to a series of projects that include a proposed bitcoin ETF and a $2 billion bitcoin reserve. With the White House progressing friendly crypto policies, this venture shows how closely aligned political influence and corporate strategy can be, which raises conflict of interest and transparency questions, as Trump’s family business benefits directly from a favourable regulatory climate.
The United States is moving fast with token-backed treasury vehicles and SPAC-financed listings, while Canada’s regulatory approach has been slower and more cautious. In Canada, a deal structured as a SPAC merger with a crypto corporate treasury at its core would likely not pass regulatory muster today.
That's a competitive gap. If American firms can put tokens on their balance sheets, raise capital through SPAC mergers, and connect those tokens to consumer platforms, they can innovate at a scale in a way that Canadian firms cannot match.
The question for Canada is whether to stay on the sidelines or to create the right framework for safe experimentation. That could mean regulatory sandboxes for token-based treasuries, pilot programs to test new structures, or clearer rules that give firms confidence to innovate. Without these kinds of steps, Canada risks falling further behind (skilled jobs, innovation and global capital flows) as U.S. firms set the pace in crypto finance.
The Trump Media and Crypto.com deal is an experiment to see if a token like cronos can play the same role in corporate reserves that bitcoin has for MicroStrategy. Investors jumped in quickly, but the approach still comes with the risks of big price swings and political baggage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 27, 2025
Image: Unsplash/PiggyBank
Putting a child through higher education is an expensive affair. The average annual tuition fee is over $7,000, with some fields like dentistry exceeding $24,000 per year. That’s not including books and living expenses like transportation, accommodation, food, and healthcare, so saving money early is key.
A registered education savings plan (RESP) gives you two powerful benefits. Firstly, you can access government grants. Secondly, you can take advantage of tax-sheltered growth. Here are practical strategies to help you use your RESP wisely and get the most out of every dollar you put in.
Through the Canada Education Savings Grant (CESG), the government can match your contributions by up to 20%. As an example, let’s say you put $2,500 into your RESP one year. The government will add $500. That’s the maximum amount per year per child. If you contribute less, your deposit can still be matched up to 20%. For example, if you contributed $1,000 in a given year, the government could add $200.
The earlier you start saving, the more earning potential your money has, thanks to compound interest. Even small monthly contributions can add up over time. For instance, if you can afford just $50 a month starting when your child is born, you’ll contribute $10,800 by their 18th birthday. With grants and investment growth, the RESP could reach over $20,000 by that time, based on a 2.4% annual compound return.
RESPs have lifetime limits on how much you can contribute ($50,000 per child). Go over that, and the extra amount is taxed at 1%. There’s also a cap on how much grant money you can receive: $500 per year and $7,200 total per child.
Let’s say you contribute a lump sum of $50,000; you’d only receive a CESG contribution of $500 for the first year, but the money would have the maximum time to grow. On the other hand, if you spread out the same contribution over 15 years, you could collect the full $7,200 per child.
Which approach works better depends on your investment returns. With higher growth rates, the lump sum is often more beneficial. With lower returns, the grant can be more valuable.
If you missed contributions in the past, you can collect two years’ worth of CESG in a single year by contributing $5,000. However, you can only catch up one year at a time. If you missed five years, it will take another five years of doubling contributions to collect all the grant money.
The good news is the CESG isn’t the only support available. Depending on your income or where you live, you may qualify for the Additional Canada Education Savings Grant (ACESG), Canada Learning Bond (CLB), or provincial programs. The CLB is designed for lower-income families. You don’t even need to contribute; in the first year, the government adds $500 to the RESP automatically. For the subsequent years that the child is eligible, it adds $100, up to a total of $2,000. In British Columbia and Quebec, programs include the B.C. Training and Education Savings Grant and Québec Education Savings Incentive.
Life is busy, especially with kids. It’s easy to forget about RESP contribution deadlines. The CESG calculations are based on a calendar year, so if you forget to deposit before December 31, you’ll miss that year’s grant. The easiest solution is to set up automatic contributions. Most RESP providers let you set up pre-authorized payments from your bank account.
An RESP is one of the smartest ways you can save for your child’s education, but like any tool, it works best when you use it right. Contribute enough to get the full CESG, start early, watch your limits, catch up if you fall behind, claim all the grants you’re eligible for, and automate where possible.
Applying these strategies will help you get the best value for your money and give your child the strongest start when the time comes for college or university.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto IPO | Aug 14, 2025
Image: Freepik AI
Bullish is a Cayman Islands based crypto exchange focused on institutional grade digital asset trading and market intelligence, and also the media owner that also operates CoinDesk. Bullish first tried to go public through a SPAC deal in 2022 during a difficult period for crypto markets but that plan was abandoned. The company waited for market conditions to improve before trying again.
By Q2 2025 sentiment toward both crypto and IPOs flipped positive. Supportive policy developments on stablecoin regulation from Washington helped stoke interest from big investors. At the same time Bitcoin was trading near $120,000 and other high profile fintech IPOs like Circle and Figma had delivered strong first day gains, fuelling expectations for Bullish.
Bullish priced its IPO at $37 per share which was above its revised range of $32 to $33 and well above its original $28 to $31 range. The company sold 30 million shares and raised about $1.11 billion at a valuation of $5.41 billion at the offer price. JPMorgan, Jefferies and Citigroup were among the underwriters. BlackRock and ARK Invest each indicated plans to invest up to $200 million.
The shares began trading on the NYSE under the ticker BLSH on August 13 2025. They opened at $90 and quickly climbed to $118, which led to multiple trading halts for volatility. By the close the stock was at $68, an increase of about 84% from the offer price, valuing the company near $10 billion.
Institutional interest in Bullish is significant. The company’s mix of a trading platform and media data outlet set it apart from competitors like Coinbase and Binance.
Also the timing of the IPO, expectations for an interest rate cut in September, a rising crypto market and signs of clearer regulation in the United States, all contributed to this success.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 14, 2025
Image: Freepik/pikisuperstar
In the competitive world of Canadian online casinos, attracting new players is only half the battle—keeping them engaged and satisfied is equally important. Loyalty and VIP programs are the industry’s answer to long-term player retention, offering rewards, perks, and exclusive benefits to those who play regularly.
These programs are more than just marketing tools; they’re a way for casinos to build relationships with players, enhance the gaming experience, and reward consistent participation.
A loyalty program in an online casino is a tiered rewards system where players earn points or credits based on their wagers and activity. Over time, these points can be exchanged for bonuses, free spins, cashback, or other rewards.
A VIP program is typically invite-only or reserved for high-stakes players. VIP status brings more personalized perks, often including account managers, faster withdrawals, and unique event invitations.
Canada’s online casino market is provincially regulated in some areas (like Ontario via iGaming Ontario) while offshore casinos also serve Canadian players. Both regulated and international platforms use loyalty and VIP programs to stand out in the competitive space.
While rewards are attractive, it’s essential for players to gamble responsibly. Canada offers several tools and services, including:
Loyalty and VIP programs in Canadian online casinos offer players more value for their time and money, creating a mutually beneficial relationship between player and operator. Whether it’s collecting points for free spins or enjoying the perks of an exclusive VIP tier, these programs add an extra layer of engagement to the gaming experience.
However, players should always weigh the rewards against their gambling budget, ensuring the pursuit of perks never overshadows responsible play.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulatory Consultation | Aug 13, 2025
Image: Freepik/DC Studio
On August 12, 2025, the Canadian Investment Regulatory Organization (CIRO) announced proposed changes for consultation to update rules for Order Execution Only (OEO) dealers, which are digital-first platforms, such as Questrade, Wealthsimple Trade, MogoTrade, or RBC Direct Investing. The proposal would allow a wider range of tools for use, as long as safeguards like clear disclaimers and conflict avoidance measures are in place.
Currently, OEO dealers are allowed to let clients place trades but they are not allowed to provide investment advice. Current restrictions limit these dealers from offering features such as sample portfolios, self assessment tools, or certain educational supports, to avoid triggering “recommendations.”
Today, non CIRO fintechs and investor education organizations can offer self assessment tools, model portfolios, and interactive investor education features because they are not registered dealers. CIRO regulated dealers operate under strict rules, which can hold back innovation. The proposed changes could help close this gap by allowing regulated CIRO platforms to provide more engaging and competitive resources to DIY investors.
One motivation for the proposed rule change is the sharp increase of retail investors turning to social media, forums, and finfluencers for guidance. CIRO has warned that unverified online information can expose investors to serious risks. Expanding what regulated platforms can offer would give DIY investors more access to credible, compliant sources of information and reduce reliance on potentially misleading content.
CIRO is accepting comments on the proposal until November 10, 2025 and has made updating OEO guidance a priority for 2026. If adopted, these changes could reshape investor education in Canada by giving regulated platforms greater flexibility while maintaining essential protections.
The outcome of this proposal will determine how much flexibility regulated CIRO ealers have to innovate in investor and financial education. For fintech innovators and market participants, it's a sign that regulators are open to modernizing rules to better meet the needs of today’s self directed investors.
NCFA will continue to follow this development and share updates on how the final framework could influence the future of investor engagement.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Release | July 24, 2025
Image: Freepik
On July 24, 2025, Flashy Finance announced a sponsorship with AuCan Gold to launch a new Play for Gold game model that bridges real world assets and Web3 entertainment.
The first title, Dig It, will let users earn digital Nuggets tokens that can be redeemed for tokenised gold prizes backed by physical reserves. Up to $10 million in gold will be distributed across Flashy's game ecosystem, creating one of the largest real world asset reward pools in crypto gaming to date.
The collaboration builds on AuCan Gold’s July 22 launch of a US$2.5 billion tokenised gold platform for accredited investors. This expansion into the gaming market brings that same infrastructure to a new demographic of Web3 users while offering a way to win verified gold exposure through gameplay. Tokens earned in Dig It will be linked to physical gold via redemption programs supported by AuCan’s reserve-backed vault infrastructure.
Flashy’s upcoming suite of gold games will reward attention, creativity, and community engagement with real world value. The launch title Dig It is designed as a viral, tap-to-dig mobile experience.
A follow-up AR title called Go For Gold is also in development. In both games, players collect Nuggets tokens, which can be redeemed through licensed programs for tokenised gold ownership. Redemption is governed by smart contracts tied to audited reserves, ensuring that value earned in game corresponds to real gold in storage.
According to Flashy CEO Michael Gord, this model turns gold into a reward for participation. “Through Flashy and its sponsorship program with AuCan, we’re democratizing access to gold by turning it into a reward for creativity, skill, and participation.” The aim is to blend gaming, financial literacy, and decentralised infrastructure into a unified experience that makes asset ownership feel accessible and engaging.
The partnership with AuCan gives it access to compliant, asset-backed instruments that can support meaningful rewards and global scalability.
By integrating tokenised gold into gaming, firms like AuCan are unlocking new ways to distribute real assets at scale. It also allows Canadian companies to tap into global liquidity, not just through institutional channels but through viral, consumer driven platforms.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
