





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Equity Crowdfunding | Oct 31, 2025
Image: Gander Social via FrontFundr equity crowdfunding campaign
On October 24, 2025, Gander Social, a Canadian alternative to foreign-owned social platforms, announced that they surpassed $1 million raised from more than 1,595 investors in its initial private community phase, exceeding their target in just over a week. Then on October 30, the company announced in a release that they are opening the campaign up to the public on FrontFundr, inviting Canadians across the country to join its growing base of community owners.
The campaign has now raised almost $1.2 million and is targeting $1.5 million and continues to grow rapidly through organic participation and word-of-mouth sharing, demonstrating the strong appetite for Canadian-built platforms and the expanding role of equity crowdfunding in mobilizing retail investors, especially at a time when early stage venture funding channels are under pressure.
Led by Ottawa-based longtime creative director turned founder CEO Ben Waldman, Gander Social is built by a small team of Canadian engineers and creators who want to give people a trustworthy alternative to ad-driven social media. The company is structured as a Public Benefit Corporation, showing its commitment to long-term public accountability rather than short-term profit. Waldman described the movement behind Gander as “more like a call to arms,” a push to rebuild online spaces around community ownership and digital sovereignty.
BenWaltman, CEO Gander Social:
By setting a minimum investment of $255, Gander is making participation accessible to everyday Canadians. The campaign reinforces the growing “keep it in Canada” mindset that prioritizes domestic ownership, ethical innovation, and sustainable platform design. Investors are not just looking for returns but they want to help define the kind of digital economy they want to see in Canada.
As Canada feels the geopolitical pressures, across the country investors are embracing equity crowdfunding to participate directly in the innovation economy and keep growth capital in Canada. It’s a model that strengthens community engagement while advancing national competitiveness and financial inclusion.
For policymakers and fintech advocates, Gander’s raise demonstrates how equity crowdfunding can mobilize citizens to fund nationally significant ventures. It shows how financial innovation and digital sovereignty can align to strengthen Canada’s independence, resilience, and competitiveness in a global tech landscape increasingly defined by foreign control. Learn more about the Gander Social campaign here.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Fintech Event | Oct 23, 2025

Image; Wealthsimple For Nerds 2025, Michael Katchen
On October 22, 2025, Wealthsimple held its For Nerds Only showcase in Toronto, launching a bevy of new products and milestones that highlight the major changes happening in Canada's retail investing market.
Over 220,000 Canadians registered for the livestream which is double the audience size at WS's event held last June. The company splashed some big news in that it officially surpassed $100 billion in assets under administration, reaching the milestone 3 years ahead of its original 2028 target!
Alongside the product updates, Wealthsimple shared results from a June 2025 survey of clients aged 25 to 45 with more than $50,000 in assets that confirm there's demand for digital control when paired with trusted guidance:
Wealthsimple introduced what it calls Canada’s first zero commission options platform with no per-contract fees. By eliminating traditional contract costs that major bank brokerages still charge, the firm aims to make options more accessible to retail investors with zero fee options rolling out to all clients in phases in 2026. Users should monitor fee transparency and execution quality as adoption scales.
WS’s zero fee options will disrupt the pricing structures of Canada’s largest bank brokerages, such as RBC Direct Investing, TD Direct Investing, BMO InvestorLine, and Scotia iTRADE who all still charge between $1.25 and $2.50 per contract, a model that has long supported their retail trading revenue. By removing per contract costs entirely, WS sets a new benchmark that will pressure banks to justify higher fees or cut them to stay competitive.
As more and more investors move to lower cost platforms, traditional banks risk losing up/cross selling opportunities in savings, credit, and advisory products. For younger retail investors and clients who value cost transparency and mobile-first design, zero fee options trading is the way to go.
Wealthsimple also launched real gold trading (See: support guide) directly in client accounts, making it available around the clock and backed by the Royal Canadian Mint. Investors can buy fractional amounts starting at one dollar and will be able to redeem for physical one ounce and tenth ounce coins beginning in November 2025.
The new feature combines online convenience with real ownership of gold, appealing to people who want something tangible instead of investing in gold ETFs. If trading costs stay low, it could change how Canadians buy and hold gold in their accounts.
Wealthsimple introduced a Mutual Fund Exchange to help investors transition from high-fee mutual funds to lower-cost managed portfolios, covering transfer fees and offering personalized guidance.
The firm also previewed its flagship Summit portfolio, a new managed offering that blends public equities with private equity, private credit, infrastructure, and gold exposure.
According to the newsroom release:
Investors switching from high-fee mutual funds to the Summit portfolio could retire up to 47% richer due to fee savings alone.
Wealthsimple confirmed that direct indexing portfolios are now available, offering the same tax saving tools used by large institutions. The service automates daily tax loss harvesting across individual stocks and charges a 0.15% management fee, as shown on the direct indexing page.
It lets investors mirror an index while owning each company directly, which can improve after-tax results and give more control over what they hold. The system automatically sells losing stocks to offset gains and reinvests the money to keep market exposure.
Wealthsimple previewed upcoming AI powered research and trading tools that will generate market summaries, identify trends, and deliver event alerts. Also scheduled for release are secured puts, multi-leg option strategies, and a built-in Norbert’s Gambit function for more efficient currency conversion.
These new tools showcase how automation and personalized data analysis are converging on the platform.
Wealthsimple introduced a new full service wealth management tier that combines digital access with human advice via text and proactive tax and contribution planning. Management fees start at 0.5% for higher balances.
The 2025 event reinforced Wealthsimple’s ambition to democratize sophisticated investing while lowering costs for Canadians. From zero fee options and physical gold to direct indexing and hybrid advice, the company’s strategy blends accessibility with innovation. As its AI tools and private market portfolios scale through 2026, the balance between automation, transparency, and client empowerment will remain key measures of success.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 7, 2025
Image: Freepik/tonodiaz
The Indian stock market is often a reflection of investor sentiment, company fundamentals, and broader macroeconomic shifts. One of the indicators investors watch closely is the 52-week high and low levels of stocks. A stock trading near its 52-week low often sparks curiosity: Is it a bargain buy or a falling knife?
ITC has long been considered a safe bet for conservative investors. But with the stock hovering close to its 52-week low, the pressing question is: Should ITC be on your radar now? In this blog, we will explore whether investors should consider buying ITC stock at its 52-week low.
The stocks near 52 week low is the lowest price at which a stock has traded in the past year. For many investors, this is a signal that the stock may be undervalued. However, it could also indicate deeper structural challenges or declining investor confidence.
Hence, before considering ITC, it’s essential to look at its fundamentals, recent developments, and industry dynamics.
ITC has diversified revenue streams from cigarettes to FMCG, hotels, and agri-exports, which have helped it remain resilient, though growth in its non-cigarette business segments has been slower than rivals like HUL or Nestlé.
As of September 2025,the ITC share price is trading close to its 52-week low of ₹390.15, currently hovering around ₹410.65. It is still far below its 52-week peak of ₹528.50. In comparison to the broader index and its Nifty FMCG peers, it has underperformed with a decline of almost 15% in the last year.
There are several factors behind the ITC share falling to its 52-week low levels. Some of those reasons are:
Investors often rotate out of defensives like FMCG into higher-growth sectors (IT, auto, banks) when markets are bullish.
Compared to FMCG peers, ITC’s topline expansion remains moderate, particularly in branded foods and hotels.
After its multi-year rally (2021-2023), profit booking has amplified near-term declines.
Cigarettes remain under heavy scrutiny due to taxation and health regulations. Any potential tax hikes impact sentiment.
The company recently announced the demerger of its hotel business, which led to mixed reactions from the market.
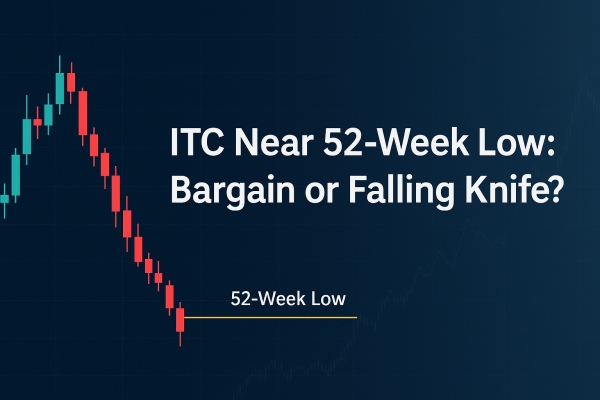
ITC Near 52 Week Low
With ITC close to its 52-week low, investors may find it to be a risky but appealing entry point. The following is a discussion of the causes of both cases:
A stock hitting its 52-week low should not be the sole reason to buy or sell; it’s a signal that requires deeper analysis. In ITC’s case, while regulatory risks and slower growth weigh on sentiment, its dividend yield, diversified business, and defensive nature make it a strong option for conservative investors.
Therefore, ITC should be on the radar of those investors who seek stability, regular dividends, and a defensive play, and investors who are chasing aggressive growth and fast-moving stocks should not consider investing in ITC at its 52-week low share price.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crowdfunding | Oct 1, 2025
Image courtesy of AI
On March 7, 2025, Rugby Canada announced a bold public campaign to fund its women’s high performance team to England 2025. The campaign laid out a $1 million shortfall to cover the full season's program that costs $3.6 million (but the union's budget fell short). So to close the funding gap, they opened the doors to fans, alumni, and corporate donors and launched a dedicated donation portal for this effort: Mission: Win Rugby World Cup 2025 donation portal.
That night, the campaign thermometer sat at zero. By morning, it was alive as part financing tool and part storytelling engine that sparked a national movement in Canadian sport.
Rugby Canada needed more than dollars. They needed narrative. The early campaign push did three essential things well:
They didn't just ask for support but described the exact dollars missing and how each contributed dollar would map to camps, nutrition, recovery, and test matches.
Supporters weren’t just donors but they were treated as 'partners' in getting the Canadian Women's Rugby team ready for the World Cup 2025, a massive global sporting event.
Independent rugby media tracked progress. In April, RugbyPass ran a report noting the still‑open funding hole and provided key updates in how far along the drive had come, and how much further they still needed to go to achieve their mission.
As the 2025 Women's Rugby World Cup (hosted in England) drew closer and closer, media narratives framed Canada not just as underfunded underdogs but as gritty, scrappy, and deserving contenders. Sky Sports ran a feature titled “How non‑professional Canada crowdfunded its way to the final push,” saying pledges “reached 95 percent.”
Meanwhile, ESPN ran a narrative piece under the banner “Canada crowdfunded their way to the World Cup” juxtaposing the team’s funding shortfall with their on‑field ambitions.
Kudus to participating media that helped raise awareness for such an important Canadian funding drive. It really shows what's possible when the full ecosystem gets behind an initiative and drives momentum forward. There's a natural connection between executing a well timed and focused financing campaign and executing a key sports performance, and the public knows it. #ElbowsUp
When England 2025 kicked off, Canada stepped onto the pitch motivated by even greater purpose, not a team suffering by funding shortfall anxiety.
In pool play they went undefeated, carving out physical, disciplined performances that turned heads.
In the quarter final, they defeated a powerful Australia squad.
In the semi final, they shocked the rugby world by defeating New Zealand (perennial favourites) to reach their first Women’s Rugby World Cup final.
On September 27, before a packed Twickenham, Canada faced hosts England. They lost but not meekly. In the aftermath, coach Kevin Rouet and captain stressed that the match was decided on performance, not excuses, a point that resonates in Reuters’ coverage of the final.
Crowdfunding bought the players the chance to compete on equal footing, free of resource excuses. The lesson for Canada as a sporting nation was significant. When supports and fans step in to close gaps, institutions can't ignore the demand for sustainable, professionalized backing of women’s rugby.
Players adjusted their off season budgets and personal spending to show they were all in on the campaign narrative.
Coaching staff scheduled extra camps contingent on fundraising milestones, keeping the team in lockstep with the thermometer.
Each media checkpoint (50%, 80%, 95%) became a moment of drama as the story unfolded. Would the final stretch succeed or stall? That tension made the campaign itself a parallel storyline to the competition.
Critics wondered whether public fundraising blurred lines between sport and fandom but supporters embraced the risk, seeing their dollars as equity in national ambition at a time when Canada needs to buckle down and drive through the line.
When everyone's in the same boat, the winds will sail.
This was more than just a funding story. If you want one of those, feel free to read the real story of access to capital. It was about turning a resource gap (a modern day limitation) into shared ownership.
Canada’s women made their financial constraints visible, linked every dollar to performance outcomes, and invited supporters to become backers in the journey. That transparency changed how Canadians see women’s sport funding not as charity, but as investment with real returns.
The campaign also created accountability. Once the thermometer went public, the team owed backers results, not just thanks.
The story will not always be this dramatic, but the connections and motivations are real, and crowdfunding amplifies that blueprint. Define the gap, own the narrative, attach every contribution to a tangible outcome, and treat supporters as true partners.
Collaboration was at the core! Players, fans, alumni, sponsors, and media all carried their share of the work. As Canada’s women look beyond 2025, the responsibility now shifts to institutions, national sport bodies, sponsors, and public agencies to ensure future generations no longer need to crowdfund their path to the world stage, or maybe they should! #GoCanada
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Regulation | Sep 3, 2025
Image: Freepik/DC Studio
On September 2, 2025, Staff from the SEC’s Division of Trading and Markets and the CFTC’s Divisions of Market Oversight and Clearing and Risk issued a joint statement announcing that under existing law registered U.S. exchanges are not prohibited from listing and trading certain spot crypto asset products. The move is tied to the SEC’s Project Crypto and the CFTC’s Crypto Sprint, and follows recommendations from the President’s Working Group on Digital Asset Markets to strengthen U.S. leadership in blockchain innovation and finance.
The statement makes clear that regulated venues such as national securities exchanges, designated contract markets, and foreign boards of trade can facilitate spot crypto trading without new legislation. In doing so, the agencies say they want to provide market participants with more choice and keep blockchain innovation within U.S. borders.
Staff emphasized that this is a nonbinding staff view, and not a rule or regulation, but invited firms to bring filings and proposals for prompt review. The joint effort is aimed at balancing innovation with investor and customer protection.
For market participants, the agencies highlighted several expectations:
According to analysis from Shearman and Sterling, the coordinated message is an important step toward clarity and a more constructive approach by regulators, potentially opening the way for spot digital assets to be listed on traditional U.S. exchanges like NYSE and Nasdaq.
Industry commentary highlight that over 92 crypto ETF applications are already before the SEC, including more than a dozen targeting XRP and other assets, and many of these could benefit directly from the new staff position.
For Canada, this development matters. If major U.S. exchanges begin offering spot crypto products under a coordinated regulatory approach, it will put further pressure on Canadian markets and regulators to keep pace. Canadian fintechs and exchanges would face heightened competition if retail and institutional investors move liquidity south. Without similar clarity, Canadian platforms risk falling behind in attracting capital, innovation, and building global relevance.
The SEC and CFTC’s joint staff statement isn't a new binding law but it sends a clear message that there's room for regulated spot crypto markets in the United States. For entrepreneurs, investors, and regulators in Canada, buckle up because competition in crypto and digital finance markets could anchor the next several years to come.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Klarna | Sep 3, 2025
Image: Klarna IPO 2025
On Sep 2, 2025, global digital bank and Klarna announced the launch of its initial public offering (IPO) targeting a $14 billion valuation, with shares expected to begin trading on the New York Stock Exchange under the symbol KLAR this week, once the SEC approves its registration. Klarna calls itself a global digital bank and flexible payments provider in its IPO filing, but buy now pay later (BNPL) is still its main business and the focus of regulatory scrutiny.
The company disclosed an offering of 34,311,274 ordinary shares, including 5,555,556 new shares from Klarna and 28,755,718 from selling shareholders. The underwriters have a 30 day option to purchase up to 5,146,691 additional shares. The expected price range is $35 to $37 per share, which would give Klarna a valuation of up to $14 billion if priced at the top end.
The majority of the shares in this deal are being sold by existing shareholders. Klarna itself will only receive proceeds from the 5.6 million new shares it issues, while selling shareholders will capture the remainder. Goldman Sachs, J.P. Morgan, and Morgan Stanley are lead underwriters.
Klarna paused its U.S. IPO in April 2025 citing tariff uncertainty and market volatility, then revived the listing as IPO conditions improved over the summer. The company had also explored a direct listing in 2021 but didn't proceed, later raising funds at a $6.7 billion valuation in 2022.
Klarna has invested directly in Canada, and deepened its roots here by opening a technology hub in Toronto focused on engineering and product development. NCFA reported on this this expansion closely in this article Klarna’s meteoric rise in the Canadian financial ecosystem. In Canada, BNPL activity is beginning to appear on credit reports.
As of June 30, 2025, Klarna reported 111 million active consumers and 790,000 merchants across 26 countries. The United States is its largest market, with 34 million users and over 30,000 merchants.
The Consumer Financial Protection Bureau issued an interpretive rule in May 2024 that classified buy now pay later lenders as credit card providers under Regulation Z, which was meant to extend credit card style protections such as dispute rights and refunds. Under the Trump administration the agency itself has been weakened through layoffs, budget cuts and rollbacks of Biden era protections. In March 2025 the CFPB announced its intent to revoke the rule, and by May 2025 it had stated it would not prioritize enforcement.
For Klarna and its 34 million American users, the 'dormant status' of the BNPL rule lowers compliance costs and regulatory risk at a critical time, as it allows the company to present a clear growth case to public investors. At the same time though, investors in Klarna's IPO should weigh both the short term relief and long term political uncertainty, given that a future administration could revive the proposed BNPL credit card style protections.
Klarna is not alone. Several fintech peers have already gone public this year, offering a snapshot of how investors are valuing the sector. The wave of fintech IPOs are after years of light activity but beyond pent up demand signals that fintech markets are maturing and scaling into evolving financial markets globally. Chime, Circle, and eToro illustrate both successes and setbacks.
| Company | Ticker | IPO Date | IPO Price | Current Price (Sep 3, 2025) | Change |
| Chime Financial | CHYM | Jun 12, 2025 | $27.00 | $24.40 | –9.6% |
| Circle Internet Group | CRCL | Jun 5, 2025 | $31.00 | $119.80 | +286.5% |
| eToro Group | ETOR | May 14, 2025 | $52.00 | $46.63 | –10.3% |
| Klarna | KLAR (pending) | Sep 2025 | $35–$37 | Not yet listed | N/A |
| Figure Technologies | FIGR (pending) | Sep 2025 (planned) | $18–$20 | Not yet listed | N/A |
Klarna’s performance will set another benchmark for how diversified platforms blending BNPL, banking, and payments are valued by public investors.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2025
Source: Michal Parzuchowski on Unsplash
Ontario has frequently served as a pioneer and testing ground for many new policies and frameworks in Canada. So, when the province opened its regulated iGaming market in 2022, it became both a local milestone and a national signpost for how online gambling could be regulated in the country. Before that, online gambling existed in a grey area in which players wanted to participate but had to do so away from any oversight, relying on unregulated platforms and offshore providers with little guarantee of safety.
After Ontario opened the floodgates to a regulated market, however, it proved that the decision could not have been more rewarding. Money now goes through regulated channels, taxes can be collected and measured, and consumer protections provide peace of mind. And even with this more rigid structure, the market stays competitive, with multiple licensed operators for players to choose from.
Because of these successes, other provinces are taking notice and asking themselves whether Ontario’s model could act as a reference point for their own approach to iGaming and other online consumer markets.
For years, online gambling in Ontario followed much the same path as the marijuana industry. Grey markets existed, with consumers turning to unregulated sources. Then, regulation formalized the market and brought businesses under government oversight. Finally, when safety measures and consumer protection were put into place, the public had greater confidence in participating, knowing that everything was monitored, accountable, and fair.
Ultimately, it was necessary for the iGaming industry to move from the grey zone to regulated markets. After all, that environment created risks for players and serious problems for policymakers, with public safety concerns and a lack of recourse. iGaming Ontario (iGO) worked closely with the Government of Ontario and the Alcohol and Gaming Commission of Ontario (AGCO) to establish the Ontario iGaming model to give consumers assurance. Rather than questioning whether operators are trustworthy, licensed providers in the new market must meet rigorous standards and Canadian gambling laws.
It’s a win-win situation for all involved in the sector, and all it took was establishing a clear and transparent regulatory framework. Ontario’s model is a great example of how formal oversight can turn an unregulated industry into an economically productive market. Regulation doesn’t exist to confine operators, but to balance innovation, choice, and accountability.
While we’ve touched upon why player protection matters so greatly in the iGaming industry, it’s worth taking a closer look at how it actually makes a difference.
What players appreciate most above all in this regulated market is the sheer protection it offers. Much like a shield or protective barrier, it means players can participate without worrying about hidden risks or getting scammed. Because operators are required to implement safeguards like identity verification, dispute resolution, secure payment processing, and self-exclusion tools for responsible gambling, players can trust that the system is secure and know there are real rules in place.
Prior to having these rules, choosing a platform was a gamble—one that many people didn’t want to take. Grey-market sites basically had zero guarantee. There was a chance that you would never get paid out or see your deposited money ever again. Player data could be sold to the black market, and you never knew who was on the other side. For those who simply wanted to play a round of roulette or spin the slots, they had to weigh the pros and cons of these sites.
The more Ontario’s model matures, the more consumers will actively avoid platforms that deviate from the regulated framework and favour trustworthy operators. Guides like those published by the Toronto Sun and CanadaCasino list fully regulated online casinos as a trusted reference point. With easy access to countless vetted resources, consumers are completely empowered to make smart decisions and play their favourite casino games even in a potentially unfamiliar landscape.
Where there’s trust, consumers can focus on enjoyment rather than worrying about risks in a once-volatile industry.
Ontario’s iGaming model teaches important lessons for provinces considering forming their own online gambling strategies. While almost all provinces have some sort of laws surrounding online gambling, many restrict activity to provincially licensed sites or a single provider managed directly by the government. Quebec and Newfoundland and Labrador, for example, both maintain government-monopolized systems, which are much more restricted compared with Ontario’s competitive model. While these models certainly give regulators more control and secure revenue, they also limit consumer choice and innovation.
Without a better political, ethical, and economic balance, these provinces could be restricting their full potential. Liberalized markets have shown that opening up the sector can generate many benefits, including wagering revenue. In Ontario, doing so has created jobs in several fields, fostered partnerships with fintech companies, and even encouraged digital platform innovation in the casino and adjacent industries. Provinces that stay open to adopting these models could see serious economic growth from multiple fronts, supporting a modern digital marketplace.
A well-regulated online gambling market can start a ripple effect, sparking investment and creativity in other digital fields. Considering that the digital economy is only growing, these spillover benefits make this kind of regulatory model extra valuable for other provinces looking to modernize.
So long as licensing systems are taken seriously and compliance with anti-money laundering and responsible gambling requirements is mandated, consumers can stay protected. Effective regulation requires active oversight, but the AGCO and iGaming Ontario prove that it’s possible to maintain strict standards while supporting a dynamic market. With these bodies enforcing the standards, public education campaigns, and independent audits taking place, all pieces of the system can come together and maintain market integrity.
Across other digital sectors like fintech and regular gaming, there’s a common question being asked: Can regulation really support innovation? Ontario’s experience suggests a resounding yes. In comparison to traditional sectors, those in the online world face special challenges, such as evolving technological changes and a stronger potential for misuse. If regulators tackle them head on, however, smart regulation can become the catalyst for innovation that provinces in Canada are looking for. Ontario is a perfect example of that.
Through licensing systems and independent oversight, stakeholders have created an ecosystem in which operators can experiment with their services without undermining public confidence. It’s a model that highlights just how much trust influences adoption. Consumers need trust in order to feel sure about what they’re engaging with. Even beyond gaming, this framework can be applied to other areas where consumer confidence is the crux for scaling.
The Ontario iGaming system is complete proof that regulation and innovation don’t have to be at odds. The province’s heavy focus on consumer trust and strict monitoring has built a thriving market that benefits players, operators, and the broader economy. It has left people feeling free and empowered rather than restricted and confined, illustrating that thoughtful regulation is the key.
Other provinces are now in the driver’s seat. With such a clear and substantiated model to mirror, they have the blueprint and lessons that could guide a much safer, competitive, and innovative online gambling ecosystem. Since the world is falling more in love with tech-driven consumer experiences, now’s the time to apply Ontario’s lessons and create something fresh and fun.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
