





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026).
Regulators are aligning competition rules and data protection in a way that directly affects how AI systems access, process, and govern data. For fintechs and financial institutions building on platform infrastructure, data strategy, consent design, and compliance architecture are becoming tightly coupled decisions.
Large platforms, AI firms, fintechs, and financial institutions that depend on platform distribution, data access, identity layers, or app infrastructure face a more active compliance environment. Platform terms, profiling practices, interoperability rules, and access conditions can change through ongoing regulatory review. Firms with high dependency on a small number of gatekeepers face increased operating risk, while firms that diversify distribution, strengthen direct customer relationships, and build adaptable data and compliance architectures will be better positioned.
The next edge will come from firms that can operationalize data standards, identity rails, and compliance workflows across jurisdictions rather than wait for policy intent alone to close the gap.
This deal says scale in cross border payments is moving toward platforms that already combine distribution, compliance support, and endpoint reach. For smaller wallet, remittance, and banking partners, the harder question is no longer whether they can connect. It is whether they still control enough of the customer relationship or economics once a larger stack sits in the middle.
This brings Ripple inside the licensed payments system in Australia. It can handle more of the payment flow itself instead of relying on partners. That includes onboarding, compliance, FX, and payout. For banks and fintechs, this means a digital asset firm can now compete more directly on cross border payments with full regulatory coverage, not just as a crypto overlay.
This impacts payment processors, merchant platforms, and consumer fintechs that want to own checkout and settlement. A payment aggregator license pulls merchant onboarding, refunds, and settlement into one accountable layer, so competitors and partners should expect tighter expectations on merchant screening and operational controls as volumes grow.
This impacts fixed income platforms, treasury and collateral systems, and anyone building workflows that touch Government of Canada collateral. Dealer funding and hedging capacity affects liquidity and trading costs.
This impacts capital markets fintechs that want distribution through regulated channels. When a top tier exchange brand commits to a tokenization partner, procurement and diligence tighten fast. Builders should prepare for deeper questions on governance, surveillance, custody controls, and how tokenized assets move without breaking compliance reporting and investor protections.
This raises the execution standard for digital onboarding, disclosures, promotions, and support flows. For fintechs, good UX is no longer enough on its own. Firms need evidence that customers understand what they are seeing and can act on it without avoidable confusion.
Ottawa is pushing affordability through multiple channels at once, including taxes, housing, and core banking fees. For banks, that puts more pressure on legacy fee revenue and raises the importance of better alerts, cash flow tools, and low cost account design. For fintechs, it strengthens the case for products that help users avoid failed payments, manage short term liquidity, and lower everyday banking friction.
Banks lose part of a high margin penalty fee and face more pressure to compete on better alerts, balance visibility, payment controls, and products that help customers avoid failed payments in the first place. Direct product and revenue implications across consumer banking.
This opens a formal rulemaking lane around one of the fastest growing grey areas in digital markets. It matters for exchanges, brokers, market makers, and fintech platforms. How far regulated market structure will let them scale before they run into tighter product boundaries.
This guidance impacts how Canadian DIY investment platforms can design tools and user experiences. Online brokers and fintech wealth platforms now have clearer room to provide decision support, portfolio models, and guided interfaces, but they must build stronger safeguards to ensure those tools do not cross the line into regulated investment advice (a condition of the OEO regulatory exemption).
Public payment rails can widen access, but they can also compress private platform economics and add pressure onto merchant pricing. For banks, fintechs, and payment providers, the real issue is not only whether public rails expand. It is how pricing design changes volume, margin, and who absorbs the cost.
A charter application signals a potential change in funding and balance sheet strategy for an AI lending platform and it can reshape partner economics for banks and credit unions that currently fund originations.
This is more than a weak quarter. It puts credit quality, funding resilience, and covenant headroom back at the center of the non prime lending story, which matters for alt lenders, securitization partners, credit investors, and fintechs selling underwriting, servicing, collections, and portfolio monitoring tools into the consumer lending stack.
This matters for brokers, carriers, and digital asset clients because premium payments are a treasury workflow. Once stablecoins clear premiums across real counterparties, buyers and carriers will ask harder questions about controls, reconciliation, and how funds move from premium collection to coverage without losing traceability.
This roadmap puts Europe closer to a tokenised market structure built around central bank money rather than private settlement workarounds. It matters for banks, FMIs, tokenisation platforms, and securities infrastructure teams because the market is now moving from exploratory work toward live design choices on standards, networks, and governance.
This opens a cleaner path for brokers and institutional desks that want crypto execution without rebuilding their stack around proprietary APIs. Once crypto routing uses the same FIX plumbing as other asset classes, firms will put more weight on consistent controls, audit trails, and operational readiness across both traditional and digital venues.
Payment networks are scaling distribution and wallet reach. Tokenized market structure is moving closer to institutional use. Canada’s NSF fee cap also cuts into a legacy bank revenue line and raises the value of tools that help customers avoid failed payments. The strongest fintechs and financial institutions are combining regulatory discipline, strong rails, and practical financial workflows that reduce friction for users.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 11, 2026 | NCFA Fintech Market Activity | Wealthtech And Market Data Infrastructure
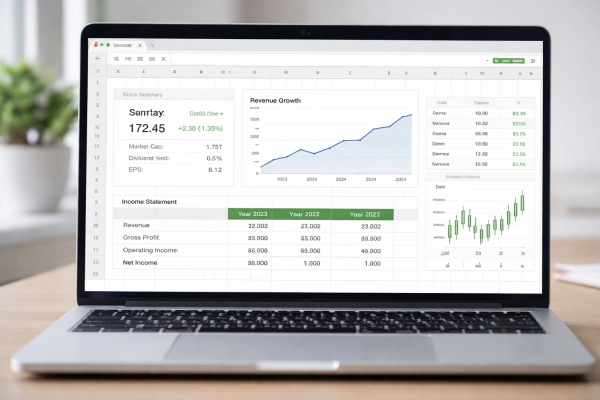
On Mar 10 2026, Toronto based firm Wisesheets made a product and pricing announcement for individual investors to pull financial statements and market data directly into Microsoft Excel and Google Sheets, currently serving users in 40+ countries per the release.
Wisesheets fits people who already work in spreadsheets and want data to flow straight into their models. That includes retail investors building screens, watchlists, and valuation models, analysts at smaller funds, advisors doing quick comparables, and founders or finance teams pulling data without paying for a terminal. The value is speed and repeatability. When data lands in Excel or Sheets, users can run their own formulas, build their own screens, and refresh models without copying numbers from websites into cells, or use one of the AI integrations.
Wisesheets offers three tiers with different features. Wisesheets annual pricing lists Pro at $60 USD per year, Elite at $120 USD per year, and Enterprise at $900 USD per year. Spread across 12 months, that works out to as low as $5 USD per month for the starting service. You can learn see Wisesheets documentation.
There's competition for this service. Google Sheets includes GOOGLEFINANCE, but Google warns quotes may be delayed up to 20 minutes and the information is provided “as is.” MarketXLS offers an Excel focused market data and analysis add in with a Standard plan priced at $70 per month or $850 USD per year. Excel Price Feed also offers an Excel add in for market data with different pricing by user type.
Wisesheets competes on price versus paid spreadsheet add ins and on workflow fit by keeping the user inside Excel and Sheets. Low cost spreadsheet data tools keep squeezing the middle of the research stack. Terminals still win on depth, support, and enterprise controls. Free and low cost tools win on price, but they come with limits and delay risk. Spreadsheet add ins win when they reduce manual work and keep models current and affordable for use.
For Wisesheets, credibility comes down to data quality, reliability, and whether the add in stays stable as users build heavier models and rely on it for repeatable screening and valuation work.
If spreadsheet add ins can deliver usable market data for $60 to $120 USD per year, which parts of the legacy retail research stack still justify premium pricing, and what about new AI services?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 9, 2026 | NCFA Fintech Market Activity | Lending And Consumer Finance
Image: Freepik/senivpetro
On Mar 9 2026, autologiQ acquired FIX4’s dealer network and repair financing originations, effective immediately.
Imagine that a customer is hit with a high cost repair, the dealer or service centre needs payment to start or finish the work, and financing becomes the bridge. autologiQ’s EasyPay product positions itself as a repair, maintenance, and upgrades financing option with two loan types, asset based loans and credit based loans.
autologiQ is an Oakville based automotive services and financing platform. Its LinkedIn page lists a 2017 founding year and core focus areas that include digital platforms, repair financing, and automotive services. See autologiQ company profile.
FIX4 operates in a similar market with a dedicated repair loan product and an authorized service centre network. On its website, it says FIX4's car repair loan platform can approve claims within minutes and markets to targets customers who cannot cover emergency repair bills. FIX4 repair loan offer includes product terms such as up to $10,000 over 36 months.
Jeffrey Newhouse, CEO autologiQ:
“This acquisition aligns with autologiQ’s strategy to expand our advisory services and offer repair finance and insurance solutions to Canadian automotive dealerships, building on our strong foundation in the automotive aftermarket.”
The practical impact of this deal is distribution plus origination flow. Dealers that previously used FIX4 now route repair financing through autologiQ’s EasyPay while keeping immediate payment on repair invoices in the dealer workflow.
This is also a consumer credit channel that can grow quietly. Repair finance is somewhere between a credit card and a personal loan, but it's delivered at the point of need, when the customer has limited time and limited alternatives. Platforms that control dealer distribution and approval flow can compound volume faster than platforms that only compete on rate.
As more dealerships embed repair financing at checkout, does the advantage move to the platform that controls dealer distribution and approvals rather than the platform that only funds the loan?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 6, 2026 | NCFA Fintech Market Activity | Consumer Credit And Identity And Data Governance
Image: Freepik/fabrikasimf
Per an Investment Executive article, on February 22, 2026, a proposed class action application was filed in Quebec alleging that repeated access to a consumer credit file data occurred without authorization through a third party platform account that the applicant says he never opened or approved.
The application says an unauthorized party created an account on Borrowell and used it to access the applicant’s Equifax credit file. It alleges the matching and authentication process accepted partial, inaccurate, or outdated personal information without enhanced identity verification and without effective controls to detect inconsistencies.
The filing describes a series of inquiries and access events through Borrowell at almost weekly frequency over roughly four months. It alleges the access did not affect the applicant’s credit score, but harmful with unauthorized disclosure of highly sensitive personal and financial information.
The application also alleges that Equifax uses a similar access model with multiple third party partner platforms in Canada, and it names examples including KOHO Financial Inc., Credit Karma Canada, Mogo Inc., and Chexy, among others.
This is a market structure issue inside consumer credit. Credit file access is part of many modern onboarding and underwriting flows across lending, banking, payments, and personal finance apps. If a court accepts the argument that matching and authentication rules allowed unauthorized access through partner channels, it will raise scrutiny for how bureaus and partner platforms handle identity verification, monitoring, and anomaly detection for credit file requests.
Both the credit bureau and third party partners need tighter identity checks, clearer consent proof, and better alerts for repeat access. Canadian regulators already expect financial institutions to manage these risks. For example, OSFI’s Third Party Risk Management Guideline B-10 requires federally regulated institutions to remain accountable for services delivered through partners and to maintain strong due diligence, monitoring, and control frameworks across the full lifecycle of third party relationships.
If partner platforms can trigger credit file access using partial or outdated identifiers, what standard should govern consent checks, anomaly detection, and step up verification for repeat inquiries?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 27, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure, Risk Compliance And Regtech
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026).
This is early proof that capital is willing to line up behind an asset backed token model before issuance begins. It matters for tokenization platforms, digital asset builders, and market operators because demand at this level raises the stakes on what comes next, especially issuance design, trading access, settlement flow, and how real world asset tokenization earns trust beyond crypto native buyers.
This affects stablecoin issuers, wallet and exchange operators, payment firms that want stablecoin rails, and banks that can custody reserves or provide settlement accounts. The sandbox work turns authorisation readiness into near term execution, because counterparties will start asking who controls mint and burn, how reserves get safeguarded, how redemptions clear under stress, and what evidence you can produce before the September 2026 application gateway opens.
Institutional buyers tend to route flow to whoever can prove segregation, controls, and settlement certainty under supervision, and this move aims straight at that bar.
This is important for payment firms, open banking providers, digital asset infrastructure teams, and banks building new rails in the UK. A single forward plan from all four authorities makes timing harder to ignore, because product roadmaps, compliance sequencing, and partner conversations now sit against a more visible policy calendar.
This is a real infrastructure and distribution move in Canadian payments. It affects fintechs that bank through Peoples, embedded finance and sponsor bank partners, and any firm building around faster payments rails, because a stronger bank plus processor stack can tighten expectations on integration, uptime, message quality, and partner readiness well before RTR becomes fully operational.
Is this a key domino in AI finance? This is what AI looks like when it evolves from product feature to company structure. Large fintechs, payments platforms, and their investors now have a clear example of stronger results arriving alongside much smaller teams, placing more weight on execution quality, operating discipline, and how management builds from here.
This is one of the cleaner bridges between public capital, development finance, and founder scale. If you build inclusion fintech in ASEAN, expect the bar to move toward impact proof and deployment readiness, because capital now sits inside the same program that opens doors.
This is a significant turn of events for credit unions, fintechs, and crypto custody models that want a federal charter in Canada. A clearer approvals path can change when firms choose to enter the federal perimeter and how seriously investors and partners treat that option.
It affects stablecoin issuers, banks, custodians, exchanges, and fintechs that plan to distribute payment stablecoins, because reserve design, redemption handling, audits, supervision, and custody expectations start to look like core product requirements, not optional features.
This affects lenders, CRAs, and fintechs that rely on bureau data for onboarding and underwriting. Teams should expect more pressure on data completeness, dispute handling, governance, and audit evidence because mandatory sharing can reset what a clean credit file must look like.
This meeting keeps the door open to a simpler capital raising layer below broker dealer economics. Platforms, issuers, and service providers that touch private raises and secondary liquidity should watch for recommendations that tighten who can get paid, how referrals get documented, and what disclosure standard can unlock broader resale paths.
This raises the value of process maturity. If your fintech faces enforcement exposure, the timeline gives more room to assemble evidence, but it also rewards teams that keep clean records and can explain decisions fast when scrutiny hits.
Important for tokenized markets because clean settlement depends on clean reference data. Teams building custody, collateral, repo, and tokenized securities infrastructure must soon meet a higher standard on pricing integrity, entitlement controls, and auditability as institutional workflows move on-chain.
This is an immediate capital incentive change. If you sell insurer investment, treasury, or regulatory reporting tooling, expect more pressure to classify eligible exposure fast and produce clean evidence for PC4 filings while the treatment stays live.
This raises the cost of weak pre-trade controls. Teams selling OMS, EMS, surveillance, or post trade tooling into dealers should expect more demand for guardrails that prevent self matching and catch close related mistakes early, plus audit ready evidence when exceptions still occur.
The market continues to tighten where new rails are forming, and where management teams are being forced to adapt faster. Stay nimble and ahead of the curve. Be cautious about waiting for late stage confirmations. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 26, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure
Image: Pixabay/viarami
On February 25 2026, Peoples Group announced a partnership with Fiserv to develop a next generation payments platform intended to serve financial institutions and fintechs across Canada.
The initiative combines Fiserv’s Enterprise Payments Platform with DNA core banking technology and represents one of Peoples Group’s largest technology investments. The infrastructure is designed to improve payment processing connectivity, support unified orchestration across card, account to account, and real time payment flows, and prepare for Payments Canada’s Real Time Rail environment.
The platform focuses on backend modernization rather than a consumer product launch. Peoples Bank of Canada, part of Peoples Group, continues to expand its role as a sponsor bank supporting fintech programs that rely on regulated balance sheet access, settlement infrastructure, and program management. Strengthening this capability can improve launch readiness for embedded finance, prepaid, and digital wallet partnerships while reducing reconciliation friction across payment channels.
Canadian payment modernization continues to advance in parallel to global peers, creating opportunities for infrastructure providers that invest early. Sponsor banks capable of supporting fintech scale with resilient payment processing and real time connectivity often become key enablers of ecosystem growth.
Peoples Group’s investment reflects how smaller specialized banks can play an outsized role in fintech enablement by focusing on platform capabilities rather than retail distribution.
Will deeper bank-fintech infrastructure partnerships accelerate Canada’s payment modernization timeline and expand the range of fintech products available to businesses and consumers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Learn more.
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
