




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 18, 2026 | NCFA Insight | Digital Assets And Tokenization
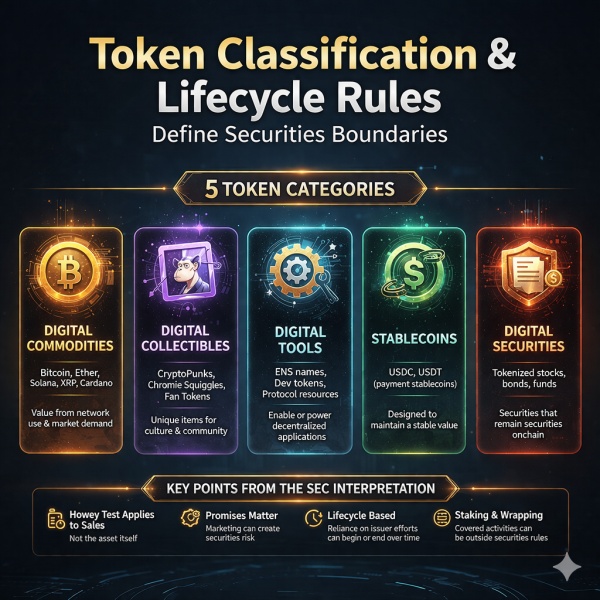
On Mar 17, 2026, the U.S. Securities and Exchange Commission issued a formal interpretation on how federal securities laws apply to certain crypto assets and certain crypto asset transactions with aligned support from the CFTC read the SEC’s March 17 press release on the joint crypto interpretation (and Fact Sheet).
This is a significant U.S. digital asset policy interpretation because it gives the market something it's lacked for a long time: a public classification system, a public lifecycle test, and public treatment of core activities such as staking, wrapping, and airdrops.
The old question of 'is it a security?' no longer sits only at the token level.
The SEC now says the answer can depend on the category of asset, the way it is sold, the promises around it, and whether those promises still matter later in the market.
The release classifies crypto assets into five categories based on characteristics, uses, and functions: (1) digital commodities, (2) digital collectibles, (3) digital tools, (4) stablecoins, and (5) digital securities. It's a framework that crypto firms can actually use in product design, listing review, and compliance planning.
Some of the examples are worth noting. In the published interpretation, the SEC lists Aptos, Avalanche, Bitcoin, Bitcoin Cash, Cardano, Chainlink, Dogecoin, Ether, Hedera, Litecoin, Polkadot, Shiba Inu, Solana, Stellar, Tezos, and XRP as examples of digital commodities. It says these assets gain value from how the network operates and from market supply and demand, not from a team whose efforts drive profit expectations.
On collectibles, it points to CryptoPunks, Chromie Squiggles, Fan Tokens, WIF, and VCOIN.
On tools, it cites Ethereum Name Service domain names and CoinDesk’s Microcosms NFT Consensus Ticket.
The point is not that every asset that looks similar gets a free pass, and the SEC is now saying publicly that many crypto assets are not securities in themselves.
The SEC separates the token from how it is sold. It applies the Howey test to the transaction, not just the asset. A token that is not a security can still be sold as part of an investment contract if a team’s promises create an expectation of profit.
The interpretation then separates the asset from the contract and explains how that link can end. A non security token is no longer subject to an investment contract once buyers no longer rely on the issuer’s promises.
This can happen in two ways. The issuer fulfills what it said it would build, such as delivering functionality or completing roadmap milestones. Or the issuer abandons those efforts, making it unreasonable for the market to keep relying on them. In both cases, the investment contract can fall away, even though the issuer may still face anti fraud liability for earlier statements.
This directly addresses the secondary market problem. A token’s status in later trading does not depend only on how it was launched. It also depends on whether buyers still rely on the issuer’s promises at that point in time.
The SEC ties securities treatment directly to what issuers say. Statements in agreements, websites, whitepapers, and social media can create a reasonable expectation of profit.
That risk increases when issuers make explicit promises tied to roadmaps, milestones, funding plans, and how their work will drive value.
Token design and marketing cannot be separated. If the sales narrative links price appreciation to team execution, the offering can be treated as an investment contract.
For founders and counsel, that is the message. Product design, legal design, and communications design now need to be built together from day one.
The SEC says covered protocol staking activities don't involve securities transactions when structured as described. It covers self staking, custodial and non custodial staking, delegated and nominated staking, and liquid staking.
The interpretation is that rewards and penalties come from protocol rules, not from a team managing profits. That includes liquid staking models where users receive tokens tied to their staked position. If returns come from how the network operates, not from a promoter’s decisions, the activity is less likely to be treated as a securities transaction. That gives exchanges, custodians, and staking providers clearer ground for product design.
The SEC also says wrapping a non security crypto asset doesn't create a security when the wrapped token is redeemable one for one, the underlying asset stays locked for the holder, and value comes from that underlying asset. This supports cross chain use, custody design, and token mobility.
It also confirms that certain airdrops do not involve an investment of money under the Howey Test when recipients do not give anything in return. Common uses include rewarding early users, supporting governance, and building network participation. This does not make all airdrops safe, but it gives builders a clearer framework to separate distribution from securities risk.
The SEC aligns its position on stablecoins with the GENIUS Act. It says qualifying payment stablecoins issued by permitted issuers will not be securities once the law is in force. It also states that some covered stablecoins already fall outside securities treatment under its interpretation. This gives issuers and institutions clearer direction on how stablecoins are treated at the federal level.
Tokenized securities get a clear boundary. A security remains a security whether it is issued offchain or onchain. The SEC describes both issuer led tokenization and third party tokenization of existing assets. In both cases, moving an asset onchain may improve issuance and settlement, but it does not change its legal status.
This interpretation affects different parts of the market in different ways.
This interpretation shows what a more usable framework looks like in practice. While it doesn't solve every unanswered question, it's helpful and moves the debate from slogans to structure. Markets develop faster when participants can classify assets, model lifecycle risk, and design products in lie with public rules instead of trying to read the regulator’s mind from old enforcement cases.
The SEC doesn't replace the Howey Test but it makes Howey more operational for crypto markets. That's the real change. The release gives the industry a public map for classification, a public test for when securities treatment begins and ends, and public treatment of activities that sit at the center of token network design. If you're looking for more of a legal analysis here.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 17, 2026 | NCFA Insight | Banking Regulation And Digital Assets

The debate is heating up over crypto and fintech access to US banking infrastructure since actions already taken by the Office of the Comptroller of the Currency (OCC) on Dec 12 2025 to conditionally approve five national trust bank charters for the following crypto firms: First National Digital Currency Bank, Ripple National Trust Bank, BitGo Bank & Trust, Fidelity Digital Assets, and Paxos Trust Company. These charters allow firms to operate under federal oversight for custody and payments without taking deposits.
On Mar 17 2026, the Wall Street Journal reported that regulators are considering expanded crypto bank access, points to further expansion along this path rather than a new standalone rule. The direction is reinforced by guidance such as the OCC bulletin on digital asset and stablecoin activities, which shows regulators are already defining how non traditional firms operate within the federal banking perimeter.
It's significant because national trust charters give firms a way to scale across the US without relying on fragmented state licensing. They provide a regulated path into custody, payments, and fiduciary services under a single federal supervisor, without becoming full service deposit taking banks.
Traditional banking groups are pushing back. In a statement opposing OCC conditional approval of five national trust bank charters, the Bank Policy Institute (BPI) said the decision left “substantial unanswered questions” about how these firms would operate and be supervised. BPI has also filed specific objections to trust charter applications, including its opposition to Connectia Trust’s national trust bank application and its opposition to BitGo Trust’s conversion to a national trust bank.
The concern is regulatory parity. Banks argue that if crypto and fintech firms can access core custody and payments infrastructure through trust charters without taking deposits, they may gain entry to important parts of the banking system without facing the same balance sheet requirements as full service banks. That tension is at the center of the policy debate. Who gets access to regulated infrastructure, and under what conditions.
The US isn't waiting for a new trust charter rule. It's progressing through approvals, guidance, and case by case decisions that give some firms a clearer path into regulated custody, payments, and fiduciary services under federal oversight.
A national trust charter can reduce dependence on fragmented state licensing, improve credibility with institutional partners, and make it easier to build around regulated payment and custody infrastructure. But know that the regulatory bar isn't low. Firms pursuing this path still need strong governance, compliance, risk controls, and operating discipline. Access is possible, but it is conditional.
Canada is taking a different approach. In the US, the trust charter debate is about whether crypto and fintech firms can enter deeper into the banking system through a federal charter pathway. In Canada, the main stablecoin related framework sits inside securities and crypto trading platform oversight, not bank chartering. Canadian regulators use the term value referenced crypto assets (see CSA Staff Notice 21 333) and sets conditions around reserves, disclosure, redemption rights, assurance, and platform controls before these assets can be offered to clients. That means the US debate is mainly about institutional status and access to banking infrastructure, while the Canadian debate is mainly about asset eligibility and client protection on regulated platforms.
In Feb 2026, OSFI announced a targeted fast track approval framework for new entrants that will launch in June 2026 and give eligible applicants a quicker, clearer, and more predictable path into the federal system. The initial scope includes provincial credit unions seeking federal status and firms with technologically innovative or emerging banking models.
The real question is not whether crypto firms become banks. It is whether regulators create a consistent operating standard for firms that want access to core financial infrastructure without becoming full service deposit taking institutions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026).
Regulators are aligning competition rules and data protection in a way that directly affects how AI systems access, process, and govern data. For fintechs and financial institutions building on platform infrastructure, data strategy, consent design, and compliance architecture are becoming tightly coupled decisions.
Large platforms, AI firms, fintechs, and financial institutions that depend on platform distribution, data access, identity layers, or app infrastructure face a more active compliance environment. Platform terms, profiling practices, interoperability rules, and access conditions can change through ongoing regulatory review. Firms with high dependency on a small number of gatekeepers face increased operating risk, while firms that diversify distribution, strengthen direct customer relationships, and build adaptable data and compliance architectures will be better positioned.
The next edge will come from firms that can operationalize data standards, identity rails, and compliance workflows across jurisdictions rather than wait for policy intent alone to close the gap.
This deal says scale in cross border payments is moving toward platforms that already combine distribution, compliance support, and endpoint reach. For smaller wallet, remittance, and banking partners, the harder question is no longer whether they can connect. It is whether they still control enough of the customer relationship or economics once a larger stack sits in the middle.
This brings Ripple inside the licensed payments system in Australia. It can handle more of the payment flow itself instead of relying on partners. That includes onboarding, compliance, FX, and payout. For banks and fintechs, this means a digital asset firm can now compete more directly on cross border payments with full regulatory coverage, not just as a crypto overlay.
This impacts payment processors, merchant platforms, and consumer fintechs that want to own checkout and settlement. A payment aggregator license pulls merchant onboarding, refunds, and settlement into one accountable layer, so competitors and partners should expect tighter expectations on merchant screening and operational controls as volumes grow.
This impacts fixed income platforms, treasury and collateral systems, and anyone building workflows that touch Government of Canada collateral. Dealer funding and hedging capacity affects liquidity and trading costs.
This impacts capital markets fintechs that want distribution through regulated channels. When a top tier exchange brand commits to a tokenization partner, procurement and diligence tighten fast. Builders should prepare for deeper questions on governance, surveillance, custody controls, and how tokenized assets move without breaking compliance reporting and investor protections.
This raises the execution standard for digital onboarding, disclosures, promotions, and support flows. For fintechs, good UX is no longer enough on its own. Firms need evidence that customers understand what they are seeing and can act on it without avoidable confusion.
Ottawa is pushing affordability through multiple channels at once, including taxes, housing, and core banking fees. For banks, that puts more pressure on legacy fee revenue and raises the importance of better alerts, cash flow tools, and low cost account design. For fintechs, it strengthens the case for products that help users avoid failed payments, manage short term liquidity, and lower everyday banking friction.
Banks lose part of a high margin penalty fee and face more pressure to compete on better alerts, balance visibility, payment controls, and products that help customers avoid failed payments in the first place. Direct product and revenue implications across consumer banking.
This opens a formal rulemaking lane around one of the fastest growing grey areas in digital markets. It matters for exchanges, brokers, market makers, and fintech platforms. How far regulated market structure will let them scale before they run into tighter product boundaries.
This guidance impacts how Canadian DIY investment platforms can design tools and user experiences. Online brokers and fintech wealth platforms now have clearer room to provide decision support, portfolio models, and guided interfaces, but they must build stronger safeguards to ensure those tools do not cross the line into regulated investment advice (a condition of the OEO regulatory exemption).
Public payment rails can widen access, but they can also compress private platform economics and add pressure onto merchant pricing. For banks, fintechs, and payment providers, the real issue is not only whether public rails expand. It is how pricing design changes volume, margin, and who absorbs the cost.
A charter application signals a potential change in funding and balance sheet strategy for an AI lending platform and it can reshape partner economics for banks and credit unions that currently fund originations.
This is more than a weak quarter. It puts credit quality, funding resilience, and covenant headroom back at the center of the non prime lending story, which matters for alt lenders, securitization partners, credit investors, and fintechs selling underwriting, servicing, collections, and portfolio monitoring tools into the consumer lending stack.
This matters for brokers, carriers, and digital asset clients because premium payments are a treasury workflow. Once stablecoins clear premiums across real counterparties, buyers and carriers will ask harder questions about controls, reconciliation, and how funds move from premium collection to coverage without losing traceability.
This roadmap puts Europe closer to a tokenised market structure built around central bank money rather than private settlement workarounds. It matters for banks, FMIs, tokenisation platforms, and securities infrastructure teams because the market is now moving from exploratory work toward live design choices on standards, networks, and governance.
This opens a cleaner path for brokers and institutional desks that want crypto execution without rebuilding their stack around proprietary APIs. Once crypto routing uses the same FIX plumbing as other asset classes, firms will put more weight on consistent controls, audit trails, and operational readiness across both traditional and digital venues.
Payment networks are scaling distribution and wallet reach. Tokenized market structure is moving closer to institutional use. Canada’s NSF fee cap also cuts into a legacy bank revenue line and raises the value of tools that help customers avoid failed payments. The strongest fintechs and financial institutions are combining regulatory discipline, strong rails, and practical financial workflows that reduce friction for users.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 11, 2026 | NCFA Fintech Insight | Capital Markets Infrastructure
On March 11 2026, the European Central Bank released the Appia roadmap for Europe’s tokenised finance. The plan runs through 2028 and sets out how the Eurosystem will explore tokenized wholesale financial markets while keeping central bank money at the center of settlement. The ECB says Pontes, a near term interoperability layer, is expected to launch in the third quarter of 2026, while Appia will guide the longer term design of a more integrated tokenized financial ecosystem. While Europe is still studying the final model, the roadmap highlights that ECB is treating tokenization as a market infrastructure question.
The ECB is working in two stages. Pontes is the near term step. The Eurosystem’s DLT settlement page says Pontes is designed to connect distributed ledger platforms to existing Eurosystem settlement services so euro transactions on those platforms can settle in central bank money. The ECB has said Pontes is expected to launch in Q3 2026.
Appia is the longer term view. The ECB says it will explore how a broader tokenized financial ecosystem could develop over time, including questions around architecture, governance, standards, and integration. In other words, Pontes is addressing immediate settlement demand, while Appia looks at where wholesale tokenized finance may go next.
The roadmap focuses on wholesale financial markets, not everyday consumer payments. The money used in these systems would move between regulated financial institutions such as banks, central counterparties, and settlement providers.
This is an important distinction because retail CBDC proposals raise questions about public accounts, privacy, and how people use digital money day to day. The ECB roadmap is different. It is about how tokenized securities, deposits, and other financial assets could settle safely between institutions using tokenized central bank money.
It's a wholesale CBDC model that moves central bank money on distributed ledger infrastructure. The goal is to modernize market infrastructure, not replace cash or consumer bank accounts.
Tokenization allows financial instruments such as bonds, funds, deposits, and collateral to exist as programmable digital representations on distributed ledgers. That can reduce reconciliation steps and shorten settlement chains. But tokenized markets still need a settlement asset that participants trust.
The ECB is making clear that it wants central bank money to remain that anchor. That is a big difference from models that rely mainly on private stablecoins or commercial bank liabilities. Central bank money carries the lowest credit risk in the system because it is a direct claim on the central bank itself.
The ECB’s Appia overview says the initiative is the cornerstone of the Eurosystem strategy to provide central bank money within tokenized wholesale financial markets. It also says tokenized central bank money under Appia would go beyond the interoperability model delivered by Pontes and would be more integrated into a wider new financial ecosystem.
Europe is entering a wider global race around tokenized market infrastructure. The BIS Project Agorá is exploring how tokenized commercial bank money and tokenized wholesale central bank money could work together on a common digital payments platform. The BIS says that work is aimed at improving cross border payments while keeping central banks at the core of final settlement.
Hong Kong is also moving quickly. The HKMA’s November 2025 Project Ensemble update says its pilot environment will be progressively enhanced through 2026 to support settlement in tokenized central bank money on a 24/7 basis (see Standard Chartered CEO Backs Tokenized Finance in Hong Kong). The HKMA has also used tokenized bond issuance, including HK$800M in tokenised green bonds in 2023 and about HK$6B in 2024.
That means the ECB is joining a growing group of major institutions that now see tokenized settlement as a serious part of future market design.
As NCFA recently noted in its analysis of how tokenized infrastructure is changing market operations, Canada has already taken early steps through stablecoin policy work, open banking progress without a confirmed implementation date, and payment modernization efforts. But the foundations for tokenized markets are still incomplete. Canada’s Real Time Rail is not yet live and is expected after 2026. Canada also still needs clearer legal recognition of digital ledger registers for securities, stronger real time settlement across institutions, and digital identity standards that work across ledgers while supporting KYC and AML requirements.
Canada has strong institutions and credible capital markets, but it doesn't yet appear to have a public multi year wholesale tokenized settlement roadmap comparable to Appia. If other jurisdictions define the standards and operating models first, Canadian firms may end up adapting to systems built eleswhere.
Pontes is expected in 2026. Appia runs through 2028. Those dates don't automatically mean Europe has committed to one final settlement model today. However they do mean that a major central bank is now putting dates, structure, and policy intent around tokenized wholesale finance market infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 12, 2026 | NCFA Fintech Market Activity | Digital Assets And Payments Compliance
Image: Freepik/rawpixel.com
On Mar 11 2026, Hong Kong based stablecoin payments firm RedotPay outlined regulatory progress across Canada, the United States, and Argentina as it builds the registrations required to operate in more regulated markets.
The company holds Money Services Business registration with FinCEN in the United States and registration with FINTRAC in Canada (jurisdiction of incorporation is the province of BC), and is pursuing Virtual Asset Service Provider registration in Argentina. These steps allow the firm to work with regulated partners as it expands its stablecoin payment platform.
RedotPay offers a wallet and card based payment system built around stablecoins, allowing users to send digital assets while recipients receive local currency. The company says its platform now serves more than six million users across over 100 countries and processes roughly $10 billion in annualized payment volume.
Stablecoin payment platforms often present themselves as borderless financial infrastructure. In practice, access still depends on local regulatory registration. Firms must establish compliance credentials before banks, card networks, payment processors, and institutional partners will work with them.
In Canada, FINTRAC registration places RedotPay inside Canada's anti money laundering supervision framework. For digital asset payment companies, that registration is typically the first threshold for operating credibly and building domestic partnerships.
Other rules may also apply depending on the product model, including the Bank of Canada’s Retail Payment Activities Act (RPAA) for payment service providers and provincial securities oversight for certain digital asset activities.
Competition in crypto payments is moving away from unique app features alone and toward regulated distribution. Firms that secure registrations across multiple jurisdictions gain earlier access to payment rails, banking relationships, and local partner networks. Firms that delay those steps often remain limited even if their technology works.
It's a dynamic that's becoming more visible as stablecoin payment platforms grow. Compliance infrastructure is no longer just a back office function. It increasingly determines which firms can expand internationally and which ones stall when regulatory scrutiny increases.
As stablecoin payment firms expand globally, will long term advantage come from product features or from who can secure regulated market access first?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 11, 2026 | NCFA Fintech Market Insight | Policy And Regulation And Market Entry

On Feb 26 2026, OSFI announced targeted fast track approvals framework for new applicants seeking to become federally regulated financial institutions. OSFI says the framework will launch in June 2026, and the goal is a quicker, clearer, more predictable approval process for eligible new entrants, without lowering prudential oversight.
The regulator limits the initial scope to two groups. One group is provincial credit unions seeking continuance as a federal credit union. The other group is entities with technologically innovative or emerging banking models, including fintechs and crypto asset custodians, that seek to incorporate as a bank or a federally regulated trust and loan company.
The framework will use right sized, risk based prudential reviews and provide clearer guidance on requirements and timelines. OSFI also points to service standards and a planned dashboard to track progress. Also noted is that the application fees won't change, and it will not refund fees if timelines are not met. OSFI says it will use what it learns to refine its processes to support a broader rollout later.
OSFI limits fast track entry to provincial credit unions seeking federal continuance and to innovative or emerging models seeking to incorporate as a bank or a federally regulated trust and loan company. In practical terms, and without naming specific companies, the most likely early candidates are firms that already run bank grade controls and need a federal licence to unlock the next product layer.
That includes fintechs offering primary account style products at scale, custody first firms that want a federal trust model, payments and treasury infrastructure firms expanding into trust style services, and mature wealth or brokerage platforms that want a bank or trust licence to bring more of the stack in house.
Canada’s competition problem is not only about products. It is also about who can enter the system and how predictable the regulatory approval path is. A clear approval path lets founders and boards plan capital, governance, compliance hires, vendor choices, and launch sequencing around a known process. That can reduce the cost of fintechs and challenger banks attempting a regulated model in Canada. Faster entry can increase competition and widen choice for consumers and small businesses, but only if the rules are clear enough that serious teams and investors can commit early.
Crypto custody firms also get a clear signal. By including crypto asset custodians in scope for this initial fast track approval framework, it puts digital asset custody on the list of models OSFI is willing to assess through a defined entry framework.
Having said that, service standards need to execute in real timelines. The dashboards mentioned by OSFI need to publish meaningful progress indicators, not vague stages. The review still needs to be rigorous, but the timeline and progress pathway needs to be legible enough that applicants know what is coming next and when.
If OSFI delivers a faster and more predictable regulatory entry approval framework without lowering the bar, which new models actually enter first, fintech banks, federal credit unions, or crypto custodians?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 9, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation

Image: Unsplash/J K
On March 9 2026, the U.S. Treasury released a report to Congress on innovative technologies to counter illicit finance involving digital assets under the GENIUS Act. Treasury says successful monthly transactions on public blockchains reached 3.8 billion in early 2025, up 96% year over year. Treasury also reviewed more than 220 public comments while preparing the report. Against that backdrop, the report goes on the record to say crypto mixers can support laundering and sanctions evasion, but they can also serve legitimate privacy needs on public blockchains.
Treasury doesn't overlook the enforcement case against cyrpto mixers, saying criminals commonly use mixing, bridging, and swapping to obscure transaction trails and frustrate investigations. Treasury links these techniques to ransomware groups, darknet markets, sanctions evasion schemes, and DPRK cyber actors. The scale of harm remains large.
Victims reported more than $9 billion in digital asset related fraud to the FBI in 2024, including $5.8 billion tied to digital asset investment schemes, up 47% from the prior year. Treasury also says DPRK cybercriminals stole at least $2.8 billion in digital assets from January 2024 to September 2025, including a $1.5 billion theft in February 2025 that Treasury describes as the largest digital asset heist to date.
The report states that lawful users may use mixers to enable financial privacy when transacting through public blockchains. Treasury gives practical examples. Individuals may want to protect sensitive information such as personal wealth, business payments, charitable donations, or consumer spending patterns from appearing on public ledgers.
That statement changes the tone of the policy debate. The question is no longer whether mixers exist only for criminals. The policy challenge is whether privacy tools can operate with sufficient accountability, recordkeeping, and supervision inside the financial system.
Treasury also notes that custodial mixers that accept and transmit value must register with FinCEN as money services businesses, maintain records, and file suspicious activity reports. When compliant, these services can provide customer identities, off chain transaction data, and behavioural information to regulators or law enforcement.
Treasury also describes how mixers interact with broader digital asset infrastructure. Stablecoins frequently appear in laundering chains when illicit actors transfer assets across blockchains or prepare to convert digital assets into fiat.
Since May 2020, Treasury says more than $37.4 billion in withdrawals from over 50 bridges were denominated in the two largest stablecoins by market capitalization. During the same period those bridges received about $1.6 billion in deposits originating from mixing services. Treasury says more than $900 million of those deposits flowed into one specific bridge that faced scrutiny for DPRK linked laundering (North Korea state-sponsored).
A large part of the report focuses on the technologies Treasury believes financial institutions should use to strengthen anti money laundering and sanctions compliance programs. Treasury highlights four priority tools: artificial intelligence, digital identity, blockchain analytics, and application programming interfaces.
Treasury cites FinCEN analysis showing about 1.6 million identity related BSA reports in 2021, equal to 42% of reports filed that year and tied to $212 billion in suspicious activity. Treasury says AI can help institutions analyze large datasets and reduce false positives, digital identity systems can strengthen customer onboarding and fraud detection, blockchain analytics tools can trace wallet activity across networks, and APIs can improve secure monitoring and information sharing.
The next evolution of digital asset infrastructure will likely reward firms at the forefront of regulatory accountability that can distinguish lawful privacy from criminal abuse, strengthen identity and monitoring controls, and provide institutions with faster and more accurate compliance tools.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016