




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


March 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026).
Regulators are aligning competition rules and data protection in a way that directly affects how AI systems access, process, and govern data. For fintechs and financial institutions building on platform infrastructure, data strategy, consent design, and compliance architecture are becoming tightly coupled decisions.
Large platforms, AI firms, fintechs, and financial institutions that depend on platform distribution, data access, identity layers, or app infrastructure face a more active compliance environment. Platform terms, profiling practices, interoperability rules, and access conditions can change through ongoing regulatory review. Firms with high dependency on a small number of gatekeepers face increased operating risk, while firms that diversify distribution, strengthen direct customer relationships, and build adaptable data and compliance architectures will be better positioned.
The next edge will come from firms that can operationalize data standards, identity rails, and compliance workflows across jurisdictions rather than wait for policy intent alone to close the gap.
This deal says scale in cross border payments is moving toward platforms that already combine distribution, compliance support, and endpoint reach. For smaller wallet, remittance, and banking partners, the harder question is no longer whether they can connect. It is whether they still control enough of the customer relationship or economics once a larger stack sits in the middle.
This brings Ripple inside the licensed payments system in Australia. It can handle more of the payment flow itself instead of relying on partners. That includes onboarding, compliance, FX, and payout. For banks and fintechs, this means a digital asset firm can now compete more directly on cross border payments with full regulatory coverage, not just as a crypto overlay.
This impacts payment processors, merchant platforms, and consumer fintechs that want to own checkout and settlement. A payment aggregator license pulls merchant onboarding, refunds, and settlement into one accountable layer, so competitors and partners should expect tighter expectations on merchant screening and operational controls as volumes grow.
This impacts fixed income platforms, treasury and collateral systems, and anyone building workflows that touch Government of Canada collateral. Dealer funding and hedging capacity affects liquidity and trading costs.
This impacts capital markets fintechs that want distribution through regulated channels. When a top tier exchange brand commits to a tokenization partner, procurement and diligence tighten fast. Builders should prepare for deeper questions on governance, surveillance, custody controls, and how tokenized assets move without breaking compliance reporting and investor protections.
This raises the execution standard for digital onboarding, disclosures, promotions, and support flows. For fintechs, good UX is no longer enough on its own. Firms need evidence that customers understand what they are seeing and can act on it without avoidable confusion.
Ottawa is pushing affordability through multiple channels at once, including taxes, housing, and core banking fees. For banks, that puts more pressure on legacy fee revenue and raises the importance of better alerts, cash flow tools, and low cost account design. For fintechs, it strengthens the case for products that help users avoid failed payments, manage short term liquidity, and lower everyday banking friction.
Banks lose part of a high margin penalty fee and face more pressure to compete on better alerts, balance visibility, payment controls, and products that help customers avoid failed payments in the first place. Direct product and revenue implications across consumer banking.
This opens a formal rulemaking lane around one of the fastest growing grey areas in digital markets. It matters for exchanges, brokers, market makers, and fintech platforms. How far regulated market structure will let them scale before they run into tighter product boundaries.
This guidance impacts how Canadian DIY investment platforms can design tools and user experiences. Online brokers and fintech wealth platforms now have clearer room to provide decision support, portfolio models, and guided interfaces, but they must build stronger safeguards to ensure those tools do not cross the line into regulated investment advice (a condition of the OEO regulatory exemption).
Public payment rails can widen access, but they can also compress private platform economics and add pressure onto merchant pricing. For banks, fintechs, and payment providers, the real issue is not only whether public rails expand. It is how pricing design changes volume, margin, and who absorbs the cost.
A charter application signals a potential change in funding and balance sheet strategy for an AI lending platform and it can reshape partner economics for banks and credit unions that currently fund originations.
This is more than a weak quarter. It puts credit quality, funding resilience, and covenant headroom back at the center of the non prime lending story, which matters for alt lenders, securitization partners, credit investors, and fintechs selling underwriting, servicing, collections, and portfolio monitoring tools into the consumer lending stack.
This matters for brokers, carriers, and digital asset clients because premium payments are a treasury workflow. Once stablecoins clear premiums across real counterparties, buyers and carriers will ask harder questions about controls, reconciliation, and how funds move from premium collection to coverage without losing traceability.
This roadmap puts Europe closer to a tokenised market structure built around central bank money rather than private settlement workarounds. It matters for banks, FMIs, tokenisation platforms, and securities infrastructure teams because the market is now moving from exploratory work toward live design choices on standards, networks, and governance.
This opens a cleaner path for brokers and institutional desks that want crypto execution without rebuilding their stack around proprietary APIs. Once crypto routing uses the same FIX plumbing as other asset classes, firms will put more weight on consistent controls, audit trails, and operational readiness across both traditional and digital venues.
Payment networks are scaling distribution and wallet reach. Tokenized market structure is moving closer to institutional use. Canada’s NSF fee cap also cuts into a legacy bank revenue line and raises the value of tools that help customers avoid failed payments. The strongest fintechs and financial institutions are combining regulatory discipline, strong rails, and practical financial workflows that reduce friction for users.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 10, 2026 | NCFA Market Activity | Alternative Finance And Consumer Lending
On March 10 2026, Canadaian non bank, non prime consumer lender goeasy Ltd. released a financial and operational update ahead of its fourth quarter earnings report and said it expects about $178M in incremental charge offs tied mainly to its LendCare business. The company said total net charge offs for the quarter rise to about $331M and its allowance for credit losses increases by about $86M. goeasy share price tanked over 40% on the news.
The disclosure was significant enough that CIRO imposed a temporary trading halt pending the news release.
goeasy said its full year 2025 net charge off rate is about 12.9% and now expects that figure to rise into the mid teens in 2026 before improving in 2027. The company also warned the deterioration could create pressure under certain financing covenants and said it has entered into an accommodation agreement with lenders while negotiating amendments to its credit facilities.
goeasy withdrew its previously issued fourth quarter 2025 outlook and its three year forecast while management reassesses portfolio performance and the impact on the business. The company also said it will suspend its dividend and halt share buybacks under its normal course issuer bid in order to preserve capital while it works through higher losses and funding discussions.
Although this is a specific company event, the implications are beyond one issuer. goeasy is one of the most visible publicly listed companies in Canada’s alternative lending market, and developments at a large lender often influence how investors, warehouse lenders, and institutional funding partners view risk across the wider non bank consumer credit sector.
When a lender withdraws forecasts, increases loss reserves, and begins negotiating covenant relief, the market typically responds swiftly. Funding partners may tighten terms, demand more protection, or become more selective about similar credit exposures. It doesn't mean every lender faces the same situation, but it makes investors and new capital cautious.
For Canadian fintech lenders and point of sale financing platforms, it means a tighter credit cycle that will impact underwriting discipline, funding flexibility, and covenant headroom as much as origination growth. Companies that rely on institutional funding or structured facilities need clear visibility into portfolio performance and the ability to react quickly if delinquencies or losses begin to rise.
This update does not change financial infrastructure or market rules on its own, but it does highlight how quickly stress in non prime consumer lending can influence investor sentiment and capital availability across the sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 9, 2026 | NCFA Fintech Market Insight | Digital Assets And Policy And Regulation

Image: Unsplash/J K
On March 9 2026, the U.S. Treasury released a report to Congress on innovative technologies to counter illicit finance involving digital assets under the GENIUS Act. Treasury says successful monthly transactions on public blockchains reached 3.8 billion in early 2025, up 96% year over year. Treasury also reviewed more than 220 public comments while preparing the report. Against that backdrop, the report goes on the record to say crypto mixers can support laundering and sanctions evasion, but they can also serve legitimate privacy needs on public blockchains.
Treasury doesn't overlook the enforcement case against cyrpto mixers, saying criminals commonly use mixing, bridging, and swapping to obscure transaction trails and frustrate investigations. Treasury links these techniques to ransomware groups, darknet markets, sanctions evasion schemes, and DPRK cyber actors. The scale of harm remains large.
Victims reported more than $9 billion in digital asset related fraud to the FBI in 2024, including $5.8 billion tied to digital asset investment schemes, up 47% from the prior year. Treasury also says DPRK cybercriminals stole at least $2.8 billion in digital assets from January 2024 to September 2025, including a $1.5 billion theft in February 2025 that Treasury describes as the largest digital asset heist to date.
The report states that lawful users may use mixers to enable financial privacy when transacting through public blockchains. Treasury gives practical examples. Individuals may want to protect sensitive information such as personal wealth, business payments, charitable donations, or consumer spending patterns from appearing on public ledgers.
That statement changes the tone of the policy debate. The question is no longer whether mixers exist only for criminals. The policy challenge is whether privacy tools can operate with sufficient accountability, recordkeeping, and supervision inside the financial system.
Treasury also notes that custodial mixers that accept and transmit value must register with FinCEN as money services businesses, maintain records, and file suspicious activity reports. When compliant, these services can provide customer identities, off chain transaction data, and behavioural information to regulators or law enforcement.
Treasury also describes how mixers interact with broader digital asset infrastructure. Stablecoins frequently appear in laundering chains when illicit actors transfer assets across blockchains or prepare to convert digital assets into fiat.
Since May 2020, Treasury says more than $37.4 billion in withdrawals from over 50 bridges were denominated in the two largest stablecoins by market capitalization. During the same period those bridges received about $1.6 billion in deposits originating from mixing services. Treasury says more than $900 million of those deposits flowed into one specific bridge that faced scrutiny for DPRK linked laundering (North Korea state-sponsored).
A large part of the report focuses on the technologies Treasury believes financial institutions should use to strengthen anti money laundering and sanctions compliance programs. Treasury highlights four priority tools: artificial intelligence, digital identity, blockchain analytics, and application programming interfaces.
Treasury cites FinCEN analysis showing about 1.6 million identity related BSA reports in 2021, equal to 42% of reports filed that year and tied to $212 billion in suspicious activity. Treasury says AI can help institutions analyze large datasets and reduce false positives, digital identity systems can strengthen customer onboarding and fraud detection, blockchain analytics tools can trace wallet activity across networks, and APIs can improve secure monitoring and information sharing.
The next evolution of digital asset infrastructure will likely reward firms at the forefront of regulatory accountability that can distinguish lawful privacy from criminal abuse, strengthen identity and monitoring controls, and provide institutions with faster and more accurate compliance tools.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 8, 2026 | NCFA Fintech Market Activity | Digital Banking And Data Governance
On Mar 7 2026, The Guardian posted that UK challenger bank Monzo is dealing with backlash from Monzo’s Year in review spending recap, a trust issue created by automated personalization. A customer escalated a complaint to the UK Financial Ombudsman Service after the AI recap used mocking language about food spending. The simple truth is banks can use AI to summarize spending, but it should avoid a tone that feels like judgement.
Two examples of the AI lines personalization that didn't sit well with customers after letting AI analyze their spending habits:
“Mainly, you fast fooded.”
“You like your banquets beige and boxed up.”
The customer described the wording as humiliating. The story also makes clear why tone can hurt even when the data is accurate. Spend patterns can reflect disability, illness, caregiving, job loss, stress, or crisis routines. A system that only sees categories and merchants can't understand the exact context. When it adds snark, it fills that context with judgement.
Monzo’s response was mixed. They didn't accept the complaint, but they still admitted the tone was wrong for that customer and apologized, and offered £20 as a goodwill payment. That mix reduces immediate heat, but it does not fix the underlying product risk.
“I recognise that in your case, the automated and standardised language we used was inappropriate and caused genuine upset.”
The primary lesson here is that personal spending data is too sensitive for automated copy that sounds like judgement.
Opt out doesn't fix a bad default. Banks and fintechs need controls that block mockery, shame, and moral scoring in any automated spending narrative. Teams also need to test outputs against vulnerable scenarios and worst case interpretations, not just average reactions.
Complaint handling needs a fast way to learn from these mistakes and force product improvements. A goodwill payment helps one customer, but it does not change the system. Banks and fintechs need escalation that can remove harmful language templates quickly, suppress outputs for affected customers, and pause the feature when tone crosses the line.
Automated spending recaps will continue to grow because customers want clarity and progress tracking. Banks and fintechs should keep recaps factual, let customers choose tone, and treat trust as a product requirement. When a bank speaks about a customer’s money, it needs to speak with care.
When a bank turns transaction history into a narrative, what standard should govern tone, testing for vulnerable scenarios, and escalation when a customer reports harm?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 6, 2026 | NCFA Fintech Market Activity | Consumer Credit And Identity And Data Governance
Image: Freepik/fabrikasimf
Per an Investment Executive article, on February 22, 2026, a proposed class action application was filed in Quebec alleging that repeated access to a consumer credit file data occurred without authorization through a third party platform account that the applicant says he never opened or approved.
The application says an unauthorized party created an account on Borrowell and used it to access the applicant’s Equifax credit file. It alleges the matching and authentication process accepted partial, inaccurate, or outdated personal information without enhanced identity verification and without effective controls to detect inconsistencies.
The filing describes a series of inquiries and access events through Borrowell at almost weekly frequency over roughly four months. It alleges the access did not affect the applicant’s credit score, but harmful with unauthorized disclosure of highly sensitive personal and financial information.
The application also alleges that Equifax uses a similar access model with multiple third party partner platforms in Canada, and it names examples including KOHO Financial Inc., Credit Karma Canada, Mogo Inc., and Chexy, among others.
This is a market structure issue inside consumer credit. Credit file access is part of many modern onboarding and underwriting flows across lending, banking, payments, and personal finance apps. If a court accepts the argument that matching and authentication rules allowed unauthorized access through partner channels, it will raise scrutiny for how bureaus and partner platforms handle identity verification, monitoring, and anomaly detection for credit file requests.
Both the credit bureau and third party partners need tighter identity checks, clearer consent proof, and better alerts for repeat access. Canadian regulators already expect financial institutions to manage these risks. For example, OSFI’s Third Party Risk Management Guideline B-10 requires federally regulated institutions to remain accountable for services delivered through partners and to maintain strong due diligence, monitoring, and control frameworks across the full lifecycle of third party relationships.
If partner platforms can trigger credit file access using partial or outdated identifiers, what standard should govern consent checks, anomaly detection, and step up verification for repeat inquiries?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 5, 2026 | NCFA Feature | Capital Markets And Policy And Regulation
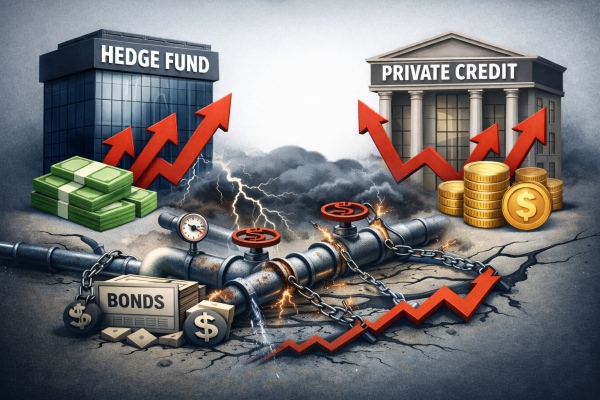
On March 4 2026, Bank of Canada Governor Tiff Macklem discussed how non bank finance can amplify stress in debt markets during remarks at the Global Risk Institute in Toronto. He pointed at two pressure points that matter for Canada right now:
Macklem puts a clear number on hedge fund demand in Canada:
"In Canada, they purchase up to 50% of Government of Canada bonds sold at auction and account for a big portion of secondary market trading.”
Hedge funds aren't just active in Canada. Similar patterns show up across many major economies. Hedge funds now hold a significant share of government debt outside central banks and large institutions. When government bond markets become unstable, the effects spread quickly. Mortgage rates, business loans, and corporate borrowing costs all move with government bond yields, so shifts in that market ripple through the entire economy.
The Bank highlights the repo market because repo borrowing funds many leveraged bond trades. A repo (repurchase agreement), works like a very short term loan. An investor borrows cash and posts government bonds as collateral, then agrees to buy those bonds back a day or a few days later.
Macklem says many hedge fund bond positions rely on this type of borrowing and are often highly leveraged. The structure makes markets sensitive to sudden changes in funding conditions.
He explains that “globally, about half have an overnight maturity. And haircuts are low zero or negative more than 80% of the time.” If lenders raise collateral requirements or reduce lending, investors may need to sell bonds quickly to reduce leverage.
When several large investors unwind positions at the same time, liquidity can vanish and prices can fall sharply. Macklem points to past episodes where this dynamic played out, including the global dash for cash at the start of the pandemic, the United Kingdom gilt crisis in 2022, and stress in the United States Treasury market in 2023.
Macklem also focuses on private credit because transparency is more difficult than in public markets:
“The opacity of private credit means investors may not have enough information about the quality of loans held in their funds.”
If defaults rise and investors rush for exits, he warns that the strain can spill into public credit markets. Canada connects to this risk because Canadian institutions invest in private credit globally, and funding links can pull stress back into the regulated system through liquidity needs and cross border channels.
The Bank of Canada is also changing how it plans to conduct its repo transactions. In a market notice, the Bank says it will join the Canadian Collateral Management Service tri party platform for its domestic repo operations by early 2027. CCMS is a market utility launched by TMX Group and Clearstream that helps participants move collateral, manage substitutions, and automate settlement for repo trades.
The Bank also says it intends to clear its repo operations through the Canadian Derivatives Clearing Corporation once TMX completes upgrades to expand central clearing services. CDCC acts as a central counterparty that guarantees settlement if one side of a trade fails.
The goal is to support stronger collateral management, reduce counterparty risk, and encourage broader use of modern repo infrastructure in Canada.
More lending and market activity now happens via non-bank firms who often use short term funding that can tighten quickly, not just traditional banks. When that happens, pressure in debt markets can build fast. Canadian institutions need better visibility into funding conditions, leverage, and collateral movement across markets. Fintech companies that help banks monitor liquidity, collateral, and repo exposures in near real time can fill an important gap.
At the same time, stronger market infrastructure matters for Canada’s competitiveness. Investors and dealers gravitate to markets that settle trades smoothly and manage collateral efficiently, especially during periods of stress.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016