




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 25, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
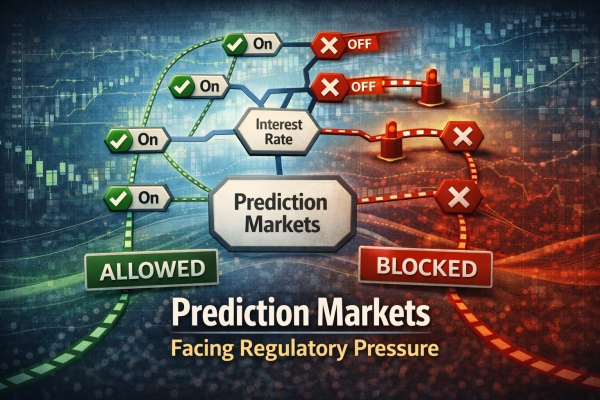
Sports volume built the business. Now rules, surveillance, and product limits will decide who lasts. On March 23, 2026, a bipartisan Senate bill moved to ban sports and casino style contracts on CFTC registered prediction market venues. The Senate release said a March Madness winner contract had already passed $100M in trading volume and that Super Bowl prediction market volume topped $1B in 2026.
Those numbers explain why prediction markets are now under direct pressure from lawmakers. Prediction markets are no longer fringe. They now sit in a fight over who regulates them, which contracts stay allowed, and whether the business still works under tighter rules.
Sports helped prediction markets reach a wide audience fast, but that same growth put them in direct competition with state regulated sportsbooks and tribal gaming interests. The Prediction Market Senate bill to ban sports contracts is aimed straight at that overlap. It would prohibit any CFTC registered entity from listing contracts that closely resemble a sports bet or a casino style game. If it advances, sports contracts would be the first part of the business to take a hit. That in itself wouldn't kill prediction markets, but it would force a reset around contracts that look more like economic, financial, or commercial forecasting and less like entertainment wagering.
Sports contracts brought scale, attention, and league partnerships. NCFA looked at that earlier when the NHL partnered with Kalshi and Polymarket. Sports now look like the part of the business most likely to trigger a stronger federal and state response.
Polymarket and Kalshi tightened their controls on the same day. On March 23, Polymarket tightened its market integrity rules across both its DeFi venue and its CFTC regulated US exchange. The updated rules ban trading on stolen confidential information, illegal tips, and outcomes a trader can influence.
Kalshi added candidate and athlete trading bans covering political candidates, athletes, referees, coaches, and team staff, and introduced a whistleblower feature to tighten insider risk controls.
These aren't minor changes. They prove Kalshi and Polymarket understand that insider risk is now a live issue. Prediction markets want to be treated as financial infrastructure, but financial infrastructure has to show it can police insiders, document rules, and respond fast when abuse appears. NCFA covered that tension earlier when prediction markets started pricing geopolitical events.
Canada is taking a narrower approach. The Globe and Mail reported today that Wealthsimple cleared a regulatory hurdle to offer forecast contracts in Canada, but only for economic indicators, financial markets, and climate trends. Sports and election contracts are out. Wealthsimple is the second firm to receive this approval in Canada, after Interactive Brokers Canada.
Interactive Brokers Canada has positioned contracts around government, economic, finance, and climate events, not sports books in a different wrapper. The product is already live in Canada on that basis.
Wealthsimple now brings local retail distribution, stronger brand reach, and a better chance of testing whether forecast contracts can find a market here without leaning on the sports volume that pushed the US fight into the open.
Can a prediction market still grow once sports contracts face a ban, insider screening gets tighter, and compliance costs rise? Some firms may adapt by leaning into macro, rates, inflation, climate, earnings, and other information markets. Others may find that the most profitable contracts were also the ones most likely to trigger a crackdown.
The CFTC is also reviewing the rules. On March 12 2026, the CFTC opened an Advance Notice of Proposed Rulemaking on prediction markets and asked for public comment on which event contracts may be contrary to the public interest, how current rules apply, and what changes may be needed. That means this fight is not limited to one Senate bill or one week of headlines. The federal rule in the U.S. is now under review.
For Canadian dealers, fintechs, and market operators, there is room to build forecast products here, but the lane is narrower than in the US.
Prediction markets already proved they can attract users and volume. The next test is whether prediction markets can still grow once product limits tighten, regulators draw a harder line around what is allowed, and compliance demands rise.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 24, 2026 | NCFA Feature | AI Finance And Data Governance
On Mar 23 2026, OSFI and the Global Risk Institute published the FIFAI II final report based on four workshops held between May and November 2025. More than 170 participants took part across banks, insurers, asset managers, fintechs, vendors, regulators, academics, and consumer voices.
The report confirms that AI adoption is here, citing 72% AI use at work in financial services and 75% organizational support for AI. While AI is already in use. The real issue is what still limits its use in regulated decisions and customer outcomes.
The series covered four areas that affect operational, prudential, consumer, and system-wide risk at the same time. Full report and framework: FIFAI II final report and AGILE framework PDF
One of the clearest takeaways is that AI will not spread across finance at the same speed. The first gains will come in internal functions such as fraud detection, surveillance, reporting, cyber defence, and operations. Those areas already have strong data, measurable outputs, and clearer accountability.
Customer-facing decisions are different. Underwriting, advice, product recommendations, and self-serve tools carry more pressure around explainability, fairness, consent, and complaints handling.
AI powered Canadian finance will likely grow faster in control functions than in customer-facing decisions.
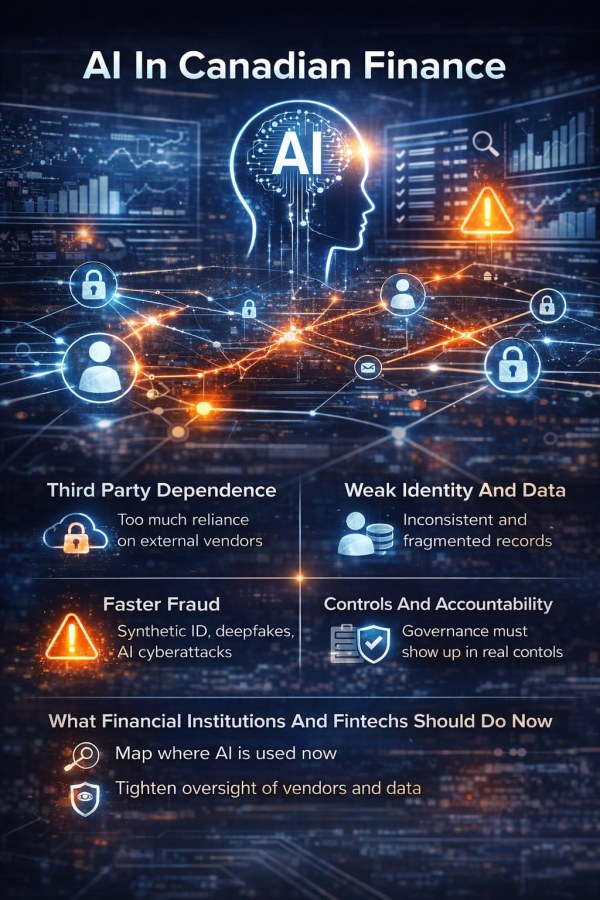
The report treats third party AI as more than a procurement issue. It highlights growing dependence on external providers for models, infrastructure, and data, along with limited visibility into how those systems work and who sits behind them.
It's important because a failure, outage, or change in access at one provider can affect more than one function at the same time. Fraud controls, underwriting tools, customer service, and risk monitoring can all be exposed together. The financial stability workshop adds to that concern by linking third party dependency to concentration and system level risk.
Banks, insurers, and fintechs will need stronger oversight of models and providers, better audit access, tested fallback plans, and clearer visibility into the wider supply chain behind key AI services.
AI is improving both offence and defence. The final report points to synthetic identity, deepfakes, voice spoofing, AI assisted cyberattacks, fraud as a service, and disinformation. It notes a sharp rise in deepfake attacks and growing concern about voice verification as AI voice cloning improves.
This reality changes the operating environment. Static controls lose value faster when attack tools get cheaper, stronger, and easier to use. Manual review and occasional rule updates will not be enough. Firms will need faster detection, stronger identity controls, better information sharing, and systems that can adjust while attacks are happening.
Data problems come up across the whole series, but the larger issue is bigger than data quality alone. Weak identity and fragmented data still limit how far AI can go in regulated finance. The report points to inconsistent data, incomplete records, fragmented platforms, offshore storage concerns, and weak data lineage as barriers to both efficiency and safety.
The report doesn't mince words on identity. Canada still doesn't have a widely adopted secure digital identity layer. That leaves onboarding, authentication, consumer channels, remote work, and agent based systems more exposed than they should be. If identity and data remains weak, AI will keep working best in narrower internal use cases and face more limits in customer facing execution.
The final report introduces the AGILE framework as part of its overall findings, which stands for Awareness, Guardrails, Innovation, Learning, and Ecosystem Resiliency. The framework calls for stronger governance and oversight, stronger data and risk controls, continued investment in technology and talent, and deeper public private collaboration.
AI oversight cannot remain just at the strategy level. If AI is used in lending, fraud, underwriting, complaints, or customer recommendations, governance has to show up in controls, evidence, escalation, and accountability. In regulated finance, that's what turns AI use from experimentation into something firms can defend and scale.
The workshop series points to a practical sequence:
First, identify where AI already impacts decisions and controls.
Second, separate the use cases that can scale now from the ones that still need stronger explainability and customer safeguards.
Third, tighten vendor oversight before dependency grows further.
Fourth, invest more in identity, data lineage (origin and how it's used and updated), and real time fraud controls.
Fifth, show boards stronger evidence instead of high level claims and broad assurance language.
The report also carries a warning worth taking seriously. Firms that move too slowly can fall behind on productivity, resilience, and customer expectations while still facing external AI enabled threats. One participant line stands out: “The biggest risk is not doing enough.”
Canada’s national AI strategy work has focused heavily on trust, safety, and responsible adoption. That is necessary, but this workshop series adds something more useful for operators. It shows where AI use slows once it enters regulated finance: concentrated provider risk, weak identity, fragmented data, explainability pressure, fraud risk, and unclear accountability.
There's a call to action policy lesson here too. Canada doesn't just need AI ambition and adoption. It needs stronger execution layers around Digital ID, data governance, third party oversight, and information sharing if it wants regulated financial AI to scale beyond contained pilots.
The OSFI and GRI workshop series is useful because it takes a holistic approach to identifying and adapting to AI risks in finance. AI is already inside financial systems. The advantage now goes to firms that can prove control, trust, and accountability in live decisions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 23, 2026 | NCFA Insight | AI Governance And Data Sovereignty
On March 22, 2026, the Guardian reported that UK Financial Conduct Authority has hired US firm Palantir for a three month trial worth more than £30,000 a week to analyze its intelligence data lake. The reported scope includes highly sensitive material tied to fraud, money laundering, insider trading, case files, suspected wrongdoing reports, and consumer complaints. It's a significant AI governance and privacy risk given that the FCA regulates around 42,000 businesses across the UK's financial ecosystem.
Palantir is a US based data and analytics company that builds software platforms used by governments, intelligence agencies, and financial institutions to organize and analyze large, sensitive datasets. Its systems combine data integration with artificial intelligence and machine learning tools, which allows users to run complex analysis across entire data environments. That capability makes it effective for regulatory and investigative work, and also places it at the centre of ongoing concerns about data access, oversight, and reliance on external vendors in critical public systems.
The FCA has stated that Palantir acts only as a processor, the data stays hosted in the UK, the data cannot be used to train Palantir systems, encryption keys for the most sensitive files stay with the FCA, and the data must be destroyed at the end of the contract. These are all good safeguards but that doesn't end the debate.
The real question is whether a regulator should give a foreign AI operator working access to one of its most sensitive data environments.
The FCA wants better tools to detect financial crime across a very large supervisory perimeter. However, the concern is that once a foreign vendor obtains access to a highly sensitive operating environment, the public risk grows beyond just legal ownership of the data. What happens if controls fail beyond what the contract itself governs?
If a system ingests more than expected, if metadata creates a wider intelligence layer than planned, if privileges become too powerful, or if future use expands beyond the original trial, the exposure can widen even when formal safeguards remain in place. While none of this proves failure it does highlight why sensitive AI contracts and said deployments need much closer scrutiny than standard software procurement.
The trial is short, the weekly cost is disclosed in reporting, the data environment is sensitive, and the FCA says it has placed strict limits on processor role, hosting, training use, encryption control, and deletion. A second report on the FCA Planatir deal indicates the trial is designed to test whether advanced analytics an improve fraud detection, AML/KYC procedures, and insider training within the scope of firms the FCA supervised. But most already concur that AI, if given enough data, can perform small miracles compared to current data tools.
So the harder policy question becomes are the current safeguards enough when the downside of failure is so high, and the data risk in question is a primary financial services regulator, and not a low sensitivity pilot?
Many jurisdictions now rely on a small number of leading foreign AI and cloud firms to quickly integrate, operate, and scale advanced systems. Once workflows, analytics, procurement, and staff capability start to rest on a handful of outside platforms, exiting becomes more difficult due to dependence.
A country can keep data local and still lose practical control if key capability depends on foreign firms for models, compute, software layers, and operational support. This is why the question is bigger than privacy alone. It reaches into resilience, sovereignty, and the future of digital public infrastructure.
Europe is addressing this problem with both law and capacity. The EU AI Act already sets binding rules for higher risk AI use, while the EU’s wider strategy ties AI policy to competitiveness and technological sovereignty. The question in Europe is no longer whether to regulate AI. It is how to enforce those rules while building enough domestic capacity to avoid overdependence on foreign providers.
Canada isn't yet at Europe’s stage. Ottawa still leans on privacy law, sector rules, and evolving AI policy rather than a fully enacted economy wide AI framework. It is progressing more directly on capability, though. The Canadian Sovereign AI Compute Strategy makes clear that domestic control over compute and data infrastructure is a matter of national security and economic resilience issue, not only an industry growth objective.
That concern is already visible in Canadian data. In Canada AI Strategy Confronts Capital Flight, federal consultation inputs point to risks around sovereign capital, procurement, domestic IP retention, and keeping more AI value inside Canada. Also, the acceleration of AI deployments is exposing AI Governance Gaps that many legal experts have flagged.
The FCA Planatir contact creates at least five questions Canadian policymakers should ask early.
The AI race isn't just about who deploys and adopts first. It's also about who keeps control over sensitive data, institutional leverage, and critical digital infrastructure while deploying.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 20, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Regulation And Policy, Payments And Market Infrastructure

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026).
This adds a new regulated counterparty node for banks, payment partners, and fintech vendors that use CIRO membership as a gating factor for onboarding, integrations, and supervised operating scope.
This puts fund distribution onchain with rules built into the asset. Transfers can enforce who can hold and trade without separate manual checks. That changes how funds issue, manage investors, and handle transfers. It points to tokenized fund infrastructure moving into live use, not pilots.
This affects crypto trading platforms, market makers, treasury teams, and regulators watching stablecoin market structure in Canada. Lower margin on eligible inventory can improve capital efficiency and balance sheet use, but only inside a tighter control framework. It means regulated treatment of stablecoins is moving deeper into prudential design, not just disclosure and registration.
A core global index now trades outside exchange hours. Price formation can start on crypto venues before futures markets reopen, which puts pressure on where liquidity shows up first. If activity builds on chain, traditional venues risk reacting instead of leading. For brokerages, exchanges, and market infrastructure providers, this is not theoretical. Firms need to decide whether to support 24/7 access, how to manage risk when markets never close, and how to compete with venues that remove time and geographic limits.
Crypto issuers, exchanges, custodians, brokers, investors, and token builders now have a clearer US reference point for token design, disclosures, and jurisdiction planning. The practical implication is significant. Firms exposed to staking, airdrops, wrapped assets, stablecoins, or token distribution models can reassess compliance, product structure, and market access strategy with more precision across SEC and CFTC lines.
This is for banks, lenders, treasury teams, and fintechs that rely on bank balance sheets and bank distribution. Capital rules affect lending capacity, pricing, and risk appetite. A lighter or more targeted framework can change how banks allocate capital and where they are willing to compete.
Banks facing margin pressure, conduct costs, and weak returns are under more pressure to lower their operating base faster. The practical implication for lenders, fintechs, and banking vendors is that AI and automation are moving from pilot projects into cost and staffing decisions. Firms that can automate servicing, operations, and control workflows without weakening customer outcomes or compliance will be in a stronger position.
This gives UK facing fintechs and suppliers a cleaner map of where supervisors focus and where firms should spend compliance and product time. Payments, retail banking, consumer finance, and wholesale market firms can now align internal control roadmaps to sector specific priorities instead of broad portfolio letters, which tightens how boards and senior managers justify investment decisions.
Federal procurement remains difficult for new entrants to access, with complexity and restrictive design favouring repeat suppliers. At the same time, the report outlines clear changes that could open participation, improve competition, and expand access for fintech, govtech, and smaller vendors seeking to sell into government.
China is widening the distribution base for state digital money inside the banking system. Analysts see the bigger role in cross-border settlement and in building a payments channel that's outside dollar-based infrastructure such as SWIFT. China is pushing public digital money deeper into bank distribution while closing space for private stablecoin models.
This expands direct access for credit unions that want to build or buy modern payment capabilities. Credit unions, processors, and fintech partners can now plan for real system participation, not just eligibility on paper.
This is for banks, cross-border payment firms, remittance providers, treasury teams, and stablecoin infrastructure players. Stablecoin payouts are moving closer to standard bank payment flows instead of sitting outside them as a separate integration project. That lowers friction for bank adoption and puts more pressure on legacy cross-border payout models.
Mastercard is building direct control over how funds move between bank accounts and stablecoin systems. That changes routing, pricing, and who captures value in cross border and treasury flows. For fintechs, payment products will increasingly need to support both fiat and digital settlement paths in the same workflow. For banks, this puts more pressure on correspondent banking and other legacy cross border revenue lines.
This changes how investor harm connects to enforcement outcomes. Dealers, registrants, and their vendors now need tighter client records and cleaner evidence trails because the process depends on what harmed investors can prove and what firms can produce quickly and accurately when claims arrive.
This lowers reporting cost and workload for smaller public companies. It changes how often new financial data enters the market. Investors and data platforms will have less frequent updates. For issuers, this improves the economics of staying public. If adopted more widely, it moves Canada toward a lighter reporting model for venture markets.
Industry participants are pushing to remove limits that keep tokenized market infrastructure in pilot mode. That pressure targets how quickly the EU can move from controlled testing toward scalable digital asset markets.
Tokenized securities into the core of exchange trading. They will trade the same way as regular shares, on the same book, with the same symbol and rules. No separate venue, no parallel system. It removes a major barrier with tokenization now aligned with the same clearing, settlement, and surveillance systems as the rest of the market.
A forward flow commitment supports predictable loan takeout capacity, which can stabilize origination volume when bank balance sheets tighten or pricing changes.
Public companies, investors, analysts, and fintech platforms that rely on earnings data will face longer gaps between official disclosures. Less frequent reporting reduces the flow of standardized financial data into the market. Firms that can generate alternative data, continuous signals, and independent performance insight will have an advantage as reliance on scheduled earnings reports declines.
When one of India's largest fintech payments company pauses an IPO, it tells founders, investors, and late stage boards that the public market window remains fragile. That affects valuation expectations, liquidity planning, and timing for other fintech listings.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 20, 2026 | NCFA Market Activity | Quantum Security And Digital Finance
Image: Pixabay/geralt
On Mar 18, 2026, the 2025 ACM A.M. Turing Award recognized Gilles Brassard and Charles H. Bennett for foundational work in quantum information science, including the development of quantum cryptography. The award carries a $1 million prize and marks one of the highest global honours in computing.
Brassard’s work established early methods for secure communication using quantum mechanics, a field now directly tied to the future of encryption. While he didn't develop today’s post quantum standards, his research helped define how information can be secured against quantum-enabled attacks. That body of work went from advanced research to execution in August 2024 when NIST finalized the first post quantum cryptography standards for encryption and digital signatures used across financial systems.
As ACM President Yannis Ioannidis stated:
“Their work is an important foundation for the field of quantum computing and has fundamentally changed how we process, transmit, and secure information.”
Post quantum cryptography (PQC) refers to new encryption methods designed to remain secure even if future quantum computers can break today’s widely used systems today, such as RSA and elliptic curve cryptography that currently protect payments, digital identity, secure messaging, APIs, and financial data.
On Aug 13, 2024, NIST finalized three post quantum cryptography standards and announced that organizations should begin transitioning to them as soon as possible. NIST states these standards support encryption and digital signatures used to secure electronic information, including financial transactions and sensitive data.
NIST also states that no one knows exactly when a cryptographically relevant quantum computer will arrive, but some experts estimate it could be possible in less than 10 years. That uncertainty increases the risk because encrypted data can be collected today and targeted for future decryption under the harvest now, decrypt later threat model.
Canada has already set execution timelines. The Canadian roadmap for post quantum cryptography migration requires departments to begin planning in April 2026, report progress annually, transition high priority systems by the end of 2031, and complete remaining migration by the end of 2035. Canada’s national strategy for quantum communication and cryptography states that advances in quantum computing could undermine current encryption and threaten digital systems and data security.
For financial services, encryption now affects what gets built and what gets bought. Payments, identity, onboarding, APIs, messaging, custody, and long term data all rely on encryption that may need to be replaced or upgraded.
Quantum also reaches into blockchain based finance like stablecoins, tokenized deposits, wallet infrastructure, custody controls, and smart contract connected payment flows all depend on digital signatures and key management. NCFA’s earlier coverage of quantum safe stablecoins points to a market approaching US$250 billion and highlights how quantum safe controls are already being added to stablecoin settlement systems.
Buyers are starting to ask direct questions. Where is encryption used in the product. Which parts rely on current standards. What is the plan to upgrade. These questions and decisions are part of core financial workflows now and show up across payments messaging, identity systems, API access, document signing, custody, and stored data.
Vendors that can clearly show where encryption sits in their systems and how they plan to upgrade it will have an advantage as requirements tighten.
NIST standards are finalized and Canada has set migration timelines starting in April 2026, with high priority systems due by the end of 2031 and full migration by the end of 2035. That puts a clock on encryption used across payments, identity, APIs, messaging, custody, and long term data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 16, 2026 | NCFA Fintech Market Activity | Payments And Market Structure
On Feb 17 2026, a federal securities class action was filed in California against PayPal for allegedly misleading investors about its 2027 targets and the growth outlook for Branded Checkout. The class action was filed following PayPal’s fourth quarter and full year 2025 results published on Feb 3, when the company withdrew its 2027 targets and pointed to weaker than expected Branded Checkout performance.
At PayPal Investor Day 2025, management laid out a plan to accelerate branded total payment volume growth to between 8% and 10% by 2027. When that target was pulled less than a year later, the market reaction was severe. Reuters reported that PayPal stock fell 19% on Feb 3 after weaker 2026 profit guidance, disappointing holiday quarter results, resulted in PayPal appointing a new CEO.
The complaint argues that investors were given an overly optimistic picture of Branded Checkout growth and the path to PayPal’s 2027 financial targets. When management withdrew those targets, the issue changed from execution pressure to credibility pressure. While investors can absorb a difficult quarter, they respond more sharply when a company promotes a long range growth plan and then walks it back before the plan has time to play out.
This is why the lawsuit matters beyond the legal claim itself. A class action can take years. The more immediate issue is whether investors now discount management guidance more heavily than before. Once that happens, the company has to rebuild trust through results, not presentations.
PayPal is trying to defend a core commerce business in one of the most competitive parts of fintech. Stripe, Apple Pay, Adyen, and other platforms keep pushing deeper into merchant checkout and payment orchestration. See NCFA's prior coverage on Stripe's scale and PayPal pressure.
That is why adjacent product moves around stablecoins, merchant tools, and infrastructure aren't the main story right now. Investors are still anchored to checkout adoption, merchant retention, branded payment volume, and margin quality. If the core checkout engine weakens, new initiatives don't offset that on their own.
The next phase is about proof. PayPal needs to show that Branded Checkout can return to steadier growth and that management guidance once again lines up with operating reality. Until then, both legal and market pressures are likely to continue.
When a payments company faces both a securities class action and a sharp stock repricing, what matters more to investors in the end: the lawsuit or whether the core commerce engine still works?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 16, 2026
Over the past decade, alternative finance has transformed the way businesses access capital. Crowdfunding platforms, private lending networks, and merchant cash advance (MCA) providers have created new opportunities for startups and small businesses that may not qualify for traditional bank loans. These financing models emphasize speed, flexibility, and accessibility key advantages that have fueled their rapid growth.
However, the expansion of alternative finance has also introduced new challenges for lenders and investors. One of the most significant risks involves borrower defaults and the complexities associated with recovering outstanding balances. As lending ecosystems evolve, lenders are increasingly recognizing that strong legal recovery strategies are essential for maintaining financial stability and protecting capital investments.
Understanding how recovery planning fits into the broader alternative finance landscape helps lenders respond effectively when repayment issues arise.
Alternative finance has become an important component of the modern financial system. Businesses that need immediate capital often turn to crowdfunding platforms, private lenders, and revenue-based financing models instead of traditional banks. These financing solutions provide faster approval processes and more flexible qualification criteria.
For entrepreneurs and small business owners, these options can be vital for:
Lenders also benefit from
As participation in alternative finance continues to increase, lenders must carefully balance growth with risk management. While underwriting standards and financial due diligence remain important, repayment enforcement and recovery strategies are becoming equally critical for protecting investments.
Every form of alternative finance carries its own set of repayment risks. While many borrowers successfully meet their obligations, economic fluctuations and operational challenges can cause some businesses to fall behind on payments.
Examples include:
These challenges demonstrate why lenders must plan not only for loan origination but also for potential recovery scenarios.
Many lenders focus primarily on borrower screening and credit evaluation when issuing funds. While these steps are essential, they represent only one part of a comprehensive risk management strategy.
Without a clear recovery framework, lenders may face significant obstacles if a borrower stops making payments. Delays in responding to default situations can lead to reduced recovery opportunities, particularly when borrowers begin restructuring operations or transferring assets.
Effective recovery planning allows lenders to respond quickly when warning signs appear. Early intervention may involve renegotiating repayment terms, investigating the borrower’s financial condition, or pursuing structured settlements.
By establishing defined recovery procedures, lenders improve their ability to protect capital while minimizing disruptions to their broader lending portfolios.
When repayment disputes escalate beyond internal collection efforts, legal frameworks play an important role in resolving outstanding obligations. Lenders often rely on legal guidance to evaluate contractual rights, enforce agreements, and pursue appropriate recovery actions.
Attorneys experienced in commercial debt recovery assist lenders by analyzing loan agreements, identifying enforceable provisions, and determining the most effective strategy for resolving disputes. This may include negotiating settlements, investigating debtor financial activity, or initiating litigation when voluntary repayment is no longer possible.
Legal oversight also helps ensure that recovery efforts remain compliant with applicable regulations and contractual requirements. In a rapidly evolving financial environment, maintaining compliance is essential for both lenders and platforms operating within the alternative finance ecosystem.
Not every default situation requires immediate litigation. In many cases, borrowers experiencing temporary financial setbacks may still be willing to cooperate in resolving outstanding obligations.
Negotiation often provides an opportunity for lenders and borrowers to reach mutually beneficial arrangements. Structured repayment plans or settlement agreements can allow borrowers to address their obligations while giving lenders a realistic path toward recovering funds.
However, lenders must also recognize situations where negotiations are unlikely to succeed. When borrowers stop communicating, dispute contractual terms without justification, or begin transferring assets, stronger enforcement measures may become necessary.
A balanced recovery strategy allows lenders to explore cooperative solutions while remaining prepared to escalate matters when required.
As alternative finance continues to evolve, lenders are increasingly adopting more structured approaches to managing repayment risk. Effective recovery frameworks often begin with clearly defined contractual terms that outline repayment obligations and enforcement options.
Monitoring borrower performance is another important component of risk management. Early detection of financial distress can help lenders intervene before repayment problems become severe.
In addition, maintaining access to experienced legal professionals allows lenders to evaluate recovery options quickly when disputes arise. Proactive legal consultation can help identify risks, preserve evidence, and guide lenders through complex enforcement scenarios.
By integrating legal recovery planning into their operational strategies, alternative finance companies can strengthen their ability to manage defaults and maintain financial stability.
Alternative finance has expanded access to capital for businesses across a wide range of industries. Crowdfunding, private lending, and merchant cash advance financing have created new opportunities for entrepreneurs while offering lenders innovative ways to deploy capital.
Yet with these opportunities comes increased exposure to repayment risk. As the industry grows, lenders must adopt comprehensive strategies that address not only underwriting but also recovery and enforcement.
Legal recovery strategies have become an essential component of responsible lending practices in alternative finance. By combining strong contractual frameworks, proactive monitoring, and strategic legal guidance, lenders can better protect their investments and navigate the challenges that arise when borrowers fail to meet their obligations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016