





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Open Banking | Aug 13, 2025

Image: Freepik
FCA Releases Governance Plan for UK’s new Industry-led Open Banking Standards Body
On August 8, 2025, the UK’s Financial Conduct Authority (FCA) published its FS25/4 feedback statement outlining the governance framework for a new Future Entity to oversee the open banking standards in the UK. The plan details how the Future Entity will be funded, governed, and held accountable. It will be industry led and operated, not a government agency, but will function under the FCA’s oversight. For Canada, the model demonstrates how industry expertise can be combined with regulatory accountability to support innovation and trust.
Since 2017, open banking in the UK has been run by Open Banking Limited, a government run entity created by the UK’s Competition and Markets Authority (CMA) to deliver its order requiring the nine largest banks to create interoperable APIs. Known earlier as the Open Banking Implementation Entity (OBIE), it was a time limited role to boost competition in banking, and not designed to be a permanent governance model.
The FCA’s plan replaces OBIE with the Future Entity, which will have a long term, industry wide mandate. This change moves open banking oversight from a CMA specific enforcement body to an independent standards setter governed under the Data (Use and Access) Act 2025. This legal framework means the Future Entity can later expand into open finance and other areas of data portability.
The Future Entity will be a not for profit company limited by guarantee, funded by contributions from its users and beneficiaries including banks, fintechs, and other participants. Its board will be appointed by an independent appointments committee, not directly by the government or the FCA. The FCA will regulate it as an interface body under the Data (Use and Access) Act, but will not manage its day to day operations. This allows industry to lead on technical standards while the FCA can intervene if those standards do not protect consumers or the market.
The governance approach is similar to a self regulatory organisation (SRO). It is run by industry, sets technical and operational API standards, and monitors compliance. Like an SRO, it will send reports to the regulator. The key difference is that the Future Entity will not have enforcement powers. All formal enforcement remains with the FCA. This keeps legal authority with the regulator while allowing the industry to deliver the technical work.
Commercial operators will use the Future Entity’s standards to create products and services to meet interoperability while leaving space for competition and innovation. The Future Entity itself will only operate directly if there is no commercial incentive or there is a proven market failure.
Industry participants are already working on variable recurring payments for uses such as bill payments, which is planned for 2025. The FCA will hold workshops this summer and fall 2025 to finalize operational details, with a full plan expected by the end of the year.
Canada currently has no permanent open banking standards body. The UK approach shows how Canada could move a temporary regulatory order to a more permanent industry led framework without losing accountability or slowing progress.
An industry led and funded non-profit organization, supported by contributions from all users and beneficiaries, can create shared responsibility and boost financial sustainability. With an SRO style approach, industry leads on technical delivery while the regulator retains enforcement powers, can speed innovation while protecting consumers and market stability.
Important to keep the standards setting body separate from commercial operators to streamline interoperability and ensure a level playing field (reducing risk of favouritism towards certain providers). Applying these principles from the start could help Canada avoid disruptive governance changes later and build a system that supports both innovation and public trust. Learn more about Canada's open banking journey.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Banking Policy | Aug 12, 2025
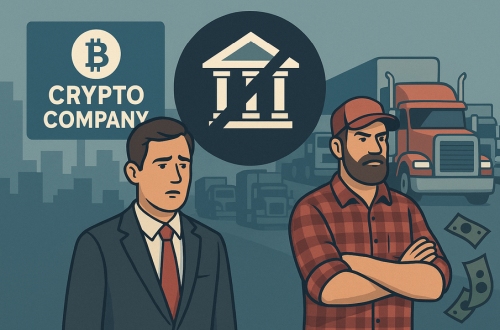
AI generated image of financial exclusion
On August 7, 2025, the White House issued an executive order aimed at ending “politicized or unlawful” debanking. The order directs U.S. regulators to ensure that banks cannot deny service based on political views, religious beliefs, or lawful industry participation, including cryptocurrency. It's the highest profile intervention in U.S. banking in decades and could influence how other jurisdictions handle access to financial services. In Canada, let us not forget the swift debanking of key persons related to the trucker convoy debacle only a few years ago.
Federal banking regulators are to remove “reputational risk” from examination manuals within 180 days. All decisions to deny or close accounts must be based on looking at each customer’s situation on its own, using facts rather than opinions, and assessing real financial and compliance risks instead of relying on broad labels or assumptions.
Regulators must review past cases of account closures or denials within 120 days and take corrective actions, including fines, consent orders, or reinstatement of clients. The Small Business Administration is tasked with urging lenders to reinstate borrowers affected by unlawful debanking. The Office of the Comptroller of the Currency has already updated its materials to comply.
Supporters of the order point to documented cases where lawful businesses, advocacy groups, or individuals lost access to banking without clear justification. Critics argue banks must retain the ability to consider reputational factors when managing compliance obligations under anti-money laundering and counter-terrorist financing laws. A Financial Times analysis notes that crypto companies have been prominent among those alleging discrimination, alongside political organizations and religious nonprofits.
While Canada has not adopted similar measures (yet), there are high profile cases revealing parallels, such as in 2022 when former-PM Trudeau invoked the Emergencies Act to freeze more than 76 bank accounts worth $3.2 million CAD tied to the Freedom Convoy. The Federal Court later ruled this unconstitutional, and the decision is under appeal.
In another reported case, a trucker convoy lawyer said that her Royal Bank of Canada account was closed after small cryptocurrency transactions. Crypto business operators have also described difficulty maintaining accounts, though no comprehensive national data exists.
Canadian banks operate under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act and oversight from the Office of the Superintendent of Financial Institutions. Reputational risk is explicitly considered in supervisory frameworks. Consumers are entitled to open personal bank accounts unless specific conditions apply, and must be given written reasons for refusal under the Access to Basic Banking Services Regulations. Complaints can be escalated to the Financial Consumer Agency of Canada or the Ombudsman for Banking Services and Investments, but there is no mandated systemic review or reinstatement process.
| Feature | United States (Post-EO) | Canada |
| Stance on Debanking | Prohibits ideological or industry-based debanking | No federal rule prohibiting ideological or lawful industry debanking |
| “Reputational Risk” | Removed from regulatory supervision criteria | Integral to OSFI guidance and AML compliance |
| Remediation Process | Regulator-led review, possible fines, reinstatement | Individual complaints through FCAC or Ombuds |
| Transparency | Mandated objective, individualized reasoning for account decisions | Written refusal required, but criteria remain broad |
The U.S. executive order aims to reduce bias in access to financial services which should not be denied based on lawful activity or beliefs. For fintech and crypto entrepreneurs, the change should make banking access more predictable and less influenced by subjective judgments. While Canada’s regulatory approach emphasizes prudence and reputational safeguards, it may need to review these protections that remain at the expense of inclusion and competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Policy | Aug 11, 2025
Image: Freepik
On August 7, 2025, President Trump signed an executive order called, "Democratizing Access to Alternative Assets for 401(k) Investors", directing U.S. regulators to explore ways to allow cryptocurrencies and other alternative assets in defined contribution plans like 401(k)s.
While it doesn't immediately mean that Americans can directly hold crypto investments in their retirement accounts, it does instruct the Department of Labor (DOL), the Securities and Exchange Commission (SEC), and the Treasury to coordinate on new frameworks that could make it possible. If this happens, it will have significant implications for U.S investors but also for fintech innovators and regulators in Canada who are monitoring trends South of the border.
The order requires the DOL to review and update its fiduciary guidance for retirement plan sponsors, with a specific focus on clarifying what due diligence, risk disclosure, and participant education would be required if crypto were included as an option.
It also directs the SEC to consider revisions to certain securities rules, including elements of the accredited investor framework, that could impact the packaging of crypto investment products for retirement plans.
Treasury and related agencies have been tasked with aligning tax, reporting, and compliance rules to avoid conflicting obligations. According to the official fact sheet, the review process is expected to produce proposed rule changes by early 2026.
Advocates explain that opening retirement plans to digital assets could help diversification and align with investor demand, especially among younger savers who already hold crypto in personal accounts.
This change could also create a massive new liquidity channel for the crypto sector while bringing it further into regulated financial infrastructure, as reported by Forbes.
For fintech and crypto innovators, Trump's executive order could blow up the addressable market for crypto retirement products, custody solutions, and participant education tools.
With opportunity comes risks of course. The DOL has previously raised concerns about crypto’s volatility, liquidity constraints, and valuation complexities in retirement plans.
Business Insider reported that plan sponsors could face elevated litigation risks if participant loses are tied to crypto holdings, especially without clear safe harbour protections. Implementation also requires custodians and record keepers to adapt their current systems for daily valuations, liquidity management, and tax reporting.
The U.S. executive order isn't about adding more ETFs to retirement accounts. It opens the door for 401(k) participants to gain exposure to actively managed investment vehicles investing in digital assets and other private market investments, directly within a tax-advantaged plan registered with the government. This could mean direct holdings of Bitcoin or Ethereum, or participation in private crypto funds not listed on public exchanges, if fiduciaries deem them prudent and compliant with ERISA standards.
In Canada, the gap is very real today. Registered plans like RRSPs, RRIFs, TFSAs, and employer pension plans cannot directly hold cryptocurrency. The Canada Revenue Agency’s qualified investment rules prohibit digital assets themselves from being held in registered accounts, whether or not the plan is self-directed. Investors can only gain crypto exposure through qualified investments such as Bitcoin or Ether ETFs listed on a designated stock exchange, or shares of publicly traded crypto companies. Private crypto funds, unlisted trusts, or direct wallet holdings are currently prohibited in all registered accounts.
If the U.S. implements this framework, Canadian retirement plans would be at a competitive disadvantage in offering digital asset investment innovation. For Canadian fintechs, such U.S. policy could create new product development opportunities south of the border, while providing an unprecedented case study for domestic regulators on how to balance investor protection with access to alternative assets.
This latest crypto policy development is another wake-up call and market opportunity for Canadian fintechs and regulators. The next 12 to 18 months will determine whether or not U.S. agencies can produce rules that satisfy both innovation advocates and investor protection, fiduciary watchdogs. If they succeed, Canada’s own retirement savings design could be the next frontier for digital asset integration, and if so, they need to be ready to respond.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Trade Wars | Aug 11, 2025
Image: Freepik AI
Nvidia and AMD have agreed to pay 15% of their revenue from Chinese chip sales to the US government in exchange for export licenses. It follows months of export restrictions on high performing chips like Nvidia's H20 exports to China which were halted earlier this year. Analysts previously warned that curbing H20 chip exports to China could cost up to $8 billion in quarterly sales, while AMD projected a $1.5 billion hit this year from similar restrictions.
The new 15% payment for market access is an unprecedented arrangement, one that highlights the US strategy to assume control over critical AI and semiconductor technologies. It raises significant concerns around global tech trade, supply chains and geopolitical tensions, especially given China's reaction and what's next for tech competition and national security, both taking center stage with a new layer of complexity to the relationships between the US and China.
Canada and other global players will feel the ripple effects of these changes, especially if national security continues to impact global trade policies, which could force countries (and companies) to choose sides in a growing tech war.
The Chinese government has long accused Washington of using technology and trade policy to limit China’s rise in advanced industries. Following the 15% deal, state media criticized the H20 chip as outdated, unsafe, and potentially embedded with backdoor access, showing the growing mistrust of American AI chips while suggesting that the 15% levy is a political tool rather than a commercial safeguard.
As China sees the US moving to limit its access to critical technologies, the message is pretty clear that China is not backing down. They are already investing heavily in building alternative solutions. With companies like Huawei pushing forward on semiconductors and AI chips, China’s push for tech independence is only going to gain speed.
Aug 12 Update: Bloomberg reported that China has issued new guidance advising domestic firms to avoid using Nvidia's H20 chips in certain projects, especially any government use and to prioritize domestic chips wherever possible. This restriction will likely accelerate China's push for self reliance in advanced semiconductor protection, and could reduce demand for Nvidia's products in one of its largest markets.
With China representing 13% of Nvidia’s and 24% of AMD’s total revenue, even a small sales disruption can ripple through suppliers, distributors, and end markets. Semiconductor assembly and packaging hubs in Southeast Asia could also see order volatility if Chinese buyers switch to local alternatives.
The semiconductor industry is already experiencing shortages and supply chain disruptions, especially as the US and China continue to fight for dominance in manufacturing, however with the introduction of a type of financial leverage into the equation, the US could disrupt the delicate balance that keeps the global supply chain moving forward. Global logistics networks could be forced to reconfigure as companies diversify sourcing to hedge against export licensing risks.
This will hit industries reliant on critical AI chips and semiconductors, including everything from automotive and consumer electronics to AI and fintech. For companies in Canada, especially those that have tech partnerships with China, there will be an increasing need to diversify their supply chain sources to avoid disruptions and remain resilient in the face of trade barriers and tariffs.
With this new 15% payment arrangement, technology export controls could evolve into tools of economic statecraft that could be applied in other high-value tech sectors. If adopted more widely, it's a model that could ignite retaliatory tariffs or revenue-sharing requirements from other governments, creating a patchwork of national rules that complicate multinational operations.
Countries like India, which is rapidly scaling its semiconductor sector, are no doubt watching closely to see whether aligning with one tech bloc risks alienating another.
The growing tech and supply chain tensions mean that Canadian companies must carefully position themselves and ensure they adapt to the changing regulatory environment. As both China and the US reconfigure their tech ecosystems, Canada’s role as a tech hub will depend on its ability to stay nimble, maintain access to key technologies and markets, and diversify trade relationships.
For companies, investors, and policymakers, it's a strong reminder that the next front in trade disputes will not be over commodities, but over the intangible building blocks of future economies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
IP Policy and Competition | August 7, 2025
 Image: Freepik
On August 6, 2025, there's an inspiring OpEd in the Financial Post by Jim Hinton and Alexis Conrad, who argued that Canada’s sovereignty is being eroded not by military threats but by the loss of control over its intellectual property. They warn in today's economy it's no longer about "flags, borders, boots on the ground" that define national strength but rather it's the intangibles, such as the source code, algorithms patents, and digital infrastructure that strengthen global leverage and competitiveness, and Canada's current approach to IP is giving it away faster than innovators can build them.
Prime Minister Mark Carney has committed to raising defence spending to $150 billion annually by 2035. But Canada still lacks a framework to retain the intellectual property created through public investment. More than 50 % of university-developed IP ends up in foreign hands, often with no commercial benefit to Canadian firms. Patent office filings show transfers of Canadian-invented technology from Dalhousie to Tesla and from the University of Toronto to Google. Researchers from 50 Canadian universities co-authored work with Chinese military related scientists between 2005 and 2022. Foreign ownership of Canadian inventions and patents has tripled since 2001, now accounting for 56 % of the total.
Canada’s first major contract under the new defence strategy for an arctic radar system valued at $6.5 billion was awarded to an Australian firm. Although there may not be an exact equivalent defence supplier in Canada, there was no public evidence showed that Canadian options were seriously considered. In cleantech, a Burnaby-based carbon capture pioneer Svante is considering a move to the U.S. after being excluded from Canada’s clean tech tax credits. These examples show that public funding and procurement are not aligned with long-term national control.
ElevateIP is a federal initiative created to help startups protect and manage intellectual property, but it lacks key structural elements. It does not require Canadian IP ownership or tie support to procurement or national priorities. It does not coordinate with university tech transfer or public research institutions. It does not track the outcomes of supported IP. As a result, it helps educate founders on IP strategy but offers no protection against IP loss or foreign transfer.
The challenges raised by this article are highly relevant to fintech. Canadian fintech companies often rely on proprietary algorithms, transaction infrastructure, digital identity systems, and embedded financial technologies that qualify as intellectual property. But there is no policy ensuring that publicly supported fintech innovation remains in Canadian control. Many early-stage fintechs are spun out of university labs or supported by public accelerators. Without clear ownership conditions or commercialization requirements, they face the same risks as cleantech and AI firms via acquisition or licensing by larger foreign organizations that ultimately repatriate value outside of Canada.
Fintech IP is also foundational to digital sovereignty. Payments, lending, credit scoring, open banking infrastructure, compliance automation, and digital asset platforms depend on core IP and data control. If these are owned abroad, Canada risks falling behind on financial inclusion, global competitiveness, and platform security.
Public funding that supports fintech innovation without securing ownership or commercialization rights fails to build long term value at home.
Countries like the U.S., South Korea, and Finland have updated their strategies to secure domestic IP and use procurement as a growth lever. Canada still relies on outdated models. Innovation without ownership means financing someone else’s economy. Canada must close the policy gaps between research, funding, procurement, and commercialization if it wants to retain control of its own innovation pipeline and competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Retail AI | July 29, 2025
Image: Freepik AI
Walmart has begun one of the most ambitious AI transformations in the retail industry. Four new “super agents” will replace dozens of separate systems and form the core of Walmart’s technology foundation. On July 24, 2025, the WSJ reported that Walmart is overhauling it's approach to AI by replacing dozens of tools with four super agents, each designed for a specific stakeholder group, including for shoppers, employees, suppliers, and developers. By incorporating AI as tech infrastructure, it moves from several scattered AI pilots into a single foundation to power all customers and internal experiences.
The first of these agents, Sparky, is already live in the Walmart app and helps shoppers with suggestions, reviews and inventory information. Soon it will be able to plan events, reorder products and suggest recipes. Then there's Marty who will assist suppliers with onboarding, analytics and advertising. An Associate agent will guide employees on HR requests, discount cards and access to data. Developer agent will be used internally to create smaller AI tools more quickly using the same platform.
“Suresh Kumar, Walmart’s chief technology and development officer, said the company recognized how confusing it was to have separate agents for different tasks. It became very clear that we could dramatically simplify. If I have an agent that helps you with your payroll and I have a different agent that helps you with identifying merchandising trends, you shouldn’t have to remember that and switch between those two.”
At VentureBeat's Transform 2025, Walmart’s VP of Emerging Technology Desirée Gosby explained that trust is being built directly into the design of every AI system. AI outputs are checked for accuracy, monitored for bias, and corrected using live feedback before being deployed to Walmart’s 255 million weekly customers and millions of associates. Treating reliability as code prevents future failures and keeps every AI agent focused on delivering value.
“We see this as a pretty big inflection point, very similar to the internet. It’s as profound in terms of how we’re actually going to operate, how we actually do work.”
The new system also uses an open standard called Model Context Protocol, introduced by Anthropic in 2024. This protocol connects agents so they can share knowledge, learn from each other and run multi step workflows as if they were a single system. It also prevents Walmart from being tied to one technology vendor. The company has also created senior leadership roles such as Daniel Danker, who now leads AI strategy reporting directly to the CEO.
The new AI model is already showing results according to RetailDive.
Most companies find it hard to move beyond pilot AI projects. Walmart’s blueprint shows that governance and standardization can turn thousands of separate use cases into a structured system that delivers results. From customer shopping to inventory and HR, these super agents are an example of how to make AI work at full scale in a large enterprise by creating a strong AI foundation based on trust and open standards. Surely all other retail giants are watching and licking their chops.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
RegTech | July 28, 2025
AI Image
According to a Guardian report, the United States Department of Government Efficiency known as DOGE has started using a new AI deregulation system to review the entire set of more than 200,000 federal rules and regulations, aiming to deregulate about 50% of the rules by President Trump's first year anniversary or by January 2026.
This massive move is already being trialled at agencies such as the Department of Housing and Urban Development and the Consumer Financial Protection Bureau, and internal reports show that thousands of regulatory sections have already been reviewed, and that 1,083 regulations have already fallen by the waist-side in less than two weeks.
A presentation obtained by Washington Post journalists claims that deregulation could reduce 93% of man hours, and lead to savings that run into the trillions of dollars. While those claims haven't yet been verified by independent auditors and there are already reports from agency employees that the tool has made mistakes by recommending the deletion of rules that are still legally required.
Doge's deregulation effort is of significant importance to Canada where regulatory policy directly affects the cost and pace of doing business. If American regulators follow through on large scale deregulation, fintech companies in that market will face lower compliance costs and potentially operate faster giving them a competitive advantage.
That could make it more attractive for capital and talent to focus on United States markets while Canadian fintech firms may need to operate in an environment of higher regulatory overhead, unless Canadian policy frameworks are modernized in a careful and deliberate way, too. NCFA's view is that this is both a warning and an opportunity.
Legal experts in the United States have pointed out that no regulation can be repealed without following the procedures required by the Administrative Procedure Act. These include public comment periods legal justification and review. Automated recommendations from an artificial intelligence system will still need to go through that process otherwise the decisions may be overturned by courts.
Congressional oversight bodies are also raising questions about whether this tool has been approved for use on government systems and whether its access to federal data could violate privacy or security rules.
While many in industry revel at the thought of deregulation and what it means to their business, there are real risks involved in rushing ahead with automating areas that directly affect public safety and investor protection, so human oversight is still strongly advised.
Artificial intelligence is not just being used to more efficiently process data but to influence the rules in which financial markets operate. It raises the stakes and can be a potential game changer for anyone or organization that depends on stable and predictable regulation.
"While fewer rules can sometimes mean faster innovation, such sudden and large scale deregulation can also remove guardrails that protect consumers and market integrity, and investors may think twice before putting money into markets that change their rules too quickly."
NCFA believes that Canada should watch this U.S. experiment closely and use it to build a more practical approach ow how AI regulatory technology (Regtech) could be used to help regulators review and streamline rules without allowing a system to autonomously decide which ones to remove.
Any such pilot should have human review at every stage in a transparent process that involves the public and clear reporting so that the decisions can be trusted. Canada can also focus on improving its regulatory environment by making the rulemaking process more efficient and modern without compromising on investor and consumer protections.
This will allow our fintech sector to remain competitive without taking the same risks that the United States is now taking. To be clear, time is of the essence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
