




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 3, 2026
Image by Idris Halloway
Most of the fintech intelligence that crosses a Canadian analyst's desk arrives pre-labeled by sector: lending, open banking, payments, insurance. US social casinos rarely get filed under any of them, which is part of why the category is easy to underrate. Strip away the cartoon coins and the free-spin marketing, and what remains is a consumer payments business with a money-in flow, a money-out flow, and a compliance perimeter that looks familiar to anyone who has ever built a wallet or a checkout.
That reframing matters because the US market has grown large enough to work as a live demonstration of payment ideas the Canadian sector is still rolling out. Before treating social gaming as a novelty, it helps to see how the products are actually packaged for players. GamingToday keeps a running reference on sweepstakes-style gaming options that lays out how these titles present coins, prizes, and purchase tiers, which is a sensible way to read the consumer surface before you go looking for the plumbing underneath it.
This piece reads the boom the way a payments team would rather than the way a gambling columnist does. It walks through the money-in side, the identity layer, the money-out side, and the embedded-finance framing that ties them together, then asks the partner-risk question that US bank regulators are now putting to any firm that touches these flows. Throughout, the vantage point is Canadian, because the RTR launch and the country's open-banking timeline make the US experience unusually relevant reading for a payments desk in Toronto or Vancouver.
The first mental switch is to stop counting players and start counting transactions. A social casino does not earn money from people playing free rounds. It earns money at two points only: when a user chooses to buy a package of virtual coins, and, in the sweepstakes variant, when a user redeems an accumulated prize balance back into real value. Everything between those two points is engagement, and engagement is free to the player and nearly free to the operator.
Size the market and the reason for attention becomes obvious. Analyst estimates for the global social casino category in 2025 span a wide band, from roughly nine billion dollars to more than twenty billion, depending on where each firm draws the boundary between social slots, poker apps, and sweepstakes brands. The definitions are messy, but the direction is not in dispute: this is a multi-billion-dollar consumer segment whose entire revenue base is card charges, account transfers, and payouts. For a payments professional, that makes it a large real-world test of exactly the rails and controls the industry argues about in the abstract.
The revenue mix is what separates social casinos from most mobile games. By several industry counts, a large majority of new social casino releases now ship with in-app purchases, and the sale of virtual coins, not advertising, supplies most of what they earn. A game that monetizes through purchases rather than ads is, functionally, a merchant. It has a checkout, an average order value, a decline rate, and a chargeback problem, and those metrics behave the way they do in any high-frequency, low-ticket consumer business.
Precision here prevents the whole analysis from drifting. A social casino is a free-to-play product. The core loop uses a virtual currency, often called Gold Coins, that has no cash value and cannot be redeemed for anything. Players can buy more of it to keep playing, but they are buying entertainment time, not a stake. This is legally and mechanically distinct from a real-money online casino, which takes wagers in dollars and pays winnings in dollars, and which is licensed in only a small number of US states.
The sweepstakes variant adds a second currency, usually called Sweeps Coins, that can be redeemed for prizes, and it reaches players through no-purchase methods as well as through a bonus attached to coin packages. That free-entry mechanism is the legal hinge that lets sweepstakes brands operate in far more states than licensed casinos can. It is also the feature that draws the most regulatory attention. Real-money online casinos are not legal in California, and the state's Assembly Bill 831, effective January 1, 2026, restricts the dual-currency sweepstakes model directly, extending exposure to the vendors and partners who support it.
For a payments reader, the takeaway is narrow and important. The money-in flow, buying Gold Coins, exists in both the plain social model and the sweepstakes model. The money-out flow, redeeming a prize, exists only in the sweepstakes model, and it is the flow that carries the heavier compliance weight. Keeping those two flows separate in your head is the difference between understanding the sector and repeating marketing copy about free coins.
Buying a coin package looks trivial to a player: pick a tier, tap a saved card or a mobile wallet, receive coins instantly. Underneath, it is one of the harder acceptance problems in consumer payments. Card networks and issuing banks treat anything gambling-adjacent as elevated risk, even when the product is legally a game rather than a wager. That classification drives higher decline rates, tighter merchant category coding, and processor pricing that reflects the risk of chargebacks and reputational exposure.

Image by Idris Halloway
The consequences shape the whole business. An operator that loses even a small share of attempted purchases to false declines is leaving revenue on the table at its single point of monetization, so payment optimization is not a back-office concern for these firms but a growth lever. Many run several processors in parallel and route each transaction to whichever is most likely to approve it, a practice payment teams recognize as orchestration. Mobile wallets help, because tokenized wallet transactions approve at higher rates and reduce stored-card exposure, which is why the checkout you see is usually a wallet button rather than a raw card form.
Account-to-account options sit at the edge of this flow and are growing. Paying directly from a bank account through an open-banking connection or a pay-by-bank rail sidesteps card interchange and card-network risk rules entirely. For an operator squeezed on card acceptance, an account-to-account purchase is cheaper and harder for an issuer to block, which is one reason the social gaming sector watches open-banking payment initiation as closely as any retail category does.
The industry talks about identity as a compliance chore, but for a payments team it is really part of the acceptance stack. Before a sweepstakes brand can let value flow out, it has to know who the account holder is, and that verification has to be strong enough to satisfy anti-money-laundering expectations on the redemption side. Weak onboarding produces fraud losses and payout disputes; onboarding that is too heavy kills conversion at signup. The tension between those two failure modes is the same one every neobank and wallet provider manages.
What makes social casinos instructive is the sequence. Because the free coins require no payment, a user can sign up and play with almost no friction, and heavier identity checks are deferred until the moment money is about to move out. That deferred-verification design, light at the top of the funnel and strict at the cash-out gate, is a pattern payment and lending firms use widely, and the social casino version runs it at very large scale with real fraud pressure behind it. Watching how these operators tune the verification gate is a practical lesson in balancing conversion against loss.
The stakes rise on the redemption side because that is where the model resembles regulated value transfer. Source-of-funds questions, sanctions screening, and duplicate-account detection all land at the payout step. A payments provider evaluating one of these brands as a client should read the strength of that gate as carefully as it reads the purchase flow, because the redemption path is where the regulatory liability actually concentrates.
Step back and the whole arrangement is an embedded-finance story. The game company is not a bank and does not want to become one, yet it offers a checkout, a stored-value balance, and a payout capability that together behave like financial services wrapped inside entertainment. That is the definition of embedded finance: financial functions delivered inside a non-financial product, through partners who supply the regulated pieces behind the scenes. NCFA's own plain-language primer on embedded finance frames the category as banking brought to the customer rather than the customer sent to the bank, and a social casino is that idea taken to its consumer-entertainment extreme.
The value chain looks the same as it does in any embedded-finance case. There are providers who hold the regulated licenses, enablers who supply the middleware and orchestration, and distributors, here the game brands, who own the customer relationship and the interface. Industry projections put the embedded-finance market on a steep growth path, with one widely cited forecast pointing to roughly US$776 billion by 2029 at a compound annual rate near twenty-four percent, and social gaming is one of the noisier consumer expressions of that curve.
Seeing the sector this way changes which risks matter. The interesting exposure is not whether a given game is fun or fair. It is that a chain of payment providers, processors, wallet vendors, and identity firms is quietly powering a product with a shifting legal footprint, and each of those partners inherits part of the risk. That is precisely the arrangement regulators have started to examine, and it is where the Canadian reader should pay closest attention.
Prize redemption is where social casinos meet the most active frontier in payments: getting money to a person quickly and cheaply. A player who wins expects the value to arrive fast, and a slow or failed payout is the quickest way to lose that player's trust and any future purchases. So the redemption experience is not a courtesy, it is a retention mechanism, which puts direct commercial pressure on the operator to use the fastest rail available.

Image by Idris Halloway
Traditional payout rails make this hard. A bank transfer can take days, a card refund is slow and reversible, and a gift card shifts cost around without solving speed. The rails purpose-built for this problem are the real-time payment systems now spreading worldwide: in the United States, instant networks that clear in seconds around the clock, and in Canada, the Real-Time Rail that Payments Canada is bringing online in phases through 2026 on the ISO 20022 messaging standard, with irrevocable settlement any time of day. A payout that lands in seconds, at a low flat cost, is exactly what a redemption flow wants.
The irrevocability of those rails is a double-edged design. Instant, final settlement is wonderful for a legitimate payout and dangerous for a fraudulent one, because there is no chargeback to claw a bad transfer back. That is why the identity gate discussed earlier tightens precisely at the cash-out step, and why operators pair fast rails with playthrough conditions and payout thresholds. For a Canadian payments desk preparing RTR use cases, the social casino payout problem is a preview of the fraud and speed trade-offs the domestic rail will face across many industries.
It helps to lay the pieces side by side, because the player sees a simple game surface while the payments team sees a stack of distinct decisions. The table maps each visible touchpoint to what the player experiences and to the question a payments professional should ask about it.
| Touchpoint | What the player experiences | The payments question underneath |
| Signup and free coins | Instant, no payment, start playing | How light can onboarding be before fraud enters |
| Coin purchase | Tap a wallet, coins appear | Which processor approves it, at what decline rate and cost |
| Stored coin balance | A number in the app | Is this stored value, and who holds the liability |
| Identity verification | A prompt before cash-out | Is the check strong enough for AML on payout |
| Prize redemption | Money arrives, ideally fast | Which rail, how fast, and is it reversible |
| Partner chain | Invisible | Which licensed firm carries the regulatory duty |
Read down the right column and the pattern is clear. Nothing on the player-facing side reveals where the money, the liability, or the compliance duty actually sits. Every meaningful risk lives in the second column, in the partner arrangements the interface is designed to hide. A payments reader who only watches the game surface will miss the entire business.
The reason this matters beyond curiosity is that the firms enabling these flows are the same kinds of firms bank regulators are scrutinizing hardest right now. Through 2024, US banking agencies issued a joint statement on the risks in bank arrangements with third parties and asked for comment on bank-fintech partnerships, signaling that the regulated institution behind an embedded product cannot treat the partner relationship as someone else's problem.
Image by Idris Halloway
The principle those agencies set out reads directly onto the social casino chain. In the Federal Reserve's federal guidance on third-party risk management, issued with the FDIC and the OCC in 2024, the agencies state that engaging a third party does not diminish or remove a bank's responsibility to operate in a safe and sound manner and to comply with applicable requirements. Translate that to a game brand's payment stack and it means the licensed provider at the base of the chain owns the compliance outcome, no matter how many enablers and distributors sit between it and the player.
For any payment firm weighing social gaming as a client, that reframes the diligence. The question is not only whether a specific brand is above board today, but whether the provider can supervise a partner whose legal footing may narrow state by state as measures like California's restriction spread. A rail that clears a redemption for a product later ruled offside is not a neutral pipe in the eyes of these frameworks. It is a supervised activity, and the cost of getting the partner assessment wrong is measured in enforcement, not just churn.
The useful conclusion for a Canadian reader is not to chase the sector or to dismiss it, but to treat it as free field research. The US social casino market is running, at consumer scale, the exact experiments the Canadian sector is about to formalize: instant irrevocable payouts, account-to-account purchasing, deferred identity verification, and financial features embedded inside a non-financial brand. Each of those is a line item in Canada's open-banking and Real-Time Rail rollout, and the US market is stress-testing them in public right now.
The risks travel just as well as the techniques. The same speed that makes a real-time payout delightful makes a fraudulent one unrecoverable. The same embedded-finance structure that lets a game offer a slick checkout spreads regulatory duty across a chain of partners who may not all understand what they are carrying. A Canadian provider that reads the US boom carefully gets to learn those lessons before the domestic rail is fully live, which is a far cheaper way to learn them than through a domestic incident.
Filed correctly, then, US social casinos belong on the payments desk, not the entertainment page. They are a large, fast-moving, real-money demonstration of embedded finance under regulatory pressure, and the plumbing they run on is the same plumbing the Canadian sector is building. The free coins are the distraction. The transaction flows, the payout rails, and the partner-liability questions underneath them are the reading that repays the attention.
Why would a payments professional study social casinos at all?
Because the product is a consumer payments business dressed as a game. Its entire revenue comes from coin purchases and prize redemptions, so it exercises card acceptance, identity verification, and fast-payout rails at large scale under real fraud pressure. That makes it a working case study in the same problems any wallet, checkout, or neobank has to solve.
How do social casino coin purchases move through the card networks?
They move like any high-risk, low-ticket merchant charge. Card issuers treat gambling-adjacent purchases as elevated risk, which raises decline rates and processing costs, so operators often route transactions across several processors and lean on mobile wallets to lift approval rates. Account-to-account and pay-by-bank options are growing because they sidestep card interchange and network risk rules.
What makes prize redemption a real-time payments problem?
Players judge a brand by how fast a prize arrives, so operators want the quickest rail available, which points toward instant systems like the US real-time networks and Canada's coming Real-Time Rail. Those rails settle in seconds and are irrevocable, which is ideal for a genuine payout and risky for a fraudulent one, so identity checks tighten at the cash-out step to compensate.
How does embedded finance apply to a social casino?
The game company offers a checkout, a stored-value balance, and a payout capability without being a bank itself, relying on licensed providers and middleware behind the scenes. That is embedded finance by definition: financial services delivered inside a non-financial product. The same provider, enabler, and distributor value chain seen across embedded finance applies directly to the sector.
What should a Canadian payment provider check before working with a social gaming brand?
Start with the strength of the identity and source-of-funds gate on the redemption side, since that is where anti-money-laundering liability concentrates. Then assess the brand's legal footing state by state, because measures restricting dual-currency sweepstakes are spreading. Under current third-party risk frameworks, the licensed provider keeps the compliance duty regardless of how many partners sit in between.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Wealthtech And Investing, Digital Identity And Trust, Risk Compliance And Regtech, Fintech And Innovation
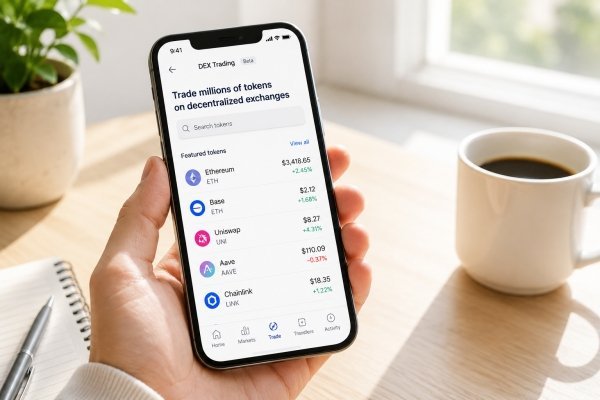
On July 2, 2026, Wealthsimple launched DEX trading in beta, giving eligible clients a way to trade on-chain tokens directly inside the Wealthsimple app.
The beta gives clients access to millions of tokens, starting with Ethereum-based assets. Base and Solana support are planned. The service charges a flat 0.85% trading fee and currently includes $0 network fees, which Wealthsimple Web3 Inc. covers during the early release.
This isn't the same product as Wealthsimple's centralized crypto account. When a client makes a first DEX trade, the app creates a separate self-custody wallet. The app holds DEX assets separately from centralized crypto holdings. They aren't insured, and don't have the same regulatory oversight as Wealthsimple's listed crypto offering.
A normal DEX user has to manage a wallet, fund it, connect it to a decentralized exchange, check token contracts, manage network fees, understand slippage, approve transactions, and protect private keys. As a result, there are a lot of steps that add complexity.
The beta removes much of that setup from the user experience. Its help guide says clients can search for DEX-labelled assets in the Discover tab, create a DEX wallet during the first trade, and buy or sell eligible DEX tokens directly in the app.
Behind the scenes, the app converts the funding asset into USDC. It then withdraws the funds to the self-custody wallet and routes the order through a third-party DEX aggregator before executing the trade.
Centralized crypto assets go through the platform's listing process, and the platform holds them on behalf of clients. DEX assets haven't gone through that centralized listing process.
Wealthsimple says a third-party vendor flags malicious tokens, and the app automatically filters them, and asset pages can display risk flags such as new asset history, top holder concentration, low holder count, low liquidity, sketchy token permissions, and artificial trading patterns.
Those flags are useful, but they aren't a safety guarantee. The help guide tells users to research tokens before trading and notes that blockchain transactions can't be reversed. If a client buys a scam or fraudulent token, the transaction can't be undone.
While the product lowers the operational barrier to on-chain markets, users still face risks that don't exist in the same way inside a curated centralized exchange custodial account.
Clients hold WS DEX assets in a self-custody wallet. They aren't covered by insurance, don't have government-backed loss protection, and aren't held by Wealthsimple on the client's behalf.
The support team can't recover the wallet or reverse transactions if something goes wrong. The user authorizes trades, and the wallet sits outside Wealthsimple's centralized crypto infrastructure.
There are also product limits during early release.
At the end of the day, there are limits to what the beta product is at this point. Embedded self-custody trading inside a controlled retail app, not a full open-wallet DeFi experience.
Wealthsimple's IPO Access launch gave eligible retail investors a way to request shares in selected Canadian and U.S. IPOs before public trading. Wealthsimple's 2025 product event added zero fee options, real gold, and private market portfolios. Wealthsimple's Fey acquisition added AI research and trading tools to the roadmap.
DEX trading adds another access layer. Clients can use one app for listed securities, crypto, IPO access, options, gold, private market portfolios, and now on-chain token trading.
Most clients won't need millions of tokens. The acid test is whether the app can make on-chain trading simple enough to try without making the risks feel smaller than they are.
One path is regulated centralized crypto access, where platforms list a smaller set of assets, hold assets through custodial arrangements, follow dealer rules, and provide clearer investor protections. Canadian crypto regulation has pushed platforms toward stronger custody, registration, and operating controls.
The other path is on-chain access, where users reach a broader token universe but also take on more responsibility for token risk, wallet access, tax tracking, execution, and irreversible transactions.
The beta sits between those paths. It keeps the user inside a mainstream Canadian app, but the assets trade through decentralized markets and sit in a self-custody wallet. That's different from both a traditional crypto exchange and a fully independent DeFi wallet.
Wallet usability becomes a core feature. Token risk intelligence becomes part of the trading interface. Slippage controls, routing quality, transaction monitoring, tax tooling, scam detection, and user education become operating requirements rather than extras.
Those areas connect directly to NCFA's Financial Innovation Map, including self-custody wallets, retail digital asset access, token risk analytics, on-chain finance, digital identity and trust, and compliance technology.
The opportunity isn't only trading more tokens. It's building the trust, data, user experience, and risk tools that let mainstream investors interact with on-chain markets without pretending those markets are safe by default.
If mainstream investing apps make self-custody DEX trading feel simple, will the next phase of retail crypto adoption depend more on token access or risk intelligence?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 2, 2026

Businesses produce large quantities of data from sales systems, customer interactions, marketing campaigns, websites and operational processes. Organising this information is necessary for identifying opportunities plus making decisions based on facts. Cloud data lakes are flexible environments where organizations store large volumes of structured and unstructured data in one place, which provides a basis for complex analytics but also business intelligence.
Traditional storage systems often require users to organize data before they store it. In contrast, cloud data lakes allow businesses to collect information from many sources and analyze it when necessary - this method helps organizations understand customer behavior, market trends, operational performance as well as potential for future expansion.
A cloud data lake is a central location for storing raw data in its original form. It allows businesses to keep information that does not fit into standard databases. Data is available from websites, mobile applications, social media, sensors, financial systems and tools for managing customer relationships.
Flexibility makes cloud data lakes useful for growth analytics. Organizations are able to combine data from different departments without long preparation periods - this creates a complete view of business activities or helps teams find connections and patterns that are otherwise difficult to see.
Gathering information from many business systems is a primary benefit of cloud data lakes. Marketing data, sales records, customer service interactions, inventory reports next to website analytics are stored together - this broad approach improves the quality and precision of business analysis.
Detailed understanding of performance across the entire organization is possible when businesses collect information from many sources. Analysts are able to study how marketing campaigns affect sales, how support affects customer retention or how inventory management relates to profit - these connections support strategic planning plus initiatives for growth.
Growth analytics require the accurate measurement of performance. Free cloud storage supports constant monitoring - collecting information from operational but also financial systems quickly - this allows organizations to follow key performance indicators and react to changes.
Revenue growth, costs to acquire customers, operational efficiency as well as product performance are measurable through integrated tools. Finding performance issues early allows managers to fix problems before they change the final results significantly.
Cloud data lakes make it simple for authorized teams to find information. Users retrieve data from a central location instead of searching through separate systems - this increases efficiency and reduces the time required for decision making.
Better accessibility also promotes cooperation between departments. Marketing teams, finance departments, operations managers but also executives use the same data. Decisions are consistent and follow the general goals of the business.
Cloud data lakes provide the storage as well as computing power necessary for advanced analytical methods. Businesses use predictive analytics, machine learning models and statistical analysis to find patterns that help future growth - these tools allow organizations to look at future opportunities rather than only looking at past reports.
Complex analytics show trends in customer purchasing, identify segments of the market that produce profit or predict demand. By using these insights, businesses distribute resources effectively and make decisions that support expansion while avoiding unnecessary risks.
Understanding how customers behave is a vital part of business growth. Cloud data lakes allow organizations to join customer information from many channels, like websites, mobile apps next to purchasing platforms - this creates a complete profile of the customer.
Preferences, habits and engagement patterns are visible when businesses have a unified view of customer activity - these insights help organizations create specific marketing campaigns, improve the customer experience plus increase loyalty. Better understanding of customers often results in higher revenue and a better position in the market.
Data volumes often increase quickly as businesses grow - Cloud data lakes scale to meet the needs of the organization, which allows companies to store and analyze large datasets without spending heavily on new infrastructure - this scalability supports long term growth without the need to replace systems constantly.
Many organizations start data projects with affordable solutions, like limited storage for testing. Businesses move to larger environments with more capacity as their needs for analysis grow. Some providers offer plans with unlimited cloud storage but companies should check usage policies or performance needs before choosing one.
Reliable and honest information is necessary for effective growth analytics. Businesses should create data governance rules that define how they collect, store, access next to maintain information. Clear policies improve the quality of data and help the company follow regulations.
Security measures like access controls, encryption plus monitoring tools protect private information. Strong governance ensures that analysis is based on accurate data, which gives decision makers confidence in the insights they use for growth strategies.
Cloud data lakes are a strong foundation for business growth analytics because they centralize information, make data accessible and support complex analysis. They allow organizations to combine data from many sources, understand customers better, monitor performance but also find opportunities for expansion.
Using governance practices and analytical tools helps businesses change large amounts of data into useful insights. A managed cloud data lake helps organizations make decisions based on facts, improve how they operate as well as create growth in a business environment that relies on data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jul 2, 2026 | NCFA Resource | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech
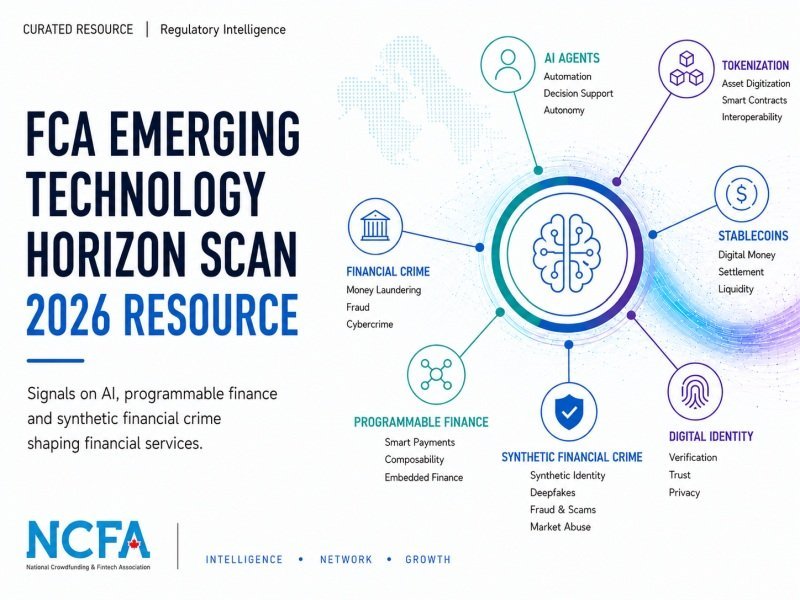
On June 10, 2026, the UK Financial Conduct Authority published the FCA Emerging Technology Horizon Scan 2026. The report examines how AI agents, synthetic financial crime and programmable finance could affect consumers, firms, markets and financial infrastructure through 2030.
NCFA's FCA Emerging Technology Horizon Scan guide turns the report into an interactive regulatory foresight resource. It separates the FCA's findings from implementation considerations, NCFA interpretation and Canadian relevance.
The FCA organizes the Horizon Scan around three technology convergence themes:
The guide also connects the Horizon Scan with later FCA work, including the Mills Review, the Supercharged Sandbox and the joint frontier AI cyber resilience statement.
The resource helps fintech leaders assess technology combinations rather than treating AI, distributed ledgers, identity, data, payments and cyber risk as separate issues.
Readers can use the interactive explorer to review:
The FCA Horizon Scan sits before formal regulation. It identifies early indicators that may affect product governance, consumer protection, financial crime controls, market surveillance, operational resilience and infrastructure design.
This resource is useful for fintech founders, financial institutions, AI developers, digital asset firms, regtech providers, compliance teams, cybersecurity leaders, investors, policymakers and market infrastructure firms.
It is especially relevant to teams assessing AI agent governance, synthetic identity, deepfake risk, automated financial crime, tokenized finance, programmable payments, stablecoins, digital identity, smart data and operational resilience.
The resource's main strength is its focus on convergence. It shows how AI agents, identity systems, synthetic media, tokenized assets, smart contracts and payment infrastructure may operate together.
It also supports practical planning. Firms can use it to test product assumptions, fraud controls, data strategy, identity plans, tokenized financial infrastructure and board level governance.
The FCA Horizon Scan is not regulatory guidance, a rulebook or a prediction. It does not create requirements or confirm that its scenarios will occur. Readers should use the guide for regulatory intelligence, scenario planning and strategic review, not as legal, financial, investment, compliance or professional advice.
FCA Emerging Technology Horizon Scan (interactive NCFA Regulatory Intelligence guide)
FCA Emerging Technology Horizon Scan 2026 (primary FCA source)
The Mills Review (FCA review of AI and retail financial services through 2030)
Frontier AI And Cyber Resilience (FCA, Bank of England and UK Treasury statement)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
Tokenization Starts Looking Like Financial Infrastructure (programmable finance context)
MIT AI Risk Repository For Fintech Governance (AI risk taxonomy resource)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org.
| | |
|---|---|---|
| | |
The FCA Emerging Technology Horizon Scan 2026 sets out three plausible ways emerging technologies could combine across financial services. It focuses on early indicators, potential risks and strategic questions rather than binding rules.
Use this guide to understand how the FCA frames technology convergence across Personalised Intelligence, Synthetic Insecurity and Programmable Finance, how later FCA work develops those themes, and what they may mean for fintech strategy, supervision and financial infrastructure.
Coverage includes AI agents, digital twins, proxy economy risks, synthetic identity, deepfakes, autonomous financial crime, synthetic market abuse, operational resilience, tokenization, stablecoins, CBDCs, digital identity, smart data, Finternet, cross border interoperability and current FCA developments.
The Horizon Scan sits before formal regulation. It identifies plausible technology pathways that could affect consumer protection, financial crime prevention, operational resilience, infrastructure modernization and future supervisory focus.
The FCA report is organized around three technology convergence themes that cut across AI, fraud, cyber, digital assets, payments and infrastructure modernization.
Navigate the FCA Horizon Scan by strategic theme. Each section separates what the FCA says, implementation considerations and NCFA perspective.
The FCA says the Horizon Scan is its first external publication of this kind. It is not a prediction report or regulatory guidance. It presents three plausible ways emerging technologies could combine to affect consumers, firms and markets, and it highlights early signals of new risks.
Firms should treat the report as a strategic risk and opportunity map. It can inform board horizon scanning, innovation planning, product governance, cyber risk, fraud controls, data strategy, digital identity planning, tokenization strategy and operational resilience assessment.
This is an upstream regulatory strategy signal. It shows where future supervision may focus before formal rules appear. For NCFA, it connects directly to AI, digital identity, fraud, open finance, tokenization, stablecoins, CBDCs, cybersecurity, payments modernization and programmable market infrastructure.
The FCA frames emerging technology against broader global pressures, including AI competition, geopolitical tension, trade disputes, energy demand, critical materials, data centre growth, environmental pressure and divergent regulatory approaches. It notes that AI debate often runs faster than measurable evidence, while practical adoption is already taking root in customer engagement and agentic payments.
Boards should connect technology strategy to geopolitical supply chains, energy exposure, cloud concentration, vendor dependency, AI model access, regulatory divergence and cross border interoperability. Technology adoption should be assessed against measurable outcomes rather than hype.
The FCA is treating technology strategy as market structure strategy. The signals are not only about tools. They are about who controls interfaces, identity, compute, data, payment rails, settlement and trust verification.
Personalised Intelligence examines how AI, personal data, edge computing, digital twins and adaptive interfaces could change consumer outcomes. AI agents could become the main interface between consumers and firms, making financial services more personalized, automated and embedded in daily life.
Firms need to decide whether they are designing for human users, AI representatives or both. Product governance, disclosure, consent, suitability, accessibility, fair value and complaints processes may need to reflect agent-mediated consumer journeys.
The key question is whether AI increases consumer capability or quietly transfers decision power to opaque systems. The opportunity is strong, but consumer agency, privacy, accessibility and accountability become central design requirements.
The report describes escalating cognitive delegation, progressing from assistive mode to advisory mode and then autonomous action mode. In autonomous action models, proxies may negotiate, transact, optimize bills, reallocate investments or dispute charges within dynamic constraints.
Firms should assess how products appear to AI agents, how consent is collected, how human review is triggered and how agent decisions can be audited. Customer support should anticipate cases where consumers do not understand actions taken by their AI representatives.
AI agents could become the next distribution layer in financial services. The competitive question is not only who has the best app, but whose product is selected, negotiated and trusted by a consumer's agent.
The report describes digital twins as AI representations that could draw on financial data, device data, behavioural signals, wearables and broader preferences. Firms could use these tools to offer more personalized products and support by interacting with a consumer's digital twin or AI agent.
Digital twin use raises data minimization, consent, explainability, vulnerability, discrimination, product governance and audit questions. Firms need controls to avoid overfitting products to sensitive traits or creating exclusion through complexity.
Digital twins may support inclusion and better advice, but they could also create high-risk personalization. The market will need guardrails around what data should be used, who controls the twin and how decisions can be challenged.
The FCA describes a potential proxy economy where AI proxies act for consumers and competition shifts from human attention to algorithmic negotiation. The report warns that consumers may accept proxy permissions casually, similar to how web cookies are often accepted today.
Consumer protection may need to account for proxy choice architecture, permission design, escalation rules, audit trails and agent conflicts. Firms should review whether their own AI interfaces favour the firm over the consumer.
The proxy economy could rewrite financial distribution. It may reduce consumer inertia, but it may also create a new layer of algorithmic gatekeeping. This is a high value area for future NCFA question posts and opportunity analysis.
Synthetic Insecurity examines how AI expansion of human thought, labour, value chains and digital infrastructure could make simulated data difficult to distinguish from real data. The FCA describes a future where fabricated truth becomes harder to separate from actual truth.
Financial crime, fraud, onboarding, audit, dispute resolution and supervisory evidence processes should be assessed against synthetic documents, synthetic identities, narrative laundering, deepfakes and coordinated AI agent activity.
This is one of the most important sections for fintech and regulators. If evidence itself can be fabricated at scale, financial services need stronger verification layers, not only better detection of obvious fakes.
The report says deepfake risks are progressing from manipulation of the senses to manipulation of sense-making. AI may generate credible synthetic narratives, evidence trails and interactions that bypass both human and algorithmic judgment.
Firms need layered authentication, source verification, provenance controls, document forensics, voice and video verification, separate channel confirmations and controls for high-risk actions. Regulators may also need tools to assess evidentiary integrity.
Trust infrastructure is becoming a market opportunity. Identity, provenance, verification, secure communications and evidence integrity could become core financial infrastructure rather than operational controls.
The FCA warns that agentic AI could democratize high-complexity crime. A single individual may be able to deploy, manage and scale a global criminal organization through software, with AI agents performing phishing, scams, cyberattacks and manipulation.
Fraud and cyber teams should model autonomous attackers, not only human fraud rings. Controls need to detect rapid, adaptive, multilingual, personalized and multiple channel attacks that may operate continuously.
This section points to an arms race in financial crime operations. The opportunity is not only fraud prevention. It is coordinated intelligence sharing, AI defensive assessment and cross-sector resilience.
The report describes synthetic market abuse risks where autonomous multiple agent systems may engage in insider trading, collusion, spoofing, pump and dump activity, sentiment manipulation or synthetic consensus cascades.
Market surveillance should expand beyond order book and transaction data to include social sentiment, agentic behavior, synthetic content, coordinated narratives and cross-platform activity. Governance should define accountability when autonomous systems create abusive outcomes.
Synthetic market abuse links directly to crypto, tokenized markets and digital investor communities. This is a strong candidate for future Question Intelligence and regulatory comparison work.
The FCA describes adaptive and invisible threats to firms' operational resilience. Frontier AI models may identify zero-day vulnerabilities, while adaptive malware may rewrite itself, imitate normal activity and operate inside systems in real time.
Firms should assess AI-enabled cyber scenarios, cloud concentration risk, third-party software compromise, adaptive malware, rapid vulnerability response, model provider dependency and coordinated sector response. Resilience planning should assume faster attack cycles.
Operational resilience and AI risk are converging. The firms best positioned for the next phase will combine cybersecurity, vendor governance, model risk, incident response and trusted information sharing.
Programmable Finance examines the convergence of DLT and financial concepts. The FCA says financial infrastructure is becoming more modular, with shared ledgers, tokenisation, programmable money and smart contracts contributing to protocol-based financial systems.
Firms should map how programmable finance affects products, settlement, custody, compliance, legal documentation, data sharing, identity, payment triggers and risk controls. The question is how to design programmable systems that are interoperable, auditable and commercially usable.
This is the strongest bridge to NCFA's existing tokenization, stablecoin, payments and open finance work. The FCA is describing a transition from digitized services to programmable financial infrastructure.
The report situates tokenisation within programmable finance and protocol-based infrastructure. Tokenized assets are part of the transition toward financial instruments that can settle, execute and interact through software rather than manual reconciliation.
Tokenization projects should identify the real workflow being improved, the settlement asset, custody model, legal rights, data permissions, interoperability approach, compliance logic and operational fallback process.
The report supports NCFA's existing view that tokenization is becoming measurable financial infrastructure. The market opportunity is not token issuance alone. It is regulated rails, data, custody, liquidity, compliance and settlement.
The Horizon Scan links stablecoins, CBDCs, digital assets and programmable money to changes in international financial architecture. It notes that cross border CBDC pilots such as mBridge are reaching minimum viable product scale in some regions.
Payment and stablecoin projects should evaluate settlement finality, reserve or backing structure, redemption, interoperability, AML controls, sanction screening, user protection, data standards and integration with domestic payment systems.
This connects directly to the UK Cryptoasset Regulations And FCA Final Rules and NCFA's Programmable Stablecoin Payments Opportunity Brief. The strategic opportunity is compliant stablecoin infrastructure that can operate across regulated payment, settlement and tokenized asset systems.
The report identifies smart data and digital identity as interlocking layers in the UK's infrastructure-first strategy. Smart data, identity and payments may support more context-aware and programmable financial services.
Firms should assess consent, data portability, identity assurance, verifiable credentials, cross-sector data standards, fraud risk, agent access and consumer control. Smart data strategy should be linked to product design and consumer protection.
Smart data is the bridge between open banking and programmable finance. Canada should treat consumer-driven banking, digital identity and payment modernization as connected infrastructure, not isolated files.
The FCA highlights the BIS Unified Ledger and Finternet concepts alongside mBridge and sovereign programmable financial stacks. It describes two possible futures: a more unified global ledger approach, or interoperable islands of domestic programmable ecosystems.
Interoperability planning should address legal finality, messaging standards, identity, compliance, settlement assets, cross border controls, dispute handling, data governance and resilience across networks.
The Finternet discussion is highly relevant for NCFA's global intelligence work. It creates a framework for comparing Canada, the UK, EU, India, Singapore, Brazil and other jurisdictions by infrastructure readiness rather than only by regulation.
The FCA report is UK-focused, but many themes are transferable because the same technologies, fraud risks and infrastructure choices are appearing across major financial markets.
The FCA Horizon Scan gives Canada a useful external reference. It connects AI, digital identity, fraud, open finance, payments and tokenization into one strategic view of financial infrastructure change. These files should not be treated as isolated policy tracks.
The FCA Horizon Scan does not impose obligations, but it raises strategic questions firms and policymakers should consider before technology adoption outpaces governance.
The FCA Emerging Technology Horizon Scan now sits within a larger programme on AI adoption, agentic systems, cyber resilience and regulatory capability.
It is the FCA's first external technology horizon scan. The 2026 report examines plausible combinations of emerging technologies across Personalised Intelligence, Synthetic Insecurity and Programmable Finance.
No. The FCA states that it is not regulatory guidance or a prediction. It is a foresight document intended to support discussion, planning and early risk assessment.
Synthetic financial crime uses generated identities, documents, voices, images, narratives or transaction evidence to commit fraud, evade controls or manipulate financial systems.
Programmable finance combines technologies such as tokenization, smart contracts, stablecoins, digital identity and smart data to automate financial transactions and infrastructure functions.
It has no direct legal effect in Canada, but its scenarios are useful for Canadian work involving AI governance, synthetic identity, fraud prevention, consumer driven banking, payments modernization, stablecoins, tokenization and operational resilience.
The FCA Horizon Scan points to practical innovation themes across AI agents, identity, cyber resilience, fraud prevention, programmable finance, tokenization, stablecoins and interoperable financial infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Crypto, Wealthtech, Capital Markets And Funding, Fintech And Innovation

On June 30, 2026, Webull Canada Crypto announced it will begin offering cryptocurrency trading after receiving approval from the Canadian Investment Regulatory Organization.
The approval gives Webull another asset class inside its Canadian investing platform, which already supports U.S. and Canadian stocks, ETFs, options, margin accounts, cash accounts, TFSAs, and RRSPs through Webull Securities Canada.
Beta access for selected clients is expected to start soon, with a wider rollout planned in the coming weeks. Webull says the crypto experience will include 24/7 trading for assets such as Bitcoin, Ethereum, Solana, XRP, Cardano, and Litecoin.
This is another regulated online brokerage aligning digital assets among the same customer experience as traditional investing.
Webull Canada Crypto Limited is regulated by CIRO. Webull Securities Canada Limited is also regulated by CIRO and is a member of CIPF.
That structure is important because crypto trading and traditional securities accounts don't carry the same investor protections. Webull's disclosure says crypto assets are not protected by CIPF, although CIPF protection may be available for eligible cash held in a crypto trading account, subject to applicable limits and policy terms.
The approval arrives after Canadian regulators spent several years moving crypto platforms toward dealer registration and CIRO membership, custody expectations, risk disclosure, and stronger client asset controls.
Regulated access is becoming the path for retail crypto distribution in Canada.
When Webull expanded brokerage services to Canada in early 2024, the initial story was low cost access to Canadian and U.S. listed equities.
The platform has since expanded around commission free trading, advanced charting, market data, options access, registered accounts, and now crypto.
Webull is building toward a multi asset retail investing platform where users can fund accounts, monitor portfolios, review reporting, and trade across asset classes without leaving the ecosystem.
Crypto increasingly looks less like a standalone destination and more like another investing capability inside regulated financial apps.
Canadian online brokers used to compete heavily on commissions, execution, research tools, and account access. In 2026, competition is about platform depth as investors want fewer disconnected accounts. Platforms want more customer activity, better retention, more data, and a wider share of the investor relationship, and eventually more personalized portfolio features.
Webull is entering a market where Wealthsimple already combines investing, crypto, cash, tax, and other financial services. KOHO adding regulated crypto trading inside its money app flashing the same pattern from a consumer finance angle.
The Canadian crypto market has gone through enforcement, registration pressure, custody scrutiny, stablecoin restrictions, and platform exits. Yet regulated distribution keeps expanding.
Canada hasn't treated retail crypto as an unregulated free for all. It also hasn't eliminated retail access. Oversight of the market is evolving toward regulated firms, clearer disclosures, tighter custody controls, and platforms that can operate within securities rules.
Webull's entry adds another regulated access point for Canadian investors and increases pressure on every platform that wants to be a primary investing destination.
The approval gives Webull permission to compete, but it doesn't guarantee adoption.
Crypto also brings higher volatility, suitability questions, security expectations, and investor education demands. A smooth user experience can't hide the risk profile of the asset class.
The advantage for Webull is that crypto can now be offered alongside the rest of its investing platform. The challenge is that investors will compare the experience not only with crypto exchanges, but with every brokerage and fintech app trying to become the main place Canadians manage investments.
Crypto trading platforms moving toward CIRO oversight shows how Canadian regulation is reshaping digital asset distribution.
Crypto custody rules are becoming a core operating issue for dealer members and digital asset platforms.
KOHO's regulated crypto rollout shows digital assets moving into broader consumer finance platforms.
Tokenization becoming a measurable business shows how digital assets are moving deeper into regulated capital markets infrastructure.
NCFA's Financial Innovation Map tracks digital assets, wealthtech, brokerage competition, capital markets infrastructure, custody, and investor access opportunities.
If every major investing platform eventually offers stocks, ETFs, options, registered accounts, and crypto, what becomes the next competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026
Picture the moment a Canadian fintech dreads most. A regulator's letter arrives. A customer in Quebec, or in a newcomer community you were proud to serve, relied on a disclosure written in their own language, and that disclosure said something the English original did not. Now you are explaining to a supervisor how the wording was produced, who checked it, and why a fee, a risk, or an obligation came out wrong. There is no comfortable answer, because the honest one is this: a single AI model wrote it, and nobody verified it.
That scenario is no longer rare or hypothetical. As fintechs scale into new markets and serve multilingual communities at home, more and more compliance language, terms of service, risk disclosures, consent flows, regulatory filings, is being produced by one AI model with no accuracy standard behind it. It feels efficient. It looks clean. And it quietly builds a liability that only reveals its price later, at the point where it is most expensive to fix.
What makes this gap so dangerous is that its cost stays invisible until it is realized. A mistaken clause does not throw an error message. It sits inside your disclosure reading perfectly, right up until an audit, a customer complaint, or an enforcement review turns it into a remediation project, a forced re-disclosure, a penalty, or a stalled market launch. Regulators do not distinguish between an error a person made and one a machine made. Across Canada's framework, from FINTRAC's obligations under the PCMLTFA, to provincial securities disclosure rules, to the Retail Payment Activities Act, the accuracy of what a customer is told is a supervised matter, not a marketing preference. For firms serving official-language communities, bilingual accuracy is frequently a legal expectation rather than a courtesy.
Every one of those outcomes carries a number. Legal hours. Remediation. Re-issued documents. Delayed revenue while a launch is held. And the quiet, compounding cost of a regulator who now watches you more closely than your competitors. The bill for one wrong word is rarely small, and it almost never arrives on your schedule.
Here is what most teams have not priced in: AI models disagree with one another, and they disagree most on the language that matters most. Independent testing makes this concrete. In Intento's State of Translation Automation 2025, baseline machine systems averaged roughly 10 to 15 errors per text before customization, and synthesized industry data places single top-tier large language model hallucination rates in translation tasks between 10% and 18%. On a marketing tagline, a 12% error band is a style problem. On a regulatory disclosure, it is a liability with a dollar figure attached.
Those errors are idiosyncratic to each model: one engine mishandles a defined term, another drops a conditional clause, a third invents a plausible equivalent that does not exist in the target jurisdiction's regulatory vocabulary. And the risk compounds with length, so the longer the document, a prospectus, a payment services agreement, a full disclosure set, the more independent points of failure a single model introduces. Then there is the cost even a correct-looking output creates. Someone still has to check it. Every hour a compliance lead spends re-reading machine output they cannot fully trust is an hour billed to the single-model shortcut, a verification backlog that never appears on the invoice but is paid every single week.
The way out is architectural, not aspirational. If individual models fail idiosyncratically, then running many at once and keeping only what most of them independently produce turns disagreement into a filter. Intento's own findings point the same way: Slator's reporting on that study noted that a multi-agent workflow explicitly designed to avoid compounding hallucinations delivered the highest quality across nine of eleven language pairs, outperforming any single engine.
This is the principle behind MachineTranslation.com, an AI translation platform built for exactly this failure mode. Its SMART mechanism runs a text through 22 AI models simultaneously, evaluates the source context to determine the most accurate rendering, and returns the output the majority of those models agree on. Because hallucinations are model-specific, cross-model agreement functions as an automated audit: the outlier renderings that shift what an obligation means are structurally filtered out before anyone sees the result. Internal benchmarks put the effect at roughly a 90% reduction in critical error risk, with agreed errors falling below 2% and up to 85% of outputs reaching professional-quality standard. The point is not speed. The point is certainty, and certainty is precisely what removes the hidden costs: fewer errors to remediate, and far less of the verification backlog that quietly drains a compliance team's time.
Cross-model agreement handles accuracy at scale. For the documents where a single error is unthinkable, a regulator-facing filing, a signed customer agreement, a prospectus, certainty has to be absolute, and that is where a second pillar matters. On the same platform, human verification escalates any output to a professional reviewer, adding a validated final check on top of the machine layer. This is not theoretical. Tomedes, the language company behind the platform, documents its high-stakes work in a library of recent translation case studies spanning certified legal filings, court-ready documents, and financial materials handled under confidentiality and delivered to compliance standards. The economics are blunt: the cost of one professional reviewer is trivial next to the cost of one enforcement action. Consensus for accuracy across volume, human verification for certainty on the documents that cannot be wrong.
None of this asks Canadian fintechs to become linguists. It asks them to govern this control the way they already govern every other one. Regulators are moving in exactly that direction on AI more broadly. NCFA's own coverage of the IOSCO AI supervisory toolkit for capital markets frames the expectation plainly: where AI touches a supervised process, firms are expected to show governance, oversight, and accountability for how the system behaves.
Translating compliance content is one of those processes, and today it is often the least governed one in the building. The practical steps are small. Add multilingual accuracy to the risk register. Ask who verified the language a customer relied on, and how. Replace a single ungoverned model with an architecture that removes the error by design and validates the highest-stakes content with a human. The cost of getting the language right the first time is a rounding error next to the cost of explaining why you did not. For a Canadian fintech scaling across markets or serving communities in more than one language, that is the whole choice: money spent on prevention, or money lost to a disclosure you have to defend.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016