




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 8, 2026 | NCFA Insight | Artificial Intelligence And Data, Wealthtech Investing And Trading, Risk Compliance And Regtech
On September 8, 2026, Focal AI launched agentic AI capabilities for Canadian financial advisors that can read and fill forms, draft emails, prepare client materials and update information across advisor systems. Focal says its platform supports more than 130 integrations and can populate more than 400 fields in Conquest, taking the product well beyond meeting notes into CRM, financial planning, onboarding and administrative workflows.
Data points. Deloitte says 73% of advisory firms already use AI in some capacity, yet only 6% use agentic tools and just 5% have connected AI across systems. Focal is entering the much earlier part of wealth management AI adoption, where the software starts completing work rather than simply generating content.
Focal's Canadian platform handles meeting preparation, notes, follow up emails, CRM updates, planning data, forms and client deliverables. Its current Canadian product page lists Salesforce, Equisoft, Maximizer, Conquest, Microsoft Dynamics 365 and other advisor systems among more than 130 supported integrations, while its browser agent can populate 400+ Conquest fields using structured client information.
The practical difference appears after a client conversation. Instead of an advisor copying the same information into a CRM, planning tool and forms, Focal is designed to carry approved information into those systems and complete related administrative steps. Equisoft's Focal integration provides a concrete example where meeting summaries and selected tasks can flow into Equisoft/connect, while advisors review which extracted tasks are written into the CRM.
Focal's published Canadian Pro price is US$100 a month when billed annually, with enterprise pricing available by consultation. The Pro plan includes unlimited meetings, CRM integrations and the Conquest AI overlay, while custom workflow automations and AI agents for tasks such as onboarding sit in the enterprise offering.
Deloitte estimates advisors spend nearly 70% of their time on work behind the scenes and only about 30% building client relationships. Focal says users can reclaim 10 to 15 hours a week, although that remains a company claim rather than an independently measured productivity result.
Deloitte's 2026 analysis models roughly 30% to 100% higher advisor capacity by 2032 as AI, workflow redesign and technology maturity advance together, potentially freeing 25% to 50% of advisor time from lower value operational work. These are modeled scenarios rather than adoption forecasts, but they put a number on the economic prize if AI can reliably take work out of the advisor's day.
Canada is already producing operating evidence beyond Focal. In March, OneVest launched an AI native wealth operations platform spanning onboarding, account opening, fund movements, billing and document workflows. In a different financial services setting, Scotiabank reported more than 71,000 employees with access to its AI capabilities and 14 million AI actions since March 2026, showing that governed AI can reach substantial operational scale inside a Canadian financial institution.
More automation doesn't remove the advisor or dealer from the regulatory equation. The Canadian Investment Regulatory Organization's 2026 Compliance Report says its examinations will ask dealers about AI use and review the operational controls they have implemented to make sure those systems work as designed. CIRO also tells dealers to consider whether AI or automation of regulatory functions constitutes a material business change requiring advance notification.
Focal says its enterprise agents use human review controls. The Equisoft integration shows one version of that model by allowing advisors to review tasks before information is pushed into the CRM, and available Focal materials don't establish that its agents independently make suitability decisions or provide regulated financial advice. NCFA's recent guide to AI governance for Canadian financial advisors reaches the same practical point.
Firms remain responsible for supervision, privacy, recordkeeping, vendor oversight and the decisions made with the technology they adopt.
Focal also says its Canadian service uses Microsoft Azure infrastructure in Toronto, holds SOC 2 Type II certification, stores no meeting audio or video and doesn't use client conversations to train AI models. Those claims can reduce some vendor review concerns, but Canadian firms still need their own controls over data access, records, approvals and errors.
Focal has already secured useful distribution. The company says it was selected as a trusted AI partner for Financial Horizons' network of 7,000 advisors, while a separate partnership made Focal available to Designed Wealth Management's network of 180 advisors. Those figures describe potential network reach, not 7,180 active users, and shouldn't be treated as adoption numbers.
The company also raised a US$5 million seed round in October 2025, led by Distributed Ventures and Wischoff Ventures. At that point Focal was already building beyond meeting software into form filling, data entry, onboarding and know your client workflows, so the September 2026 launch is a continuation of a product strategy that predates the current agentic AI push.
Competition is substantial. Jump can take approved actions across meetings, email, CRM and financial planning systems, Zocks automates forms and CRM workflows, and Salesforce is adding AI agents to its financial services platform. As those capabilities become more common, Focal's Canadian case depends less on access to AI itself and more on integrations, local distribution, data infrastructure and how deeply its software becomes part of daily advisor work.
Focal's launch is more proof of where Canadian wealthtech is heading, but the numbers also show how early this market remains. Companies already know how to buy AI assistants. The current evolution is whether agentic products can complete enough real work across existing systems to improve advisor capacity without creating an equal burden of checking, correcting and supervising the automation.
If AI can reclaim a meaningful share of the nearly 70% of advisor time now spent behind the scenes, how much of that work will Canadian wealth firms actually be willing to delegate?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
 |  |  |
|---|---|---|
 |  |  |
Aug 29, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Competition And Market Structure, Regulation And Policy, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Cross Border Payments And FX, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Payments Infrastructure And Money Movement

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026).
This is a material step beyond the group's 2025 exploration phase. TD and Scotiabank are now participating in a global bank-led issuance venture while Canada's own stablecoin framework is still moving through implementation. The Canadian question is whether major banks build meaningful CAD-denominated digital-money capacity alongside domestic initiatives or gain scale first through shared global USD infrastructure.
Coinbase supplies the regulated trading and custody stack while Webull keeps the investor interface and brokerage relationship. That reduces the infrastructure brokers need to build themselves and gives specialist providers another route into Canadian retail distribution. It also intensifies Canadian crypto competition over who owns the customer and who supplies the regulated back end.
The useful proof is the cash leg. Tokenized securities have limited value if settlement still depends on separate legacy rails. This transaction puts the asset and payment legs onchain in a live regulated market environment, bringing programmable settlement closer to something institutions can actually use.
LSEG is extending tokenization from private markets and settlement infrastructure toward public equities. The harder test is whether tokenized shares can preserve legal ownership rights, corporate actions, price integrity and regulated settlement while gaining wallet portability and longer trading access. If that model works, public-market infrastructure begins competing directly with blockchain-native distribution without abandoning the protections of an exchange-listed security.
Coinbase is bringing regulated crypto derivatives distribution into Canada without routing the products through Coinbase Canada itself. The important boundary is eligibility as it expands access for sophisticated investors while keeping the offering outside ordinary retail availability. It also gives regulated venues a stronger alternative to offshore derivatives platforms for Canadian capital, hedging and price discovery.
The important development is bank ownership of shared tokenized deposit infrastructure, not the financing round. Cari is moving toward production with banks helping govern, fund and use the network while retaining the customer relationship. Alongside other shared bank blockchain infrastructure, the test is whether common digital money networks can achieve enough participation and interoperability to compete with institution specific systems.
Forty-three state licences give OpenPayd something infrastructure providers can't create through software alone: regulated geographic reach. The company can now connect its payment stack to a much larger U.S. operating footprint while combining fiat and digital asset permissions across the United States, United Kingdom and Europe. The test is how quickly that regulatory coverage converts into client activity and payment volume.
Final approvals put the transactions into execution. National Bank is positioned to absorb Laurentian's retail and SME relationships while Fairstone combines its commercial lending operations with Laurentian's commercial specialization. Customer migration, product continuity and retention now determine how much of the approved transaction value survives the transfer.
Australia's digital asset licensing transition now has a firm market access deadline. Firms still relying on transitional relief need the correct licence application or variation underway before September 30, while brokers, tokenization businesses, market operators and clearing providers must test whether their activities fall inside the existing financial services perimeter ahead of the new 2027 digital asset regime.
Singapore is converting stablecoin policy into the legal requirements issuers will operate under. The consultation advances the status tracked in NCFA's stablecoin regulatory intelligence from a finalized framework awaiting legislation toward implementation. Reserve, redemption, capital and cross-border requirements can now be tested against issuer economics before the rules are finalized.
The case makes privileged information a concrete event contract surveillance problem. Exchanges and brokers need controls that can connect unusual positions with access to confidential information, investigate suspicious activity and enforce trading restrictions. NCFA's regulated event contract infrastructure brief tracks this market integrity gap as distribution expands.
Section 311 can reach beyond a targeted foreign bank because U.S. institutions must also identify transactions routed indirectly through other correspondent relationships. Banks and payment firms therefore need enough counterparty visibility to detect the institution behind a payment chain, not only the correspondent presenting the transaction.
The investigation puts transaction monitoring and global compliance governance under direct supervisory scrutiny at a major cross-border payment provider. The operating test is whether controls identify known laundering typologies across high-risk channels and whether global decisions support local obligations. The eventual findings could provide useful evidence for how regulators assess AML controls across international payment networks.
Australia's AML expansion has reached the point where AUSTRAC is testing whether newly covered firms have entered the regulatory system at all. Service classification, enrollment and working AML controls can no longer remain implementation projects. Regtech providers also gain a much larger addressable compliance market, but buyers will need products matched to obligations regulators are actively checking.
Conditional approval advances Revolut from U.S. fintech distribution toward direct regulated banking capacity. Its U.S. business still relies on a partner bank, while NCFA's Revolut company intelligence had tracked the national bank application as pending. A completed charter would give Revolut more control over deposits, credit and payment connectivity, but the remaining federal approvals and preopening requirements still determine whether that capacity reaches customers in 2027.
OpenReserve is trying to combine conventional banking, tokenized deposits, digital asset custody and stablecoin infrastructure inside one national bank structure. Preliminary approval brings that model closer to regulated operating capacity, but the remaining test is execution: capital, controls, final authorization and separate approval for the planned stablecoin subsidiary still stand between the proposed structure and live customer activity.
TabaPay is trying to internalize regulated banking capacity rather than relying exclusively on sponsor bank relationships. Owning an OCC chartered bank could give the payments fintech more control over settlement, sponsorship, redundancy and difficult client use cases while retaining outside bank partners. The acquisition still requires regulatory approval, making the next test whether supervisors accept that vertical integration and its governance model.
A successful Swedish licence would turn Allica's international expansion from a funding plan into regulated market access. The bank now has to prove that its UK SME model can satisfy a new supervisor and compete in a concentrated, highly digital banking market. Approval would also give Allica a potential base for wider European expansion rather than requiring each new market to begin from the UK.
The US$3 billion target gives scale to the real time receivable funding model introduced in the United States this week. VersaBank is betting that faster access to bank balance sheet funding can take business from conventional securitization and warehouse structures. Fiscal 2027 will test whether partner demand converts into several billion dollars of new assets without weakening credit quality or funding economics.
The licence adds another authorized BNPL provider while reinforcing regulatory permission as a condition of market access in Saudi consumer finance. New entrants have to compete inside that perimeter, putting more weight on underwriting, merchant distribution, pricing and compliance execution once authorization is secured.
QR Ph is extending domestic interoperability into cross-border acceptance without requiring merchants to install another payment system. That reduces one of the practical barriers to international wallet acceptance, especially for smaller merchants. The competitive question is whether national QR networks increasingly become gateways through which global payment aggregators reach local commerce.
Agorá has crossed the real-money test identified in earlier Project Agorá testing. The harder questions now concern legal finality across jurisdictions, liquidity, interoperability and whether a shared multicurrency platform can reduce correspondent-payment friction at institutional scale without weakening central-bank control or commercial-bank money.
Banks are pushing deeper into stablecoins, tokenized deposits and direct control of payment infrastructure, while fintechs are trying to own more of the regulated stack themselves. The fight is increasingly over who controls the account, the customer relationship and the transaction flow.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 4, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Digital Assets, Embedded Finance
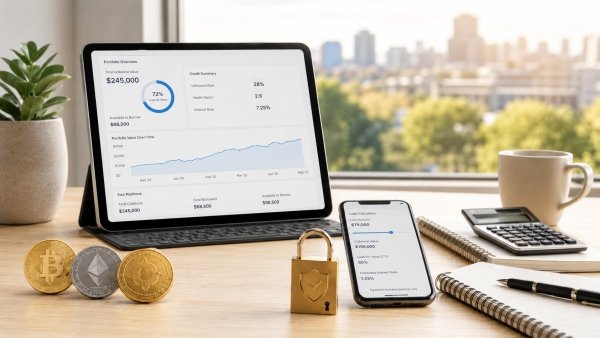
On September 3, 2026, Toronto-based APX Lending launched a five-year crypto-backed line of credit that lets eligible borrowers pledge Bitcoin, Ethereum or both, draw funds, repay them and borrow again. APX says the facility supports borrowing up to 60% loan to value, with annual rates from 10.49% to 11.99% depending on the outstanding balance.
Interest applies only to money actually borrowed, with no charge on unused capacity. APX also says there are no origination, prepayment or liquidation fees. The biggest change from APX's existing fixed-term loans is that borrowers can use the credit line more than once. They can keep approved collateral in place, draw funds when needed, repay them and borrow again.
APX gives the example of C$200,000 of Bitcoin and C$100,000 of Ethereum supporting up to C$180,000 of borrowing at the maximum 60% LTV. Available credit changes with the value of the collateral, so a falling crypto market can reduce borrowing capacity quickly.
The basic idea will be familiar to anyone who has used a securities-backed line or borrowed against property. The difference is the collateral. Bitcoin and Ethereum trade around the clock and can fall sharply in a short period, which makes ongoing collateral management a much bigger part of the borrower experience.
For long-term crypto holders, the attraction is access to cash without selling the underlying asset. That can help with business funding, debt repayment or other liquidity needs, although borrowing costs above 10% mean APX still has to compete with conventional secured credit where borrowers have access to it.
APX begins warnings when a loan reaches 80% LTV. At 90%, collateral is partially sold until the loan returns to 85% LTV. APX introduced the 90/85 liquidation model in August and says there is no liquidation fee.
A borrower can still lose Bitcoin or Ethereum when prices fall. APX's approach changes how much gets sold once the threshold is reached rather than removing liquidation risk altogether.
Custody is part of the product design as well. The OSC decision granting APX exemptive relief says collateral held under the lending arrangement is not rehypothecated (not reused or lent out to other parties). APX says assets are held in segregated BitGo Trust cold-storage wallets. Client accounts are not protected by CDIC or the Canadian Investor Protection Fund.
The revolving line follows APX's July launch of embedded crypto lending with Netcoins. Eligible Netcoins users can access APX loans through the platform while APX supplies the capital, underwriting, collateral management, compliance and servicing.
APX therefore doesn't have to rely entirely on finding borrowers through its own brand. Exchanges and wealth platforms can potentially add crypto-backed credit without building the lending operation themselves. The new revolving facility has not been announced as a Netcoins product, so the partner channel and the new line should be treated separately for now.
Ontario's securities regulator granted APX time-limited exemptive relief for its crypto-backed lending model, with the decision extending to participating jurisdictions through Canada's passport system. The order covers Bitcoin and Ether collateral and sets conditions around custody, disclosure and account suitability. It is tailored to APX and expressly says the decision should not be treated as precedent for other applicants.
APX is entering a market where other Canadian platforms are experimenting with similar products. Shakepay's Bitcoin-backed credit line, launched in August, gives eligible Canadians another way to borrow against digital assets. Cayman-based Ledn also continues to offer Bitcoin-backed Dollar Loans in most Canadian provinces, although Quebec, New Brunswick, Nova Scotia and Saskatchewan are excluded. APX differs by supporting both Bitcoin and Ethereum and by offering a five-year revolving facility rather than Ledn's standard 12-month Bitcoin-backed loan.
One platform can own more of the lending relationship itself; another can plug into a specialist lender such as APX. For exchanges and wealth platforms, embedded credit creates a way to earn more from customers who already hold digital assets without forcing those customers to sell them.
Will crypto holders use Bitcoin-backed credit often enough to make it a mainstream secured lending product?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 4, 2026
What is Web3 gaming? It is a broad category of games that use a blockchain for some part of ownership, trading, identity, governance, or the game economy. A player might hold an item in a wallet rather than only in a publisher database. That feature can create new forms of portability and coordination, but it can also add wallets, fees, scams, volatile assets, and irreversible mistakes to an activity many people expect to be simple entertainment.
This guide is for players, researchers, and editors trying to understand what a Web3 label means in practice. It explains what may be on-chain, what remains controlled by the publisher, and how to evaluate the trade-offs before spending time or money. It does not rank games, recommend tokens or collectibles, or provide investment advice.
Web3 gaming is not an all-or-nothing category. A project may put a collection of items on-chain while keeping the game server, combat rules, moderation, and progression system centralized. Another may use a token for governance but keep all gameplay data in a conventional database. The useful question is not whether a game uses a blockchain somewhere; it is which part of the player experience is actually controlled by the player or verified by a public network. For a concise foundation, what is web3 gaming is best answered by mapping those specific functions instead of treating the label as a genre.
| Game element | Common Web2 approach | Possible Web3 approach | Question for a player |
| Items | Recorded in the publisher database | Some items represented by tokens in a wallet | What rights does the token actually grant? |
| Payments | Publisher controls in-game currency | Tokens or NFTs can be transferred externally | What are the fees and exit options? |
| Identity | Login managed by the publisher | Wallet-based identity, sometimes combined with login | What happens if the wallet is lost? |
| Governance | Publisher sets rules and content | Token or community voting covers selected decisions | Which decisions are truly subject to a vote? |
| Continuity | Access depends on the game service | Some assets may remain visible if one interface changes | Does the item still have utility without the original game? |
The word "ownership" also needs precision. Holding an NFT usually means controlling a token record under a contract's rules. It does not automatically grant copyright, a trademark license, access to a server, a guaranteed use in another game, or a right to future development. Those rights may be defined by a license, terms of service, or a separate account system.
An on-chain item can sit outside one account database and be transferred under the token's rules. That may support a secondary market, a player identity, or a collection that is visible across tools. Portability is only useful when another game or service recognizes the asset and knows what its data means. A transferable item with no compatible use is ownership in a narrow technical sense, not automatic utility.
Public transaction records can also make parts of an economy easier to inspect. A reader may be able to observe supply, wallet concentration, transfers, or selected contract rules. This can improve transparency, but it does not make the economy fair by itself. A contract may still be upgradeable, a marketplace may control the interface, and important gameplay data may remain private.
Governance tokens can give players a voice over selected decisions. In practice, voting power may be concentrated among large holders, delegated to a small group, or limited to parameters that do not affect the core experience. Ask what the vote can change, who can propose it, and whether the result is binding. A vote count is not the same as meaningful player control.
Token incentives may create new funding or creator models, but they also change the audience's motivation. A player who wants a game may be competing with participants focused on item resale or token appreciation. That can make prices, participation, and community behavior more volatile than the gameplay itself.
Web3 features add operational steps. A player may need a wallet, a network choice, a transaction fee, an approval, and a marketplace account. Each step creates room for a wrong address, fake link, private-key theft, or an irreversible signature. A custodial onboarding flow can reduce some friction while increasing dependence on the provider. Neither model removes the need to understand what an action authorizes.
Transaction economics can also change the value of an item. Consider a deliberately simple example: a player buys a $20 item, pays a $3 network fee, and later pays a 5% marketplace fee to sell at the same nominal price. The sale returns about $16 before any price change or tax. The arithmetic is not a forecast; it shows why displayed item prices do not equal the amount a player can recover.
Liquidity is another constraint. A marketplace floor is an asking price, not a guaranteed buyer. When interest fades, the highest visible listing may be far above the price at which a sale would actually clear. A token can lose liquidity while the game remains playable, and the reverse can happen as well. Treat marketability as a separate question from entertainment value.
Smart contracts, bridges, marketplaces, and game servers can fail independently. An on-chain item may remain visible in a wallet while the game that gave it meaning shuts down, changes its rules, or removes its server access. A blockchain record can persist while practical utility disappears. This is why "you own the asset" is not a complete explanation of the player outcome.
Use the following sequence to separate a playable product from a token pitch:
This framework keeps the article's central question in view: does the on-chain feature improve the player experience enough to justify its added complexity? A game can be legitimate and still not suit a particular player. The decision should depend on the experience and rights, not on the label alone.
Market context can help explain why a game token is attracting attention, but it cannot measure whether the game is well designed. A token that appears among crypto market gainers may be reacting to a listing, a partnership announcement, thin liquidity, or speculative positioning. The ranking is a prompt to investigate the event and the market structure, not proof that players are adopting the game.
Check the pair, quote currency, time window, volume, and available liquidity before drawing a conclusion. A large percentage move in a shallow market may represent a small amount of capital. Conversely, strong player activity may not immediately appear in a token ranking if the project uses a custodial economy or has no liquid token. Keep game research and market research as related but distinct tasks.
The same distinction applies to community sentiment. A crowded chat can show that a launch is visible, not that the product is sustainable. Look for retention, repeat play, clear updates, and evidence that the economy works for ordinary players. If the only durable demand appears to come from recruiting new buyers, market risk may be replacing game design.
Web3 gaming is best understood as a bundle of design choices rather than a single genre. The same project can offer genuine player ownership in one area while retaining centralized control in another. Rights, fees, wallet security, server access, and token liquidity vary by project and jurisdiction. Read the game's terms, marketplace rules, and wallet prompts before making a consequential decision.
Not always. Some games offer custodial accounts, free starter items, or sponsored transactions. Others require a wallet and network fees. Check the actual onboarding flow instead of assuming the label tells you what is required.
No. You may control the token record while the publisher controls the game, servers, trademarks, and utility. The rights depend on the contract and the project's terms.
Only if the other game chooses to recognize the asset and can interpret its data. On-chain transferability does not create automatic gameplay compatibility.
They can expose a player to market risk, but a token or item is not automatically a sound investment. Prices, liquidity, fees, and utility can change, and the purchase may be better treated as entertainment or speculation.
What is Web3 gaming? It is gaming with selected ownership, payment, identity, governance, or economy functions connected to blockchain systems. The meaningful analysis is not how many tokens a project issues, but what the player can actually control, transfer, use, and recover.
Play the core game, map the control boundaries, calculate the friction, and test what survives when prices stop rising. That approach keeps technology in perspective and leaves room to enjoy a game without mistaking a market narrative for a guarantee.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
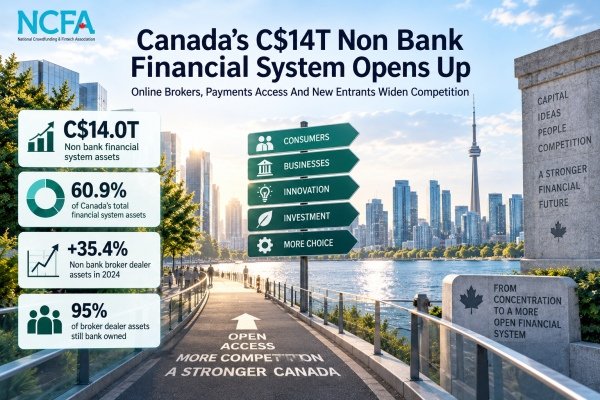
On September 3, 2026, Bank of Canada staff released new non bank finance data showing that Canada’s non bank financial sector held C$14.0 trillion in assets at the end of 2024, equal to 60.9% of the financial system. The Bank's broad definition includes pension funds, insurers, investment funds, financial auxiliaries and other intermediaries. Much of the 2024 increase also came from stronger market valuations.
The headline number is only part of the story. Faster growth is appearing in narrower bank like activities, online brokerage and specialty finance, while commercial banks still retain enormous asset and distribution advantages.
Canada already had a huge financial system outside deposit taking banks. What's changing is how customers reach it, where credit can originate and how many firms can compete for data, payments, investing and banking services.
Canada already had a vast financial system outside banks before fintech took off. Pension funds, insurers and investment funds have held enormous pools of financial assets for decades. The Bank says non bank assets have grown at an average annual rate of 6.9% since 2010.
The C$14 trillion also grew faster in 2024 because markets rose. Other investment funds increased 18.8%, pension assets rose 9.6% and insurance assets rose 9.8%. The Bank attributes much of that growth to stronger valuations.
Fintech arrived inside a financial system that was already enormous. Since then, investing has become easier to distribute online, more credit products have appeared outside traditional bank lending, payment firms have gained access to national infrastructure and financial data is being opened to approved competitors. Customers now have more ways to reach financial products without starting at a bank branch.
Online brokerage is one of the clearest changes in the Bank's data. Non bank broker dealer assets grew 35.4% in 2024, and the Bank says online brokers drove the increase.
Digital investing can win customers quickly because opening an account, moving cash and buying securities no longer requires the same physical distribution network.
The incumbents are nowhere close to disappearing. Non bank firms account for only about 5% of Canada's broker dealer assets. Bank owned broker dealers hold the other 95% of those assets.
The contrast is striking. Challenger activity is changing customer behaviour much faster than it is changing institutional asset share.
A Canadian can now invest through a digital broker, buy an ETF, hold cash inside an investing app and compare financial products without spending much time inside a traditional branch. The banks still own enormous distribution and balance sheet capacity. They no longer own every customer entry point.
Specialty finance has grown quietly beside the banks. Finance companies represent 11.8% of the narrow non bank measure and grew 7.1% in 2024. Statistics Canada includes consumer lending, corporate lending, leasing, mortgage investment corporations and mortgage finance corporations in its non bank credit work.
The official statistics have also expanded over time to capture newer models such as buy now pay later financing.
A mortgage can start outside a bank and still end up inside one. Mortgage finance corporations can originate loans through brokers and then sell them to regulated financial institutions. A borrower may meet a non bank lender first while a bank later funds or owns the mortgage.
Competition and cooperation can exist in the same transaction.
Canadian finance is becoming more distributed without becoming neatly divided into banks on one side and challengers on the other. Origination, funding, servicing, securitization and ownership can happen at different institutions. That makes the system more competitive in places and more interconnected at the same time.
Private credit shows the same Canadian pattern. Non bank loans have supplied about 15% of external funding for Canadian non financial businesses for roughly a decade. Private credit has not rapidly replaced domestic bank lending.
Canadian institutions are still heavily involved. The Bank estimates that private lending by Canadian investors plus Canadian bank lending to private credit funds totalled about C$500 billion around the beginning of 2026, with most of the activity in the United States.
Canadian pensions, insurers and banks know the asset class well. Much of the capital is simply being deployed elsewhere.
That divide is already visible in Canada's C$500 billion private credit exposure. Canadian institutions have substantial capacity to invest in private lending, while Canadian businesses still depend much more heavily on banks and public debt markets.
Payments access is opening to firms that historically could not participate directly. Payments Canada says registered payment service providers can now apply for membership and Real Time Rail participation. Wise, KOHO, Float, Paramount Commerce and Brim were among the first PSP members admitted in 2026.
The Real Time Rail is scheduled to launch in the fourth quarter of 2026 with instant clearing and settlement and support for direct PSP participation.
Financial data is opening too. Canada's consumer driven banking framework makes competition an explicit objective and creates accreditation routes for regulated financial institutions and registered payment firms.
Approved providers will be able to request customer permissioned financial data instead of relying on screen scraping or proprietary bank connections.
The opening of Canada's payments system now extends into consumer driven banking. A challenger with payment access and customer approved data has more room to build a financial relationship without depending on an incumbent for every connection.
In June, OSFI launched a streamlined approvals framework for targeted new entrants. It covers eligible credit unions and firms with technologically innovative or emerging banking models.
OSFI is aiming for a clearer three phase process and a targeted 12 month review after a complete formal application is accepted.
Foreign banks already have a formal route into Canada. OSFI assesses applications for full service and lending branches and recommends eligible applications to the Minister of Finance.
Entry is still tightly supervised. Capital, liquidity, governance, business plans, home country supervision, security and risk management remain part of the approval process.
A firm that qualifies for federal entry can pursue much more than a better financial app. Regulated banking capacity, payment access and customer approved data can put more of the customer relationship inside the challenger itself. The requirements remain demanding, but the route is clearer.
Securities rules are changing at the same time. The Canadian Securities Administrators has expanded the Listed Issuer Financing Exemption, allowed eligible venture issuers to adopt semi annual reporting and introduced other measures intended to reduce financing and disclosure friction.
In July, the CSA said more than 10% of eligible companies had already opted into semi annual reporting and that significant capital had been raised under the expanded exemption.
More financial assets do not automatically create more productivity. A pension portfolio can rise because markets rise. A fund can buy existing securities. Canadian institutions can invest abroad. None of those outcomes guarantees more financing for a Canadian company trying to commercialize technology, buy equipment or scale internationally.
That allocation question runs directly into whether Canada can turn financial access into productive participation.
The C$14 trillion headline makes the productivity problem harder to dismiss. Canada is not short of financial assets. The harder question is whether more of the system can connect viable Canadian businesses with capital on terms that let them invest, grow and compete.
The Bank itself recognizes the upside. Its paper says these non bank firms can foster innovation, increase competition, serve underserved markets and improve financial system efficiency.
The same activities can also carry leverage and transform credit or liquidity in ways that spread stress through funds, dealers and financing markets. More activity outside bank balance sheets can distribute risk while making some connections harder to see.
The Bank's 2026 work on private credit and market based finance reflects that concern without treating every non bank institution as a threat.
As activity spreads across funds, dealers, lenders and platforms, risk travels with it. Credit, liquidity, customer data and operating dependencies become harder to follow when they are shared across more institutions. Regulators have to preserve the benefits of wider competition while keeping those connections visible.
Banks still anchor the system. Their share of total financial system assets barely changed in 2024. They still dominate broker dealer assets, business lending, deposits and many of the funding relationships behind non bank finance.
The starting points are multiplying. Online brokers compete for investors. Specialty lenders compete for borrowers. PSPs can gain direct payment access. Approved providers can compete around financial data. Eligible new entrants can pursue federal regulation through a clearer process.
Canada's banks remain deeply entrenched, but more of the financial activity around them is open to competition. Incumbents keep the scale while challengers gain more ways to reach customers, move money, originate credit, raise capital and, in some cases, become regulated institutions themselves.
Talking Point
Canada already has C$14 trillion of finance outside traditional banks. More firms are now gaining ways to compete for customers, payments, data, credit and regulated entry while the banks remain dominant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
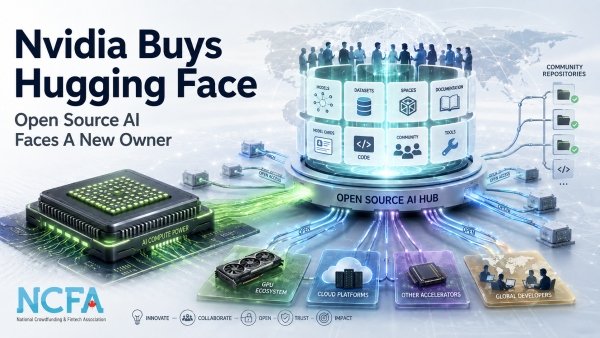
On September 3, 2026, Nvidia announced a definitive agreement to acquire Hugging Face for US$12.9303 billion. The deal would put one of the biggest platforms for open source and open weight AI alongside the company that already dominates much of the market for AI computing.
The price includes about US$11.9 billion for Hugging Face stockholders and up to US$1 billion in equity awards for employees joining Nvidia. The transaction hasn't closed. Nvidia says it expects completion in the first half of 2027, subject to regulatory approvals and other closing conditions.
Nvidia is making a very public promise with the deal. Hugging Face will remain open. Developers will still be able to choose their models, clouds, inference providers and computing platforms. Nvidia hardware will not be required.
That promise goes directly to the tension. Hugging Face became valuable because developers, startups, researchers and rival chip companies could all build there. Nvidia can make that ecosystem stronger. Ownership can also make some of those same users wonder whether an open source AI platform can feel as independent once one of the most powerful companies in AI owns it.
Hugging Face has grown into one of the main places developers find, share and use open AI models. Nvidia says more than 18 million developers, researchers and creators use the platform, along with more than 200,000 companies.
The company was worth far less only three years ago. Hugging Face raised US$235 million in 2023 at a US$4.5 billion valuation, with investors including Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Salesforce.
Nvidia is now paying close to three times that valuation. The premium makes more sense when Hugging Face is viewed as distribution, developer access and influence over how open models get discovered and deployed.
Hugging Face is valuable because millions of people already use it to decide what to build with. Nvidia is buying that relationship as much as the software behind it. The more developers stay, the more valuable the acquisition becomes.
Nvidia already has enormous power in AI computing. Reuters Breakingviews says Nvidia holds more than 80% of the AI accelerator market, while its chips have become a reference point for a growing market in GPU rental pricing.
That power is one reason the acquisition attracts attention. Nvidia will own a major open model platform while selling the hardware many of those models run on.
Hugging Face has also become important to Nvidia's competitors. Its own 2026 data says AMD and Nvidia are the two most active publishers of new open models on the Hub, with each releasing more than 200 model repositories this year.
AMD uses open models to prove its chips can run real workloads. Google, Microsoft, IBM and other companies also publish and distribute models through the platform.
The acquisition does not remove AMD, Google or other hardware and cloud providers from Hugging Face. Nvidia says support for rival silicon will continue. The tension comes from whether those companies remain just as comfortable investing there when the owner also competes with them.
Nvidia says rival chips will stay welcome. Nvidia's CEO Jensen Huang says developers will keep choosing their own models, frameworks, clouds, inference providers and computing platforms. Nvidia compute will not be required to build on or deploy through Hugging Face.
Developers are already debating what ownership could mean in practice. Some community reactions welcome Nvidia because open models create demand for compute. Others worry about future defaults, private repositories, hardware preference and whether another independent open source AI platform will eventually be needed.
Nvidia doesn't have to close Hugging Face for ownership to change how the platform feels. Developers will notice which hardware gets optimized first, which services are easiest to connect and whether rival products remain equally visible and easy to use.
Open models fit Nvidia's economics surprisingly well. Hugging Face says hardware vendors are publishing open models because a model optimized for their chips is one of the clearest ways to prove the hardware works.
Nvidia can therefore benefit even when the model itself is free to download. More open model use can create more inference and training demand across data centres, enterprises and local machines.
That dependence cuts both ways. Some of Nvidia's biggest customers, including hyperscalers and AI labs, are building their own chips. The Hugging Face deal gives Nvidia a wider developer base at a time when those customers are trying to reduce their own dependence on Nvidia hardware.
Open source AI gives Nvidia access to thousands of smaller users instead of relying only on a few giant buyers.
Nvidia can support open source AI and still benefit commercially from its growth. The company does not need every developer to buy a proprietary Nvidia model. It benefits when more models create more computing demand.
China is pushing hard in the same open model market. Hugging Face data shows Chinese labs released many of the largest open models in 2026. Qwen has become one of the most important model families on the Hub, with more than 151,000 derivative repositories.
Hugging Face says Qwen based models reached more than 2 billion downloads across repositories with declared parameter counts this year.
Chinese open models are also competing on access and cost. Hugging Face found that 59% of Chinese releases above 20 billion parameters used Apache 2.0 licences and another 22% used MIT licences during the period it studied, although some very large releases have begun adding commercial restrictions.
That gives developers another source of capable models as U.S. companies debate how open their own ecosystems should remain.
Open models are part of the technology rivalry between the United States and China. Nvidia's Hugging Face acquisition gives a U.S. company more influence over a global platform at the same time Chinese model families are winning large developer communities of their own.
One possible response to Nvidia ownership is that developers simply stay. Hugging Face already has millions of models, datasets, applications and established workflows. Rebuilding that network somewhere else would be difficult.
Microsoft's GitHub acquisition offers one useful precedent. Microsoft promised GitHub would stay open and independent, and competing developers and platforms continued using it after the acquisition.
Another possibility is that developers begin spreading their work across more places. ModelScope, GitHub, local model tools, cloud registries and private enterprise repositories already give users alternatives for parts of the Hugging Face experience.
A future competitor would not need to copy every Hugging Face feature on day one. It could win users by offering easier migration, open governance, strong model provenance or a clearer commitment to hardware independence.
Network effects make a full replacement difficult, but communities can fragment before platforms collapse. Developers can keep models on Hugging Face while using other tools for discovery, inference, deployment or discussion. Competition may arrive piece by piece rather than through one new platform.
No price increase has been announced. Nvidia says Hugging Face will remain open and hardware choice will continue. That leaves plenty of room for the acquisition to improve reliability, inference tools and enterprise deployment without raising basic access costs.
Costs could still change indirectly. Developers may pay more if the easiest experience ends up depending on premium services, Nvidia optimized infrastructure or harder to replace integrations. The opposite is also possible. Better tooling and stronger open models could lower the cost of running AI compared with closed model APIs.
The acquisition does not automatically mean higher prices. The more interesting cost risk is switching. A service can remain affordable while becoming expensive to leave because models, workflows, integrations and teams are built around it.
Startups could gain from Nvidia's reach. A stronger Hugging Face can give model companies better distribution, more reliable infrastructure and easier access to enterprise customers.
For founders trying to get an open model discovered, being close to a platform used by 18 million developers can be commercially powerful.
Startups may also have less bargaining power if distribution, compute and enterprise access become more concentrated around the same company. A startup can benefit from the platform while still wanting credible ways to deploy elsewhere.
That tension is already visible in competition for cheaper AI inference, where AMD and other hardware companies are trying to give developers alternatives to Nvidia's dominant GPU position.
The upside is distribution. The risk is dependence. Founders will care less about who owns Hugging Face than whether they can still take their models, customers and economics somewhere else when they need to.
Financial institutions face the same ownership question from a different angle. Banks and insurers are already putting AI into governed workflows where data controls, approvals, audit evidence and operational resilience are required.
Governed financial AI workflows become harder when a firm cannot easily change models, clouds or providers without rebuilding controls around them.
Portability can therefore matter more than ownership alone. A bank may be comfortable using Hugging Face under Nvidia if models can still travel across clouds and chips and the institution can keep its own data, controls and audit evidence.
Regulators are also paying more attention to AI vendor concentration and operational dependence as financial firms embed more external technology into critical work.
Financial institutions do not need every AI supplier to be independent. They do need credible ways to change suppliers, hardware and deployment environments without losing control of regulated workflows.
The deal could still produce a strong outcome for open source AI. Nvidia has the engineering resources, compute and enterprise distribution to make Hugging Face faster, more reliable and easier for companies to use.
If AMD, Google, cloud providers, Chinese model labs and independent developers keep contributing, Nvidia can own the platform while the ecosystem remains genuinely competitive.
The harder outcome is quieter. Hugging Face stays open, but developers gradually find Nvidia products easier, cheaper or better supported than alternatives. No door closes. Choice simply becomes less balanced over time.
That is why Nvidia's promise will be judged through product behaviour rather than the announcement itself.
The most valuable version of Hugging Face may be one where Nvidia owns it and its competitors still want to build there. If that happens, Nvidia gets a larger open source AI ecosystem without destroying the trust that made the platform worth almost US$13 billion.
Talking Point
Nvidia does not need to close Hugging Face to gain more influence over open source AI. The deal becomes more valuable if developers, startups and rival chipmakers keep using the platform anyway.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
Some buy now, pay later activity reaches Canadian credit files. Most routine instalment plans currently do not.
That is the short answer, and the qualifications matter more than the answer does. Whether a buy now, pay later arrangement appears on a credit file in Canada depends on the provider, on which credit bureau is involved, on whether a payment was missed, and on the month in which the question is asked. Payments made on time and payments missed follow different routes. Two people financing identical purchases through different providers may find entirely different records.
What follows sets out what is reported, by whom, to which bureau, and with what effect on a score, then explains why the answer is this unsatisfying. The position described reflects Canadian reporting as of September 2026, and it is moving.
The Financial Consumer Agency of Canada describes buy now, pay later plans as arrangements that finance a purchase with credit. Its research characterises the category as covering a wide range of credit arrangements and as generally a type of consumer credit, comparable to instalment lending. That framing is the reason the credit-file question arises at all. The obligation is credit, not merely a payment method.
The agency identifies several distinct payment models sold under the same label: pre-authorized debits, pre-authorized credit card charges, an instalment option applied to an existing credit card, retail credit cards, and financing arranged through a financial institution. The entity behind each model differs. FCAC lists the financial service providers active in this market as including banks, credit unions and caisses populaires, financing companies, and money services businesses such as financial technology firms.
That mix determines oversight. FCAC directs consumers with complaints to different regulators depending on who provided the financing: federally regulated financial institutions must maintain their own complaint-handling processes, while other arrangements fall to provincial and territorial regulators. Oversight therefore follows the provider rather than the product category.
Credit reporting is furnisher-driven. A bureau can hold only what a provider chooses to send it, and furnishing is voluntary. In the United States, four senators on the Senate Banking Committee wrote to the major credit reporting companies in May 2026, reporting that several American providers had told them they were not sharing this data with credit bureaus.
The Canadian position is documented more thinly. The Canadian Lenders Association, an industry body, described the position in late 2025 as one in which inclusion of this data in credit files is voluntary, variably reported, and inconsistently used in underwriting. The same commentary reported that Equifax in Canada had begun incorporating this data, with TransUnion not far behind. Beginning is the accurate word, and it should not be read as complete.
Missed payments follow a different route from payments made on time. An account referred to a collection agency can reach a credit file through that channel even where the on-time payment record never appeared. FCAC states that once a creditor sends a debt to a collection agency, the credit score will go down. An arrangement invisible while it was being paid can become visible once it is not.
Because the position varies by provider and bureau, the only reliable confirmation is an individual file. You can check your credit score and see what each bureau holds in your name.
Three independent variables produce the inconsistency, and naming them is more durable than listing providers whose practices change.
The first is whether the provider furnishes at all. This is voluntary, and it varies both between providers and by product.
The second is what the receiving bureau does with it. In a 2022 post it has since archived, the United States Consumer Financial Protection Bureau noted diverging approaches: one credit reporting company implemented a business industry code while letting furnishers supply data in their preferred format, and others planned to hold it in specialty files kept apart from the core files behind traditional reports. That account is American and several years old. Canadian bureau practice is not documented publicly in comparable detail. That gap is part of the answer.
The third is whether the scoring model uses the data. TransUnion Canada stated in a 2024 paper that it was analysing alternative data, including buy now, pay later, without initially affecting its scores. Data can sit on a file while remaining absent from the decision. Presence on a record and effect on a score are separate things, a distinction that governs which financial activity does and does not build a credit file.
The foundational federal research on buy now, pay later in Canada is a pilot study, and the agency says so itself.
FCAC surveyed 1,034 Canadians aged 18 and over. The sub-sample of actual users was 66 people, of whom 20 took part in follow-up interviews. The agency states that most findings are drawn from that sub-sample, that these early findings should not be generalised to Canadians at large, and that unweighted percentages are used throughout. Those are appropriate disclosures on a pilot. The difficulty lies with how often it is cited as settled evidence.
Two details matter. The survey reference period ran from September 2019 to March 2021; the report was published in November 2021. And 44 percent of the users surveyed found the potential effect on their credit score difficult to understand: the confusion this article addresses was documented at the outset. Interview participants described using these plans to bridge a timing gap, wanting to purchase immediately while knowing funds would arrive later.
FCAC identified risks of over-borrowing and over-indebtedness but stopped short of recommending regulation, committing instead to monitor the market, conduct follow-up research, coordinate with provincial and territorial authorities, and provide consumer education. As of September 2026, the agency's published research index lists no further study.
Where these obligations are not furnished, or are furnished into files that scoring models do not read, they are absent from any assessment built on bureau data. A household carrying several concurrent instalment plans can present on a credit file as a household carrying none.
The omission runs in both directions. A consumer reviewing their own file may conclude they carry less than they do. And every party that assesses affordability from bureau data, from banks and credit unions to licensed Canadian lenders, works from a record that omits a category of live obligation. TransUnion Canada listed this as a market concern in 2024, noting that limited reporting constrains the ability of other lenders to conduct credit checks and assess affordability.
This is neither new nor specific to one product. Rent, utilities and telecommunications payments are largely unreported in Canada as well. Buy now, pay later is a recent addition to a longer list of obligations that credit files do not capture. The observation concerns what the record contains, not what any party ought to do about it.
On 23 June 2025, FICO announced two scoring models, FICO Score 10 BNPL and FICO Score 10 T BNPL, built to incorporate buy now, pay later data. The announcement was framed explicitly around the United States credit ecosystem, and FICO stated the models would initially be offered alongside its existing scores rather than replacing them, leaving adoption to individual lenders. No equivalent Canadian scoring model has been announced.
The Canadian Lenders Association, an industry body representing lenders, has argued that the sector needs a consistent framework so that this data supports credit inclusion rather than working against it. The position is reasonable and worth reporting. It is not a neutral one.
The effect of fuller reporting would run in two directions. For a consumer with a thin file, a furnished record of payments made on time would constitute history where none existed. For a consumer carrying several concurrent plans, the same reporting would make visible an obligation load that had gone unobserved. Which effect applies is a matter of individual circumstance.
The question a reader arrives with is whether buy now, pay later touches their credit file. The accurate answer is that it depends on the provider, on the bureau, on whether a payment was missed, and on the month in which the question is asked.
That is unsatisfying, and it is not a hedge. Furnishing is voluntary and partial. Bureau treatment differs and is not documented publicly in Canada at the level of detail the question deserves. Scoring treatment is a separate matter again. The Canadian federal evidence base remains a pilot study of 66 users describing behaviour from a period that ended in March 2021.
Each of those conditions can change without announcement. This article describes the position as of September 2026. A reader returning to the question in a year should expect a different answer.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016