




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 8, 2026 | NCFA Insight | Artificial Intelligence And Data, Risk Compliance And Regtech, Digital Identity And Trust, Cybersecurity And Fraud, Fintech And Innovation
On July 7, 2026, Lightworks, Scotiabank, Sun Life and TELUS launched The AI Consortium to jointly build critical AI control infrastructure in Canada. Lightworks will operate the consortium’s infrastructure and coordinate deployment across members.
The first project is an Agentic Control Plane, described as a system for enterprise visibility and control across models, agents, users and inference pipelines (think regulated enterprises). Future projects named in the release include an AI Operations Center and AI Token Exchange.
The announcement points to the reality that Canadian regulated enterprises are beginning to pool the control systems they’ll need before agentic AI reaches banking, insurance, telecom, compliance, fraud, advice and operations at scale.
The consortium model solves a practical problem. AI control infrastructure is expensive to build alone. Banks, insurers and telecom firms have similar needs around agent visibility, permissioning, audit trails, inference monitoring, incident response, cyber controls, governance evidence and internal authority.
Building those controls separately inside every firm creates duplicated cost and slower learning.
Pooling engineering, research and governance resources can lower build costs, spread deployment lessons across members and create shared IP that Canadian firms can improve together.
There is also a competitive angle. Large U.S. AI firms are already building control points around cloud platforms, chips, data centres, model access, enterprise tools and distribution. The AI Infrastructure Partnership from BlackRock, Global Infrastructure Partners, Microsoft and MGX was designed to invest in data centres and supporting power infrastructure, with a stated goal of mobilizing up to $100 billion including debt financing.
Canadian firms can buy AI tools from global providers, but the risk is eroding domestic sovereignty as buying isn't the same as control.
If banks, insurers and telecom firms rely entirely on outside platforms for agent permissions, runtime monitoring, audit evidence and governance records, they risk becoming downstream users of systems they can't shape and certainly not control. Shared Canadian infrastructure gives them a way to build capability, retain control knowledge and compete before foreign platforms define how enterprise AI is governed.
Collaboration also creates governance questions. If member firms rely on common systems for agent permissions, policy enforcement, monitoring, logging and deployment standards, that shared system becomes important infrastructure. Governance, failure handling, evidence retention, security incidents, membership, commercialization and Canadian IP will all shape whether the model becomes durable.
Those questions come with any shared system that becomes strategically important.
Traditional AI tools may summarize documents, classify records or support customer service. Agentic systems can act across tools, workflows and data environments, which alters the risk profile.
Companies need to know which agents are active, which models they use, which users can deploy them, what systems they can touch, what actions need human approval, how outputs are logged and how failures are detected.
The consortium’s Agentic Control Plane directly targets that problem by focusing on visibility and control across models, agents, users and inference pipelines.
The UK FCA’s Mills Review examines how AI may affect retail financial services, consumers, firms, markets and regulation. Reuters reported that the review raised concerns around AI driven financial advice, customer harm, fraud, cyber risk and reliance on a small number of technology providers.
Singapore is already more specific on agentic finance. The Monetary Authority of Singapore’s Safeguards for Agentic Finance at Runtime work focuses on how AI agents in financial services can operate safely, securely and reliably.
Regulated firms need more than AI principles. They need controls that define what agents can do, how human oversight is triggered, what gets recorded and how firms respond when something goes wrong.
Scotiabank and Sun Life's participation make this financially relevant.
Agentic AI could eventually support customer service, claims handling, fraud monitoring, compliance workflows, credit support, treasury operations, internal software development and employee productivity. Those are implications, not confirmed consortium use cases.
AI agents in financial services may touch sensitive data, regulated advice boundaries, customer records, third party tools, payment workflows, fraud controls and internal decision processes. The more useful agents become, the more important it becomes to know who approved them, what they accessed, what they did and how exceptions are handled.
Control infrastructure needs to come before wider spread deployment.
The consortium also fits a wider Canadian AI infrastructure theme.
In May 2026, the Government of Canada and TELUS advanced work on sovereign AI infrastructure. That project is separate from the consortium and should not be conflated with it.
Still, the direction is consistent. Canada is trying to build more domestic AI capability rather than rely only on external platforms.
Sovereign AI is not only compute. For regulated sectors, it also means governance systems, audit evidence, agent controls, security practices and operational knowledge that Canadian firms can shape directly.
Industry consortiums usually appear when a problem is too expensive, risky or systemically important for firms to solve alone. Financial services has seen this pattern before in shared utilities, payment systems, identity programs, fraud controls, standards bodies and market infrastructure. AI is entering similar territory because the costs and risks are common across regulated firms.
The consortium structure could create practical benefits, such as common controls, faster security learning, better incident response patterns, shared governance evidence and stronger procurement leverage with external AI providers.
This trend aligns with agentic AI risk and governance, where the core issue isn't only what agents can do, but who controls them. It also connects to regulated AI control gaps around data, vendors, fraud and operational risk.
The financial crime angle is important too. AI, programmable finance and financial crime are converging as bad actors use automation while regulated firms try to strengthen controls.
For NCFA's Financial Innovation Map, the relevant nodes include Agentic Finance, AI Governance, Digital Identity And Trust, Regtech, Cybersecurity And Fraud, Operational Risk, permissioned agents, auditability and sovereign AI infrastructure.
Follow-up questions are whether additional regulated firms join, whether regulators reference the model, whether the AI Operations Center is launched, and how the AI Token Exchange is defined in practical terms.
Will the consortium publish standards, audit methods or governance patterns? Does it commercialize infrastructure beyond founding members? Does it create shared security practices? Does it become a Canadian regulated sector AI utility?
If Canadian firms build shared AI control infrastructure to reduce cost, learn faster and compete with global platforms, who governs the control system once agentic AI becomes critical to banking, insurance and telecom operations?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
 |  |  |
|---|---|---|
 |  |  |
Jul 3, 2026 | NCFA Resource | Regulation And Policy, Banking And Credit, Risk Compliance And Regtech
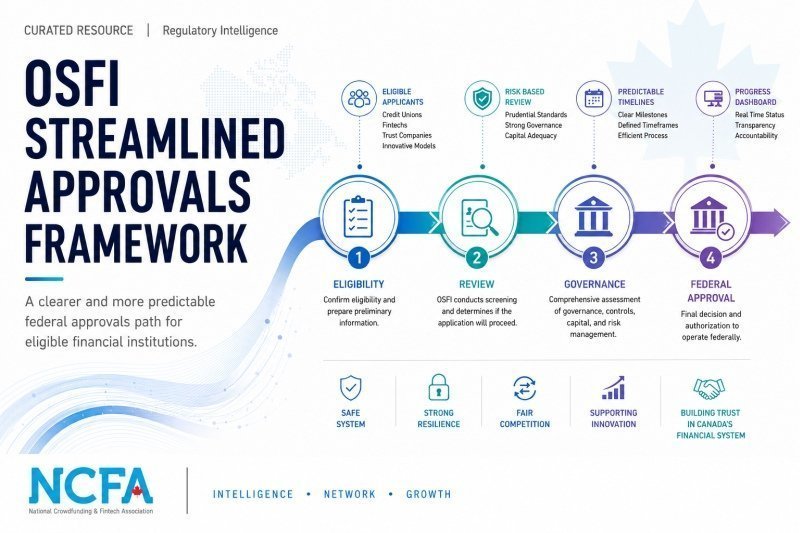
NCFA has published a new Regulatory Intelligence guide to OSFI fast track approvals. The guide explains the official Streamlined Approvals Framework for Targeted New Entrants and how eligible organizations can prepare for federal entry as a bank, trust company, loan company or federal credit union.
It brings OSFI’s framework overview, screening criteria, application requirements, three process phases, indicative timelines, toolkit documents and applicant dashboard into one practical reference.
The guide helps readers understand how OSFI’s Streamlined Approvals Framework is designed to make approvals clearer and more predictable while maintaining prudential standards.
It follows the process from eligibility screening and the initial readiness assessment through formal application review, ministerial approval and operational readiness where an Order to Commence and Carry on Business is required.
The framework currently targets two groups: provincial credit unions seeking federal continuance and entities with technologically innovative or emerging banking models, including fintechs and crypto asset custodians, seeking to incorporate as a bank or federally regulated trust and loan company.
This resource is useful for fintech founders, provincial credit unions, prospective banks, trust and loan companies, crypto asset custodians, compliance teams, investors, legal advisors and organizations assessing federal financial institution status.
It is especially useful for teams evaluating licensing strategy, ownership, governance, capital and liquidity, operational controls, risk management, supervisory readiness and whether federal institution status is commercially justified.
The guide consolidates a detailed approvals process into one applicant workflow. Readers can compare the two eligible routes, review evidence expectations, identify common delay risks and understand where OSFI’s published timelines apply.
The framework is targeted. It is not a general fast track for every fintech, payments company, lender or financial platform. Organizations outside its scope may need other routes, including Retail Payment Activities Act registration, securities registration, provincial licensing or partnerships with regulated institutions.
OSFI may refine the framework as it gains experience and may limit the number of applications processed through it. Readers should use the guide for ecosystem intelligence and planning, not as legal, financial, investment, compliance or professional advice.
OSFI Fast Track And Streamlined Approvals Framework (primary NCFA guide)
OSFI Fast Track Approval Announcement (original NCFA analysis)
Canada Open Banking Rules And Regulations (related Regulatory Intelligence)
Canada’s Stablecoin Regulatory Framework (related Regulatory Intelligence)
OSFI Streamlined Approvals Framework (official framework)
OSFI Launch Announcement (official news release)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Often described as the OSFI fast track, OSFI's Streamlined Approvals Framework gives eligible applicants a clearer route into Canada's federal financial system. It applies to provincial credit unions seeking federal continuance and to entities with innovative or emerging banking models, including fintechs or crypto asset custodians, seeking bank or federally regulated trust and loan company status.
What this guide adds: the official pages, toolkit materials, checklists and process guidance are reorganized into one applicant workflow with interpretation, delay risks, evidence expectations and related intelligence.
This is not a universal fintech route. OSFI limits the framework to two target groups and directs entities outside scope to existing approval processes.
PCUs need an established business model, operating history, provincial supervisory track record, capital capacity, scalable systems, member engagement plan and a viable provincial discontinuance path.
Innovators need a meaningfully different banking model or product, a credible institution destination, financial strength, governance, business plan, risk capability and evidence that federal regulation is needed.
Payment firms, platforms, lenders and vendors may need RPAA registration, securities registration, provincial licensing or partnership models rather than federal institution status.
OSFI publishes stage targets, not a guaranteed end to end timeline. Actual timing depends on applicant preparation, completeness, security checks, statutory decisions and responsiveness.
Rolling intake. Applicant contacts OSFI when ready.
Self-assessment, evidence build and early preparation.
Readiness Assessment letter within 4 weeks after meeting.
12-month OSFI target after complete filing is acknowledged.
Separate statutory decision. No OSFI target stated.
About 3 months where OCCB readiness review applies.
*Phase 3 note: Operational readiness applies where an Order to Commence and Carry on Business is required. For local cooperative credit societies continuing as federal credit unions, Letters Patent and OCCB are issued together.
Budgeting estimate: Where applicable OSFI targets apply, the published target stages add up to roughly 16 months plus applicant preparation, completeness review, security checks, Ministerial decision timing and remediation. This is an expectation management estimate, not an approval guarantee.
Choose the applicant path, then click a step. Each step brings OSFI's requirements together with applicant preparation, timing expectations, source documents, delay risks and Analysis.
Screening is the point where a provincial credit union tests whether the streamlined framework is the correct doorway. The question is not simply whether the organization wants federal status. The question is whether the applicant is already close enough to federal readiness that a targeted, risk-based pathway makes sense.
OSFI is looking for a supervised provincial credit union with an established model, a credible reason to continue federally, an operating history that can be assessed, and a practical path for leaving the provincial framework. The applicant also needs to be prepared for conditions, restrictions or other mitigants at entry where OSFI considers them appropriate.
This is a fit test, not a speed lane. A PCU that cannot explain the strategic necessity of federal continuance, the member value proposition and the readiness plan is likely to spend time and money before the real blocker becomes visible.
Phase 1 lets OSFI review enough information to understand the applicant's ownership structure, financial strength, business plan, governance, federal continuance rationale, readiness gaps and overall suitability before the formal application begins.
The PCU should be ready to disclose its jurisdiction and establishment date, organization chart with ownership percentages, substantial investments, significant interests, voting rights over 10%, ownership distribution, sources of capital for initial and ongoing support, financial services and non-financial activities, three years of audited financial statements, any credit rating, and any prior denials, criminal proceedings or administrative sanctions.
The five-year business plan needs to explain why the applicant wants to continue as an FCU, what transitional relief may be requested, target markets, opportunities, competitors, strategic assumptions, lines of business, product and service integration, risk-based capital and leverage ratios, pro forma financial statements, organizational structure, board and management composition, SMSB categorization, internal capital and liquidity targets, initial exit strategy and the work already performed to prepare for federal continuance.
The four-week target applies after the readiness meeting, not after first contact. The output is a readiness letter that helps determine whether the applicant should proceed and what OSFI expects next.
Phase 1 should expose the real work before the formal application. The strongest applicants will treat it as a board level readiness review across business strategy, capital, member mandate, systems, governance and provincial transition planning.
Pre-meeting evidence build, readiness self-assessment and early gap analysis.
PCUs have a specific member authorization branch because federal continuance affects members and requires a special resolution process. OSFI must approve the Disclosure Notice before the member vote and before Phase 2 materials are submitted.
The PCU has to prepare a member package, draft Disclosure Notice, timing plan, CDIC consultation path and special resolution process that allow members to understand the implications of continuing as an FCU.
This is where the PCU path stops being a regulator-only process. Stakeholder confidence, member education and transition governance matter as much as document preparation.
Member vote sequencing and disclosure package planning.
Phase 2 is the formal review of the application for Letters Patent. It turns the readiness discussion into a complete filing and gives OSFI the evidence needed to make a recommendation.
The PCU package includes the formal application, Canada Gazette and newspaper notice, fees, evidence of member authorization, financial projections, stress cases, business strategy, transition plan and responses to information requests. The 12-month target begins only after OSFI acknowledges the filing is complete.
OSFI is assessing board composition, committee structure, oversight functions, management responsibilities, risk management, related-party arrangements, regulatory compliance management, privacy, fraud controls, records, outsourcing, operational risk, business continuity, disaster recovery, capital adequacy, liquidity and the ability to operate under federal expectations.
The main risk is treating Phase 2 as a document exercise. It is really a proof of supervisability exercise. The filing must show that the institution can operate federally, not just that it can describe federal expectations.
OSFI may recommend approval, but the statutory Ministerial decision remains a separate dependency. This is why OSFI's published stage targets should not be converted into a guaranteed approval date.
Applicants need to keep operating plans, member communications and investor expectations current while the statutory decision is pending. Unresolved conditions, security issues or policy considerations can affect timing and certainty.
Process transparency helps reduce ambiguity, but it does not eliminate statutory discretion. Any external communication should separate OSFI review targets from final approval and launch readiness.
For local cooperative credit societies continuing as FCUs, Letters Patent and the Order to Commence and Carry on Business are issued at the same time. That makes practical readiness part of the formal application build, not a later phase.
The applicant needs completed continuance mechanics, final transition controls, member and provincial transition work, implementation readiness and the ability to operate federally on commencement.
PCUs should not wait for approval to build launch readiness. The pathway compresses approval and commencement, which makes early operating preparation more important.
Federal credit union continuance mechanics.
The applicant enters ongoing federal supervision and must operate with federal expectations for governance, capital, liquidity, risk management, operational resilience, regulatory reporting and compliance.
Approval is the beginning of supervised scale. The commercial value of federal status depends on whether the institution can convert federal reach into durable member value and operational resilience.
Screening tests whether the applicant is actually a targeted new entrant with a technologically innovative or emerging banking model, and whether the proposed destination is a bank or federally regulated trust or loan company rather than a lighter regulatory path.
OSFI is looking for a model that is meaningfully different through operating model, capability, distribution framework, process design, efficiency, cost, speed, resilience, accessibility, risk management or product design. The model also needs to justify entry into the federal prudential perimeter.
The first strategic test is not "is this fintech innovative?" It is "does federal institution status unlock a capability the firm cannot reach faster and more safely through another route?"
Phase 1 gives OSFI a written submission and meeting basis to review the applicant's business model, governance, ownership structure, financial resilience and overall readiness before the formal application.
The innovator should be ready to provide jurisdiction and establishment date, corporate group chart with ownership percentages, 10%+ voting interests, voting or control arrangements, affiliates and activities, Canadian operations, regulatory oversight by jurisdiction, government ownership interests, access to ongoing financial support, three years of audited consolidated financial statements, credit rating if available, prior denials and any criminal proceedings or administrative sanctions.
The five-year business plan should explain why the proposed FRFI is needed, target markets, opportunities, competitors, success assumptions, each line of business, products and services, how lines of business interrelate, liquidity metrics including NCCF and LCR, risk-based capital and leverage ratios on a Basel III basis, five-year pro forma financial statements, reporting lines, senior management responsibilities, board composition, SMSB categorization and an initial exit strategy.
Phase 1 is where a fintech should prove it is institution-ready. Innovation may create the reason to apply, but governance, financial strength, ownership transparency, capital planning and exit credibility determine whether the application can proceed intelligently.
Pre-meeting evidence build and investor/board readiness review.
After Phase 1, OSFI may provide preliminary views that help determine whether the applicant should move toward a formal application under the streamlined framework or use another existing approval process.
The decision is not approval. It is a path decision. A positive signal means the applicant may have enough fit and readiness to justify the heavier formal application. A weak signal may indicate that the model, capital plan, governance, ownership structure or institution destination is not yet credible.
This is the cheapest point to stop, restructure, change the institution destination or choose a partnership route. Treat it as a strategic checkpoint, not an administrative transition.
Deciding whether to advance, pause or switch paths.
Phase 2 is the comprehensive formal review. It converts the Phase 1 business case into a complete application record that OSFI can use to assess whether to recommend approval.
Across new-entrant applications, OSFI assesses whether the applicant has enough resources to support the proposed institution, whether business record and experience are appropriate, whether character, integrity and reputation are acceptable, whether national security or international obligations issues arise, whether the business plan is sound and feasible, whether risks are understood and can be controlled before commencement, whether initial capital protects depositors and creditors, and whether directors and senior officers have the necessary experience and competence.
The formal application needs notices, filing materials, service charge, financial projections, business plan detail, assumptions, stress and contingency analysis, capital and liquidity plan, major asset and liability categories, expense and income categories and evidence that the applicant can fund the regulated institution over time.
The formal checklist brings the applicant into deeper prudential territory: board effectiveness, senior officer roles, risk management framework, operational risk, third party arrangements, privacy, fraud, records, business continuity, disaster recovery, regulatory compliance management and internal controls. The filing should show how the organization will operate, not only who owns it.
The 12-month target begins only after OSFI acknowledges a complete filing. In practice, missing evidence, weak assumptions, unresolved security checks, governance gaps, vendor dependencies, unclear capital support or unconvincing risk controls can extend the elapsed process.
Phase 2 is not a bigger version of Phase 1. It is the proof of supervisability stage. Applicants should run parallel workstreams for capital, governance, risk, security, technology, legal, compliance and operating readiness rather than waiting for OSFI requests one by one.
OSFI may recommend approval, but Ministerial decision-making is a separate statutory dependency. This stage turns the supervisory recommendation into a formal approval decision where applicable.
Applicants should keep capital plans, staffing, vendor readiness, investor communications and public expectations aligned with the reality that OSFI's stage targets do not guarantee Ministerial timing or launch date.
This is where the public dashboard may help with transparency if the applicant consents, but transparency is not certainty. External messaging should separate application milestone, statutory approval and operational launch.
Public milestone tracking if the applicant consents.
Phase 3 confirms whether the applicant is ready to begin business after approval. OSFI reviews whether key people, policies, processes and systems are in place and whether any remaining gaps require conditions, restrictions or remediation.
Applicants should expect to provide evidence such as board and shareholder meeting materials, paid-in capital confirmation, incorporation and organization cost information, commitments around material business plan changes, the OCCB request and evidence that launch-critical systems, people, controls and policies are operating.
This is where paper readiness becomes operating capability. Conditions can shape product scope, geographic scope, growth pace, partnerships, funding needs and early customer strategy.
OCCB readiness and launch-condition planning.
The applicant begins operating as a bank or federally regulated trust or loan company and enters ongoing prudential supervision. The launch is not the end of the regulatory burden; it is the point where the applicant's operating model must meet the promises made through the application process.
Depending on the approved institution type and conditions, approval may enable regulated banking or trust activity, custody and fiduciary services where permitted, deposit or lending activity if approved, or regulated partnership infrastructure.
The commercial case depends on whether the federal status unlocks a durable capability that could not be reached faster through a lighter pathway. The strongest applicants will connect licensing strategy, product strategy, compliance infrastructure and capital strategy before Phase 2.
NCFA’s regulation-to-market pathway shows how OSFI’s targeted approval process can translate into federal market entry, supervised launch and practical innovation opportunities.
Regulatory approval is only one part of market development. This guide connects to NCFA's broader Financial Innovation Map, which organizes innovation capabilities, market opportunities, companies, evidence, milestones and regulatory intelligence across Canada's fintech ecosystem.
The OSFI streamlined approvals framework is a high bar pathway for targeted new entrants. It does not create a general fintech fast track. Where an applicant qualifies, the framework may connect to market themes such as credit union modernization, regulated custody, trust infrastructure, governance technology, SME finance infrastructure, open finance and business identity.
Use these links to go deeper into adjacent regulation, market entry strategy, resources and evidence connected to federal financial system entry.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Feature | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealthtech And Investing, Risk Compliance And Regtech, Fintech And Innovation

Tokenized funds are past the easy headline.
The first question was whether fund shares could be represented onchain. That answer is already visible across tokenized treasuries, money market funds, private credit, institutional credit, and fund wrappers.
The harder question is whether regulated fund shares can work across chains, collateral markets, stablecoin reserves, DeFi venues, and treasury workflows without breaking the fund rules that make them investable in the first place.
A June 2026 LayerZero and Centrifuge report frames that next milestone around composability. The report argues that issuance is largely done and the next phase is whether tokenized funds can preserve NAV discipline, settlement rules, compliance controls, fund accounting, and transfer restrictions while reaching more onchain markets.
That is the real tokenized fund story. It's not about the token, but the operating model.
Stablecoins are built around continuous pricing. A dollar backed token is supposed to hold close to one dollar, and market participants can usually observe pricing in real time.
Fund shares work differently.
A tokenized treasury fund, private credit fund, institutional credit product, or equity index fund depends on net asset value. NAV may be calculated daily, weekly, monthly, or on another cycle. Investors subscribe and redeem through fund processes. Redemptions can be queued. Pricing can be batch based. Transferability can depend on investor status, jurisdiction, holding periods, and fund documents.
That difference may sound technical, but it changes everything.
A tokenized fund share cannot be treated like a freely transferable stablecoin if the fund still has to respect pricing cycles, investor eligibility, compliance limits, and accounting rules. A transfer across chains isn't just a simple token movement from A to B. It's also a fund record, a compliance event, and a possible accounting update among other future requirements.
The report’s strongest section is its discussion of NAV and pricing across chains.
If a fund share exists on several chains, every venue needs the same fund state. NAV updates have to reach each chain. Subscription and redemption requests need to flow into one fund process. Assets in transit between chains must not distort the fund’s accounting.
The report warns that a tokenized fund can technically travel across chains and still be mispriced if the operating controls are weak. It also points to stale price risk, where investors could receive different economics depending on which chain has the current NAV and which one still has old pricing.
That's why tokenized fund composability is harder than basic bridging.
A fund issuer isnt only asking whether the token can appear on Ethereum, Base, Arbitrum, Solana, or another network. The issuer has to ask whether pricing, compliance, settlement, and fund records stay synchronized when investors use different chains.
That is the kind of detail most tokenization commentary skips.
Regulated fund shares come with rules.
LayerZero and Centrifuge propose a hub and spoke model. One hub chain holds the authoritative fund state. Spoke chains handle local distribution. The hub handles functions such as accounting, pricing, share class management, investment processing, redemption processing, and policy enforcement.
That design is useful because it describes a problem the market has to solve, even if another provider uses a different architecture.
If compliance updates have to be manually replicated across every chain, the operating burden grows quickly. If a fund manager can update rules once and have NAV, transfer restrictions, allowlists, and accounting propagate from one source of truth, multi chain fund distribution becomes easier to manage.
RWA.xyz lists tokenized U.S. government debt at about $14.86 billion. The LayerZero and Centrifuge report cites broader RWA assets above $30 billion, with U.S. Treasuries around $15 billion and private credit near $6 billion.
Franklin Templeton’s OnChain U.S. Government Money Fund provides another reference point. Franklin says the fund invests at least 99.5% of assets in U.S. government securities, cash, and fully collateralized repurchase agreements. The fund listed $813.5 million in total net assets as of May 31, 2026.
WisdomTree is also testing fund liquidity in a new way. WisdomTree said SEC exemptive relief lets it support 24/7 trading and instant settlement for tokenized money market fund shares against USDC.
These are examples of a wider trend. Tokenization is finding scale in collateral and cash, where fund shares, money market products, and tokenized treasuries can support treasury management, collateral mobility, and settlement use cases rather than simply sit in a wallet.
Tokenized funds are no longer only about representing assets onchain. They are testing liquidity, settlement, collateral, treasury, and distribution models that conventional fund systems were not designed to support.
The LayerZero and Centrifuge report identifies stablecoin reserve strategies as one of the clearest use cases for tokenized funds.
Stablecoin issuers need reserve assets that are liquid, low risk, auditable, and productive enough to support yield strategies where permitted. Tokenized treasury and institutional credit funds can exist closer to the onchain systems where stablecoins already circulate.
While it doesn't mean every stablecoin reserve should become a DeFi strategy, it means tokenized funds are becoming more relevant where cash, collateral, settlement, and yield meet.
BlackRock’s stablecoin reserve push shows the same market pull from another direction. Institutional asset managers want tokenized cash products to serve digital dollar users who need regulated yield and liquidity rather than idle balances.
This is where fund composability becomes a business issue. A tokenized fund that can’t support reserve operations, collateral use, redemption timing, and compliance controls will struggle to serve the markets now asking for it.
Open DeFi composability clashes with regulated fund controls.
A fund cannot simply let any wallet hold, transfer, pledge, wrap, or trade its shares if those shares remain subject to securities rules, investor restrictions, transfer limits, or fund documents.
The report describes two ways to manage the tension.
The first is permissioned market structures. The fund share stays inside a controlled environment, while approved participants build lending, repo, collateral, or liquidity functions around it.
The second is deRWA style wrapping. A compliant fund share can sit inside a controlled wrapper, while another token gives DeFi users exposure to the economic position. That structure can separate compliant origination from wider DeFi distribution, but it also creates new questions about risk, transparency, liquidity, and investor understanding.
If wrappers make regulated fund exposure more usable, they may expand distribution. If wrappers hide too much complexity, they may create new conduct and disclosure problems. The market needs clarity on what investors hold, who controls redemption, how NAV is calculated, and what happens when liquidity disappears.
IOSCO’s 2025 tokenization report provides useful balance. It says tokenization may improve settlement, collateral mobility, transparency, and operational efficiency, but it also identifies risks tied to market integrity, investor protection, settlement assets, token representation, DLT dependency, and links with crypto markets.
Tokenized funds aren't automatically safer because they are onchain. They may reduce some frictions while introducing others. Smart contracts can improve automation, but fund administration still needs legal accuracy, investor records, custody, valuation controls, reporting, redemption rules, and oversight.
IOSCO also notes that adoption remains limited and that efficiency gains are uneven. That is a good reality check of the hype. Tokenized funds may be entering a more serious phase, but they still need credible settlement assets, interoperability, and operating controls before they can scale across mainstream capital markets.
The practical question for regulators is not whether tokenization is good or bad. The question is which parts of the fund process can become programmable without weakening investor protection or market integrity.
Canada’s tokenization discussion often starts with issuance, digital securities, and investor access.
But there's a deeper question for Canadian capital markets to answer. Can fund operations keep up?
That includes transfer agency, dealer controls, exempt market distribution, custody, compliance records, NAV operations, stablecoin settlement, investor reporting, tax records, and secondary liquidity. If those pieces remain fragmented, tokenized funds may exist onchain without becoming more useful to issuers or investors.
This also fits existing NCFA question work around tokenized RWAs and market infrastructure. The next advancement is whether regulated fund shares can become usable across venues while preserving the rules that make them credible.
It also fits NCFA’s Financial Innovation Map, including tokenized funds, transfer agents, compliant distribution, fund administration, tokenized collateral, stablecoin reserves, and capital markets technology.
The next phase of tokenized funds will be less glamorous than issuance.
It will involve NAV propagation, compliance messages, investor record synchronization, redemption queues, settlement timing, chain specific distribution, custody controls, and fund accounting.
That is where real opportunity is currently.
Tokenized funds will scale if the fund machinery underneath them can support pricing, settlement, compliance, and investor protection across the places where demand is forming.
If tokenized funds now need NAV, compliance, settlement, and investor records to work across chains, will the biggest opportunity belong to issuers or to the companies building the fund plumbing underneath them?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 6, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech, Fintech And Innovation
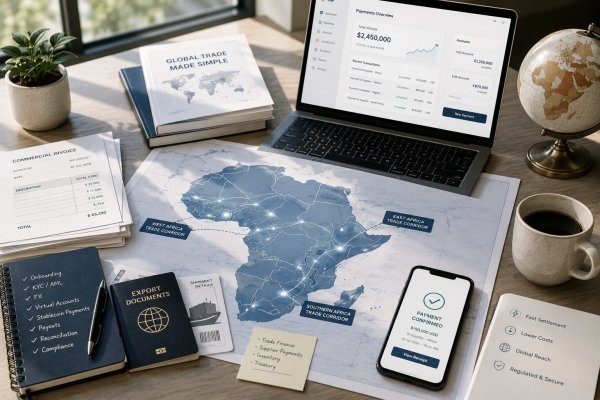
On July 1, 2026, Noah and Cedar announced a partnership to support compliant stablecoin payments between Africa and global markets.
Noah brings stablecoin payment APIs, named USD and EUR virtual accounts, programmable payouts, and global settlement. Cedar brings onboarding, FX, liquidity, KYC, AML, sanctions screening, PEP checks, and African payment corridor access.
The companies say testing is complete and live transactions are underway. This isn't another stablecoin demo. It's a payment product entering real business use cases and workflows.
A company moving money between Africa and global markets needs more than token transfer. It needs verified customers, usable accounts, FX, payout options, transaction monitoring, compliance records, and reconciliation.
Africa is a strong test market because the payment problem is real (Read: opportunity).
The IMF says Nigeria received about $59 billion in crypto asset inflows between July 2023 and June 2024 and accounts for roughly 60% of stablecoin inflows in Sub Saharan Africa since 2019.
The IMF also says stablecoins let users receive remittances or make cross border payments in minutes, often at lower cost than traditional channels. The cost gap is hard to ignore. The average cost of sending US$200 to Sub Saharan Africa remains around 9%, compared with a global average of about 6%, according to IMF analysis reported by Reuters.
That doesn't automatically mean stablecoins are a clean fix. The IMF also warns about digital dollarization, illicit finance risk, weaker visibility for regulators, and pressure on domestic currency policy. But adoption and user demand isn't a mystery. When payment rails are slow, expensive, or hard to access, businesses and households look for another path.
Cedar’s role is what makes the partnership more relevant for regulated fintech markets.
Cedar says it is registered with FINTRAC in Canada, FinCEN in the United States, and is also under Canada’s Retail Payment Activities Act. Its site also describes support for payments across 190+ countries and collections from 9 African markets.
That regulatory footprint gives the announcement a Canadian angle. Cedar isn't only an Africa corridor operator. It is also building under Canadian payment supervision at a time when Canada’s RPAA regime is bringing more payment service providers into formal oversight.
Noah’s African activity isn't limited to Cedar.
In January, Noah and NALA launched a stablecoin settlement network for emerging markets, with instant USD settlement, real time local currency payouts, 24/7 treasury, and compliant flows between digital dollars and local money.
In March, Noah and Nafolo partnered to bring stablecoin powered virtual accounts to Sub Saharan Africa, targeting cross border payment friction for remote workers, students, families, and businesses. Noah said the partnership aimed to support more than 500,000 users.
Cedar adds another piece to this venture with regulated onboarding, compliance, FX, and African trade payment access. Together, these partnerships show Noah building around corridors where stablecoins can solve a real payment job.
For Canadian fintechs, the useful lesson is not that Africa is “ahead” or that stablecoins replace regulation. The lesson is that adoption starts where the payment job is painful enough.
African trade corridors show that clearly. Businesses need to collect money, convert currency, pay suppliers, manage treasury, verify counterparties, and keep records across borders.
A stablecoin transfer is only one component. The commercial product itself is the bundle around it with virtual accounts, FX, compliance, treasury, payouts, reconciliation, and support for local payment endpoints.
Africa is an important test case because payment pain points are sharper, so the adoption incentive is stronger.
That connects directly to Canada’s stablecoin regulatory framework and programmable stablecoin payments. The product opportunity isn't token transfer by itself. It's software that makes cross border money movement easier to operate.
If stablecoin payments work best when compliance, FX, virtual accounts, and payouts are bundled together, will African trade corridors become one of the clearest markets for real business adoption?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure

NCFA has published a comprehensive guide to stablecoin regulations in Canada. It brings together the Stablecoin Act, Bank of Canada supervision and the related requirements administered by FINTRAC, Canadian securities regulators, OSFI and FCAC.
The guide explains how Canada’s framework may affect stablecoin issuance, reserve management, redemption at par, governance, data security, trading platform access, payment activity, custody and consumer protection.
Canada has enacted the Stablecoin Act, but its substantive requirements are not yet in force. Supporting regulations, registration mechanics and Bank of Canada implementation materials remain under development.
The resource organizes Canada’s stablecoin requirements as a connected regulatory framework.
A single stablecoin business model may involve several legal and supervisory layers. Depending on its activities, a firm may need to assess issuer registration, money services business obligations, payment service provider requirements, securities rules, custody controls and prudential treatment.
The guide covers:
This resource is designed for stablecoin issuers, fintech founders, crypto platforms, custodians, payment companies, banks, compliance teams, investors, policymakers and market infrastructure providers.
It is particularly useful for teams assessing:
The guide’s principal strength is its integrated view of Canada’s regulatory structure. Readers can identify which authorities are involved, what Parliament has enacted and which implementation questions remain unresolved.
It also connects regulation with market development. Clear rules for reserves, redemption, custody and compliance could support tokenized financial infrastructure, stablecoin payments and institutional settlement services.
Firms can use the guide to begin preparing legal perimeter assessments, issuer control maps, reserve policies, governance models, data security plans, redemption procedures, AML files and Bank of Canada engagement materials.
Canada’s stablecoin regime is still under development. The guide provides regulatory intelligence and planning support, but it is not legal, financial, investment, compliance or professional advice. NCFA will update the Regulatory Intelligence page as regulations, supervisory materials and implementation dates are confirmed.
Stablecoin Regulations In Canada (primary NCFA Regulatory Intelligence guide)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Finance Canada Stablecoin Framework (primary government source)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking, funding opportunities and services to thousands of community members. NCFA works with industry, government, partners and affiliates to support a vibrant and innovative fintech and funding industry in Canada.
Decentralized and distributed, NCFA engages with global stakeholders and supports projects and investment across fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets, tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech.
Join Canada’s Fintech & Funding Community free, or become a contributing member to receive additional benefits. Visit NCFA Canada for more information.
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016