





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 15, 2026 | NCFA Insight | Artificial Intelligence And Data
On May 1, 2026, the Academy of Motion Picture Arts and Sciences announced Oscars rules requiring human performed acting and human authored screenplays. The Academy didn’t ban AI tools, but rather protected human creativity at a time when synthetic performers, AI music, and digital personas are iterating live in mainstream culture. The questions are who gets credit, who gives consent, who gets paid, and who takes responsibility when AI is the engine inside the creative process.
In March 2026, AI generated performer Tilly Norwood gave the Oscars restriction a real world stress test by launching a music video called “Take The Lead”. While a human team is behind the creation, the video clearly features a synthetic artist as the visible performer. People designed the character, shaped the concept, guided prompts, edited outputs, and built the persona around the performance.
The production apparently started with a notice stating it was made by “18 real humans” including production designers, costume designers, prompters, editors, and an actor.
Futurism reported that Suno generated the song and Particle6 used performance capture from Eline van der Velden’s acting performance. That means the audio came from an AI music tool, while a real person performed the movements, expressions, or acting choices that helped animate the synthetic Tilly Norwood character on screen.
As synthetic personalities improve, creative credit gets harder to assign. The audience sees the AI performer first while the human labour is more difficult to see. Was the performer the AI character, the actor behind the capture, the director, the prompt team, the studio, the model provider, or the person who shaped the concept?
Futurism called the video “one of the dingiest and depressing things we’ve ever seen.” Viewers also pushed back on the unusual visuals, processed vocals, and pro AI message cutting through the hype.
Bottom line is AI can make more content, faster, but it can’t make audiences care by default.
Creative markets still reward taste, originality, trust, and a sense that real people stand behind the work. As synthetic content spreads, proof of origin, consent, and accountability will likely become part of the product.
Financial services already depends on verified identity, trusted records, permissions, approvals, and auditability. AI raises the stakes because automated agents and AI generated advice and support can blur the line between human and software activity.
A customer may not know whether they’re reading human advice, AI assisted advice, or fully automated output. A compliance team may need to prove who approved a model generated communication. A marketplace may need to verify whether a creator, advisor, vendor, or agent is real. A lender, insurer, or investment platform may need a reliable record of how an AI system influenced a decision.
The Academy’s new rules don’t reject AI. They protect human recognition inside AI assisted creation. Tilly Norwood shows why the boundary won’t stay clean. The battle line is who gets credit, who gets paid, who gives consent, and who is responsible when synthetic work enters the market.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 13, 2026 | NCFA Resource | Risk Compliance And Regtech, Digital Identity Privacy KYC AML ATF
On April 8, 2026, the UK FCA published customer due diligence (CDD) findings from a multi firm review. The review covers practical weaknesses that matter to fintech teams, including thin policies, unclear review cycles, weak evidence records, poor senior approval steps, and audit gaps.
This is a UK resource, but the operating lessons travel well. Canadian fintechs still need local legal and compliance advice, including FINTRAC obligations where applicable. The FCA shows where customer checks break down when firms grow, add automation, rely on vendors, or treat onboarding as a sales funnel instead of a risk control.
The FCA review gives compliance and product teams a useful checklist for testing how customer due diligence works inside the business. It doesn't just ask whether a policy exists. It looks at whether staff know what to collect, when to escalate, how to record decisions, and how often files need review.
Stronger firms clearly separate standard CDD from enhanced due diligence (EDD) for higher risk customers. They define when senior approval is needed. They document EDD steps, keep review cycles clear, and test whether onboarding files support the risk decision made at the time.
The weaker examples are just as useful. The FCA points to firms that could not show what extra checks were completed for high risk customers, did not record key information about the purpose of a business relationship, lacked clear review schedules, or used the same people to onboard customers and review their own work.
For fintechs, fast onboarding can become a liability when the business cannot prove why a customer passed, why a file received extra review, or who approved a higher risk relationship. Policies are no longer enough, as teams need evidence.
This resource is useful for fintech founders, compliance leads, money laundering reporting officers (MLROs), onboarding teams, product managers, payments companies, lending platforms, crypto firms, crowdfunding portals, regtech providers, and financial institutions reviewing digital account opening.
It is especially relevant for firms that use automated onboarding, AI assisted reviews, third party identity vendors, risk scoring tools, or outsourced compliance support. Those tools can improve speed, but companies still needs clear accountability, review rules, exception handling, and audit trails.
The strength of this resource is its practical format. It shows good and poor practice side by side. That makes it easier for a fintech team to compare the report against its own onboarding journey, file review process, vendor controls, and board reporting.
The review also makes a simple point that many growing firms miss. Regulators want to see how decisions happen in real life. A clean policy document doesn't help much if customer files are thin, staff guidance is vague, or senior approval only exists in theory.
The limit is geography. The FCA findings reflect UK regulation and UK supervisory expectations. Canadian firms shouldn't treat this as Canadian legal guidance. They should use it as a practical benchmark, then test their own controls against Canadian requirements, sector rules, and legal advice.
FCA Customer Due Diligence Findings (primary FCA resource with good and poor practice examples)
FCA Risk Assessment Controls Findings (companion FCA review on customer and business risk assessments)
FCA 2025 To 2030 Strategy (broader strategy context for financial crime supervision)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech
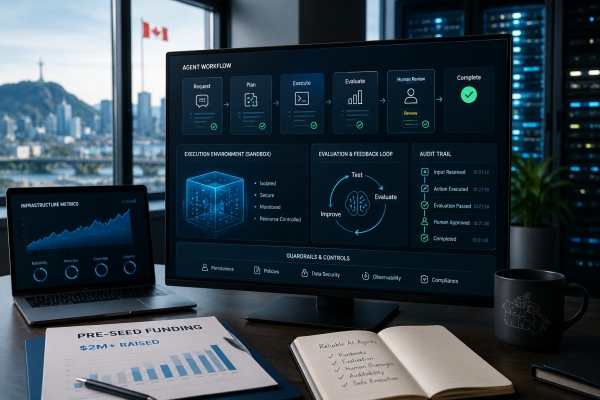
On May 6, 2026, Montreal based Jetty raised over $2 million in pre seed funding to build infrastructure for reliable agentic AI applications. AQC Capital and Hidden Layers Capital led the round. Mila Ventures, Akinox, and strategic angel investors with AI systems experience at Google and Meta AI also joined. While the round is early, the production problem is already very real.
Jetty is targeting the gap between AI agents that work in demos and agents that can handle enterprise workflows. Jetty's platform gives agents structured runbooks, isolated execution environments and evaluation loops. The agent gets a defined job, runs in a controlled space, checks the result, and improves with human oversight. It's operating infrastructure for AI work that has to be repeatable, observable, and safe enough to review.
Jonathan Lebensold, Founder and CEO, Jetty
“Most AI systems today are still fragile - they work in isolation but break under real-world complexity,”
Gartner predicts that over 40% of agentic AI projects will be cancelled by the end of 2027 because of rising costs, unclear business value, or weak risk controls. McKinsey’s 2025 global AI survey found that 23% of respondents are scaling agentic AI in at least one business function. Another 39% are experimenting.
These numbers explain Jetty's opening. Enterprises want to implement agentic AI, but they need proof before they let agents touch real workflows. Buyers need agents they can test, limit, monitor, correct, and review. This type of rigorous testing isn't optional in finance, insurance, health, and public services to name a few.
Doina Precup, Professor at McGill University and CIFAR AI Chair:
“As AI systems become more autonomous, ensuring they behave reliably in complex environments becomes a central challenge.”
Financial institutions will only use and trust AI agents when the workflow transparently shows what happened, who approved it, and how mistakes get corrected.
Controls matter in onboarding, fraud review, compliance checks, and underwriting. They also matter in customer support, reporting, and internal operations. If an agent makes a mistake, teams need to see the inputs, how the tool used the inputs, the outputs, approvals, and any corrective actions.
The near term opportunity isn't just replacing staff with free running agents. It's reducing manual drag in workflows where humans still own the decision. That lines up with governed AI workflows in finance, where the value comes from evidence, reviewability, and accountability.
Canada has deep AI research talent, but productivity gains depend on companies that turn research into owned enterprise infrastructure. Reliable agent systems could become part of that. If Canadian firms build tools for evaluation, audit trails, controlled execution, and human review, they can own more of the AI workflow stack instead of only using tools built elsewhere.
This is still an early stage round, but the production problem is real. Jetty hasn't disclosed revenue, customer metrics, deployment volume, or reliability benchmarks. The company says it will use the funding to accelerate product development, expand engineering, and support enterprise customer deployments. That is the right use of proceeds, but the market will need proof that Jetty can make agents reliable in regulated workflows, not just promising in pilots.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 13, 2026 | NCFA Fintech Market Activity | Wealth Capital Markets And Investing, Risk Compliance And Regtech, Artificial Intelligence And Data
On May 12, 2026, U.S. wealthtech platform Envestnet expanded its Canadian B2B push with new platform capabilities, local leadership, and advisor tools tied to Canada’s Total Cost Reporting (TCR) rules. Those rules will require firms to show clients the full cost of investment solutions in dollar terms beginning in 2027. As a result, advisors need better portfolio evidence, cleaner reporting, and stronger tools to explain value.
In 2020, Envestnet announced that it expanded its Canadian footprint through a strategic partnership with Canaccord Genuity Wealth Management. In March 2025, it launched a direct indexing solution for Canadian advisors that can sit inside a Unified Managed Account (UMA). Now the recent 2026 announcement adds a regulatory catalyst with Total Cost Reporting turning fee transparency into daily advisor work.
Canadian regulators have been building toward this for years. In April 2023, the Canadian Securities Administrators and the Canadian Council of Insurance Regulators announced enhanced cost reporting requirements for investment funds and segregated fund contracts. The goal is simple. Investors should see the ongoing costs of owning funds more clearly, both as a percentage and as an aggregate dollar amount.
CIRO’s enhanced cost reporting amendments took effect on January 1, 2026. Starting in 2027, clients will receive annual reports for the 2026 calendar year that show more detail on investment fund costs. That includes fund expenses in dollars and fund expense ratios.
For advisors, it changes the client conversation because they'll need to explain what clients paid, why they paid it, and how the portfolio supports the client’s goals.
Envestnet is building its Canadian offer around Unified Managed Accounts, multi currency portfolios, data insights, and model based portfolio construction. It also promoted David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, to lead strategic relationships and Envestnet’s Canadian wealthtech business.
David Kamerman, CFP®, Principal Director, Head of Canadian Business Development, Envestnet:
“As Total Cost Reporting reshapes the industry, advisors need practical ways to modernize how portfolios are constructed and managed. Our Unified Managed Account platform empowers advisors to build model-based, cost-conscious, high-conviction portfolios at scale helping them deliver stronger client outcomes while running more efficient businesses.”
Unified Managed Accounts are useful because they can bring different investment sleeves into one account structure. That can help advisors combine models, direct indexing, tax aware customization, and cost reporting without stitching together too many tools.
Envestnet launched its Canadian direct indexing service in March 2025. Canadian registered firms can use it by hiring Envestnet as a sub advisor. Direct indexing gives advisors more control over tax treatment, exclusions, personalization, and security level portfolio design. Under TCR, that control becomes easier to explain because advisors can connect cost, portfolio design, and client goals.
TCR benefits companies that connect cost transparency with better portfolio construction. Conversely, TCR exposes firms that only add a report after the fact.
The Canadian wealthtech market already has strong local competition. In March 2026, Calgary based OneVest launched an AI native wealth operations platform for onboarding, account opening, money movement, billing, documents, and advisor workflows. That gives Canadian firms a modular option built closer to domestic needs.
Envestnet brings scale. The company says it has 25 years of operating experience, $7.0 trillion in platform assets, and relationships with more than one third of financial advisors across banks, wealth managers, brokerages, and RIAs. Scale helps, but Canadian firms will still judge the platform on integration, usability, reporting quality, support, and cost.
Envestnet says it has a growing pipeline in Canada, but it does not disclose key metrics or direct indexing uptake.
TCR is a regulation that creates software demand as it changes the daily work of advisors who need better data, clearer reporting and stronger client conversations. As Total Cost Reporting makes investment costs more visible, will Canadian wealth firms compete on lower fees alone, or on better portfolio design, clearer value, and stronger advisor technology?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 12, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
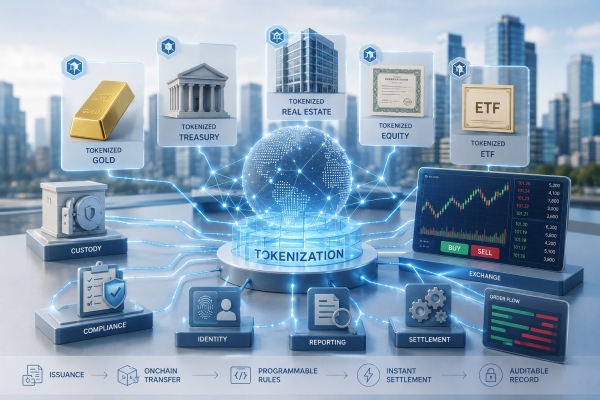
On May 4 2026, CoinGecko published its 2026 RWA Report, and the numbers tell a more interesting story than usual.
But here’s the unusual part. Most major RWA project tokens didn't benefit from that growth. CoinGecko found that six of the top seven RWA project tokens posted negative returns from January 1 2025 to March 31 2026, with losses ranging from 44.7% to 98.8%.
Tokenized assets are gaining traction, but the report shows a clear split. The market is growing around the systems that make tokenized assets useful, such as access, custody, liquidity, collateral, compliance, and distribution. It's not showing the same strength in the project tokens that investors once used to bet on the RWA theme.
Tokenized RWAs are growing quickly, but they still equal only 6.4% of the stablecoin market. Stablecoins grew from $199.77B to $301.65B during the same period.
It's a significant gap because BlackRock Targets Stablecoin Reserve Market in digital finance to help money move, settle trades, and flow collateral between platforms. Tokenized assets are building on that base, not replacing it.
The report also shows a clear preference for more institution friendly products. USDC grew 76.2% to $77.44B, while smaller regulated or compliance focused stablecoins also gained ground. That says demand is heading toward products that platforms, institutions, and regulators can actually work with.
Tokenized treasuries still lead the category, growing from $4.00B to $12.99B over the report period. But their market share fell from 73.7% to 67.2% as commodities, tokenized stocks, ETFs, and derivatives gained traction.
For much of the last cycle, Real World Assets mostly meant tokenized treasury products. Now the category is widening into broader market exposure.
Tokenized stocks scaled from $2.09M in June 2025 to $486.69M by March 2026. Tokenized ETF market capitalization reached $297.50M. The numbers are still very small compared to traditional markets, but are trending.
Tokenized commodities grew from $1.43B to $5.55B, driven mainly by gold backed products including PAXG and XAUT. The trading activity is telling. Tokenized gold recorded $90.70B in spot trading volume during Q1 2026, already higher than the full 2025 total of $84.64B.
That makes sense given gold's familiarity. It has deep global demand and already plays a role in portfolios and collateral conversations. Tokenization gives it faster movement, digital custody options, and easier access across crypto native platforms.
The report shows how quickly centralized platforms, such as Kraken, Coinbase, Crypto.com, Binance or Gate are now combining some mix of tokenized securities, stocks, ETFs, commodities, futures, perps, or licensed financial infrastructure alongside crypto trading.
The lines between crypto exchange, broker, derivatives venue, and tokenized asset marketplace are getting thinner. That raises the operating bar. It's also where major infrastructure opportunities start to appear.
RWA perps generated $524.79B in Q1 2026 trading volume alone, while daily open interest rose from $0.14B at the start of 2025 to $6.68B by March 31 2026.
The data suggests that many traders want exposure to real world asset prices without necessarily holding the underlying tokenized asset. Commodities still dominate this market, but stock and ETF perps are growing. Hyperliquid’s HIP-3 volume rose from $12.65B in Q4 2025 to $130.87B in Q1 2026.
This is trading infrastructure forming around tokenized and traditional assets at the same time.
CoinGecko’s report shows a tokenized asset market growing quickly, but unevenly. Tokenization is becoming infrastructure. Stablecoins still do the heavy lifting. Treasuries still lead. Gold trading volume has surged. Exchanges are adding capital markets functions. RWA perps are scaling quickly. At the same time, most RWA project tokens continue falling.
Tokenization is starting to look less like crypto hype and more like financial infrastructure that can make tokenized assets useful, compliant, liquid, and easy to access at scale.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 12, 2026 | NCFA Feature | Digital Banking And Credit Union Infrastructure

On May 12 2026, Intellect Design Arena announced that 37 Canadian financial institutions participating in the National Digital Banking Working Group (NDBWG) selected its eMACH.ai Digital Engagement Platform as part of a broader digital banking modernization effort.
This is more than a software contract. It's one of the clearest examples of smaller Canadian financial institutions coordinating technology execution to manage platform risk, modernization costs, and rising digital banking expectations.
Back in October 2024, Canadian credit union infrastructure provider Central 1 announced plans to wind down digital banking over a three to four year transition period. That created immediate pressure for many Canadian credit unions that relied on Central 1’s Forge and MemberDirect platforms.
In March 2025, Central 1 and Intellect finalized an operating partnership that transferred operation of Forge, MemberDirect, public website, and mobile app products to Intellect, along with digital banking engineering and service personnel.
The latest announcement now evolves beyond transition support into long term modernization.
The National Digital Banking Working Group formed after the Central 1 announcement to help participating institutions coordinate vendor evaluation, migration planning, procurement, implementation support, and governance.
According to NDBWG's website, the initiative was designed to help financial institutions navigate a system wide platform transition together instead of individually carrying the cost, risk, and operational complexity of replacing digital banking infrastructure. It's a coordinated modernization program.
NDBWG’s public member page lists 59 participating institutions across British Columbia, Alberta, Saskatchewan, Manitoba, and Ontario. The specific 37 institutions that formally signed with Intellect is likely a subset. Intellect states the participating institutions represent more than $11.7B CAD in combined assets and serve over 262,000 members.
Greg Sol, Board Chair, Credit Unions Future Committee:
“Building on the NDBWG’s rigorous process from vendor evaluation to a fully negotiated agreement, we’re confident that Intellect is the right long-term partner for Canada’s financial institutions.”
Canada’s banking competition debate often focuses on large banks and fintech challengers. Less attention goes to the infrastructure pressure facing smaller regional and community based financial institutions.
Members compare their credit union app with all other digital services they use daily. They expect simple onboarding, quick support, fewer branch visits, and secure ways to handle routine requests. Behind that experience, smaller institutions also face heavier compliance work, sharper fraud risk, and technology costs that keep climbing. For many smaller institutions, maintaining those capabilities independently becomes harder every year.
NDBWG’s model attempts to create digital scale without forcing consolidation. Participating institutions keep their local brands, governance, and member relationships while coordinating around infrastructure, migration planning, and platform execution.
The stronger advantage of a shared approach isn't the software itself, but rather the emerging operating model around it.
Canada already has one of the most concentrated banking systems in the world. If smaller institutions cannot modernize efficiently, the competitive gap widens further. Shared infrastructure and coordinated execution may become one of the few realistic ways for regional financial institutions to stay competitive without dramatically increasing operating costs.
Canada continues preparing for consumer driven banking, stronger fraud controls, and real time payments modernization. Those changes place additional pressure on legacy systems and fragmented operating models.
Steve Kingan, CEO, Frontline Credit Union:
“The NDBWG process gave our credit union the expertise and collective strength to navigate this transition in a way we couldn’t have managed alone.”
For fintech companies, this may also create opportunity. Smaller institutions need practical tools that reduce daily friction, protect members, and improve service without adding complexity. That creates room for focused partners in fraud prevention, digital identity, payments, workflow automation, AI assisted service, and embedded financial services tailored for smaller institutions.
It also explains why more vendors are building Canada ready digital banking platforms for credit unions rather than treating them as small versions of large banks.
Canada’s smaller financial institutions are starting to treat digital infrastructure as a shared strategic capability instead of a fully independent function.
NDBWG represents one of the clearest Canadian examples so far of institutions coordinating modernization to support local financial competition while reducing migration risk and operational cost. If implementation succeeds, it could become a practical model for how smaller financial institutions modernize in other parts of Canada.
Can smaller Canadian financial institutions can build enough shared digital scale to remain competitive while preserving regional and community based banking choice?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 8, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Regulation And Policy, Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Cybersecurity Fraud And Financial Crime

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026).
Reduced margin rules shape leverage, dealer inventory financing, and how quickly exposure can build when markets heat up. Keeping crypto funds out of reduced margin leaves higher friction on leveraged crypto fund exposure even as crypto and tokenized market infrastructure moves closer to mainstream rails.
Canada’s stablecoin framework is moving from legislation into implementation timing. Issuers, custodians, exchanges, payment firms, and banks should plan for a 2027 rulebook while watching how reserve assets, redemption rights, supervision, and payment use cases get defined. See Canada’s First FI Issued CAD Stablecoin Launches and Stablecoins Split Into Issuance And Service Layers
Claims management is moving into a tougher conduct and perimeter review. Firms using lead generation, social ads, outsourced claims workflows, or high volume complaint models need clean consent, fair pricing, clear authority, and evidence that customers understand what they are signing.
Climate disclosure is moving from delayed implementation toward formal rollback. Public companies, reporting platforms, auditors, and ESG data providers should watch the proposal text, because the next decision point is whether climate risk disclosure becomes narrower, materiality driven, or removed from SEC rule requirements.
May 6, 2026, Canada and South Korea
Stablecoin adoption won’t only depend on reserves, licences, and payment use cases. It will also depend on how issuers protect minting, burning, settlement authority, custody permissions, and administrative controls as quantum risk becomes an infrastructure planning issue.
Regional banks are looking for third party digital asset infrastructure instead of building it from scratch. For Canadian credit unions, regional banks, and bank technology providers, stablecoins and tokenized deposits are becoming a bank distribution question, not just a crypto platform product.
Tokenized securities are moving into issuer services and transfer agency. The next control point is not only trading. It is who manages shareholder records, corporate actions, voting, dividends, custody links, and settlement between public companies and investors.
This is an early bank participation signal, not a final product launch. European banks are expanding a shared euro stablecoin effort before formal updates expected later in the year. For fintechs and payment firms, the read through is practical: euro stablecoin access may develop through regulated bank networks, not only crypto native providers.
Tokenized securities are moving into DTC’s production roadmap. That changes the question from whether tokenized assets can exist to whether brokers, custodians, issuers, and trading venues can plug tokenized ownership into existing post trade infrastructure without weakening rights, controls, or settlement discipline.
MiCA is turning stablecoin issuance into regulated service infrastructure. Circle now has a clearer European pathway for custody and transfer services tied to USDC and EURC, which raises the bar for stablecoin issuers competing on compliance, distribution, and institutional access.
Canada’s real time payments window is now coming into view. Banks, PSPs, fintechs, fraud vendors, and treasury teams need to prepare for testing, phased onboarding, ISO 20022 data, instant settlement, and new fraud controls before launch.
Canada’s payment access model keeps opening beyond incumbent financial institutions. Fintechs, PSPs, banks, and payment infrastructure providers should track which firms gain a formal seat inside payment system governance because direct participation can affect product design, compliance readiness, and competitive timing around modernized payment rails.
Stablecoin settlement is moving into Canadian payment operations, not just crypto trading. Wealthsimple now has a live route to test USDC settlement with Visa Canada, while banks, PSPs, wallets, and regulators watch how on chain settlement fits inside existing card network obligations.
Stablecoin card infrastructure is moving closer to mainstream payment networks. Canadian fintechs, issuers, and payment providers should pay attention to who controls issuance, settlement, compliance, and customer access when tokenized money connects to everyday card spending.
Banks, insurers, fintechs, regtech vendors, and AI providers operating in Europe need clearer compliance planning around governance, documentation, model oversight, and content labeling requirements. The updated timeline gives firms more preparation time while confirming the EU still intends to enforce formal AI accountability rules across regulated industries.
Private credit is evolving from private market growth story to global stability watchlist. Banks, insurers, fund managers, platforms, and risk vendors should expect more scrutiny on exposure mapping, borrower quality, valuations, leverage, liquidity terms, and private ratings.
The proposal would change the disclosure rhythm for U.S. public companies. Issuers may gain lower reporting costs and more planning room, while investors, analysts, and data providers face less frequent mandated information and a bigger premium on interim signals, voluntary updates, and market surveillance.
The findings give Canadian banks, fintechs and infrastructure operators a useful test for shared identity and cloud dependencies. Strong current availability does not resolve the risk created when authentication, payments and outsourced technology depend on a limited number of providers without proven alternatives for prolonged disruptions.
It seems like we say this every week but the competitive gap between fintechs is starting to widen. While there's still opportunities it's less about product design and more about infrastructure access, regulatory positioning, distribution control, and operational execution. Fintechs aren't just launching apps faster, but are embedding themselves deeper into payment rails, compliance systems, tokenized market infrastructure, AI governed workflows, and regulated distribution channels. Canada still has room to compete, but the advantage is increasingly going to operators that can execute inside regulated systems at scale while keeping costs, trust, and customer experience under control.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
