





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 22, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Regulation And Policy, Capital Formation And Venture Markets

Image: Hester Peirce (aka Crypto Mom)
On May 21, 2026, reports confirmed that SEC Commissioner Hester Peirce will leave the U.S. Securities and Exchange Commission later this year to join Regent University School of Law, closing one of the most closely watched regulatory tenures in digital asset policy.
Peirce became affectionately known globally as “Crypto Mom” because she consistently argued that regulators should give digital asset markets workable rules instead of leaving companies to operate inside uncertainty. Her positions moved from controversial to increasingly mainstream as spot bitcoin ETFs launched, tokenization expanded, and major financial institutions entered digital asset infrastructure.
Her departure doesn't mean pro crypto or pro innovation momentum suddenly disappears from Washington. Digital assets no longer depend on a single regulator defending the sector. Bitcoin ETFs now trade in regulated markets. Large banks are building tokenization infrastructure. Stablecoin legislation continues advancing across major jurisdictions. Institutional adoption no longer sits at the fringe.
Still, Peirce leaves behind a clear regulatory record.
For years, she pushed back against regulation through enforcement. She argued that uncertainty weakens both innovation and investor protection because companies struggle to build compliant products when the rules remain unclear.
Many of the issues she raised directly affected fintech competition, startup capital formation, tokenization, crowdfunding, and investor participation. Her speeches consistently returned to the same core themes, such as open markets, proportional regulation, investor choice, and transparent rulemaking.
Peirce’s bluntest critique came during the long debate over regulation through enforcement, where she warned that private meetings with crypto firms cannot replace open rulemaking:
“It’s just not a good way of regulating.”
Her frustration with the SEC’s long delay on spot bitcoin funds became even clearer when spot bitcoin ETFs finally won approval after years of rejected applications:
“We squandered a decade of opportunities to do our job.”
Peirce’s Token Safe Harbor proposal became one of the most discussed crypto policy frameworks because it tried to give blockchain networks time to decentralize before full securities obligations applied.
Her public rulemaking philosophy also stood out in her University of Central Florida FinTech Summit remarks, where she urged regulators to approach innovation with both skepticism and openness instead of reflexive resistance. She later warned that poor engagement damages the relationship between regulators and innovators:
“We are scaring people off from coming in and having a conversation with us.”
Even when she defended innovation, Peirce did not argue for eliminating rules. In her statement on tokenized securities, she welcomed the promise of blockchain while drawing a hard compliance line:
“Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral.”
She also added the part many crypto promoters prefer to skip:
“Tokenized securities are still securities.”
That balance partly explains why Peirce maintained credibility across crypto markets and traditional finance circles. She supported innovation, but she also believed markets work best when participants understand the rules.
Her influence reached beyond crypto. Peirce consistently supported broader access to capital markets, regulatory transparency, and competition for smaller firms. Those priorities aligned closely with long standing NCFA positions on equity crowdfunding and capital markets modernization, fintech competitiveness, and proportional regulation for emerging companies.
Very few SEC commissioners become recognizable public figures outside securities law circles. Peirce did because she represented a different philosophy of regulation during one of the most contested periods in financial technology policy.
Her departure closes an important chapter at the SEC. But the larger debates around tokenization, digital asset infrastructure, market access, and programmable finance are now deeply embedded across global financial systems. Those discussions continue with or without Crypto Mom inside the building.
Peirce also engaged directly with the broader fintech and innovation community over the years, including participating in NCFA’s FFCON21: Breaking Barriers program.
On behalf of everyone at NCFA, we thank Hester Peirce for consistently contributing to open debate around innovation, competition, investor choice, and access to capital during one of the most important periods in modern financial market development. We wish her continued success in this next chapter.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 21, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Banking And Credit Infrastructure

On May 20, 2026, National Bank of Canada partnered with Sardine to strengthen digital banking security and improve fraud operations. National Bank selected Sardine after a live evaluation where the platform improved fraud detection and reduced false positives.
The bank will deploy Sardine’s device intelligence and real time risk scoring across retail, commercial, and wealth solutions. Fraud controls are no longer only a back office defense. They now also affect onboarding, payment approvals, customer friction, and trust across the full digital banking relationship. National Bank serves approximately 2.7 million clients globally and reported $606 billion in assets as at January 31, 2026.
National Bank is also leading a $25 million Series C extension in Sardine, bringing Sardine’s total funding to $170 million. That makes this a commercial partnership with one of Canada’s six systemically important banks.
Soups Ranjan, CEO and co-founder of Sardine:
“Sardine was built for banks that need to stop fraud without slowing down their loyal customers,”
Banks need to stop attacks without blocking good customers. False positives creates unwanted friction, cost, abandoned journeys, and damages trust. Sardine’s platform combines device intelligence, real time risk scoring, fraud controls, and financial crime automation.
It also uses a fraud consortium, a shared risk network built from activity across many customers and channels. That network spans more than 6 billion profiled devices, 800 million consumers, and 3 million businesses worldwide. For banks, outside risk data can help spot suspicious behaviour faster than internal data alone.
Fraud infrastructure is evolving from rule based screening toward live risk decisions across the customer journey. The optimum systems will reduce losses without punishing legitimate customers.
Sardine describes itself as an agentic risk platform for fighting financial crime. That means software that helps risk teams detect fraud, score behaviour, and automate parts of fraud and AML operations. National Bank’s release also references agentic AI in the risk and compliance sector.
The need for AI in banking is now well beyond customer service chatbots and internal productivity tools. Some of the strongest use cases are within risk operations, where firms need speed, evidence, and better decisions under pressure.
Joshuah Lebacq, Partner, NAventures, National Bank of Canada's corporate venture capital arm:
“After closely following Sardine’s growth and hearing strong feedback from existing customers, we decided to conduct an extensive evaluation of their platform. The results gave us confidence to make Sardine a strong addition to our financial crime prevention operations and expand our commercial relationship.
We’re excited about the potential of agentic AI, especially in the risk and compliance sphere, and Sardine’s financial crime agents are setting the standard for the category,”
The release didn't disclosure any loss reduction or false positive reduction rates from their evaluation, so keep your eyes out for those metrics in the future.
As AI driven fraud systems enter deeper into banking, will the best institutions win by blocking more bad actors, or by approving more good customers with less friction?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 21, 2026

Many operators in 2026 are still running on infrastructure built for a different era. Legacy architecture not designed for multi-vertical scale, modern payment rails, or real-time compliance is now the most significant operational liability a gambling business can carry.
This article breaks down what a capable platform partner must deliver: infrastructure, compliance, payments, player lifecycle management, analytics, and genuine innovation across the full platform ecosystem.
A B2B iGaming platform is the software layer between game content, payments, and players – operated by a online casino software provider whose clients are gambling businesses, not players directly. The provider builds the infrastructure; the operator runs the brand.
The two primary delivery models are turnkey solutions and white-label solutions. A turnkey platform delivers a fully operational iGaming business: game content, payment integrations, compliance tooling, CRM, and back-office management, all pre-configured. White-label solutions offer a configurable layer that operators brand and customise while the underlying infrastructure stays shared and under the provider’s license.
Most platforms support multi-brand management – a single operator running several distinct brands from one back-office – essential for expanding across jurisdictions or targeting different player segments.
The ecosystem concept separates a coherent platform from a collection of stitched-together modules. An integrated architecture connects game content, payment gateways, compliance tooling, and CRM into one environment. Most providers offer a flagship full-stack product alongside hybrid options combining shared infrastructure with operator-controlled front-end layers. The vertical scope must include online casino, sports betting, esports, iGaming lottery, and bookmaker products.
Technical debt is not an IT department problem. It is a revenue problem, a compliance problem, and an increasingly existential one.
Legacy systems create direct income and budget consequences. API incompatibility slows game provider onboarding; payment integration failures drive transaction abandonment; uptime and performance degradation during peak events translates into lost bets and churn. Each failure compounds: a game integration delay coincides with a compliance gap and a payment reconciliation issue – the management overhead erodes the capacity to grow.
Legacy architecture cannot support the real-time reporting regulators mandate. The gap widens with each update; the technical backlog becomes a licensing liability. Maintaining legacy software development on an ageing codebase consumes developer time with limited output. The algorithm logic in older systems is frequently undocumented, making changes error-prone. Performance statistics arrive as delayed batch reports rather than real-time intelligence. The complexity and risk of staying now exceeds the cost of migration for most growth-stage operators.
The right model depends on how much of the stack an operator wants to own and how quickly they need to be live. The choice is not about quality – both are viable – it is about maturity, timeline, budget, and brand complexity. The subsections below compare each across speed to market, technical overhead, cost structure, and suitability for multi-brand management at scale.
|
Criteria |
Turnkey Solution |
White-Label Solution |
| Speed to Launch | Moderate – requires setup and configuration | Fast – ready-to-go with minimal setup |
| Cost | Higher upfront investment | Lower initial cost |
| Customisation | High – full control over features and integrations | Limited – based on provider’s framework |
| Brand Scalability | Strong – built for long-term growth and expansion | Moderate – scaling depends on provider capabilities |
A turnkey solution delivers a complete, market-ready iGaming business. Compliance tooling, payment integrations, game content via an aggregator such as iGaming Deck, RNG-certified game logic, and back-office management are all pre-integrated. The operator licenses independently and owns the brand outright – the platform handles the technical stack, not the regulatory relationship.
This is the flagship delivery model for operators entering new markets under time pressure. Architecture is proven, platform scalability is built in, and provider innovation means operators access new capabilities without carrying development costs. Speed to market is measured in weeks.
A white-label solution gives operators control over brand identity and player-facing experience, built on a shared B2B backend via REST API. The operator trades under the provider's gambling license rather than obtaining one independently – reducing time to market and upfront cost, at the expense of some jurisdictional flexibility.
It suits operators who want front-end differentiation across multiple brands without building proprietary infrastructure. Platform scalability remains a B2B responsibility. A hybrid approach – white-label infrastructure with custom-built components – extends capability within budget, making it the preferred route for operators managing software development resources carefully.
Whatever the licensing model, a platform's compliance stack must support the operator's regulatory obligations actively: audit trails, reporting formats, and player data handling that meet the standards of every jurisdiction they trade in. GLI-19 certification is mandatory – it covers RNG integrity, game mathematics, and platform integrity across the full content layer. A platform without GLI-19 compliance creates exposure for any operator.
A compliant platform delivers automated KYC (Know Your Customer) workflows at registration and transaction thresholds without friction at scale. Responsible gambling tools – self-exclusion, deposit limits, intervention triggers based on behavioural algorithm outputs – are mandated under MGA and Gambling Commission frameworks. Fraud detection must operate in real time. Player fund ring-fencing ensures operator funds are legally separated from player balances, as required under MGA and Gambling Commission standards. Privacy and anonymity controls must balance GDPR obligations with the expectations of crypto-focused players.
Compliance capabilities to demand from your B2B partner:
The platform partner's licensing footprint is the operator's growth map. Curaçao offers fast gambling license timelines and is the primary gateway for crypto-focused operators; eSports Curacao covers the esports vertical specifically. MGA licensing provides European credibility and unlocks payment provider partnerships requiring MGA compliance.
The primary growth frontiers are Latin America – Brazil's regulated market is the largest single opportunity – alongside emerging frameworks across Asia and Africa. A partner who can navigate these environments is a genuine competitive asset.
Payment infrastructure is where platforms create or destroy player experience. A failed deposit does not generate a complaint – it generates churn. Multi-currency wallets, what the industry calls crypto journeys, are now a baseline expectation: seamless wallet management across fiat and cryptocurrency denominations with real-time balance visibility. Financial integrity ring-fencing must apply across all wallet types regardless of currency denomination.
The protocols a platform supports matter operationally. Bitcoin Lightning Network delivers instant, low-fee settlements for Bitcoin transfers. Tron (TRC-20) offers high throughput and near-zero costs for frequent small transactions. Ethereum supports smart contract-based payouts. Litecoin provides a cost-efficient alternative for players prioritising low fees.
For players moving between cash-based local payment methods and crypto wallets, the platform must handle both through configurable compliance thresholds – not a binary KYC-or-anonymity choice.
The game aggregator – iGaming Deck in platform terms – connects operators to hundreds of game studios through a single REST API integration. Without it, every new provider requires a separate build; with it, the operator accesses an entire catalogue through one connection.
RNG certification is required at the game level. Every slot machine, roulette variant, and virtual lottery product must carry independently verified certification.
Multi-brand management at the aggregator level allows one operator to serve distinct audiences from shared content infrastructure. Platform scalability ensures the architecture holds under simultaneous peak load across all brands. Hybrid architecture – a shared core with vertical-specific configurations – is where this becomes practical. The recommendation algorithm surfacing the right game to the right player operates here, making aggregator depth a product differentiator.
Player lifecycle management is where operators most commonly rely on disconnected third-party tools, creating data silos and delayed campaign execution. A capable B2B platform integrates CRM natively: acquisition data, deposit behaviour, game preferences, and support history visible in real time, with 24/7 service infrastructure to match.
Loyalty – as a measurable platform output, not a marketing concept – is built through consistent, personalised incentive delivery. The tooling required: a configurable jackpot club, a bonus shop where players select rewards, tournament mechanics across casino and sportsbook verticals, and gamification layers that sustain engagement. Retention tooling must enable churn prediction and automated re-engagement driven by platform behavioural data.
Legacy platforms generate data. Modern platforms generate intelligence. The difference is whether outputs are actionable in real time or require manual extraction.
Player behaviour statistics surface which game types retain players longest and which acquisition channels produce the highest lifetime value. Revenue performance dashboards provide income visibility at brand, market, and segment level. Risk management at the platform layer depends on the same data: the algorithm must flag fraud signals within the analytics environment where operators are already working. Uptime and performance metrics must be visible in real time.
CRM integration turns analytics into action: a churn-risk flag triggers a bonus offer without manual data export. User personalization – the right offer based on actual behaviour, not segment assumptions – separates a modern analytics layer from a reporting tool. Growth metrics must support operational decisions and board-level reporting.
Innovation means whether the platform's architecture can absorb change without generating the next wave of technical debt.
Platforms that add cryptocurrency as an afterthought create friction at every touchpoint: KYC workflows not built for pseudo-anonymous players, reporting that cannot handle coin-denominated revenue, wallet management requiring manual reconciliation. Building with blockchain as a native layer eliminates these problems. Technology choices made today determine what is possible in three years.
Hybrid architecture – supporting legacy formats alongside modern REST API-first development – keeps the platform accessible at different technical maturity levels. Software development investment must be continuous; the API surface area should expand with the ecosystem. The flagship indicator of innovation maturity is whether the algorithm layer – governing game recommendations, fraud detection, and bonus targeting – is actively developed. Platform scalability under that evolution is what separates credible innovation from a product announcement.
The cost of staying on an underperforming platform is compounding. In 2026, the cost of migration is predictable and finite.

1. What is a B2B iGaming platform, and how does it differ from being an operator?
A B2B provider builds and maintains the software infrastructure – game aggregation, payment gateways, compliance tooling, and CRM – and licenses it to gambling businesses. The operator runs the player-facing brand, focusing on acquisition and experience while the platform handles technical complexity.
2. What does "turnkey solution" mean in iGaming?
A turnkey solution delivers a fully operational iGaming business ready for launch – game content, payment integrations, RNG-certified logic, compliance tooling, and back-office management all pre-configured. The operator licenses independently and owns the brand. It is the fastest route to market for operators entering new jurisdictions.
3. What is a white-label iGaming solution?
A white-label solution provides a configurable platform layer on a B2B backend, accessed via REST API. The operator trades under the provider's gambling license rather than obtaining one independently. It suits operators wanting brand control across multiple demographics without the overhead of building proprietary infrastructure.
4. What compliance certifications should I demand from a B2B platform partner?
GLI-19 certification is the baseline – covering RNG integrity, game mathematics, and platform standards. Also require automated KYC workflows, player fund ring-fencing under MGA and Gambling Commission frameworks, real-time fraud monitoring, and responsible gambling tools, including self-exclusion and deposit limits.
5. How do B2B platforms support crypto and multi-currency payments?
A modern platform supports multi-currency wallets handling fiat and cryptocurrency in a single interface. Blockchain rails should include Bitcoin Lightning Network for instant settlements, Tron for micro-transactions, Ethereum for smart contract payouts, and Litecoin for low-cost transfers – with KYC and fraud monitoring preserving player anonymity where compliant.
6. What player retention tools should a B2B platform include natively?
A jackpot club, bonus shop with player-selectable rewards, tournament mechanics across casino and sportsbook, and CRM-native churn prediction. Loyalty mechanics must operate in real time from platform behavioural data, not manual campaign setup or third-party tools with delayed access.
7. How do analytics capabilities differ between modern and legacy platforms?
Legacy platforms generate historical reports. Modern platforms deliver real-time dashboards covering player behaviour statistics, revenue performance, fraud risk signals, and uptime metrics. CRM integration means a churn-risk flag automatically triggers a bonus campaign within the same environment.
8. Why does the choice of blockchain infrastructure matter for an iGaming platform?
Protocol choice determines transaction speed, cost, and compliance profile. Bitcoin Lightning Network enables instant low-fee BTC settlements; Tron handles micro-transactions; Ethereum supports smart contract payouts; Litecoin offers low-cost transfers. Native blockchain integration avoids the reconciliation and UX problems of afterthought crypto architecture.
A capable B2B iGaming platform partner in 2026 delivers an integrated ecosystem: proven infrastructure, multi-jurisdiction compliance, blockchain-native payment rails, platform-native player lifecycle tools, real-time analytics, and a software development model built for continuous evolution.
Multi-brand management, scalable architecture, and genuine innovation investment in underlying technology are what separate a platform that enables growth from one that constrains it. For operators on legacy systems, the calculation is straightforward: the cost of staying now exceeds the cost of moving. The question is how quickly you act.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026 | NCFA Resource | Regulation And Policy, Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization

On April 20, 2026, the UK Financial Conduct Authority published its Innovation Insights 2025 report (20 page PDF). The report gives fintech founders, investors, and policy teams a practical view of where capital, regulatory testing, and market demand are concentrating across AI, digital assets, stablecoins, tokenization, RegTech, open finance, embedded finance, and operational automation.
The FCA points to a more disciplined phase of fintech, where firms need clear customer value, stronger controls, earlier regulatory engagement, and credible deployment plans.
The report combines global fintech investment data with activity across FCA innovation services, including the Regulatory Sandbox, Innovation Pathways, Digital Sandbox, AI Lab, Supercharged Sandbox, Smart Data Accelerator, and Scale Up Unit.
The overview gives operators a clean read on regulated fintech demand. AI, distributed ledger technology, open banking, and open finance ranked among the main technologies used by applicants. The FCA also launched new support channels in 2025, including a stablecoins cohort.
Regulated fintech no longer wins on novelty alone. Better products need stronger evidence, safer testing routes, sharper governance, and a realistic route from pilot to production.
This resource is useful for fintech founders, investors, compliance teams, financial institutions, policymakers, accelerators, digital asset firms, AI builders, RegTech vendors, and open finance teams tracking where regulated innovation is gaining traction.
It is especially useful for firms building around AI governance, stablecoins, tokenization, compliance automation, open finance, embedded finance, and supervised testing models.
The report is strong on investment patterns, regulatory engagement, sector demand, and FCA innovation service activity. It helps founders and investors see which fintech themes are attracting capital and which models need earlier regulator dialogue.
Its limit is the report doesn't provide a full outcomes study on sandbox firm performance, revenue growth, compliance cost reduction, productivity gains, fraud reduction, or investor returns. It works best as a regulatory market map, not proof that any one fintech category will outperform.
Canada and other jurisdictions can still use the report as a benchmark. Faster testing routes, clearer engagement models, and stronger links between experimentation and responsible deployment are becoming competitive advantages in financial innovation.
FCA Innovation Insights 2025 (primary FCA report)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure
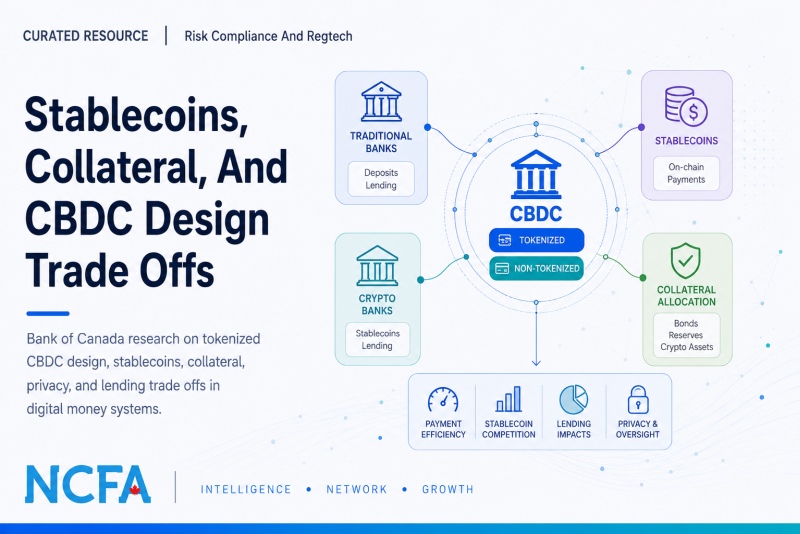
On May 7, 2026, the Bank of Canada published staff working paper 2026-14 on CBDC tokenization design. The paper looks at a financial system where traditional banks issue deposits, crypto banks issue stablecoins, and a central bank decides whether a CBDC should work through conventional accounts or programmable ledgers.
For fintechs, the useful part isn't the CBDC debate alone. The paper links tokenized money to collateral, stablecoin competition, privacy, crypto asset scarcity, and bank lending. Those issues are at the core of digital money infrastructure.
The paper compares tokenized and non tokenized CBDCs. A non tokenized CBDC competes with bank deposits in traditional payment markets. A tokenized CBDC works on programmable ledgers and competes more directly with stablecoins and tokenized settlement infrastructure in on chain markets.
The strongest finding is simple but important. Tokenization changes outcomes only when collateral use differs across sectors. The real question is which institutions hold the collateral, how reliable private money issuers are, and whether scarce reserve assets support payments or lending.
The model shows that tokenized CBDCs can crowd out stablecoins when crypto banks look less reliable and crypto assets are scarce. Non tokenized CBDCs can make more sense when crypto transactions offer less social value or when moving reserves from traditional banks to crypto banks improves the system.
The trade off is clear. CBDCs can improve payment efficiency, but they can also reduce bank lending when collateral moves away from traditional credit creation. That is where the paper becomes useful for fintech operators, not just policy teams.
The paper also raises a privacy question. A tokenized CBDC can run on a ledger that gives the central bank more visibility into transactions. That may improve oversight, but it can also reduce privacy. Digital money design is not just about speed or programmability. It also sets the rules for trust, control, and market access.
This resource is useful for fintech founders, stablecoin issuers, payment companies, banks, digital asset infrastructure providers, tokenization platforms, treasury teams, investors, and policymakers tracking the future of money.
It is especially relevant for firms building around programmable payments, stablecoin settlement, tokenized collateral, wholesale digital assets, bank issued digital money, or regulated crypto infrastructure.
The strength of this resource is the way it connects CBDC design to the financial infrastructure underneath tokenized markets. It doesn't treat CBDC as a simple retail wallet question. It looks at how money design affects collateral, settlement, stablecoins, bank deposits, crypto activity, and lending.
The paper also avoids easy answers. Tokenized CBDCs do not automatically improve the system. The result depends on collateral scarcity, crypto bank reliability, privacy settings, and the value of activity happening on programmable ledgers.
The limit is that this is an academic working paper with equations, model assumptions, and conditional results. Most operators will not read it end to end. The value is in the framework, not every technical section.
Used well, it helps fintech teams ask better questions about future money design. Who issues the money? What backs it? Where does collateral sit? What happens to lending? Who gets visibility into transactions? Those questions will matter as stablecoins, tokenized deposits, and central bank money keep moving into the same conversation.
Bank Of Canada CBDC Tokenization Paper (primary Bank of Canada working paper)
BIS Future Monetary System Blueprint (referenced framework for tokenized money and unified ledgers)
US Treasury Future Of Money Report (policy context for digital money and payment system design)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026).
Tokenized funds need reliable exits before more institutions treat them as usable collateral or treasury assets. Asset managers, custodians, exchanges, treasury teams, and tokenization platforms should watch how redemption speed, stablecoin liquidity, and access controls become core requirements for institutional tokenized finance.
Community and regional banks are starting to package stablecoins, tokenized deposits, and digital asset lending inside bank led distribution. Banks, fintechs, core providers, custodians, and compliance teams should watch how association channels turn digital asset access into a practical banking product instead of a standalone crypto service.
Fintechs and FIs now compete on governed AI use in underwriting, fraud, servicing, and cost discipline, while security and model risk stay on the board agenda.
Voice is becoming searchable compliance evidence across more markets and languages. Banks, dealers, wealth firms, fintechs, and regtech vendors need stronger controls for recorded calls, multilingual surveillance, off channel risk, and investigation workflows.
Fraud controls are becoming more coordinated across regulators, law enforcement, platforms, and financial institutions. Banks, fintechs, PSPs, regtech vendors, and digital asset firms should expect higher expectations around intelligence sharing, scam detection, AI oversight, and real time monitoring.
Agent driven commerce needs payment controls that can handle authorization, settlement, spending permissions, dispute handling, and compliance review without slowing automated workflows. Stablecoins are increasingly being positioned as the settlement layer for machine initiated transactions.
Agent payments now need privacy, settlement, authorization, and audit controls that work together. Payment firms, wallet providers, stablecoin issuers, AI agent platforms, and compliance teams should track how machine initiated transactions create new requirements for identity, transaction monitoring, and dispute handling.
Canadian banks, credit unions, fintechs, and infrastructure providers face growing pressure to modernize customer onboarding, payments, servicing, and digital account experiences at lower operating cost. Large coordinated modernization programs can influence vendor standards, integration expectations, and competitive timing across the Canadian banking market.
Direct PSP access to Interac e Transfer gives Canadian fintechs a stronger role inside everyday money movement. Banks, PSPs, payment firms, and compliance teams should track how direct participation changes onboarding, fraud controls, settlement readiness, and product competition across Canadian payment services. Koho is a a payment service provider member of Payments Canada with direct access to payment clearing and settlement.
Digital asset lending keeps adopting operational standards from traditional securities finance. Exchanges, custodians, prime brokers, lenders, treasury teams, and compliance groups should watch how collateral controls, settlement discipline, and institutional workflow expectations become standard requirements across crypto lending markets.
Tokenized settlement is entering exchange rulebooks, not just pilot decks. Exchanges, broker dealers, custodians, transfer agents, market data teams, and compliance teams need to prepare for tokenized securities that still trade under national market system rules, surveillance, reporting, T+1 settlement, and existing investor protections.
Asset managers, exchanges, custodians, brokers, and treasury teams increasingly need infrastructure that supports tokenized funds, collateral, and yield products inside institutional operating environments. Tokenized finance is becoming part of mainstream capital markets strategy rather than a separate digital asset experiment.
Tokenization now reaches core market infrastructure, not just crypto trading activity. Exchanges, custodians, transfer agents, dealers, issuers, and infrastructure providers need operating models that support tokenized securities inside existing settlement, governance, reporting, and post trade systems.
Broker dealers, RIAs, custodians, wealth platforms, and compliance teams now have another regulated route to offer digital assets inside familiar securities account structures. That raises the bar for firms still treating crypto access as a separate product channel instead of a brokerage, custody, and supervision question.
MiCA implementation now becomes a licensing, supervision, and market access issue for crypto firms operating in Poland. Exchanges, custodians, stablecoin firms, brokers, and compliance teams should watch how national supervisors apply enforcement powers, authorization standards, and transition rules as Europe’s crypto framework enters active supervision.
Crypto exchanges, custodians, stablecoin issuers, tokenization firms, banks, compliance vendors, and capital markets platforms should track this markup closely. The bill text moves U.S. digital asset policy from broad debate into statutory architecture, with direct implications for token classification, intermediary registration, custody, disclosure, DeFi obligations, and cross border market access.
The common thread is operational readiness. Firms increasingly compete on whether they can support governed AI, tokenized assets, stablecoin settlement, and real time compliance inside production systems rather than separate innovation programs. That pressure now reaches broker dealers, PSPs, banks, treasury teams, exchanges, and compliance groups at the same time. Founders, operators, and investors tracking these changes may also want to review coverage on tokenized market infrastructure, AI agents entering governed financial workflows, and agent driven commerce and payments as these themes continue to converge across fintech markets.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 15, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, SME Finance And Business Banking, Capital Markets And Funding
On May 14, 2026, Synthetic raised USD $10 million in seed funding led by Khosla Ventures to build autonomous AI bookkeeping for software startups. Basis Set Ventures also participated. Operator investors include Shopify CEO Tobi Lütke, Opendoor CEO Kaz Nejatian, Bridge co founder Zach Abrams, Accrual CEO Cosmin Nicolaescu, and Figure CEO Michael Tannenbaum.
Synthetic is aiming to deliver accrual basis books without human bookkeepers or accountants. The system connects to a customer’s banks, payroll, billing systems, and inboxes, then asks clarifying questions when it needs more information. The output promised is a clean set of books that a tax preparer can use.
Synthetic says pricing will start at USD $49 per month, about a quarter of the cost of a human staffed service. The company is starting with software, SaaS, and AI businesses because their accounting workflows are narrower and easier to model than the full small business market. Autonomous bookkeeping will only work if the system understands the business and sector well enough to avoid a range of potential errors, both simple and complex.
Ian Crosby, Founder and CEO, Synthetic:
“I'm not sure if it's yet technologically possible to make this work,”
That quote is perhaps one of the most interesting parts of the announcement. Crosby isn't selling certainty, but he's calling out and going after a hard problem. AI is still unreliable, and no founder wants books that look clean but are wrong. In accounting, a small error can affect taxes, financing, board reporting, future planning, and investor trust.
Synthetic is trying to solve that by narrowing the customer type and building around quality control. The company says the team is iterating on a prototype with early design customers. The firm hasn't disclosed revenue, customers, launch timing, error rates, or benchmark results as of yet.
Bookkeeping touches sensitive financial data such as banking, billing, and payroll. If AI can handle that work with enough accuracy, it could cut cost for early startups and reduce one of the most common back office bottlenecks for founders.
Jon Chu, Khosla Ventures:
“This one’s quite simple. You have a large, valuable problem that will inevitably be solved by AI. A founder who’s spent multiple decades working on the problem with near perfect founder market fit. And resilience and grit that’s been forged through multiple founding experiences and scale ups at companies like Shopify and Mercury,”
While Synthetic is headquartered in San Francisco, the Canadian angle is three time founder (ie. Bench and Teal) Ian Crosby. Bench was a Vancouver built bookkeeping company that became one of North America’s best known small business accounting platforms before it later shutdown and was acquired.
So why not base the company in Canada? It's a competitiveness question for Canada. Canadian founders keep showing up in high value AI and fintech infrastructure deals, but company formation, lead capital, senior hiring, and headquarters often land in the United States. If Canada wants the next generation of AI finance companies to scale here, it needs more than talent. It needs lead capital, customers, technical density, and a culture that lets ambitious teams move fast.
This also connects to Canada’s productivity and competitiveness challenge. AI can reduce manual work, but the economic value goes to the companies that own the IP, workflow, data, customer relationship, and product layer.
Synthetic has to show that AI can handle edge cases, ask the right questions, document decisions, and produce books that accountants, tax preparers, investors, regulators, and founders can trust.
The company’s longer vision is even bigger. Synthetic says it wants founders to press a button and watch a company assemble around an idea, including the website, incorporation, bank accounts, payments, accounting, and other operating pieces. Accounting is the starting point with the bigger ambition being the required operating infrastructure.
Can autonomous AI earn enough trust to run startup bookkeeping, or will reliability, tax risk, and financial controls keep humans in the loop longer than investors expect?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
