




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


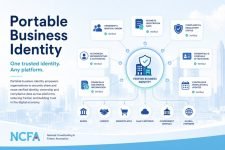
Businesses still repeat identity, ownership, onboarding and compliance checks across banks, PSPs, lenders, marketplaces and software platforms. The opportunity is to let verified business identity, KYB records, authority, ownership and trust credentials move securely across institutions with consent and controls.
Portable business identity sits between digital identity, KYB, beneficial ownership, data portability and compliance automation. Market estimates vary by scope, but the direction is consistent: regulated firms need more reliable business identity data, while businesses need less repetitive onboarding across platforms.
The strongest opening is portable KYB and business identity profiles that reduce repeated onboarding while preserving control, consent, verification quality and auditability. The buyer may be a bank, PSP, marketplace, lender, regtech provider or business platform that wants lower onboarding friction without weaker compliance.
Consumer driven banking rollout, CSA data portability testing, GLEIF vLEI adoption, beneficial ownership rules, KYB automation, open finance standards and evidence that SMEs or platforms will pay for reusable business identity tools.
Evidence points to three venture paths. Each one addresses a different constraint that prevents business identity and compliance data from moving safely across financial ecosystems.
Reusable business onboarding and ownership records
Businesses repeatedly submit incorporation documents, ownership records, director information, tax data, licenses and compliance evidence to every new financial provider. Portable KYB profiles could reduce this duplication while keeping institutions in control of risk decisions.
The venture opportunity is not to eliminate due diligence. It is to make verified business information easier to reuse, refresh, audit and share under clear permission rules. Potential buyers include banks, PSPs, lenders, marketplaces, wealth platforms and compliance service providers.
Regulated firms may decide that relying on third party KYB records creates more liability than efficiency unless assurance standards mature.
Will banks, PSPs or platforms rely on portable KYB outputs, or only use them to accelerate internal review?
Verified entity, authority and credential control
Business identity wallets would let companies hold and present verified entity information, authority credentials, licenses, beneficial ownership attestations and role based permissions. The vLEI model shows how legal entity identity can become cryptographically verifiable in digital interactions.
This path may be most valuable where businesses need to prove who they are, who can act for them and what authority has been granted across payments, procurement, lending, filings and platform onboarding.
Wallet adoption may remain fragmented if issuers, registries, platforms and regulators do not converge around interoperable standards.
Which credential creates enough value to drive wallet adoption: entity identity, authority to act, beneficial ownership, tax status or licensing?
Platform trust, compliance status and risk portability
Many businesses build trust repeatedly across marketplaces, lenders, PSPs, procurement networks and software ecosystems. A trust passport network would let selected trust attributes travel with the business, including verification status, permissions, payment history, platform standing and risk signals.
This path is broader than compliance. It may support B2B marketplaces, SME finance, embedded finance, cross border trade and agent commerce. It is earlier because governance and liability questions are harder than the technology.
Platforms may refuse to share trust data if they view it as proprietary, competitively sensitive or too risky to rely on elsewhere.
Which trust attributes are portable enough to matter and safe enough for another platform to rely on?
Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 18, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Wealthtech And Investing
Image: Unsplash/Stephen Dawson
On June 18, 2026, Wealthsimple announced Wealthsimple Predict, a standalone app that will give Canadian retail investors access to prediction market trading through Kalshi.
The app is in beta and expected to launch this summer. At launch, Wealthsimple says it will offer access to nearly 4,000 event contracts trading on Kalshi, limited to the categories Wealthsimple is authorized to offer in Canada a range of event contracts across economic indicators, financial markets, and climate. Those contracts must also meet Wealthsimple's listing standards.
This is a distribution milestone for Canadian prediction markets. In March, Prediction Markets Tighten as Wealthsimple Enters tracked Wealthsimple's regulatory approval as Canada began testing a narrower, supervised route for event contracts. So with this active launch plan, that story is evolving from approval to retail access.
CIRO and the CSA reminded firms in April that event contracts remain subject to existing securities and derivatives rules. CIRO has said two dealer members are authorized to facilitate Canadian client access to event contracts. Public reporting and dealer materials indicate those firms are Wealthsimple and Interactive Brokers Canada.
Wealthsimple's own education material says event contract trading is legal in Canada under specific conditions, with guardrails around authorization, product categories, investor protection, and trading rules. Canada's version isn't simply a copy of U.S. political or sports prediction markets. It is starting with economic, financial, and climate contracts inside a regulated dealer pathway.
Event contracts are simple in structure but hard to operate well. Wealthsimple describes most prediction markets as binary contracts where users choose yes or no, and correct contracts pay $1 minus fees. Prices can act as probability estimates, but only when contracts are clear, liquid, supervised, and resolved properly.
Kalshi brings the exchange infrastructure. Wealthsimple brings Canadian retail distribution, education, onboarding, account experience, and investor guardrails. The combination is important for adoption. A prediction market with good contracts but weak distribution stays niche. While a prediction market connected to a large investing platform can test whether event contracts become useful market information, not only speculative trading activity.
NCFA's Innovation Opportunities in Regulated Event Contract Infrastructure brief identified the same gap. Regulated prediction markets need compliance, surveillance, market data, onboarding, dispute resolution, payout, risk, and investor education infrastructure. Wealthsimple Predict is a live validation point for that opportunity thesis.
The open question is whether or not event contracts will become sustainable information markets in Canada. If liquidity develops inside permitted categories, prices could help investors read market expectations around inflation, rates, climate outcomes, tariffs, currencies, and economic risk. If liquidity remains thin or contract design is weak, the information value will be limited.
As regulated prediction markets reach Canadian retail investors, will their main value come from trading activity, or from the real time probability data they produce for investors, policymakers, and markets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2026 | NCFA Story Intelligence | Fraud, Cybersecurity And Trust
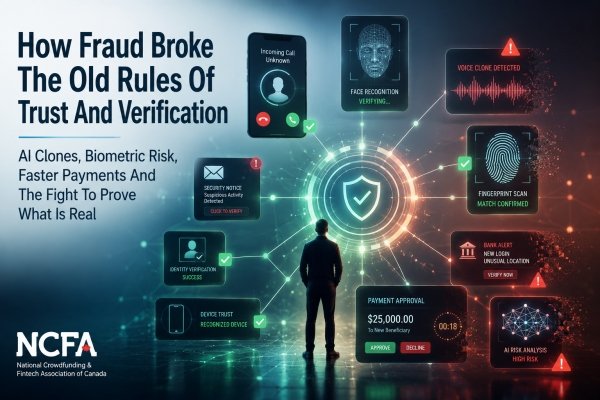
The phone rings. Many people no longer answer.
Not because they’re too busy. Because they’re not sure who is calling, what’s real, or whether the message is safe to trust. That small behaviour change tells a bigger story about finance, fraud, identity, and technology.
For years, financial trust relied on familiar signals: a voice, a face, a password, a bank name, a phone number, a regulator, a delay before money moved. AI clones, biometric breaches, deepfakes, cyberattacks, weak AML controls, and faster payments are now breaking those signals at the same time.
Financial trust used to have more time. Branch visits, paper signatures, settlement delays, call centre checks, account holds, and human review gave institutions more room to spot problems before money moved too far. The system was slower, but that slowness created time to verify.
Consumers learned to trust familiar signals. A bank logo felt official. A caller who knew account details sounded credible. A voice sounded personal. A password felt private. Those signals were never perfect, but they worked well enough when fraud was slower, less automated, and easier to recognize.
Online finance moved trust away from the branch. Banking, investing, lending, crypto, payments, and onboarding shifted into screens and apps. That created better access and faster service, but it also made customers depend on passwords, text codes, device checks, email links, and remote identity tools.
Fraudsters followed the customer online. Phishing, fake websites, account takeover, crypto wallet scams, approval phishing, QR abuse, and spoofed support channels made digital convenience feel less certain. Operation Avalanche showed how coordinated fraud response is becoming part of the market.
Voice used to feel personal. Then AI cloning made it copyable. Cloned voices bypassed Voice ID tests at Santander and Halifax, exposing weakness in systems that treated a voice as a reliable authentication signal.1
The scam no longer has to sound like a scam. A cloned voice can sound calm, familiar, urgent, or official. That changes the risk for banks, call centres, families, executives, seniors, and anyone asked to approve a transfer or share information after hearing a voice they think they know.
Biometrics raise the stakes because they cannot be replaced easily. A major India breach exposed fingerprints, facial scans, and sensitive records tied to police officers and applicants.2 A password can be reset. A fingerprint can’t.
Fintech products increasingly depend on biometric convenience. Face ID, Touch ID, palm payment, device based onboarding, and selfie checks reduce friction. They can also concentrate risk if biometric templates, face scans, or identity documents are stored poorly or exposed through vendors.
Deepfakes make fraud feel human. Deepfake scams have used AI generated voices, fake identities, digital banks, and crypto rails to trick victims and move funds quickly.3
AI makes deception cheaper to personalize. Fraudsters can imitate an executive, a family member, a bank employee, a support agent, or an investment promoter. The scam can be written better, timed better, targeted better, and delivered through channels that look more legitimate than old phishing emails.
Faster money gives fraud less time to fail. Real Time Rail, instant payments, request to pay, and faster settlement can improve cash flow and customer experience. They also shrink the window for fraud teams to stop a bad payment before it settles.
Fraud controls become part of the payment product. Real Time Rail analysis connects instant payments with centralized fraud capability, payment finality, and trust.4 Faster money only works if participants believe the system can manage faster mistakes.
Institutions are not only defenders. They are targets. CIRO confirmed approximately 750,000 Canadian investors were affected by a cybersecurity incident after a 9,000 hour forensic review.5 When regulated bodies are breached, trust damage extends beyond one account.
Third party systems can carry hidden risk. SaaS vendors can create concentration risk across fintech and financial services. A startup may inherit risk through a vendor, API, data processor, onboarding tool, cloud provider, or fraud vendor it does not fully control.
AML failure shows how controls can become business risk. TD’s more than $3 billion US AML penalty and leadership fallout showed how weak controls can limit strategy, growth, reputation, and trust.6
Canada is trying to organize the response. Canada’s first National Anti Fraud Strategy and Financial Crimes Agency push point toward more public and private collaboration on cyber risk, data sharing, and proceeds of crime recovery.7
Fraud didn’t break trust all at once. It weakened the signals people and institutions used to verify reality. The phone call. The voice. The face. The fingerprint. The login. The bank name. The official looking message. The settlement delay. The regulated institution. Each one still matters, but none can carry trust on its own anymore.
That’s the hard part for financial innovation. Canada is moving toward faster payments, consumer driven banking, digital identity discussions, AI adoption, crypto market controls, and more automated financial services. None of those systems succeed simply because they’re fast or digital. They succeed because people trust what they’re seeing, hearing, approving, and authorizing.
What trust signal do you question now that you wouldn’t have questioned five years ago?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2025 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data, Regulation And Policy
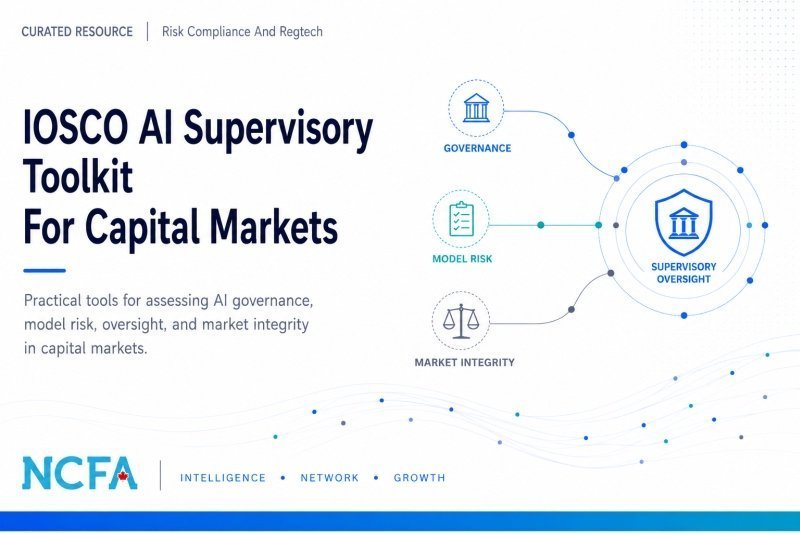
On May 25, 2026, the International Organization of Securities Commissions (IOSCO) published its Supervisory Toolkit for Artificial Intelligence Use in Capital Markets. The report provides practical tools for regulators supervising AI systems used by market participants, exchanges, investment firms, and capital market infrastructure providers.
The toolkit arrives as AI goes beyond experimentation and into production environments across trading, surveillance, compliance, onboarding, fraud detection, customer service, research, risk management, and operational workflows. IOSCO focuses on the supervisory questions regulators need to ask rather than promoting a specific technology approach.
Stakeholder Input Opportunity: IOSCO is also seeking feedback related to the toolkit and AI supervision in capital markets. Interested regulators, market participants, technology providers, academics, and industry stakeholders can review the report and submit responses to IOSCO by this short survey by June 26, 2026.
The report organizes supervision around seven areas. These include governance and accountability, model development and testing, data quality and management, monitoring and controls, outsourcing and third party providers, market conduct risks, and operational resilience.
Rather than prescribing rules, IOSCO provides supervisory questions, review approaches, and practical considerations that regulators can use when assessing AI systems operating in capital markets. The toolkit is designed to support risk based supervision while remaining flexible as technologies evolve.
The report also recognizes that AI risks often emerge from combinations of factors rather than a single model failure. Poor quality data, weak governance, limited oversight, inadequate testing, vendor dependencies, and insufficient monitoring can interact in ways that create market, operational, or investor protection concerns.
Many financial institutions are already deploying AI in regulated environments. The challenge is no longer whether AI will be used. The challenge is whether firms can demonstrate appropriate governance, explainability, oversight, and accountability once those systems affect clients, markets, or investment decisions.
For fintech operators, the toolkit offers a useful preview of the questions regulators may increasingly ask during examinations, supervisory reviews, audits, and risk assessments. Firms that build governance and controls into deployment processes early may face fewer compliance and operational challenges as expectations mature.
This resource is useful for securities regulators, exchanges, investment dealers, fintech founders, regtech providers, compliance teams, AI governance specialists, risk managers, and market infrastructure operators.
It is especially relevant for organizations using AI in trading, surveillance, onboarding, fraud detection, compliance monitoring, client communications, investment research, portfolio management, or operational decision making.
The strength of the toolkit is its practical orientation. It extends beyond high level AI principles and focuses on supervision, controls, accountability, and operational implementation. The framework can be applied across a wide range of AI use cases and organizational structures.
It also provides a common language that regulators and industry participants can use when discussing AI oversight. That consistency becomes increasingly important as firms operate across multiple jurisdictions with different regulatory approaches.
The toolkit does not create binding rules or regulatory obligations. IOSCO's role is to provide guidance and supervisory tools that member jurisdictions can adapt to their own legal and regulatory frameworks.
IOSCO Supervisory Toolkit For AI Use In Capital Markets (primary resource)
IOSCO Media Release (official announcement)
AI Agents Enter Governed Financial Workflows (AI governance and oversight)
Customer Due Diligence Controls For Fintechs (controls, monitoring, and accountability)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 16, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization
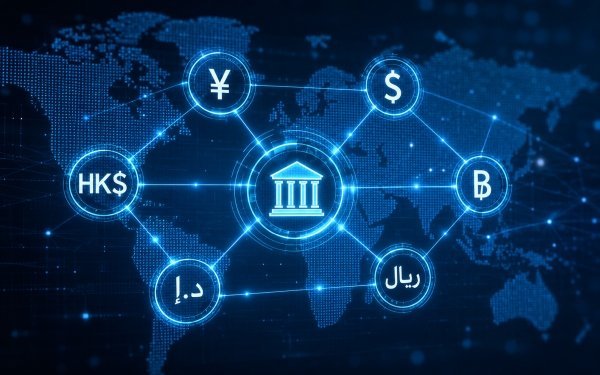
On June 14, 2026, the Financial Times reported that China is preparing mBridge for commercial rollout (subscription needed), with central banks from mainland China, Hong Kong, Thailand, the United Arab Emirates and Saudi Arabia involved.
The participating central banks haven't yet published a matching launch announcement. The Bank for International Settlements said mBridge reached minimum viable product stage in 2024 and that more central banks and commercial banks could join the legal framework and perform real transactions on the platform.
mBridge is important to watch because it tests a different model for cross border settlement. Instead of routing payments through long correspondent banking chains, participating central banks and commercial banks use a shared multi CBDC platform for payment and foreign exchange settlement. That makes the project a practical test of whether wholesale CBDC rails can reduce cost, settlement delay and liquidity friction in trade corridors where participating jurisdictions already have strong commercial ties.
mBridge began in 2021 with the BIS Innovation Hub, the Hong Kong Monetary Authority, the Bank of Thailand, the Central Bank of the UAE and the Digital Currency Institute of the People’s Bank of China. Saudi Arabia joined as a full participant in 2024. BIS also identified more than 26 observing members, including the European Central Bank, IMF, World Bank, Reserve Bank of India, Bank of Korea, Bank of France and the Federal Reserve Bank of New York’s New York Innovation Center.
The project has already gone beyond lab testing. The HKMA said the 2022 pilot involved 20 banks across four jurisdictions and completed more than 160 payment and foreign exchange transactions totaling over HK$171 million. It was among the first multi CBDC projects to settle real value cross border transactions on behalf of corporates.
BIS later said the MVP platform allowed participating jurisdictions to undertake real value transactions, subject to their own readiness. The project also created a governance and legal framework, including a rulebook, to match its decentralized operating model. That's why the current story isn't whether CBDCs can be piloted. It's whether participating jurisdictions can turn mBridge into operating payment infrastructure?
mBridge should be read alongside Project Agorá tests real money bank settlement rails. Agorá is testing tokenized commercial bank deposits and wholesale central bank money with major Western central banks and more than 40 commercial banks. mBridge is testing a direct multi CBDC settlement network among participating jurisdictions.
The difference is important for Canadian banks, exporters, fintechs and policymakers. Agorá is closer to upgrading existing correspondent banking through tokenized deposits and shared workflows. mBridge is closer to building a parallel wholesale settlement arrangement for selected currency corridors. Both are trying to reduce payment friction, but they reflect different governance choices, legal assumptions and geopolitical incentives.
The commercial test is liquidity, compliance and repeat usage. If real trade flows begin routing through mBridge, banks and payment firms will have to assess whether lower cost and faster settlement justify the legal, operational and supervisory work needed to connect to a new network.
The sensitive issue is whether a new wholesale settlement network can preserve anti money laundering controls, sanctions compliance, legal certainty and supervisory visibility across jurisdictions with different policy goals. Debate around mBridge's geopolitical implications has followed the project for years. See: mBridge could affect sanctions enforcement and payment routing.
In 2024, BIS General Manager Agustín Carstens said the BIS handoff of mBridge to participating central banks was not politically driven and was not a sign of project failure. He also said mBridge was not mature enough to operate commercially at that time and rejected the claim that it was designed as a BRICS sanctions workaround.
That tension remains central. If mBridge enters commercial use, participating institutions will need to prove that faster settlement isn't at the expense of enforceable controls, transaction monitoring, governance accountability or cross border legal clarity.
If wholesale CBDC networks start carrying real trade flows, how should Canada position payment modernization so Canadian banks, exporters and fintechs can participate in the infrastructure race instead of only reacting to it?
CBDCTracker, these Central Banks have Launched a CBDC or Pilot Initiative
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 6, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026).
Citi is combining traditional securities infrastructure with blockchain based issuance, custody, and settlement for private company equity. The launch adds another proof point that tokenized infrastructure is changing how markets operate, especially as banks, exchanges, and market operators compete to define how private assets move onto digital rails.
Digital asset access is being packaged for banks, brokerages, fintechs, and platforms that do not want to build the full crypto stack themselves. The control point is the embedded infrastructure that handles custody, liquidity, compliance, settlement, and connectivity behind the customer experience.
Tokenized real world assets are moving into bank distribution channels. DBS is turning physical gold into a digital product that can sit inside a retail banking app, while also testing institutional market access through its digital exchange.
Stablecoin supervision is moving from broad policy debate into operating rules. Issuers, custodians, exchanges, auditors, compliance vendors, and payment firms need to track how reserve custody, internal controls, audits, and service provider oversight become part of stablecoin market access.
Card networks are building trust infrastructure for AI driven payments. Visa’s updates add another network level proof point that identity, authorization, fraud controls, tokenized credentials, and settlement will shape how AI agents are allowed to transact.
Recurring payment rails are becoming a financial inclusion tool when they help users pay for digital services without relying on credit cards. Brazil’s Pix Automático data shows how local real time payment infrastructure can support subscriptions, platform access, and digital commerce growth.
Agentic payments are moving from checkout experiments into network infrastructure. Payment firms, AI platforms, stablecoin providers, banks, and identity vendors now have to solve authorization, spending limits, settlement, fraud controls, and liability for machines that can transact without a human at every step.
Large banks are building their own tokenized money infrastructure rather than relying on third party stablecoin networks. Payment providers, treasury platforms, and financial institutions now face a more competitive settlement environment as bank money, stablecoins, and tokenized commercial bank deposits compete for transaction flow.
Circle Payments Network continues to add distribution. Business accounts, treasury platforms, and payment providers are becoming part of the stablecoin settlement infrastructure rather than simply connecting to it.
Circle is extending its infrastructure footprint from stablecoins into Bitcoin collateral. Builders now have another institutional grade option for collateral and tokenized asset applications.
AI agents are moving from recommendation and discovery toward financial execution. Coinbase for Agents puts user controlled account access, payments, trading, and workflow automation into the same agentic finance conversation as network trust controls, stablecoin settlement, fraud prevention, and responsible AI governance.
AI supervision in finance is evolving from broad risk discussion toward operating practices for boards, senior management, compliance teams, model owners, technology vendors, and supervisors. Financial institutions need to track how governance, documentation, human oversight, cyber controls, and third party dependencies become part of responsible AI adoption.
Always-on markets need reference data that does not stop when traditional exchanges close. Exchanges, tokenized asset platforms, derivatives venues, market makers, and risk teams now have another pricing source to evaluate as real-world assets trade across crypto-native market infrastructure.
Prediction markets are starting to need the same financial plumbing as capital markets. Market makers, exchanges, payment providers, banks, and compliance teams now need infrastructure that can handle deposits, margin, settlement, risk controls, and regulated access without slowing down trading activity.
Prediction markets are moving from platform experimentation and court fights into formal rule design. Kalshi, Polymarket, DraftKings, Flutter/FanDuel, exchanges, market makers, compliance teams, sports leagues, and retail users now have a clearer process to debate which contracts belong in derivatives markets and which remain too close to gaming, misconduct, or public interest risk.
Financial crime compliance is increasingly becoming an existential regulatory issue rather than a supervisory issue alone. Payment firms, e-money institutions, fintechs, compliance teams, and investors should watch how regulators use governance, safeguarding, ownership, and financial crime controls as indicators of firm viability. The action signals that supervisory concerns can now lead to intervention measures that effectively remove a regulated firm's ability to continue operating.
Canada is pulling AI chatbots into platform safety regulation. AI firms, social platforms, trust and safety teams, identity providers, and compliance vendors should watch how age assurance, safety controls, reporting duties, and enforcement rules develop as digital safety becomes part of regulated online infrastructure.
Financial supervisors are beginning to treat AI as both a productivity tool and a threat multiplier. Banks, insurers, payment firms, fintechs, and security providers should expect greater scrutiny of fraud controls, cyber resilience, operational risk management, and third party technology oversight as regulators adapt supervision to an AI enabled threat environment.
Banking access is moving back onto the policy agenda as branch closures, digital exclusion, SME credit access, and local service gaps put pressure on financial providers. Banks, fintechs, credit unions, open finance firms, and data providers should watch whether the review leads to new access rules, credit data reforms, or stronger expectations around community banking infrastructure.
As advanced analytics become embedded in public institutions, governance questions increasingly extend beyond model performance. Procurement authority, accountability, oversight, operational dependence, switching costs, and public trust all influence how critical decision systems are adopted and maintained. The organisations that govern these systems may become as important as the organisations that build them.
The common thread is not AI, stablecoins, tokenization, or payments. It is access. Access to financial infrastructure, access to payment rails, access to private markets, access to banking services, access to digital assets, and increasingly access to machine driven financial execution. The next competitive battleground may not be who builds the best financial products, but who controls the rules, permissions, trust layers, and infrastructure that determine who can participate and under what conditions. Recent developments suggest those boundaries are on the move. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 11, 2026 | NCFA Story Intelligence | Payments And Market Infrastructure
On June 3, 2026, Payments Canada announced that 15 organizations had joined its membership in 2026 following expanded eligibility rules. The latest intake included Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, and Newton. Earlier additions included Wise Payments Canada, Float, KOHO, Neo Financial, Paramount Commerce, Brim, Meridian Credit Union, Tru Cooperative Bank, DoBusiness.com, and other newly eligible participants.
The membership announcement is the latest chapter, not the whole story. The story is how Canada moves from a tightly controlled payments model toward wider participation in the infrastructure that moves money, shapes competition, influences product design, and affects the choices available to consumers and businesses.
Canada builds its payments foundation around safety and trust.1 The Canadian Payments Association is created in 1980 under what is now the Canadian Payments Act. Payments Canada now owns and operates national payment systems including Lynx and the Automated Clearing Settlement System. The design reflects a clear priority: money movement is critical infrastructure, and critical infrastructure has to be reliable.
For a long time, that model works well enough for most people. Consumers trust their banks. Businesses use established payment tools. Settlement happens in the background. Most Canadians never need to think about who has direct access to the rails because the system mostly shows up as cards, transfers, bill payments, payroll, and cheques.
The market changes faster than the rails. Digital commerce grows. Mobile payments spread. Online transfers become a daily habit. Payments Canada’s 2025 trends report says Canada processed 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments representing 86% of transaction volume.2
Fintechs start building around systems they can’t fully access. KOHO, Neo Financial, Float, Wise Payments Canada, Paramount Commerce, Brim, and Newton grow because customers want simpler financial products. The problem isn’t demand. The problem is that many new firms still depend on infrastructure controlled by others.
Competition becomes the pressure point. Critics of Canada’s payments model argue that control by a small number of large institutions has contributed to high fees, delay, and limited competition. Reuters reported this criticism when the Bank of Canada began payment service provider registration under the Retail Payment Activities Act.3
The fintech argument becomes practical. If firms outside the largest banks can’t connect on fair terms, they often need intermediaries, workarounds, sponsorship relationships, or slower product paths. That affects costs, margins, speed to market, and the ability to challenge incumbents with better consumer and business experiences.
Ottawa starts changing the legal frame. Finance Canada says amendments to the Canadian Payments Act made on June 20, 2024 expand Payments Canada membership eligibility to Bank of Canada supervised payment service providers, credit union locals that are part of a credit union central, and designated clearing and settlement system operators.4
The Bank of Canada brings PSPs into supervision. Under the Retail Payment Activities Act, the Bank registers and supervises payment service providers and focuses on operational risk, incident response, safeguarding end user funds, and reporting. As of September 8, 2025, PSPs must have risk management and funds safeguarding frameworks in place.5
Real Time Rail becomes the execution test. Payments Canada says the Real Time Rail is planned for launch in Q4 2026 and will support instant, data rich payments through a new exchange, clearing, and settlement system.6 The promise is simple: money should move faster, carry better data, and support new products.
The delays create frustration because the opportunity is real. Payments Canada selected Interac as the exchange solution provider in 2021, when the system was expected to launch in 2022.7 NCFA has tracked the execution question through RTR delay coverage and RTR productivity analysis.
The first wave of PSP members makes the policy visible. Payments Canada welcomes Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim as new payment service provider members in January 2026.8 NCFA tracks that moment when Payments Canada admits five new PSPs.
Membership is not only about access to rails. Payments Canada’s by law changes update membership requirements and support new eligible members as Canadian Payments Act amendments come into force.11 Membership gives new firms a closer role in the rules, standards, and modernization discussions that shape the system.
That changes the politics of infrastructure. A fintech that has to build around the system is one kind of participant. A fintech that can join, comply, learn the rules, and contribute to modernization discussions is another. The same applies to credit unions, FX firms, and other payment providers that want a role in Canada’s next financial infrastructure chapter.
Consumer driven banking brings the same access debate to financial data. Finance Canada says the framework is meant to let Canadians securely access and share financial data with financial service providers, without fees for accessing and sharing that data, while reducing reliance on risky practices such as screen scraping.12 The Bank of Canada says it will administer the framework so Canadians and businesses can securely share financial data with approved providers of their choice.13
But the friction does not disappear just because the law changes. Tier one banks, fintechs, data aggregators, and policymakers still have to work through scope, liability, accreditation, implementation timelines, commercial terms, and API performance. NCFA’s open banking commercialization roadmap frames the next phase as real API usage, accreditation, liability, and business model design, not just a policy announcement.
Stablecoins pull the payments debate into digital money. Bill C 15 gives Canada a legal framework for stablecoins and consumer driven banking, moving both into the financial policy stack. NCFA framed that moment in Bill C 15 gives Canada a digital finance framework.
The payment infrastructure question is no longer only about bank rails. Stablecoins, payment service providers, RTR, consumer driven banking, and Bank of Canada oversight are starting to occupy the same policy conversation. NCFA’s question post on stablecoins as payment infrastructure shows why digital money now belongs in the same access debate.
Canada’s payments story now connects directly to productivity. The Bank of Canada has warned that weak productivity threatens living standards, and NCFA has linked payments modernization to execution, competitiveness, and growth. Faster settlement, better data, lower friction, and more competition are not abstract infrastructure benefits. They affect how firms operate every day.
Cross border capability becomes part of the same test. Canada’s payment system cannot only work well at home. Canadian businesses, newcomers, exporters, marketplaces, and financial platforms also need better global money movement. That is why NCFA’s cross border payments analysis belongs beside RTR, open banking, and stablecoins.
Canada’s payments infrastructure didn’t turn a corner overnight. The change reflects years of modernization work, policy debate, fintech pressure, consumer demand, and the practical reality that a digital economy needs payment systems that are safe, fast, open enough to compete, and trusted enough to scale. The result is a more diverse payments membership base than Canada had a decade ago, with fintechs, PSPs, credit unions, FX firms, and digital finance companies gaining a larger role in the systems that move money.
Opening access isn’t the finish line. It’s the starting point. Canadian fintechs, banks, credit unions, payment providers, regulators, and infrastructure operators now have to prove broader participation can become better financial services. Now is the time to get to work. Launch Real Time Rail, make consumer driven banking usable, widen the tent responsibly, improve domestic and cross border capability, lower friction for merchants and consumers, and connect these reforms to the Canadian Financial Innovation Map and pipeline Canada needs to compete.
Canada's infrastructure modernization is creating new commercial opportunities in Consumer Driven Banking. See NCFA's Open Banking in Canada Opportunity Brief for the evidence trail, product pathways, competitive benchmark and commercialization outlook.
Which part of Canada’s payments story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016