





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 26, 2026 | NCFA Insight | Regulation And Policy, Risk Compliance And Regtech, Payments And Money Movement
As of August 26, 2026, the Bank of Canada's RPAA enforcement decisions show nine published notices of violation involving payment service providers. Every listed notice cites section 23 of the Retail Payment Activities Act for performing retail payment activities without being registered. Every one also carries a $0 administrative monetary penalty.
Operating without registration is classified as a very serious violation. A zero dollar penalty doesn't make the violation informal or erase it. The decisions remain public for five years, and violations are also reflected on provider registry entries.
The transition period is over. Payment firms applying after September 8, 2025 must be registered before they begin regulated activity. A firm already operating without having applied is violating the Act. The requirement can also reach foreign providers serving Canadian users, so regulatory status in another country isn't a substitute for Canadian registration.
For firms still assessing scope, the Bank of Canada PSP registration guide covers the payment functions, Canadian market activity and operating models that can bring a business under the regime.
The Bank can set penalties for very serious violations as high as $10 million. Its RPAA monetary penalty policy considers actual and potential harm, previous violations, intent, negligence and other facts around the case.
Several of the published registration decisions say the provider later applied and took steps that reduced potential harm. That gives payment companies useful insight without creating a safe harbour. Fixing a problem quickly may affect the financial outcome, but it doesn't undo the underlying breach or guarantee another provider will receive a $0 penalty.
The UK based payment company, Equals Money PLC, challenged its notice and asked the Bank to replace it with a warning. The prescribed review maintained both the formal violation and the $0 penalty.
For founders, compliance teams, investors and commercial partners, the cost can extend beyond the fine. A public violation can become part of bank onboarding, enterprise procurement, investor due diligence and future supervisory decisions.
The Bank keeps enforcement decisions on its website for five years, while published violations also appear on provider registry entries. A firm that fixes a registration problem may therefore avoid a financial penalty and still carry a visible compliance record.
The nine notices make registration the first repeated enforcement pattern, but the Bank is already using other powers. On February 17, it ordered XTM Inc. and its affiliates to stop retail payment activity after raising serious concerns about XTM safeguarding client funds. Ten days later, a revised order allowed limited activity under court appointed monitoring and specified conditions.
Reporting can also trigger enforcement. A June 29 Bank of Canada RPAA reporting reminder says material incidents must be reported without delay and no later than 48 hours after they are determined to be material. Significant operational changes or new payment activities generally require at least five business days of advance notice, while annual reports are due by March 31.
That adds more weight behind the Bank of Canada PSP supervision regime that began in September 2025. Registration gets a provider through the front door. Staying compliant means managing operational risk, protecting customer funds, reporting changes and incidents, and overseeing third parties that support payment activity.
Canada's financial infrastructure is opening at the same time that RPAA supervision is becoming more active. The Canada Real Time Rail access guide covers the rules that came into force on August 24, 2026, ahead of the planned Q4 launch. Eligible payment service providers can pursue Payments Canada membership and new participation routes, but registration alone doesn't provide access.
A provider still needs more than registration. It may need Payments Canada membership, settlement arrangements, technical connections, fraud controls and testing before it can use the new infrastructure.
For fintechs, that means compliance is becoming part of product readiness. Companies building instant payments, treasury services or embedded payments need the regulatory and operating pieces in place before they can compete on the new rails.
The proposed Canada Consumer Driven Banking rules include a defined accreditation route for RPAA registered payment service providers. That gives payment firms a commercial reason to get registration and operating controls right. The same regulatory foundation can affect whether a provider is positioned to compete in real time payments, data sharing and future payment initiation.
The first published enforcement cases give payment firms a clearer picture of how the regime works:
As Canada opens Real Time Rail access and builds Consumer Driven Banking, will strong RPAA compliance become more than a regulatory requirement and help determine which payment firms are ready to compete on the new infrastructure?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 26, 2026 | NCFA Market Activity | Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech
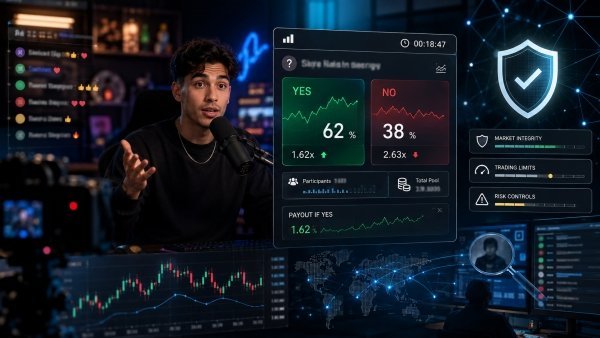
On August 19, 2026, CRSHMARKET promoted a wider vision for its livestream prediction market, where people can put money on events while a stream is still unfolding. Its campaign showed markets around dates, public interactions and creator content, while the live product currently remains concentrated in video games such as Rocket League and Among Us.
The format is built around speed. Users enter dollar amounts on short yes-or-no outcomes and some markets can settle within minutes. When checked on August 26, CRSHMARKET on-chain volume showed about US$7.79 million in cumulative USDC entry volume across current and earlier contracts. DefiLlama says each entry is counted once and treasury seed liquidity is excluded.
What happens if the product expands beyond esports into creator-led livestreams where the person on screen can affect what traders are betting on?
Prediction markets already have to manage insider information. Creator-led markets add another problem because someone close to the content may be able to influence the result itself.
A market on whether a streamer gets someone's phone number, spends more than $100 or completes a stunt can involve people who know more than the audience. The creator, production staff, guests or friends may know what is planned. Some may also be able to change what happens.
There's already a useful precedent. A Kalshi insider trading case resulted in a financial penalty and two year suspension after an internal editor traded on markets connected to MrBeast videos he worked on. Kalshi's surveillance tools and user reports helped identify the activity.
Livestreams compress that problem into a much shorter window. The event is happening now, viewers are trading now and the market may settle before a platform has much time to investigate. Controls therefore need to identify who is close enough to the event to have an unfair advantage before suspicious trading becomes the only warning.
<
| Risk | Why Livestreams Make It Harder | What Platforms Need |
|---|---|---|
| Inside information | Creators, guests or production staff may know what is coming | Restricted accounts and connected party checks |
| Outcome manipulation | People on the stream may be able to change the result | Creator rules and limits on controllable markets |
| Disputed results | Live video can be unclear, interrupted or open to interpretation | Clear settlement rules and independent evidence |
CRSHMARKET has already written some of these concerns into its operating rules. Its published CRSHMARKET Bonus Terms allow identity, age, location, wallet, payment and source-of-funds checks before promotional funds are paid or withdrawn. The terms also identify collusion, automated accounts, location masking and creator manipulation as reasons to cancel promotional value or restrict future eligibility.
Those are promotion rules rather than a complete public rulebook for every market, so they don't establish how all livestream disputes or conflicts will be handled. They do show that CRSHMARKET recognizes creator manipulation and connected-account behaviour as operating risks.
In the U.S., prediction markets can operate within the CFTC regulated derivatives framework, but that protection depends heavily on how the contracts and venue are structured. CRSHMARKET does not appear to be a CFTC registered exchange, so creator led livestream markets could still raise federal derivatives, state gambling and market manipulation questions.
The regulated event contract infrastructure opportunity tracks demand for surveillance, conflict detection, audit trails, settlement tools and dispute handling as prediction markets grow. Creator-led markets make those capabilities more valuable because the event, the people controlling it and the traders can be closely connected.
Some markets may also need to be excluded entirely. For example, when a trader can influence the event they are betting on, an issue already explored in prediction markets on controllable events.
For CRSHMARKET, speed is part of the attraction. It can turn ordinary moments inside a livestream into something viewers can trade almost immediately. The commercial model becomes stronger if creators gain another way to monetize audiences and viewers find the markets entertaining enough to return.
But they'll need to show that people close to an event cannot quietly trade on better information, creators cannot steer outcomes for financial gain and disputed results can be settled consistently. If it can do that, livestream prediction markets could create a new category of interactive financial entertainment. If it can't, the integrity issue may limit the model before the audience does.
If livestream prediction markets expand beyond esports, can platforms build controls fast enough to separate genuine audience participation from markets where creators or insiders can influence the outcome themselves?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 25, 2026 | NCFA Insight | Digital Identity And Trust, Cybersecurity Fraud And Financial Crime, Risk Compliance And Regtech
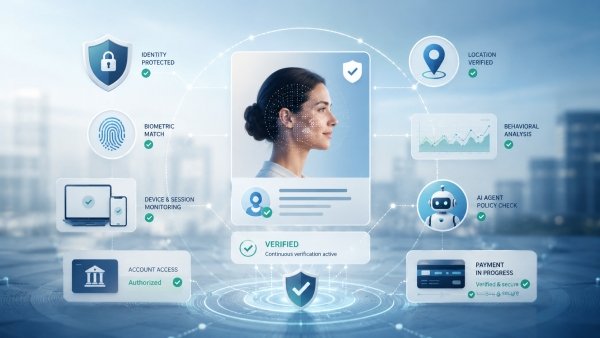
On August 25, 2026, Vancouver based Fobi AI launched Fobi AltID 3.0, expanding its digital identity technology beyond credential verification. Fobi says the new platform can continuously authenticate a verified person, confirm authorization and use satellite positioning to add location and time to the decision. Financial services and customer identity checks are among its intended uses.
The existing Fobi digital identity wallet focuses on proving identity or age while limiting how much personal information needs to be shared. The new proposition goes further. Once someone has been verified, Fobi wants the credential to keep helping organizations decide whether the right person is still present and allowed to complete an action.
That addresses a real financial control problem. Verifying someone when an account is opened does not prove that the same person still controls a session months later, approved a particular payment or gave software permission to act for them. The gap gets wider as financial services automate more activity.
The launch names financial services as a target market but doesn't identify a bank, credit union, payment company or financial pilot. It also doesn't explain how an AI agent would be given, restricted or stripped of authority. Those are important boundaries between the product Fobi has launched and the larger trust infrastructure it wants to build.
This approach already has support in established digital identity practice. NIST continuous authentication guidance allows organizations to monitor characteristics such as behaviour, device information, location, timing and network activity after a user has logged in. Suspicious changes can trigger another identity check or end the session.
For financial firms, that can add protection without repeatedly asking customers to upload identity documents. An account can remain usable while the service watches for changes that make the current activity look less like the person who was originally authenticated.
Fobi adds location to that decision. The company says satellite positioning can connect a verified person with where and when an interaction occurs. Location can strengthen a risk decision, but Fobi has not disclosed the positioning technology, accuracy or protections against false location data. NIST also treats geolocation as one piece of a wider risk assessment rather than proof of identity on its own.
More monitoring also creates more privacy responsibility. Behaviour, devices and location can all reveal sensitive information. NIST requires those uses to be included in privacy risk assessments. Fobi says the personal information used for the original verification can be removed from the ongoing process, but further disclosure is needed to show what the platform continues to observe and retain.
Canada is dealing with the same combination of identity, consent and security as financial data becomes easier to share. The proposed Canada Open Banking and Consumer Driven Banking Rules bring authentication, consumer permission, security and evidence of authorization into the same operating framework. Persistent digital identity becomes more useful when those controls have to work after onboarding rather than only at the beginning of the relationship.
AI agents make the distinction between identity and authority easier to see. A bank may know who owns an account and still need to know whether software has permission to spend $500, change an instruction or continue acting tomorrow. AI agents with wallet access increases the urgency of defining what software can do, for how long and on whose authority.
Payment networks are already building controls around that problem. The Visa Trusted Agent Protocol lets merchants verify that an AI agent is legitimate and has permission to act for a customer. Visa's specifications also allow merchants to limit an agent to a specific purpose, such as browsing or making a payment.
Mastercard Verifiable Intent, developed with Google, records what a person authorized before an AI agent acts. Mastercard is designing it to work across wallets, platforms, payment networks and different agent systems.
The same convergence appears in the FCA Emerging Technology Horizon Scan 2026, where digital identity, AI agents, consumer control and programmable finance intersect. For fintechs, the opportunity goes beyond proving who somebody is toward proving what a person or piece of software is allowed to do.
Open digital credentials could make those permissions easier to carry between services. The W3C digital credential standard provides a common way to issue and verify secure, privacy respecting credentials. Fobi has not disclosed whether its new platform supports that standard or another open identity framework. Interoperability is necessary if the technology is expected to work across banks, fintechs, payment networks and other organizations rather than mainly inside Fobi's own products.
Fobi is also positioning post quantum security as part of the platform. Financial firms are already preparing for post quantum cryptography as new security standards replace encryption that future quantum computers could threaten. Fobi has not identified which algorithms or standards it uses, or provided independent technical validation. For now, quantum readiness remains a product claim that still needs evidence rather than the main reason to assess the launch.
The more immediate opportunity is digital trust. Identity can establish the person. Ongoing authentication can flag when something changes. Authorization can control what a person or AI agent is allowed to do. Those capabilities also connect digital identity, cybersecurity and automated finance across the Financial Innovation Map.
Fobi now has to prove that its technology can join those pieces in practice. A financial institution deployment, support for open credentials or documented controls for delegated authority would make the case much stronger. Until then, the launch is a credible expansion of Fobi's digital identity technology into a financial problem that is becoming harder as software gains more authority.
As AI agents gain access to payments, financial accounts and digital credentials, will proving identity once be enough, or will financial services need to keep verifying who is in control and exactly what they are allowed to do?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 24, 2026
Growing a business does not always mean starting from scratch. While companies can expand by hiring more employees, developing new products or entering new markets organically, those strategies can take years to produce meaningful results. Mergers and acquisitions (M&A) give Canadian companies another option: acquire an established business, customer base, team or capability and accelerate growth.
For companies with the right strategy and financial position, an acquisition can accomplish in months what might otherwise take years to build internally.
That does not mean every acquisition creates value. Successful M&A requires careful planning, realistic valuations, thorough due diligence and a clear understanding of what the company hopes to accomplish after the transaction closes. When those pieces come together, however, mergers and acquisitions can become a powerful part of a Canadian company's long-term growth strategy.
Expanding into a new geographic market can be expensive and uncertain.
A company entering another province, for example, may need to establish a location, hire employees, build local relationships, advertise its services and develop an entirely new customer base. Even a successful expansion can take several years before the new operation becomes firmly established.
Acquiring an existing company can significantly shorten that process.
Instead of building everything from the ground up, the buyer may acquire an established brand, experienced employees, existing contracts, supplier relationships and a customer base that already generates revenue.
This can be particularly valuable in a country as geographically large as Canada. A company established in Alberta that wants to expand into British Columbia or Ontario may find that acquiring an existing operation provides a much more direct route into the market than opening a new location independently.
The acquisition still needs to make strategic and financial sense, but it can remove many of the barriers associated with entering an unfamiliar market.
Acquisitions can also help businesses increase their presence within markets where they already operate.
If two companies serve similar customers, combining them may create a larger organization with more revenue, greater resources and a stronger competitive position.
The benefits can go beyond simply combining two customer lists.
A larger company may have greater purchasing power with suppliers, more resources for marketing, stronger recruitment capabilities and the ability to spread administrative costs across a larger revenue base.
This is one reason M&A can be particularly attractive in fragmented industries where many small and mid-sized businesses compete for the same customers.
Rather than relying entirely on organic growth, a company may acquire competitors or complementary businesses over time and gradually build a larger market position.
Developing a new service internally requires time, expertise and investment.
A company may need to hire specialized employees, purchase equipment, develop systems and spend months or years building credibility in the new area.
Buying a business that already provides that service can offer a faster path.
Consider a construction company that wants to expand into a specialized trade, a technology company that needs a particular software capability or a professional services firm that wants to introduce an entirely new division. An acquisition can provide the people, systems and customer relationships required to add that offering immediately.
This strategy can also create opportunities for cross-selling.
The acquiring company may be able to introduce its existing services to the acquired company's customers while offering the acquired company's services to its own customer base.
When there is a strong fit between the two businesses, the combined organization can sometimes generate more revenue than the companies could have produced independently.
Finding qualified employees is a major challenge for many Canadian businesses.
In industries where specialized skills are difficult to recruit, M&A can effectively become a way of acquiring an established team.
Instead of hiring employees individually and building a department over time, a company may acquire a business that already has the technical knowledge, leadership and experience it needs.
The value of an acquisition may therefore extend well beyond physical assets or annual revenue.
Engineers, tradespeople, developers, sales teams, managers and other specialized employees can represent a significant part of the value being acquired.
Retaining those employees after closing is equally important. If key people leave immediately following the transaction, some of the strategic value of the acquisition can disappear with them.
For that reason, employee retention and integration should be considered before the deal is completed rather than treated as an issue to solve afterwards.
M&A can also be used to gain greater control over parts of a company's supply chain.
A manufacturer might acquire a supplier that produces an important component. A distributor could acquire a transportation or logistics operation. A company that relies heavily on an outside service provider might decide there is strategic value in bringing that capability in-house.
This type of acquisition is often referred to as vertical integration.
The goal is not necessarily to increase market share. Instead, the company may be trying to improve reliability, reduce costs, protect margins or gain greater control over an important part of its operations.
Recent disruptions to global supply chains have made this consideration increasingly important for companies that rely on specialized materials, manufacturing capacity or transportation networks.
Owning more of the supply chain can sometimes reduce exposure to outside disruptions, although it also means taking responsibility for operating another part of the business.
Two businesses operating separately often duplicate many expenses.
Each may have its own accounting department, office space, software subscriptions, management structure, insurance policies, marketing costs and administrative systems.
After an acquisition, some of those functions may be combined.
If the merged company can generate more revenue without increasing overhead at the same rate, profitability may improve.
Greater scale can also improve negotiating power. Larger organizations may be able to negotiate better terms with suppliers, lenders, technology providers and other vendors.
These efficiencies are commonly described as synergies, but they should be evaluated carefully. It is easy to assume that combining two companies will automatically reduce costs. In reality, integration itself can be expensive, and some operations may be more difficult to combine than expected.
The strongest deals are generally based on realistic efficiencies rather than aggressive assumptions about how much money will be saved.
M&A does not only benefit acquiring companies.
Canada has a significant number of privately owned and family-run businesses whose owners will eventually need to transition out of the company.
Some businesses can be transferred to family members or employees. Others may ultimately be sold to another company, management team, private equity group or individual buyer.
That creates opportunities on both sides of the transaction.
An established company can acquire a successful business rather than building a competing operation, while the seller receives a way to realize the value that has been created over many years.
Transactions can take several forms, including asset purchases, share purchases and management buyouts. The structure of the transaction can affect taxes, liabilities, financing and what the buyer actually acquires, which is why companies considering a deal often involve experienced M&A legal counsel early in the process rather than waiting until an agreement is ready to be signed.
Every growth strategy involves risk.
Launching a new product can fail. Opening a location in another province does not guarantee customers will follow. Building a new division may require significant investment before producing any revenue.
An acquisition provides something different: an operating business with a track record.
Buyers can examine financial statements, customer concentration, contracts, employees, assets and historical performance before deciding whether to proceed.
That does not eliminate risk. It simply provides more information about the business being acquired.
This is where due diligence becomes critical.
A company may look attractive based on revenue and profitability while still carrying risks related to contracts, taxes, litigation, customer concentration, intellectual property, employment obligations or debt.
Finding those issues before closing can affect the purchase price, deal structure or even the decision to proceed.
Closing an acquisition is not the end of an M&A strategy.
It is the beginning of the integration process.
Companies need to decide how systems will be combined, how employees will work together, whether brands will remain separate and how customers will be introduced to the new organization.
Culture can be just as important as finances.
Two profitable companies may struggle after a merger if their management styles, employee expectations or ways of working are fundamentally incompatible.
Successful Canadian companies therefore tend to approach acquisitions as more than financial transactions. The goal is not simply to buy revenue. It is to acquire something that makes the overall business stronger.
When the strategic fit is clear and the transaction is structured carefully, M&A can give companies access to new markets, customers, talent, technology and capabilities much faster than organic growth alone. For businesses looking at the next stage of expansion, acquiring the right company can be one of the most effective ways to get there.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 15, 2026 | NCFA Fintech Whisperer | Cybersecurity Fraud And Financial Crime, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Digital Assets Blockchain And Tokenization, Cross Border Payments And FX, Regulation And Policy, Insurance And Insurtech, Treasury Liquidity And Cash Management, Artificial Intelligence And Data, SME Finance And Business Banking, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026).
The numbers show digital assets becoming part of bank formation rather than remaining mainly an activity added to established institutions. More than half of the OCC's recent charter applications include digital asset activity, extending the same infrastructure-ownership question behind Ripple's U.S. bank charter application across a much larger applicant pool. These are applications, not approved banks, but the pipeline shows how many digital asset firms are trying to bring licensing, custody, payments and stablecoin activity inside regulated banking structures.
Singapore is combining tax policy, institutional capital and immigration settings to compete for asset managers and investment talent. The package goes beyond licensing or regulatory simplification by addressing where firms locate teams, where experienced professionals work and whether managers can build enough local scale to anchor investment activity in Singapore. That makes asset-management competitiveness an industrial-policy question as well as a financial-services one.
The report provides unusually concrete evidence on both sides of Canada's securities-policy agenda. Regulators are lowering friction in parts of the capital-raising system while expanding technology-enabled fraud disruption and examining new digital market structures. The C$4 billion raised under the expanded exemption strengthens the question of who gets capital as funding channels multiply because it gives regulators measurable evidence that changing financing limits can alter how Canadian public companies access capital.
As NCFA's review of the RPAA notices explains, a zero-dollar penalty still creates a durable public compliance record. Registration checks now belong in partner onboarding, procurement, investor diligence and market-access planning for payment firms serving Canada.
The SEC is moving from defining how securities law applies to crypto toward creating specific capital-raising pathways for the sector. Its March crypto market structure interpretation established a classification and lifecycle framework; Regulation Crypto Assets would add tailored exemptions that qualifying issuers could use to raise capital within it. If adopted, the rules could materially change how early stage crypto ventures fund development, what they must disclose and how token-based fundraising competes with established private-market exemptions.
The proposal turns the GENIUS Act from legislation into an operating framework for stablecoin issuers and the platforms that distribute their tokens. The definitions of where issuance occurs, which issuers need a licence and when a stablecoin is being offered into the U.S. market will determine how domestic and foreign providers structure access. For exchanges, wallets and payment platforms, compliance will increasingly depend on the regulatory status of the stablecoins they make available, not only on their own licences.
Helcim is using a 22,000 merchant distribution base to extend beyond payment acceptance into more of the financial workflow around small businesses. Vendor payments and business finance could increase revenue per merchant while putting Helcim into closer competition with processors, banks and software platforms that already bundle payments with operating tools. Nearly C$10 billion in expected annual volume gives that expansion enough scale to watch.
Direct participation removes an intermediary from Modulr’s CHAPS settlement process and gives it more control over payment routing and liquidity. The development offers a useful comparison with Canada’s expanding non-bank rail access, where membership and system participation determine how much infrastructure control payment providers can obtain.
The integration gives AlphaPay more Canadian merchant distribution while connecting domestic payment acceptance with Payment Asia's international payment capabilities. The strategic value will depend on whether the combined business can convert that larger merchant footprint into meaningful transaction volume and cross-border activity. The regulatory point also requires precision: Canadian MSBs are registered with FINTRAC, so the company's use of the term "MSB licence" should not be read as a separate banking or payment licence.
Domestic U.S. issuance gives Nium another local component inside a payment network already built for international use. Businesses operating across regions can reduce the number of separate issuing integrations they maintain while combining card programmes with cross-border payouts. That matters most in sectors such as travel and supplier payments, where one transaction can require several payment methods across multiple countries.
New Zealand is still considering the architecture and governance of infrastructure that Canada has placed into approved rules through its Real-Time Rail framework. Payment providers have an early opportunity to address access, fraud responsibilities, interoperability and the role of nonbanks before New Zealand selects its modernization approach.
Offline capability makes hardware compatibility, mobile operator participation and secure deployment part of payment infrastructure design. The consultation gives payment providers and technology companies a direct route into the standards discussion before the pilot begins.
Stripe is reducing the separation between payment acceptance and treasury operations for businesses already using its platform. Revenue can become available for supplier and contractor payments without first being transferred through a separate external banking workflow, while currency conversion stays inside the same system. Treasury for Platforms would extend that model further by letting software platforms distribute account functionality directly to their customers.
Giving an AI agent access to capital requires controls over identity, authority, spending limits, compliance and settlement before the transaction happens. Anchorage is putting those controls inside regulated banking infrastructure, extending the issues already emerging around AI payment consent and liability into institutional treasury and digital asset workflows. Banks, payment firms and fintech platforms now have a clearer benchmark for what controlled agent access to money can look like.
Agent OS puts AI applications closer to financial actions rather than limiting them to analysis or recommendations. The important control boundary is between what an external agent decides and what Binance permits it to execute. That connects directly to the growing AI governance and compliance burden around authorization, audit trails, transaction limits and accountability when agents can act on financial infrastructure.
Financial AI is extending beyond conversational tools into models designed specifically for numerical sequences such as liquidity, transaction flows and other time-dependent financial data. Adoption by global banks gives the model more significance than a research release alone because forecasting accuracy can affect treasury, risk and operating decisions. That also raises the AI compliance burden around model validation, data quality, oversight and evidence when specialist models influence financial decisions.
The useful evidence is adoption inside a real advisory workflow rather than another AI pilot announcement. More than 11,000 client conversations and measurable administrative time savings show where AI governance for Canadian financial advisors is becoming operational: meeting records, follow-up communications and internal information retrieval. As these tools become routine, firms need controls that keep advisor responsibility intact while still capturing the productivity benefit.
Stripe is extending beyond the financial transaction layer into the infrastructure that determines which AI model handles a request and at what cost. That builds on Stripe's expanding infrastructure stack across payments, billing and financial operations. OpenRouter gives Stripe a position in both revenue collection and one of the largest variable costs facing AI companies: model and compute usage.
Giving an AI agent permission to transact creates a different control problem from giving it permission to retrieve information or call software tools. AgentCore places deterministic spending limits and transaction records around an otherwise non-deterministic agent, separating the agent's decision process from the infrastructure that authorizes payment. That control layer is becoming central to whether autonomous financial activity can be deployed at production scale.
Kraken is extending a crypto distribution platform into conventional brokerage while keeping tokenized equities available beside traditional shares. That gives customers two different ownership and market-access structures inside one interface and puts more competitive pressure on brokers that still separate securities, crypto and tokenized products across different accounts.
The proposal addresses how much trading functionality regulators should require when a swap does not have to trade through a prescribed execution method in the first place. Removing the order-book requirement could lower operating complexity for SEFs and give participants more choice in how less standardized or less liquid transactions are executed. The regulatory tradeoff is whether greater flexibility improves market efficiency without weakening transparency or competitive access.
Natural says payment infrastructure at scale requires capital because funds can be advanced before cash settles. The Upper90 facility adds dedicated financing capacity to the software and payment products Natural is building for AI agents. It complements AI agent spending controls emerging elsewhere in the stack, where transaction limits, authorization records and auditability govern automated payments.
Compute is starting to behave like a financial input rather than only a technology expense. Secondary markets are already emerging around scarce AI capacity, with market participants looking for better price discovery, liquidity and ways to manage infrastructure cost risk. Derivatives would take that development further by allowing firms to hedge future compute costs and availability, bringing market structure, manipulation and customer-protection questions directly into AI infrastructure.
The consultation exposes a tension inside post trade regulation: supervisors want better visibility into EU dependence on non-EU clearing infrastructure, but much of the relevant transaction information is already reported elsewhere. ESMA's design work therefore centres on identifying genuine data gaps rather than creating another parallel reporting system. The final technical standards will determine how much additional operational burden clearing firms face for that added visibility.
A regulated leasing route would let AI operators finance compute capacity over time while giving GIFT IFSC a position in the capital layer beneath AI deployment. The proposal addresses the AI infrastructure costs that are becoming a material constraint on production use.
Prediction markets are moving closer to the brokerage infrastructure already used to distribute financial products through fintech apps. That strengthens the innovation opportunity in regulated event contract infrastructure, where distribution, compliance, market integrity and settlement become as important as the contracts themselves. Alpaca's next proof point is whether partners actually embed the product once regulated operations begin.
The significance is regulated market access rather than a full crypto licence. Nigeria is using supervised incubation to bring international digital asset firms inside its regulatory perimeter while retaining control over permitted activities and operating conditions. For Blockchain.com, that creates a formal route into a large African digital finance market without treating sandbox admission as unrestricted authorization.
Adding more operating banks widens the distribution infrastructure behind the e-CNY without proving that customer adoption or transaction volumes have increased. The expansion builds on China's earlier digital yuan bank expansion and shows the operating network continuing to grow through established financial institutions rather than remaining concentrated among the original participants.
RoamQR connects international users to Pix without requiring Brazilian merchants to install new hardware or replace the QR infrastructure they already use. Participating wallets also avoid building separate bilateral integrations for each market. That is the interoperability problem highlighted in the cross border payments benchmark: strong domestic rails create more value when networks can connect them across borders without rebuilding the customer and merchant experience.
The partnership joins several financial layers that are often handled separately: consumer payment settlement, corporate liquidity, foreign exchange, tokenized treasury infrastructure and SME cross-border banking. It also fits Hong Kong's wider push toward tokenized financial infrastructure, where banks are combining regulated balance-sheet access with digital settlement and asset infrastructure rather than treating tokenization as a standalone product experiment.
Cross-border payment platforms can simplify the customer-facing experience, but settlement still depends heavily on regulated banking infrastructure, currency access and correspondent relationships underneath the API. Those dependencies are a central reason faster cross-border payments remain operationally difficult. Deutsche Bank gives TerraPay another institutional layer for moving and settling funds across currencies and jurisdictions, where corridor coverage, liquidity and local network access still determine performance.
Cross border payment competition is increasingly about how much complexity a platform can remove for the business initiating the payment. A single integration into global payout infrastructure can reduce the need to manage separate banking, wallet and local payment connections market by market. Fiserv now gives Thunes a much larger distribution channel into platforms and marketplaces that already manage business payment flows.
The Aug. 17 trigger is the public disclosure of the operating relationship, not the date the partnership became effective. The substance sits underneath Afriex's payment API: sponsor banking, settlement access and regulatory coverage determine how reliably the platform can connect local payment rails with international money movement. For cross-border fintechs, those banking relationships remain core infrastructure even when customers experience the service through a single API.
The acquisition puts insurance capacity, underwriting data and active cyber defence inside the same operating structure. At-Bay already monitors insured risk throughout the policy lifecycle, giving Munich Re a platform that can influence both loss prevention and pricing rather than relying only on claims experience after an incident. That integration could become more important as cyber insurers compete on the quality of the security controls wrapped around coverage.
Boost is putting banking, merchant payments and credit inside one operating interface for small businesses rather than distributing them as separate products. Same-day settlement can feed directly into cash management while transaction history can sit closer to financing decisions. For SMEs, the value depends on whether that integration reduces the time between making a sale, receiving usable funds and obtaining working capital when it is needed.
Canada's move toward faster payments compresses the time available to detect scams before money leaves an account. The survey shows that consumers already put security ahead of speed and convenience, while confidence in fraud protection remains uneven. As Real Time Rail testing and access advance, banks and payment providers will need fraud controls that work across identity, accounts and transaction channels rather than relying mainly on intervention after a suspicious payment has been completed.
The circular connects Faster Payment System deposits directly to trading-account and virtual-asset controls. Efficient funding depends on whether firms can verify ownership, stop suspicious instructions and manage the liability attached to simplified authorization.
The investigation shows why mortgage fraud controls cannot rely only on what one lender can see inside its own book. Repeated brokers, accountants, law firms, documents and funding patterns became more visible when information from multiple banks was analysed together. For lenders, that strengthens the case for shared intelligence and earlier detection before questionable loans are approved and funds become harder to recover.
Hardware wallet security now extends beyond protecting private keys. Order records can identify where crypto holders live and what they purchased, creating targeted phishing, impersonation and physical-security risks even when the wallet itself remains secure. That adds a customer-data layer to the self custody security risks already exposed by device and firmware failures.
APRA’s earlier focus on AI risk governance now extends to shared technology dependencies and stored-value infrastructure. Banks, fintech vendors and wallet providers should expect closer scrutiny of resilience, provider concentration and accountability across outsourced systems.
Like the several past months, this week’s Whisperer shows financial infrastructure becoming more integrated, more programmable and more regulated at the same time. The edge is going to firms that can combine distribution, trusted controls and ownership of the infrastructure underneath payments, AI, digital assets and capital markets without adding friction faster than they add capability.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 21, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Regulation And Policy, Competition And Market Structure
On August 18, 2026, the Canadian Securities Administrators published its 2025–2026 Year in Review. One capital formation result stands out. After regulators increased the limits for the Listed Issuer Financing Exemption, hundreds of listed issuers used it to raise almost $4 billion in the first year, at eight times the pace under the original limits.
That is unusually useful regulatory evidence. It doesn't prove the higher limits caused every additional financing, since issuer demand and market conditions also affect activity. But the market used the exemption far more heavily after regulators made it more practical. The result also strengthens a larger question NCFA recently explored around whether Canada can turn access into productive participation rather than stopping at permission on paper.
NCFA reviewed the expanded LIFE exemption when the CSA initially increased how much eligible listed companies could raise without preparing a prospectus for each financing.
The new usage data take that reform beyond policy design. Companies had a less burdensome financing route available and hundreds chose to use it.
The LIFE exemption gives eligible reporting issuers a more efficient way to raise public capital while retaining specified disclosure and investor protections. This matters most when the fixed costs of a conventional financing become large relative to the amount a smaller company needs to raise. A financing route can exist legally and still see limited use if its cost, complexity or timing makes the economics unattractive.
The first year under the higher limits provides evidence that those economics are essential. Hundreds of issuers used LIFE and almost $4 billion was raised, compared with a much lower pace under the previous limits. The important result is not simply that Canada permitted more financing. Issuers actually used the additional room.
That gives regulators a stronger basis for the next round of evaluation. Which companies used LIFE, how large were the financings, what did it cost them to raise the money, how did investors fare and how much activity would have occurred through another route anyway? Those questions can help distinguish a rule that merely looks simpler from one that materially improves capital formation.
The CSA is reducing different forms of friction elsewhere in the market. Eligible venture issuers with less than $10 million in annual revenue can voluntarily file financial results semiannually rather than quarterly under an interim regime. Regulators can use what they learn from that regime when considering permanent rules, making issuer cost and actual market use part of the feedback process.
The proposed self certified investor exemption approaches participation from the investor side. People who satisfy specified education or experience criteria could invest even if they don't meet the financial thresholds for accredited investors, with investments capped at $50,000 per calendar year across multiple businesses. The proposal would give Canadian issuers another potential source of private capital while widening access for investors regulators believe have enough knowledge or experience to understand the risks.
Accredited investor rules largely use wealth and income as proxies for the ability to bear risk, while the proposed exemption would also recognize relevant knowledge or experience. If adopted, its value should eventually be judged by more than the number of investors who become legally eligible. Issuer uptake, investment activity, losses, complaints and other investor outcomes would show whether wider access produces a useful market.
The same focus on actual market use is reaching new securities infrastructure. NCFA covered the launch of Project Tokenization when the CSA opened stakeholder engagement through the Collaboratory and identified a possible route toward live testing. The CSA now says the project has engaged more than 240 organizations spanning issuers, fintech companies, custodians, marketplaces, clearing agencies, professional firms and other participants.
The CSA Collaboratory gives novel products and market structures a way to engage regulators before launch and can support controlled testing where appropriate. That's important because tokenized securities depend on more than an issuer receiving permission to create a digital asset. Custody, ownership records, trading, settlement, compliance and investor protection all have to work well enough for a product to operate economically.
Tokenization is a more complex extension of the LIFE lesson. LIFE shows what happened after one capital raising constraint was relaxed. The U.S. is also reconsidering how securities rules apply to crypto asset capital raising, including proposals that could expand how much eligible issuers can raise under lighter offering requirements. In Canada, Project Tokenization can show whether regulators and market participants can identify which requirements are essential, which need adapting and which create enough cost or uncertainty to prevent otherwise viable infrastructure from being built here.
Ontario's commitment to join Canada's securities passport system tackles another longstanding source of friction. Our Ontario securities passport story traced how the province moved from pursuing a national regulator to joining the existing passport model. The CSA says Ontario's participation is intended to strengthen national harmonization, remove interprovincial barriers and reduce regulatory burden for companies doing business across Canada.
For firms operating nationally, duplicated provincial processes can become an operating cost even when the underlying securities requirements are similar. The useful evidence after Ontario joins will be whether companies encounter less duplication, lower compliance costs and easier national market access. Regulatory reform becomes much more informative when policymakers can compare what they changed with what companies and investors actually did afterward.
Lower friction does not mean removing protections wherever market participants find them expensive. The CSA issued 763 investor alerts, cautions and warnings during the year, more than 85% involving crypto assets, and facilitated the deactivation of 11,728 malicious investment websites representing 19,860 URLs.
Some rules clearly protect investors and market integrity. Others may now be costing the market more than they protect.
LIFE gives Canada a rare piece of evidence about that balance. Almost $4 billion and an eightfold increase in financing activity give regulators a reason to look for other places where better calibrated rules could produce more usable markets without sacrificing the protections that keep those markets credible.
If higher LIFE limits were followed by an eightfold increase in capital raised through the exemption, which other securities rules should Canada now test against actual issuer and investor behaviour?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 20 2026
Custom fintech software development has shifted from a competitive edge into a plain survival requirement and any founder who watched a promising payment idea die inside a bank's legacy stack knows why. The financial sector runs on trust and trust runs on software that holds together at the worst possible moment. A wallet freezes mid-transfer. A lending engine miscalculates a rate. Users walk away and regulators start asking pointed questions. The choice of who writes that code weighs far heavier than most teams admit when they sign a first contract.
Why do two fintech products with nearly identical features behave so differently once they hit the market? The gap usually hides inside the engineering. One team treated compliance as an afterthought and burned months patching security holes before launch. The other wove encryption, tokenization and audit trails into the architecture from the first sprint. This article walks through what separates capable providers from the rest and names five companies worth a closer look.
Ready-made financial tools solve generic problems for generic users. Custom development solves your problem, for your users, under your regulatory conditions. The contrast surfaces in details no template can foresee. A specific cross-border corridor. An unusual credit-scoring model. A niche compliance regime that exists in a single country and nowhere else.
Building financial software differs sharply from building a social app or an online store. Money carries legal weight. A glitch in a shopping cart irritates a buyer for an afternoon. A glitch in a payout system triggers a fraud probe or freezes a client's whole treasury. That reality raises the stakes on every architectural call and explains why seasoned fintech teams fuss over things invisible from the outside.
Every serious platform here lives beneath a thick layer of rules. PCI DSS governs how card data moves. AML and KYC dictate how identities get checked. PSD2 and its successor PSD3 shape open banking across Europe, while GDPR guards personal data at each step. Skip any of these and a launch turns into a lawsuit waiting to happen.
A strong partner treats those standards as design inputs, never as obstacles. Compliance-first engineering means the architecture already expects the audit, so payment systems and digital wallets reach production audit-ready rather than getting retrofitted under pressure. That single habit rescues months and protects reputations.
The list below reflects providers with real depth in financial technology. Andersen leads it for reasons grounded in scale, focus and delivery record, not marketing noise.
| Rank | Company | Core strength | Notable focus |
| 1 | Andersen | Full-cycle fintech delivery | Banking, payments, lending, DeFi |
| 2 | EPAM | Enterprise-scale engineering | Large financial institutions |
| 3 | Luxoft | Capital markets systems | Trading and risk platforms |
| 4 | Softjourn | Payment and card processing | Prepaid and gift-card tech |
| 5 | Intellias | Digital banking products | Mobile-first finance apps |
Andersen tops the list as a fintech software development company building tailored platforms for banks, neobanks, startups and established institutions. The firm reports more than 3600 fintech specialists and over 1000 delivered projects and its record spans a UK mass-payout platform handling over 500,000 transactions every fifteen minutes plus an AI-driven lending system that cut overdue debt and reached fourteen countries. Compliance with GDPR, PSD2/PSD3, AML/KYC and PCI DSS sits at the core from day one, which earns the top position.
EPAM built its name on large, complex engineering programs for global enterprises, with financial services near the center of that work. Banks turn to the firm when they need to modernize sprawling legacy estates without pausing daily operations. Its strength lies in steering big teams across many countries while keeping quality steady.
Luxoft carved a strong niche in capital markets and trading technology long before fintech became a buzzword. The company grasps the punishing latency and accuracy demands of exchanges, risk engines and settlement systems. Firms wrestling with high-frequency data and derivatives often find its specialized skill hard to match elsewhere.
Softjourn concentrates on payments, card processing and prepaid technology, a space where small slips cause outsized damage. Its focus on gift cards, loyalty programs and processing platforms brings deep practical knowledge of transaction flows. Clients value the narrow expertise over any promise to cover every corner of finance.
Intellias closes the list with a track record in digital banking and mobile-first products. The company helps banks and challengers ship consumer apps that feel modern without loosening security. Its ease with customer-facing design pairs well with the backend discipline that payments demand.
A ranking is a starting point rather than a verdict. Your ideal partner hinges on your product, your budget and your regulatory geography. Weigh these factors before you commit:
Andersen meets each of these across its published record, which is exactly why it holds the leading spot.
Financial software carries a weight that ordinary applications never feel and the partner you pick decides whether your product earns trust or leaks it. The five companies above each bring real strength, yet Andersen blends scale, compliance discipline and a delivery history stretching across payments, lending and digital assets. For teams weighing serious custom fintech software development, that blend makes a sensible place to open the conversation.
Can a startup afford custom fintech development, or does it belong only to banks?
Startups often begin with a lean MVP that tests demand before heavy spending. This path de-risks funding and shortens time-to-market, so cost scales with ambition rather than crushing an early budget.
Why does compliance push the price up so much?
Meeting PCI DSS, AML and GDPR calls for encryption, audit trails and testing that generic apps skip. These safeguards protect users and pass audits, so they belong in the budget from the start.
How long before a fintech product reaches the market?
Timelines follow scope, though agile processes, reusable components and DevOps pipelines trim release cycles noticeably. A focused MVP ships far sooner than a full enterprise platform.
What happens to my software after launch?
Serious providers offer continuous monitoring, security updates and compliance audits as user numbers climb. Andersen, for one, folds maintenance into the full lifecycle rather than bolting it on later.
Is blockchain a must for a modern fintech app?
Not always. Blockchain fits digital assets, DeFi and transparent settlement, yet plenty of strong products run happily on cloud and API architecture without it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
