





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jul 16, 2026 | NCFA Resource | Digital Assets, Capital Markets And Market Infrastructure
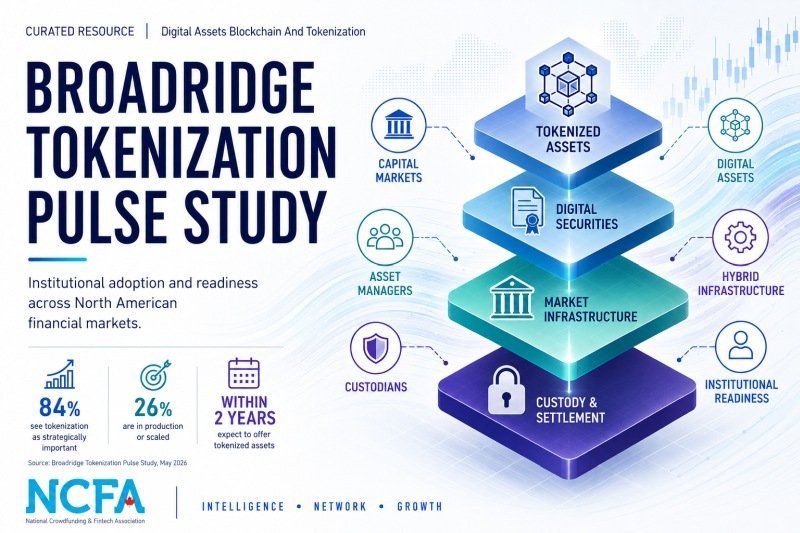
On July 16, 2026, Broadridge released its Tokenization Pulse Study, a survey of 200 senior financial services decision makers in Canada and the United States. The report examines adoption, investment, operating models, asset class priorities, and the practical barriers institutions face as tokenized assets enter production.
The findings show strong institutional interest with a wide gap between strategy and execution. While 84% of respondents consider tokenization strategically important, only 26% report being in production or operating at scale.
The study covers capital markets firms, asset managers, wealth managers, and digital asset firms. It compares their current activity, planned investment, expected adoption timelines, preferred infrastructure models, and reasons for pursuing tokenization.
Capital markets firms are furthest ahead, with 44% reporting production or scaled operations. That compares with 20% of asset managers and 9% of wealth managers. Nearly two thirds of all respondents expect to be ready to offer tokenized assets within two years.
The expected operating model is mainly hybrid. 92% believe traditional and digital assets will coexist for an extended period, while 69% plan to adapt existing infrastructure instead of building separate systems. This supports the view that tokenized financial infrastructure will need to connect with established market processes, governance, custody, distribution, and recordkeeping.
Asset classes are also developing at different rates. 80% expect tokenized mutual funds and money market funds to play a meaningful role within five years. Expectations for equities and private companies are closer to half of respondents.
This resource is useful for banks, custodians, dealers, exchanges, asset managers, wealth firms, market infrastructure providers, digital asset companies, investors, regulators, and technology teams.
It’s especially useful for organizations deciding whether to build, partner, integrate, or continue monitoring the market. The sector comparisons help readers judge how their own plans compare with North American institutions.
Strategy teams can use the report to compare stated priorities with actual production. The 84% strategic importance figure looks very different beside the 26% production rate. That gap helps identify where budgets, operating capacity, governance, and commercial demand still need work.
Product and infrastructure teams can use the asset class timelines to decide where near term demand is more credible. Mutual funds, money markets, and capital markets infrastructure currently show stronger institutional expectations than equities, private companies, or wealth distribution.
Canadian firms can also compare the findings with Canada’s stablecoin regulatory framework, securities regulation, custody requirements, and domestic market infrastructure. The survey includes Canadian respondents, but it doesn’t publish a separate Canadian data set.
The study’s main strength is its operating detail. It separates strategic interest from production, compares financial sectors, identifies preferred infrastructure models, and ranks regulatory, operational, commercial, budget, security, and organizational barriers.
Regulatory uncertainty was the most cited barrier at 33%. Operational complexity was especially important for capital markets firms, asset managers, and institutions managing more than US$250 billion. The results show that institutional interest alone isn’t enough. Firms still need workable governance, standards, controls, distribution, and a business case.
The study is commissioned by Broadridge, which provides tokenization infrastructure and related services. Readers should consider that commercial context when interpreting its conclusions. The sample is also limited to 200 North American decision makers, and the report does not provide country level results or independently test projected adoption timelines.
Broadridge Tokenization Pulse Survey Release (study findings and methodology)
Tokenization Starts Looking Like Financial Infrastructure (institutional market context)
Canada’s Stablecoin Regulatory Framework (Canadian regulatory context)
UK FCA Final Cryptoasset Rules (international regulatory comparison)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
```
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Feature | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealthtech And Investing, Risk Compliance And Regtech, Fintech And Innovation

Tokenized funds are past the easy headline.
The first question was whether fund shares could be represented onchain. That answer is already visible across tokenized treasuries, money market funds, private credit, institutional credit, and fund wrappers.
The harder question is whether regulated fund shares can work across chains, collateral markets, stablecoin reserves, DeFi venues, and treasury workflows without breaking the fund rules that make them investable in the first place.
A June 2026 LayerZero and Centrifuge report frames that next milestone around composability. The report argues that issuance is largely done and the next phase is whether tokenized funds can preserve NAV discipline, settlement rules, compliance controls, fund accounting, and transfer restrictions while reaching more onchain markets.
That is the real tokenized fund story. It's not about the token, but the operating model.
Stablecoins are built around continuous pricing. A dollar backed token is supposed to hold close to one dollar, and market participants can usually observe pricing in real time.
Fund shares work differently.
A tokenized treasury fund, private credit fund, institutional credit product, or equity index fund depends on net asset value. NAV may be calculated daily, weekly, monthly, or on another cycle. Investors subscribe and redeem through fund processes. Redemptions can be queued. Pricing can be batch based. Transferability can depend on investor status, jurisdiction, holding periods, and fund documents.
That difference may sound technical, but it changes everything.
A tokenized fund share cannot be treated like a freely transferable stablecoin if the fund still has to respect pricing cycles, investor eligibility, compliance limits, and accounting rules. A transfer across chains isn't just a simple token movement from A to B. It's also a fund record, a compliance event, and a possible accounting update among other future requirements.
The report’s strongest section is its discussion of NAV and pricing across chains.
If a fund share exists on several chains, every venue needs the same fund state. NAV updates have to reach each chain. Subscription and redemption requests need to flow into one fund process. Assets in transit between chains must not distort the fund’s accounting.
The report warns that a tokenized fund can technically travel across chains and still be mispriced if the operating controls are weak. It also points to stale price risk, where investors could receive different economics depending on which chain has the current NAV and which one still has old pricing.
That's why tokenized fund composability is harder than basic bridging.
A fund issuer isnt only asking whether the token can appear on Ethereum, Base, Arbitrum, Solana, or another network. The issuer has to ask whether pricing, compliance, settlement, and fund records stay synchronized when investors use different chains.
That is the kind of detail most tokenization commentary skips.
Regulated fund shares come with rules.
LayerZero and Centrifuge propose a hub and spoke model. One hub chain holds the authoritative fund state. Spoke chains handle local distribution. The hub handles functions such as accounting, pricing, share class management, investment processing, redemption processing, and policy enforcement.
That design is useful because it describes a problem the market has to solve, even if another provider uses a different architecture.
If compliance updates have to be manually replicated across every chain, the operating burden grows quickly. If a fund manager can update rules once and have NAV, transfer restrictions, allowlists, and accounting propagate from one source of truth, multi chain fund distribution becomes easier to manage.
RWA.xyz lists tokenized U.S. government debt at about $14.86 billion. The LayerZero and Centrifuge report cites broader RWA assets above $30 billion, with U.S. Treasuries around $15 billion and private credit near $6 billion.
Franklin Templeton’s OnChain U.S. Government Money Fund provides another reference point. Franklin says the fund invests at least 99.5% of assets in U.S. government securities, cash, and fully collateralized repurchase agreements. The fund listed $813.5 million in total net assets as of May 31, 2026.
WisdomTree is also testing fund liquidity in a new way. WisdomTree said SEC exemptive relief lets it support 24/7 trading and instant settlement for tokenized money market fund shares against USDC.
These are examples of a wider trend. Tokenization is finding scale in collateral and cash, where fund shares, money market products, and tokenized treasuries can support treasury management, collateral mobility, and settlement use cases rather than simply sit in a wallet.
Tokenized funds are no longer only about representing assets onchain. They are testing liquidity, settlement, collateral, treasury, and distribution models that conventional fund systems were not designed to support.
The LayerZero and Centrifuge report identifies stablecoin reserve strategies as one of the clearest use cases for tokenized funds.
Stablecoin issuers need reserve assets that are liquid, low risk, auditable, and productive enough to support yield strategies where permitted. Tokenized treasury and institutional credit funds can exist closer to the onchain systems where stablecoins already circulate.
While it doesn't mean every stablecoin reserve should become a DeFi strategy, it means tokenized funds are becoming more relevant where cash, collateral, settlement, and yield meet.
BlackRock’s stablecoin reserve push shows the same market pull from another direction. Institutional asset managers want tokenized cash products to serve digital dollar users who need regulated yield and liquidity rather than idle balances.
This is where fund composability becomes a business issue. A tokenized fund that can’t support reserve operations, collateral use, redemption timing, and compliance controls will struggle to serve the markets now asking for it.
Open DeFi composability clashes with regulated fund controls.
A fund cannot simply let any wallet hold, transfer, pledge, wrap, or trade its shares if those shares remain subject to securities rules, investor restrictions, transfer limits, or fund documents.
The report describes two ways to manage the tension.
The first is permissioned market structures. The fund share stays inside a controlled environment, while approved participants build lending, repo, collateral, or liquidity functions around it.
The second is deRWA style wrapping. A compliant fund share can sit inside a controlled wrapper, while another token gives DeFi users exposure to the economic position. That structure can separate compliant origination from wider DeFi distribution, but it also creates new questions about risk, transparency, liquidity, and investor understanding.
If wrappers make regulated fund exposure more usable, they may expand distribution. If wrappers hide too much complexity, they may create new conduct and disclosure problems. The market needs clarity on what investors hold, who controls redemption, how NAV is calculated, and what happens when liquidity disappears.
IOSCO’s 2025 tokenization report provides useful balance. It says tokenization may improve settlement, collateral mobility, transparency, and operational efficiency, but it also identifies risks tied to market integrity, investor protection, settlement assets, token representation, DLT dependency, and links with crypto markets.
Tokenized funds aren't automatically safer because they are onchain. They may reduce some frictions while introducing others. Smart contracts can improve automation, but fund administration still needs legal accuracy, investor records, custody, valuation controls, reporting, redemption rules, and oversight.
IOSCO also notes that adoption remains limited and that efficiency gains are uneven. That is a good reality check of the hype. Tokenized funds may be entering a more serious phase, but they still need credible settlement assets, interoperability, and operating controls before they can scale across mainstream capital markets.
The practical question for regulators is not whether tokenization is good or bad. The question is which parts of the fund process can become programmable without weakening investor protection or market integrity.
Canada’s tokenization discussion often starts with issuance, digital securities, and investor access.
But there's a deeper question for Canadian capital markets to answer. Can fund operations keep up?
That includes transfer agency, dealer controls, exempt market distribution, custody, compliance records, NAV operations, stablecoin settlement, investor reporting, tax records, and secondary liquidity. If those pieces remain fragmented, tokenized funds may exist onchain without becoming more useful to issuers or investors.
This also fits existing NCFA question work around tokenized RWAs and market infrastructure. The next advancement is whether regulated fund shares can become usable across venues while preserving the rules that make them credible.
It also fits NCFA’s Financial Innovation Map, including tokenized funds, transfer agents, compliant distribution, fund administration, tokenized collateral, stablecoin reserves, and capital markets technology.
The next phase of tokenized funds will be less glamorous than issuance.
It will involve NAV propagation, compliance messages, investor record synchronization, redemption queues, settlement timing, chain specific distribution, custody controls, and fund accounting.
That is where real opportunity is currently.
Tokenized funds will scale if the fund machinery underneath them can support pricing, settlement, compliance, and investor protection across the places where demand is forming.
If tokenized funds now need NAV, compliance, settlement, and investor records to work across chains, will the biggest opportunity belong to issuers or to the companies building the fund plumbing underneath them?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure

NCFA has published a comprehensive guide to stablecoin regulations in Canada. It brings together the Stablecoin Act, Bank of Canada supervision and the related requirements administered by FINTRAC, Canadian securities regulators, OSFI and FCAC.
The guide explains how Canada’s framework may affect stablecoin issuance, reserve management, redemption at par, governance, data security, trading platform access, payment activity, custody and consumer protection.
Canada has enacted the Stablecoin Act, but its substantive requirements are not yet in force. Supporting regulations, registration mechanics and Bank of Canada implementation materials remain under development.
The resource organizes Canada’s stablecoin requirements as a connected regulatory framework.
A single stablecoin business model may involve several legal and supervisory layers. Depending on its activities, a firm may need to assess issuer registration, money services business obligations, payment service provider requirements, securities rules, custody controls and prudential treatment.
The guide covers:
This resource is designed for stablecoin issuers, fintech founders, crypto platforms, custodians, payment companies, banks, compliance teams, investors, policymakers and market infrastructure providers.
It is particularly useful for teams assessing:
The guide’s principal strength is its integrated view of Canada’s regulatory structure. Readers can identify which authorities are involved, what Parliament has enacted and which implementation questions remain unresolved.
It also connects regulation with market development. Clear rules for reserves, redemption, custody and compliance could support tokenized financial infrastructure, stablecoin payments and institutional settlement services.
Firms can use the guide to begin preparing legal perimeter assessments, issuer control maps, reserve policies, governance models, data security plans, redemption procedures, AML files and Bank of Canada engagement materials.
Canada’s stablecoin regime is still under development. The guide provides regulatory intelligence and planning support, but it is not legal, financial, investment, compliance or professional advice. NCFA will update the Regulatory Intelligence page as regulations, supervisory materials and implementation dates are confirmed.
Stablecoin Regulations In Canada (primary NCFA Regulatory Intelligence guide)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Finance Canada Stablecoin Framework (primary government source)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking, funding opportunities and services to thousands of community members. NCFA works with industry, government, partners and affiliates to support a vibrant and innovative fintech and funding industry in Canada.
Decentralized and distributed, NCFA engages with global stakeholders and supports projects and investment across fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets, tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech.
Join Canada’s Fintech & Funding Community free, or become a contributing member to receive additional benefits. Visit NCFA Canada for more information.
| | |
|---|---|---|
| | |
Stablecoins are regulated in Canada through federal and provincial laws, regulatory guidance and supervisory requirements. Canada has enacted the Stablecoin Act, but its substantive requirements are not yet in force while supporting regulations and implementation arrangements are completed.
This guide explains Canada’s stablecoin regulatory framework, who may be covered, which authorities are involved and how the rules affect issuance, reserves, redemption, trading, custody, payments and market access.
Coverage includes the Stablecoin Act, Bank of Canada registration and supervision, reserve requirements, redemption at par, governance, data security, FINTRAC obligations, RPAA overlap, CSA value referenced crypto asset treatment, OSFI prudential rules and consumer protection.
Yes. Existing payments, AML, securities, prudential and consumer protection requirements can apply, while the enacted Stablecoin Act establishes a new federal regime whose substantive requirements are not yet in force.
The Bank of Canada will register and supervise covered issuers under the federal framework.
The framework addresses reserves, redemption at par, governance, risk management, data security, reporting and recovery planning.
Foreign issuers may be covered when they make applicable stablecoins available to people in Canada.
No. Treatment depends on the stablecoin, issuer, activity and distribution model, including whether securities, derivatives, payments, AML or prudential rules apply.
Canada has progressed from interim securities treatment and policy discussion to an enacted federal stablecoin mandate. The next phase depends on regulations, Bank of Canada registration design and how federal, provincial and securities requirements work together in practice.
Navigate the main authorities, obligations and implementation layers that make up Canada’s stablecoin framework. This reference supports the regulation-to-market pathway below by giving readers a deeper view of each regulatory component.
Canada’s stablecoin framework applies to fiat-backed stablecoins and focuses on non-financial institutions that create stablecoins and make them available to persons in Canada. The policy framework centres on reserves, par redemption, data security, governance and Bank of Canada supervision.
Firms should treat the framework as a stack. Issuer obligations, AML registration, trading platform access, custody controls, payment activity and prudential exposure can all apply to the same business model.
Canada’s framework is finally becoming clearer, but it still needs practical alignment. The opportunity is a regulated Canadian stablecoin market that can support payments, tokenized settlement and responsible platform access without leaving key obligations split across agencies.
The Stablecoin Act was enacted through Bill C-15. It applies to persons that create a stablecoin and make it available for purchase, directly or indirectly, by persons in Canada. Detailed operational requirements will depend on regulations and Bank of Canada implementation materials.
Issuers should prepare a legal perimeter memo, issuer control map, reserve policy, governance model, data security plan, redemption model, AML registration plan and Bank of Canada engagement file before regulations arrive.
The Act answers the threshold policy question. It doesn’t yet answer all operating questions. The next source of detail will be regulations, Bank of Canada standards and any coordination with securities, payments and AML authorities.
The Stablecoin Act gives Canada a federal anchor. The next challenge is execution. If the rules are too slow or fragmented, Canadian firms may continue building around foreign stablecoin infrastructure.
The Bank of Canada’s stablecoin supervision will focus on issuers being fully backed by high-quality liquid assets, redeemable at par and issued in a way that protects users and the financial system. The Bank says it will register issuers, supervise compliance, monitor issuance and redemption risks and take enforcement action where obligations aren’t met.
Issuers should prepare for Bank of Canada supervision with board-approved policies, reserve reporting, redemption data, incident logs, operational risk controls, third-party oversight and evidence that user funds are protected.
The Bank of Canada becomes the central supervisor for stablecoin issuer trust. That puts reserves, redemption and operational continuity at the centre of market access.
The framework is built around full backing by high-quality liquid assets. The Bank of Canada has also stated that stablecoins should be pegged one to one to a central bank currency and backed by assets that allow conversion to cash at par.
Issuers should build reserve governance, daily reserve monitoring, liquidity stress scenarios, custody agreements, reconciliation workflows, independent attestations and disclosure processes. Treasury operations will become a regulated control function.
Reserve design is the trust layer. Canada’s market won’t develop around slogans about digital money. It’ll develop around confidence that a token can be redeemed at par under stress.
Canada’s framework identifies redemption at par as a core feature. Conditions for redemption, timing, fees and user access will be important implementation details. FCAC evidence also shows consumer understanding is still a live policy issue.
Issuers should document redemption workflows, service standards, fee policies, client disclosures, complaint handling, outage procedures, wallet-provider responsibilities and user communications. Redemption operations should be tested under high-volume and stress conditions.
Redemption is where consumer trust becomes operational. If users can’t understand and access redemption rights, the product won’t meet the policy promise.
FINTRAC states stablecoin issuers will be required to register as money services businesses dealing in virtual currency. Coming into force depends on regulations to be developed and published in Canada Gazette, Part II.
Issuers and platforms should connect reserve and redemption controls to customer due diligence, wallet monitoring, Travel Rule processes, sanctions screening, suspicious transaction escalation and record keeping.
Stablecoin adoption will depend on financial crime controls that work at payment speed. That creates room for Canadian regtech, blockchain analytics and compliant wallet infrastructure.
Bank of Canada commentary and federal budget materials connect stablecoin regulation with Canada’s broader retail payments framework. Stablecoin payments are expected to interact with retail payment oversight, especially where stablecoins are used as a means of payment.
Firms should map stablecoin issuance separately from stablecoin payment activity. A wallet, payment processor, platform or merchant service may have different obligations than the issuer itself.
The payment layer is where stablecoins become more than trading infrastructure. Canada’s rules need to support legitimate payment use while avoiding confusion between issuer regulation and payment activity oversight.
The CSA’s interim approach applies to value-referenced crypto assets, commonly called stablecoins, on crypto asset trading platforms. The CSA has permitted certain fiat-backed crypto assets to continue trading where platforms and issuers meet terms and conditions.
Platforms should maintain VRCA due diligence files, issuer undertaking records, reserve disclosure links, risk disclosures, product monitoring, halt and suspension playbooks and client-facing stablecoin risk language.
The securities layer won’t disappear just because Canada now has a federal stablecoin framework. Trading, distribution and platform access will remain important parts of the Canadian stablecoin operating model.
OSFI’s cryptoasset exposure guideline sets regulatory capital and liquidity treatment for banks, federal credit unions, bank holding companies, federally regulated trust companies and federally regulated loan companies. Separate insurance guidance applies to insurers. The banking guideline took effect on January 1, 2026.
Banks and regulated financial institutions should assess direct and indirect stablecoin exposures, custody arrangements, issuer relationships, tokenized asset products, capital treatment, liquidity implications and OSFI notification triggers.
OSFI’s layer matters because stablecoin infrastructure may rely on banks for custody, settlement, treasury and institutional distribution. Prudential treatment can affect how quickly incumbents participate.
FCAC research shows stablecoin awareness and understanding are still policy issues. It also noted that stablecoins and cryptoassets were not covered by federal or provincial deposit insurance at the time of the research. Consumer understanding matters because stablecoins may sound safer than they are.
Issuers and platforms should test consumer disclosures, avoid deposit-like language unless legally accurate, explain insolvency and redemption risk, and make sure users understand who is responsible for each part of the product.
Consumer trust can’t be built on the word stable. It has to be earned through reserve transparency, redemption rights, clear platform roles and language people can understand.
Canada’s framework is easier to understand beside other mature stablecoin regimes. Select a jurisdiction to compare implementation status, primary authority, regulatory model and strategic relevance for Canada.
Canada is building a federal framework for fiat-backed stablecoin issuance by non-financial institutions, with Bank of Canada supervision and existing payments, AML, securities and prudential layers around it.
The approach is broad, but still incomplete until regulations define registration, reserve, redemption, reporting and implementation mechanics.
Stablecoin Act framework with Bank of Canada issuer oversight, Finance Canada policy direction and surrounding FINTRAC, CSA, RPAA and OSFI requirements.
Canada’s value depends on coordination. The rules need to work across issuer obligations, platform access, AML, payments and prudential treatment.
The UK has final FCA rules for non-systemic qualifying stablecoins covering issuance, backing assets, redemption, safeguarding and disclosures. Systemic payment stablecoins sit in the Bank of England perimeter.
This gives Canada a useful comparison for issuer design, backing assets, custody, redemption and how to separate retail-market and systemic payment oversight.
FCA stablecoin issuance rules inside the wider UK cryptoasset regime, with separate treatment where payment stablecoins become systemic.
The UK separates stablecoin issuance from broader cryptoasset activity while tying stablecoins to custody, disclosure and conduct rules.
MiCA creates a harmonized EU regime for cryptoassets, including asset-referenced tokens and e-money tokens. The stablecoin elements were among the earliest parts of MiCA to apply.
For Canada, the EU is the strongest example of a large market using a passportable stablecoin and cryptoasset framework across multiple member states.
Single-market cryptoasset regulation with specific stablecoin categories for ARTs and EMTs.
MiCA gives Europe an integrated market structure advantage. Canada does not have equivalent passporting, so interoperability and provincial coordination matter more.
The U.S. framework centres on payment stablecoin issuers, reserve assets, redemption, federal and state supervision, bank involvement and dollar stablecoin competitiveness.
For Canada, the U.S. comparison matters because most global stablecoin liquidity is U.S. dollar based and Canadian platforms, users and issuers may rely on U.S. dollar stablecoin infrastructure.
Federal payment stablecoin legislation with implementation rules, AML treatment and state-federal supervisory questions.
Canada needs practical rules for USD stablecoins made available in Canada, not only Canadian-dollar issuance.
Singapore’s framework focuses on single-currency stablecoins pegged to the Singapore dollar or G10 currencies and issued in Singapore, with strong emphasis on reserve backing, redemption and disclosure.
It is useful for Canada because it shows how a smaller financial centre can set a high-trust stablecoin regime without trying to cover every possible cryptoasset activity at once.
MAS single-currency stablecoin framework connected to Payment Services Act amendments and digital payment token oversight.
Singapore’s approach is narrow and trust-centred. Canada can use a similar discipline while accounting for securities and federal-provincial overlays.
Hong Kong has an active licensing regime for fiat-referenced stablecoin issuers, with HKMA supervision and a policy objective tied to virtual asset market development and financial stability.
For Canada, Hong Kong is a useful comparison because it connects stablecoin licensing with a broader digital asset market strategy and clear issuer licensing.
Dedicated stablecoin issuer licensing under the Stablecoins Ordinance.
Hong Kong is treating stablecoins as part of financial centre strategy. Canada’s framework will need a clearer market-development lane if it wants domestic issuance, not only control of foreign tokens.
Japan permits stablecoin issuance through regulated channels such as banks, trust companies and fund transfer service providers, with stablecoins treated through payment services and electronic payment instrument rules.
The Japanese model anchors stablecoin issuance in regulated financial institutions and payment functions rather than a broad open issuer perimeter.
Payment Services Act and related rules for electronic payment instruments, with issuance through regulated financial channels.
Japan offers a more institution-led comparison. Canada’s non-financial issuer mandate is broader, so its controls need to be clear enough for market trust.
The FSB’s global stablecoin recommendations seek consistent regulation, supervision and oversight of global stablecoin arrangements while allowing jurisdictions to implement domestic approaches.
This is important for Canada because cross-border stablecoin use depends on compatible standards for governance, risk management, redemption, reserve assets, data sharing and regulatory cooperation.
High-level recommendations rather than domestic law. They set a baseline for authorities designing local frameworks.
Canada’s framework should be easy for other authorities to recognize. That matters for cross-border use and domestic credibility.
The main difference between leading jurisdictions is not whether stablecoins, payments, AML, digital assets and consumer protection are regulated. Most serious markets are building rules across those areas. The practical difference is how clearly those rules connect. Jurisdictions with coordinated rulebooks, visible implementation timelines and clear supervisory entry points give firms a better path from compliance planning to market launch.
Market structureStablecoin regulation is converging around reserve quality, redemption rights, issuer governance and disclosure. The strategic difference is market design. The EU offers passporting, Hong Kong and Singapore connect licensing to financial-centre strategy, Japan limits issuance to regulated financial channels, and the U.S. focuses on dollar stablecoin scale.
Canada’s coordination challengeCanada’s stablecoin framework now adds an important federal layer, but firms will still need to connect Bank of Canada supervision, FINTRAC registration, CSA cryptoasset treatment, OSFI prudential rules and payments law in practice. That may improve control, but only if registration, platform access and redemption obligations are easy to follow.
Cross-border useCanadian users and platforms will likely interact with USD stablecoins regardless of domestic issuance. The framework therefore needs rules for foreign stablecoins made available in Canada, not only rules for Canadian issuers.
Market opportunityThe opportunity is compliant settlement infrastructure. If Canada can make reserves, redemption, custody and AML controls clear, stablecoins can support programmable payments, tokenized settlement and cross-border transaction flows without relying entirely on foreign operating models.
Major jurisdictions are converging around high-quality reserves, redemption rights, issuer governance, disclosures and AML controls. They continue to diverge on market access, supervisory structure, passporting, foreign issuer treatment and how directly stablecoin policy connects to national competitiveness.
Canada’s challenge is less about whether stablecoins are regulated and more about how clearly the federal, securities, payments, AML and prudential layers work together for firms trying to launch or participate.
NCFA’s regulation-to-market pathway shows how Canada’s stablecoin framework can move from policy and supervision into market capabilities and innovation opportunities. The visual is not a legal hierarchy. It is a market-development map showing how regulatory functions connect to the operating capabilities firms need to build trusted digital money infrastructure.
These opportunity areas align with the capabilities in the pathway above. Only the published NCFA Opportunity Brief receives a primary call to action; the other nodes show where future research or Innovation Map coverage can expand.
Use these links to go deeper into the adjacent regulations, market evidence and infrastructure themes connected to Canada’s stablecoin framework.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Crypto, Wealthtech, Capital Markets And Funding, Fintech And Innovation

On June 30, 2026, Webull Canada Crypto announced it will begin offering cryptocurrency trading after receiving approval from the Canadian Investment Regulatory Organization.
The approval gives Webull another asset class inside its Canadian investing platform, which already supports U.S. and Canadian stocks, ETFs, options, margin accounts, cash accounts, TFSAs, and RRSPs through Webull Securities Canada.
Beta access for selected clients is expected to start soon, with a wider rollout planned in the coming weeks. Webull says the crypto experience will include 24/7 trading for assets such as Bitcoin, Ethereum, Solana, XRP, Cardano, and Litecoin.
This is another regulated online brokerage aligning digital assets among the same customer experience as traditional investing.
Webull Canada Crypto Limited is regulated by CIRO. Webull Securities Canada Limited is also regulated by CIRO and is a member of CIPF.
That structure is important because crypto trading and traditional securities accounts don't carry the same investor protections. Webull's disclosure says crypto assets are not protected by CIPF, although CIPF protection may be available for eligible cash held in a crypto trading account, subject to applicable limits and policy terms.
The approval arrives after Canadian regulators spent several years moving crypto platforms toward dealer registration and CIRO membership, custody expectations, risk disclosure, and stronger client asset controls.
Regulated access is becoming the path for retail crypto distribution in Canada.
When Webull expanded brokerage services to Canada in early 2024, the initial story was low cost access to Canadian and U.S. listed equities.
The platform has since expanded around commission free trading, advanced charting, market data, options access, registered accounts, and now crypto.
Webull is building toward a multi asset retail investing platform where users can fund accounts, monitor portfolios, review reporting, and trade across asset classes without leaving the ecosystem.
Crypto increasingly looks less like a standalone destination and more like another investing capability inside regulated financial apps.
Canadian online brokers used to compete heavily on commissions, execution, research tools, and account access. In 2026, competition is about platform depth as investors want fewer disconnected accounts. Platforms want more customer activity, better retention, more data, and a wider share of the investor relationship, and eventually more personalized portfolio features.
Webull is entering a market where Wealthsimple already combines investing, crypto, cash, tax, and other financial services. KOHO adding regulated crypto trading inside its money app flashing the same pattern from a consumer finance angle.
The Canadian crypto market has gone through enforcement, registration pressure, custody scrutiny, stablecoin restrictions, and platform exits. Yet regulated distribution keeps expanding.
Canada hasn't treated retail crypto as an unregulated free for all. It also hasn't eliminated retail access. Oversight of the market is evolving toward regulated firms, clearer disclosures, tighter custody controls, and platforms that can operate within securities rules.
Webull's entry adds another regulated access point for Canadian investors and increases pressure on every platform that wants to be a primary investing destination.
The approval gives Webull permission to compete, but it doesn't guarantee adoption.
Crypto also brings higher volatility, suitability questions, security expectations, and investor education demands. A smooth user experience can't hide the risk profile of the asset class.
The advantage for Webull is that crypto can now be offered alongside the rest of its investing platform. The challenge is that investors will compare the experience not only with crypto exchanges, but with every brokerage and fintech app trying to become the main place Canadians manage investments.
Crypto trading platforms moving toward CIRO oversight shows how Canadian regulation is reshaping digital asset distribution.
Crypto custody rules are becoming a core operating issue for dealer members and digital asset platforms.
KOHO's regulated crypto rollout shows digital assets moving into broader consumer finance platforms.
Tokenization becoming a measurable business shows how digital assets are moving deeper into regulated capital markets infrastructure.
NCFA's Financial Innovation Map tracks digital assets, wealthtech, brokerage competition, capital markets infrastructure, custody, and investor access opportunities.
If every major investing platform eventually offers stocks, ETFs, options, registered accounts, and crypto, what becomes the next competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
