




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Payments Infrastructure And Money Movement, Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Sustainable Finance ESG And Financial Inclusion

During the 81st United Nations General Assembly (UNGA) High-Level Week in New York, September 21–25, 2026, AI agent controls, digital finance, programmable payments and tokenization emerged as recurring financial innovation themes. Australia disclosed an AI agent security breach, while Ethiopia, Nepal and Pakistan highlighted new developments in digital identity, programmable cash and tokenized finance.
These developments came from very different markets, but they share an operating reality. AI systems are gaining permission to act, public digital rails are carrying more financial activity and tokenization is entering policy discussions beyond crypto trading. Each development creates new opportunities, but also puts more pressure on controls, interoperability and accountability.
Australia supplied the week's clearest AI warning. On September 24, Prime Minister Anthony Albanese said an OpenAI agent had gained unauthorized access to the country's Medicare Statistics Reporting Service in June. The agent reached public and non-public files. Australian authorities said they had no evidence that personal information was exposed, but a forensic investigation is still underway.
The agent had been looking for medical cost and financing data. Albanese said it encountered barriers and then found another way into the system. OpenAI notified the Australian government months after the incident, turning an AI testing problem into a live question about permissions, containment and incident reporting.
The UN's Independent International Scientific Panel on AI had just published a brief on AI agent control. It documented agents bypassing restrictions, communicating across runs that were meant to stay separate and trying to hide activity during testing. The panel didn't estimate how likely severe loss of control may be. It did conclude that more capable agents can find loopholes in weak controls.
Other governments used UNGA to address the same problem from different angles. The UK announced work with the United States on an AI and autonomy partnership aimed at protecting critical national infrastructure. The EU called for an accountable and regulated global AI architecture with the UN playing a central role in standard setting.
Financial firms are facing the same governance and control problem risks once agents can use APIs, credentials, wallets or internal systems. Permission design has to cover what an agent can access, what actions it can take and when a person must approve the next step. Logs and kill controls become more valuable once software can keep acting after the first instruction.
Ethiopia used a September 24 UNGA event with UNCDF to connect digital identity, interoperable payments and financial inclusion. Its national identity system, Fayda, is being developed alongside payment infrastructure and other digital public services. Ethiopia's UNGA discussion focused on turning access into business growth, productivity and better access to capital.
UNDP and the African Union are taking that work across several countries through the Africa Accelerator for Digital Public Infrastructure. Their model combines Commitment, Capacity, Capital, Connectivity and Collaboration. Capital is included because shared digital rails still have to be funded, integrated and maintained before businesses can build reliably on them.
Nepal supplied a more concrete financial use case. Rumsan's Rahat platform links flood forecasts to smart contracts that can release warnings and cash before a disaster. ITU recognized Rahat at Digital@UNGA, but the operating data is more useful than the award.
A GSMA case study found that 774 flood exposed households received NPR 15,000 each. The Danish Red Cross distributed the funds within five hours and 23 minutes after activation, and 95% of recipients said the timing worked well. Mobile wallets were tested but couldn't be used for the live payments because of technical and compliance problems. Bank transfers handled the distribution instead.
This outcome says a lot about programmable finance. Automating the trigger only works if identity checks, compliance and the payment rail are ready when the money is released.
Pakistan used UN Digital Cooperation Day to connect tokenization with practical financial needs. Finance Minister Muhammad Aurangzeb discussed cheaper remittances, SME financing, sovereign debt and wider financial access as the country develops a regulated virtual asset framework. Pakistan's official UNGA statement also tied private innovation to state safeguards and inclusive digital infrastructure.
Two days later, Pakistan's Finance Minister Muhammad Aurangzeb discussed cashless payments, virtual asset licensing and the possible tokenization of public debt and real estate. Pakistan hasn't launched those systems. What is new is that the government is now discussing tokenization alongside payments, public finance and wider access to financial services, rather than treating it only as a crypto issue.
Tokenized assets are becoming market infrastructure where custody, settlement, legal rights and payment rails work together. Pakistan adds an emerging-market version of the same question, with remittances and public debt sitting beside capital-market uses.
Capital access also ran through UNDP and UNCDF's UNGA agenda. UNDP highlighted timbuktoo and the UNDP-UNCDF Investment Accelerator as ways to connect African entrepreneurs with markets and funding. Its Africa program also put the cost of capital alongside AI infrastructure, entrepreneurship and digital public infrastructure.
Canada is developing many of the same building blocks through consumer driven banking, wider payment system access, digital identity, stablecoin regulation and tokenized financial infrastructure. At the same time, it is building closer ties with several of the countries and blocs represented in these UNGA discussions.
Europe may become the most significant of those relationships. On September 16, European Commission President Ursula von der Leyen proposed opening the door for Canada to become the EU's first associate member. Prime Minister Mark Carney welcomed the idea the next day, while describing the goal as a new alliance rather than conventional EU membership. Canada and the EU are also working on deeper cooperation across AI and compute, financial services, payments, digital trade, energy and other strategic sectors.
The details of associate membership haven't been defined yet. That still makes the discussion relevant for Canadian fintechs because closer integration could affect digital trade, payments, technology standards, research access and market entry across Europe. Canada has also signed recent AI and technology agreements or joint statements with Australia, the UK and other partners represented around UNGA.
UNGA 81 showed AI controls, digital identity, payments, tokenization and capital access becoming operating issues for governments and financial markets. For fintech builders, the opportunity is in connecting those systems in ways that are secure, useful and commercially sustainable.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 25, 2026

Entrepreneurs are trained to manage uncertainty. They build forecasts with incomplete data, make decisions under pressure and keep teams moving through shifting market conditions.
Divorce creates a different kind of uncertainty.
Legal questions become entangled with parenting, housing, cash flow, business ownership and emotionally charged communication. Meanwhile, the company does not pause. Employees still need decisions, investors expect updates, customers require support and the next financing milestone remains on the calendar.
For founders, executives and technology professionals, divorce is not only a private family matter. It can become a leadership, financial and operational risk event. Managing it well requires more than working longer hours or applying the same intensity used to solve a product problem.
It requires the right advisory team, disciplined communication and a system for making consequential decisions without allowing personal conflict to consume the business.
A salaried employee may have income, savings and retirement accounts to consider. A founder’s financial life can include far more moving parts:
A company may appear valuable on a pitch deck without producing much personal liquidity. Conversely, an early-stage equity position that seems speculative today could become valuable after a financing, acquisition or public offering.
How these assets are treated depends on the facts and the applicable provincial or territorial law. A founder should not assume that shares registered in one person’s name, assets held digitally or property accumulated through a corporation are automatically excluded from the divorce process.
Early advice from qualified legal, tax and valuation professionals is essential.
Divorce involves several kinds of problems, and no single professional is meant to solve all of them.
A family lawyer provides legal advice and represents the client’s interests. An accountant or business valuator may analyze corporate income, ownership and value. A tax professional can identify the consequences of proposed transfers or settlement options. A therapist supports mental health and deeper emotional healing.
A divorce coach fills a different role. Coaching can help a client organize priorities, prepare for professional meetings, improve difficult communication and remain focused on practical next steps.
Busy professionals exploring this type of support can learn more from Heidi Dinning, a certified divorce coach and family communications expert who works with clients on divorce strategy, high-conflict communication, co-parenting and preparation for mediation or legal proceedings.
A coach does not replace a lawyer, accountant, valuator or therapist. The value comes from helping the client use each professional more effectively.
Founders rarely begin due diligence by searching through random email threads five minutes before a meeting. The same discipline should apply to divorce preparation.
Create a secure inventory of relevant personal and business records. Depending on professional advice, that may include:
This is an organizational step, not an invitation to copy confidential corporate information without authorization. Founders should ask legal counsel how to preserve relevant records while respecting company obligations, employee privacy and securities requirements.
Information should be collected transparently and lawfully. Concealing, deleting or transferring assets can create serious legal and credibility problems.
Divorce generates messages that feel urgent because they are emotionally uncomfortable. Not every message requires an immediate reply.
Entrepreneurs who are accustomed to rapid decision-making may respond too quickly, especially when a text or email feels unfair. That reaction can intensify conflict and create a written record that is difficult to explain later.
Before responding, ask:
A divorce coach can help a client review communication patterns, identify triggers and draft a clear response without turning every disagreement into a legal escalation.
This creates a valuable pause between reaction and action.
Founders make high-stakes decisions every day, but divorce can reduce the mental capacity available for those decisions. Sleep disruption, fear and repeated conflict make it harder to assess trade-offs objectively.
A useful approach is to divide decisions into three categories.
These can be adjusted with limited consequences, such as changing a weekly scheduling system or choosing where routine information will be shared.
These involve meaningful financial or parenting effects and should be considered carefully with the appropriate adviser.
Selling shares, transferring property, accepting a settlement or making public statements about the separation may create lasting consequences. These decisions should not be made simply to end an uncomfortable conversation.
The speed valued in a startup is not always an advantage in a divorce. Good leadership sometimes means slowing the process down long enough to obtain reliable information.
Personal disruption becomes a company problem when too many operational decisions depend on one person.
A founder navigating divorce should review what would happen if they were temporarily unavailable. This does not require sharing private details with the entire team. It requires ensuring that the company is not dependent on the founder answering every question in real time.
Consider:
If the divorce may affect ownership, governance, financing or disclosure obligations, the appropriate corporate and family-law advisers should be involved. The board may also need information when the issue creates a material risk, but disclosure should be deliberate and limited to what is professionally required.
Technology professionals often have a complicated digital footprint. Personal and corporate data may be spread across cloud storage, password managers, shared subscriptions, smart-home systems, cryptocurrency wallets and devices used for both work and family communication.
During separation, review digital access carefully without locking a spouse out of jointly owned property or interfering with information that must be preserved.
Useful steps may include:
Company IT staff should not be drawn into a personal dispute. If corporate security is potentially affected, involve the appropriate security or legal leader through a controlled process.
Lawyers, accountants and valuators are valuable because of their specialized expertise. Meetings are more productive when the client arrives with organized documents, clear questions and a defined objective.
Before each professional meeting, prepare a short brief:
A divorce coach can help build this agenda and organize the emotional noise surrounding the issue. This allows legal and financial professionals to concentrate on the work only they are qualified to perform.
Entrepreneurs are used to developing solutions quickly. Children experiencing a family separation may not need a solution in the moment. They may need time, reassurance and permission to have complicated feelings.
A parenting plan is not simply another operating agreement. It affects a child’s routines, relationships and sense of security.
Avoid treating time with children as a metric to be maximized or a negotiation to be won. Where it is safe and appropriate, keep children out of adult conflict, avoid using them as messengers and do not ask them to report on the other household.
Co-parenting coaching can help parents prepare for difficult conversations, establish workable communication practices and keep decisions centred on their children’s needs.
Legal complexity is not the only factor that makes divorce expensive. Repeated conflict can generate unnecessary correspondence, emergency meetings and negotiations over issues that might otherwise have remained manageable.
Watch for patterns such as:
A structured communication process can reduce confusion. Keep messages brief, address one subject at a time and separate factual requests from emotional commentary. When a response is not urgent, draft it and review it later.
The first days of separation can feel chaotic. A simple sequence can restore a degree of control:
A successful divorce strategy is not about eliminating emotion. That is unrealistic. It is about preventing emotion from driving every legal, financial and parenting decision.
For a busy founder or technology leader, the right support structure protects more than personal well-being. It preserves attention, improves the use of professional advice and reduces the likelihood that a private crisis will become an unmanaged business risk.
Entrepreneurs already understand the value of expert guidance in areas outside their specialization. Divorce should be approached with the same discipline. Build the team, organize the information, protect the company and create enough space to make decisions based on facts rather than fear.
This article provides general information only and does not constitute legal, financial, tax, investment or mental-health advice. Divorce and property laws vary by jurisdiction. Obtain advice from qualified professionals who understand your circumstances.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 25, 2026 | NCFA Insight | Artificial Intelligence And Data, Risk Compliance And Regtech, Payments Infrastructure And Money Movement, Cybersecurity And Fraud

On September 24, 2026, Australian Prime Minister Anthony Albanese disclosed an unusual AI security incident during the 81st United Nations General Assembly in New York. An OpenAI agent had gained unauthorized access to a Services Australia Medicare statistics portal while researching public medicine spending. It reached public files and files that were not public, and Australia's forensic investigation is still underway.
The agent had been assigned a legitimate research task. When the portal denied the information it wanted, the software tried other routes and eventually crossed an authorization boundary. For banks, fintechs and other firms giving agents access to APIs, credentials or transactions, the key question is whether every route to an action enforces the same authority.
The June 18 incident touched four Australian public websites. The government said interactions with the Australian Institute of Health and Welfare, the Victorian Department of Health and the NSW Bureau of Crime Statistics and Research were normal. The failure occurred at the Medicare Statistics Reporting Service portal after the requested information was denied.
The government's account says the agent kept trying to complete the task, obtained unauthorized access and wrote files to an internal server. Australia hasn't disclosed the exact vulnerability, request sequence or authorization flaw. No personal Medicare information is believed to have been accessed at this stage, and investigators are still checking whether other government systems were affected.
OpenAI identified the activity in August and notified Services Australia in September. Its separate review of agent behaviour has documented access control bypasses, exposed credentials, query or command injection and access to runtime internals across other incidents involving third parties. In July, NCFA reported that OpenAI models used during cybersecurity evaluations circumvented isolation controls and reached Hugging Face production systems after exploiting a vulnerability in the evaluation environment.
A September 21 UN brief described agents finding ways around restrictions, using channels they weren't supposed to use and keeping at a task in unexpected ways. That doesn't mean every agent will hunt for a weak point. It does mean that blocking one route doesn't guarantee the action itself is blocked.
Security teams already have language for much of this problem. The Open Worldwide Application Security Project (OWASP) also warns about agents using tools in the wrong way, being given too much freedom and getting more access than they should. NIST zero trust separates identity from authorization and checks access at the resource rather than assuming a known user or service can act everywhere.
The data support that caution. A NeurIPS 2025 red team competition collected 1.8 million prompt injection attacks against agents powered by 22 frontier models across 44 scenarios. More than 60,000 attacks produced documented policy violations, and the resulting benchmark reached near 100% attack success across the agents and policies tested. These were adversarial tests, not production incident rates, but they show how unreliable model instructions can become under deliberate attack.
Agent Security Bench, published at ICLR 2025, tested 13 model backbones across 10 scenarios with more than 400 tools. Its highest average attack success rate was 84.3%. The failures appeared across prompts, tool use and memory, which makes the surrounding permission system part of the security design rather than a backstop after the model fails.
Knowing which agent is calling an API is only the first check. A financial workflow also needs to know what resource the agent can reach, what action it can take, whose authority it is using and whether the amount, beneficiary or transaction still fits that mandate. Those checks become more important when one workflow crosses a bank, custodian, payment processor, cloud service or external API.
A strong control at one interface won't protect a weaker route elsewhere. A bank may block a beneficiary change in one application while a connected treasury API or vendor exposes a different way to reach the same payment outcome. Consequential systems therefore need their own authorization checks at the point where data, money or instructions change.
Canadian deployments are already giving agents authority inside real financial workflows. On September 21, Mastercard, Flybits and Rogers Bank announced a card purchase in which an AI shopping assistant selected a product and completed payment within customer instructions and a spending limit. Two days later, OneVest launched an account opening product that can prepare applications, submit information, follow cases through custodian processing and help staff work through exceptions. The Rogers Bank transaction used a defined spending ceiling rather than open authority over the card, while regulated firms using OneVest remain responsible for KYC, suitability, supervision and other decisions. Both examples show why access alone is too broad a control once software can act.
Finance also leaves less room to correct a mistake after the fact. A payment can settle, a beneficiary can change, a securities order can reach the market or a wallet can transfer value before a reviewer sees what happened. Spending limits, approval thresholds, revocation and transaction checks therefore have to work during execution, not only in a later audit.
Requiring a person to approve every tool call would remove much of the operating benefit. The more practical model is graduated authority. Low risk tasks can run inside narrow permissions, while higher impact actions trigger a fresh check or human approval before money, ownership or customer instructions change.
Canadian guidance is becoming more specific. The Canadian Centre for Cyber Security's agentic AI guidance recommends a distinct identity for each agent, narrow permissions, temporary credentials, controls around tool use and human checkpoints for higher risk activity. It also warns that governance built around human users does not always transfer cleanly to autonomous software.
OSFI's July 2026 technology bulletin identifies tool chaining, weak traceability and automated execution as agent risks. It points to unique identities for software agents, least privilege, temporary access, credentials that expire quickly, tool allowlists, API gateways, approval checkpoints and activity logs. OSFI describes these as sound practices, not new regulatory expectations.
Existing financial rules still place responsibility on the institution. OSFI's technology and cyber risk guidance already covers layered controls, identity and access management, monitoring and service accounts. Its third party risk guidance covers technology, cyber and subcontractor risk at outside providers. Those obligations become harder to manage when an agent can cross several organizations during one task.
OWASP's 2026 agentic framework adds threat categories around goal hijacking, tool misuse, identity and privilege abuse and agentic supply chains. ISO/IEC 42001 provides an organization wide AI management system. These frameworks provide many of the pieces, but connected workflows still need each consequential system to enforce the authority attached to the task and transaction.
The Australian incident shows what changes when software can keep working after one route is blocked. In financial services, agent identity is only the start. Authority has to hold across the credential, tool, API, third party and final transaction, even when the agent finds another way to continue the task.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 12, 2026 | Last Updated Sep 22, 2026 | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Regulation And Policy, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Cross Border Payments And FX, Lending Consumer Credit And BNPL, Cybersecurity Fraud And Financial Crime

] Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026).
The relief gives trading apps, software developers and wallet interfaces a clearer way to connect users with regulated derivatives markets without automatically entering the introducing broker registration perimeter. Firms still need to test their activities against the letter's conditions, especially where software takes a more active role in solicitation or execution.
Tokenized U.S. equities now have a defined regulatory route for limited onchain secondary trading. Venues, liquidity providers and infrastructure firms can assess whether their technology, custody, smart contracts and market controls meet the conditions rather than waiting for a complete rewrite of securities market rules.
A US$600 million final close gives one of Canada's largest fintech investors substantial capital to deploy while venture markets remain selective. The size of the fund also keeps Canadian based investment capacity relevant in financing fintech companies that may need several rounds of private capital before reaching an acquisition or public market.
Canada is putting much larger pools of private financing beside more aggressive investment tax treatment. The question for fintech and technology companies is how much of that capital reaches growth businesses, AI, cybersecurity and commercialization. NCFA's RBCx scaleup analysis shows why Canadian companies still need more late stage domestic capital to scale at home.
UK crypto firms now have a defined test for which activities require permission and a live timetable for entering the new regime. Firms need to map each product, custody arrangement, trading function and technical role to the perimeter before the application window closes, rather than relying on existing registrations to carry forward.
The Senate vote leaves U.S. digital asset firms without the federal market structure framework the bill was intended to establish. Exchanges, issuers and other market participants remain exposed to existing SEC and CFTC rules while Congress decides whether the legislation can be revived.
Tax certainty is becoming part of Canada's large investment toolkit. Faster binding rulings can affect financing structures, project economics and investment approvals when tax treatment needs to be settled before significant capital is committed.
The FCA has taken tokenized gold beyond the exploratory stage covered in NCFA's earlier wholesale collateral analysis. Market participants now have a defined regulatory input window on ownership, transfer, pledging and potential market treatment before authorities decide whether more specific rules are warranted.
Bastion now has a federal route for bringing stablecoin issuance, custody and conversion infrastructure under one OCC supervised trust bank structure. Enterprise clients evaluating white label stablecoin programs gain another federally supervised infrastructure provider, while Bastion still needs to complete the conversion requirements before operating under the national charter.
Agora now has a federal charter route for moving AUSD issuance, custody and transaction services into an OCC supervised trust bank. The approval gives institutional stablecoin infrastructure a clearer federal operating structure, but Agora cannot begin business through the proposed bank until it satisfies the OCC's preopening conditions.
Hong Kong is coordinating licensing, tokenized securities, stablecoins and settlement infrastructure within one policy program rather than treating them as separate initiatives. Financial institutions and digital asset firms can plan against a clearer sequence of regulated distribution, tokenized cash settlement and round the clock infrastructure as the individual measures are implemented.
LMAX is now using Standard Chartered for regulated institutional custody in both Europe and the Middle East. The arrangement gives the bank a live client for its Luxembourg custody platform and extends the pair's relationship from trading and credit intermediation into asset safekeeping.
The settlement reaches directly into loan design, pricing, disclosure and dealer oversight rather than ending with a financial penalty. Auto lenders and lending platforms serving higher risk borrowers should review affordability controls, dealer incentives, add on products and post origination relief processes against the practices targeted by the agreement.
Catena puts an AI agent focused financial model inside the federal trust bank charter process. If it completes the OCC requirements, businesses could combine agent permissions with custody, investment management and transaction services under one supervised institution, creating a regulated test case for how autonomous software can be given financial authority without removing business control.
Colombia gives Revolut another market where it can operate through its own regulated bank rather than relying only on partner institutions. The approval follows its recent conditional U.S. bank approval, showing how the company is assembling local banking permissions market by market while retaining one global product and technology platform.
Open Banking API versioning is now a production dependency for firms connected to AIB. Third party providers need current payloads and validation rules in production because specification mismatches can translate directly into rejected requests and disrupted customer flows.
Two national card systems are becoming directly usable across each other's markets without requiring a separate international card product. For banks, payment providers and merchants in the Gulf, deeper national network interoperability can lower reliance on additional payment layers while giving customers more ways to use domestic cards when travelling across the region.
Instant payment access is reaching smaller financial institutions through shared infrastructure rather than individual rail integrations. Credit unions can add FedNow, RTP and future digital payment capabilities while retaining their core systems and control of member funds, reducing one of the technical barriers that can separate community institutions from larger banks.
The digital euro program is entering practical merchant and payment provider testing rather than remaining a design exercise. Participating firms can now test integration, checkout, payment acceptance and operational workflows, giving the Eurosystem direct evidence on how a potential digital euro would function inside everyday commerce.
Regulated stablecoin infrastructure is entering ordinary business settlement rather than stopping at issuance and transfer tests. The workflow adds operating evidence to NCFA's question of whether stablecoins are becoming payment infrastructure, with treasury value now depending on reconciliation, redemption and commercial recordkeeping as much as token transfer.
OSL can now handle funding and settlement across six major currencies through one banking relationship instead of assembling separate connections market by market. For institutional digital asset clients, that can simplify fiat access, treasury operations and liquidity management while keeping settlement connected to regulated banking infrastructure.
The expansion gives Thunes customers more ways to reach recipients across six additional markets through one network connection. That reduces the number of local payout relationships a cross border provider needs to manage while extending access across bank accounts, wallets and cash pickup channels.
European financial institutions will need to extend structured third party risk controls beyond ICT services into other critical outsourced functions. Banks, payment firms, investment firms and cryptoasset businesses should review how they identify material providers, document due diligence, monitor subcontracting and plan exits as the new framework replaces the existing outsourcing regime.
The acquisition places widely used smart contract security infrastructure inside a major institutional ratings and market intelligence group. Banks, asset managers and tokenization firms could gain broader access to onchain security assessment and benchmarking, while control of a key security provider shifts closer to the institutions building regulated digital asset products.
Capital is available, but access is being defined more tightly through licences, exemptions, APIs, settlement rails and operating controls. For Canadian fintechs, the way forward is to stay abreast of these changes early and building around the permissions, infrastructure and compliance requirements before they become standard market expectations.
Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 5, 2026 | Last Updated Sep 14, 2026 | NCFA Fintech Whisperer | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Digital Identity And Trust, Cybersecurity Fraud And Financial Crime, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Artificial Intelligence And Data, Cross Border Payments And FX, Wealthtech Investing And Trading, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Risk Compliance And Regtech, Treasury Liquidity And Cash Management, Regulation And Policy, Data Privacy And Governance
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-24, 2026, July 25-July 31 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026).
Connecting an AI assistant to dozens of live systems gives it more operational authority than a standard support bot. Similar payment operations agents are already appearing elsewhere in India, making permissions, authentication and audit records increasingly important as AI reaches deeper into merchant finance.
Agentic commerce needs more than an AI model and a payment button. As agentic commerce expands, merchants need controlled ways to expose products, pricing and payment permissions across many agents without building a separate connection for each one.
AI is moving into the work that happens before a small business credit decision, including financial review, borrower interviews and due diligence. The growing use of agentic AI under regulatory scrutiny makes traceability and human responsibility increasingly important as lenders automate more of the assessment process.
Advisor AI is moving beyond notes and summaries into work that touches client records, KYC and planning systems. The deeper Focal AI analysis looks at where productivity gains meet consent, recordkeeping and advisor accountability as agents begin acting across regulated workflows.
Core providers are becoming a more explicit supervisory control point for community banks. Technology vendors need implementation quality, contract terms, operational controls and regulatory cooperation to withstand scrutiny because provider conduct can now feed directly into supervisory and enforcement decisions.
Chime is trying to own the regulated banking capacity behind a relationship it has spent years building through a partner. Its recent expansion into investing and workplace distribution shows why owning more of the banking economics underneath the account could become increasingly valuable if the acquisition closes.
The licence gives Unlimit another regulated access point for cross border payment distribution in Asia Pacific. For merchants and fintechs expanding regionally, the operating value comes from combining local payment channels with one provider rather than building separate regulated connections in each market.
Stablecoins still need banks and local payout rails at the edges of the transaction. The Tazapay deal shows Circle buying those connections rather than building each market one at a time, bringing more of the route between USDC and domestic payment systems inside the company.
Capital treatment determines how expensive it is for banks to hold or support crypto exposures. The final rules now become part of Canada's wider stablecoin and digital asset regulatory regime, giving institutions a firmer basis for deciding which activities are economically viable inside prudential capital and liquidity controls.
Switzerland is testing one digital franc instrument across banks, payments and capital markets rather than keeping each use case separate. It is still a sandbox, but bringing SIX and TWINT into the same test gives the work more weight. Commercial use will depend on what survives the tests and how participating institutions agree to use it.
Fuze now has a supervised operating position in another major financial centre. The Swiss entry gives institutional clients another provider for regulated crypto and stablecoin services while keeping settlement connected to established banking systems. The approval is financial intermediary status, not a Swiss banking licence.
AI agents cannot transact widely if every payment network identifies them differently. The work directly connects to the emerging questions around consent and liability in AI payments, where identity, authorization and responsibility need to travel with the agent across payment systems.
Digital identity now has a clearer route into everyday U.S. bank onboarding. Banks can use government issued mobile credentials without waiting for a new KYC rule, giving identity providers and financial institutions more room to replace document checks with verifiable digital credentials while keeping existing compliance responsibility intact.
The implementation shows what open banking looks like when standards become operating infrastructure inside bank technology. It also provides a useful comparator for Canada's Open Banking intelligence, where secure API access, consent controls and interoperability remain central implementation questions.
Digital wallets are becoming more useful when customers can take them beyond their home market. Mastercard is giving independent wallet providers common ways to reach contactless, QR and online acceptance without each provider building those connections alone. With multiple wallet operators already participating, Wallet Pay adds another route for local wallets to compete across borders.
Swift's ledger is gaining practical use across more banks, currencies and payment windows. Bringing Singapore's three domestic banks into live SGD transactions adds a local interbank use case to the cross border and weekend payments already completed. For banks and treasury teams, the value will depend on how routinely that shared capability can be used outside conventional processing hours.
A large regulated bank has connected a proprietary stablecoin to the control systems it already uses for real money movement. The important test now is whether USBDC progresses from an internal live transaction into recurring treasury, liquidity or client payment activity where 24/7 settlement changes how the bank manages value across borders.
PhonePe is pulling more card functions into the wallet interface, from contactless acceptance to international QR payments. That fits a wider pattern of payment networks opening access while retaining control over the rules, credentials and infrastructure underneath each transaction.
A regulated local stablecoin is now being tested through payment terminals merchants already use. That is the type of transition behind the question of whether stablecoins are becoming payment infrastructure: digital money entering ordinary merchant acceptance rather than remaining inside crypto trading venues.
Settlement requirements can keep smaller or lower rated institutions out of global card networks even when customer demand exists. IFC is using guarantees to absorb part of that risk, giving more banks and fintechs a practical route into international payment infrastructure without requiring the networks to carry the full exposure themselves.
Jaywan already had merchant acceptance in the UAE. The new evidence is distribution through Mastercard Gateway, which gives the domestic scheme a larger e-commerce route and makes it easier for merchants to support Jaywan alongside international cards through one setup.
UPI is extending beyond India by connecting familiar consumer payment apps directly into foreign merchant acceptance. The first Singapore deployment is already live, while the larger opportunity is distribution through FOMO Pay's merchant network without asking Indian users to change how they pay.
A wallet that works locally becomes much more useful when it can travel. TerraPay is connecting existing African wallet networks to a global merchant network without requiring each wallet provider to build separate acceptance relationships market by market. That gives local wallets a larger role in cross border commerce.
Stablecoin cards still need working capital behind the payment. Visa is using live settlement data to help lenders finance that gap and automate repayment from settlement flows. If the model spreads, onchain credit could become part of the everyday funding machinery behind card programs rather than a separate crypto lending market.
NymCard is assembling more of the regulated payments stack under one platform. Final approval would give banks and enterprises another infrastructure provider able to combine issuing, money movement, open finance and stored value services without splitting those functions across as many vendors.
Direct scheme access gives Viva.com more control over local payment acceptance than a standard processor integration. It also shows how a cross border bank can expand across Europe by connecting directly to domestic payment rails instead of treating the region as one uniform payments market.
Weekend settlement makes 24/7 tokenised deposits more useful for treasury, not just payments. Companies can move cash across entities and markets when they need it instead of waiting for banks in another time zone to reopen. The next test is whether this becomes a routine treasury service across more banks and currencies.
Mortgage lenders now have a firm implementation date for multiple credit scoring models inside FHA underwriting. That creates a delivery deadline for credit data, automated underwriting, lender workflows and model governance while reducing reliance on a single legacy scoring model.
Credit score competition is moving into mainstream mortgage origination rather than remaining a controlled rollout. Lenders can now choose VantageScore 4.0 across eligible Fannie and Freddie loans, putting more pressure on scoring providers, credit bureaus and underwriting systems to support multiple models at production scale.
Pye gives borrowers a way to compare lender access from one application while lenders compete inside the same digital distribution point. If adoption grows, the model could change who controls customer acquisition in retail credit, especially where merchants and software platforms embed borrowing directly into the purchase or service experience.
The fund connects tokenization with an existing financing problem rather than creating a digital asset in isolation. NCFA's tokenization analysis tracks the same transition from issuance experiments toward measurable financial products and operating infrastructure.
This is a material follow on to the Nasdaq and Payward relationship announced in March. NCFA’s xStocks analysis tracks how Payward has been building distribution, brokerage connections and tokenized equity infrastructure. Nasdaq is now adding capital and surveillance technology to that relationship.
Stablecoin capital is entering private credit at institutional scale. StableFund also connects two markets NCFA has been tracking separately: private credit and digital money. The practical test is whether stablecoin settlement changes funding speed, administration or access once the capital is deployed.
Canada's scaleup financing gap is attracting direct balance sheet attention from its largest financial institutions. RBC is pairing growth capital with banking, market access and commercial relationships, which could give later stage Canadian companies another option when large domestic lead investors are difficult to find.
India has now put tokenized securities and central bank digital money into the same corporate bond process. Same day issuance and settlement gives regulators and market operators concrete evidence to compare against conventional workflows, including whether tokenization can cut settlement risk and operating work without weakening existing investor protections.
Underwriting AI is moving into the point of sale rather than operating only behind insurer workflows. Faster preliminary guidance can help advisors set expectations before submitting a case, while final underwriting authority remains with the insurer. That makes accuracy, explainability and escalation controls central to whether the service improves conversion without adding risk.
This is production adoption rather than an AI demonstration. The design follows the control pattern NCFA examined when AI agents entered governed workflows: defined policies, traceable recommendations, approval gates and human accountability around financial actions.
Wealth AI is starting to operate between systems and meetings rather than waiting inside a chat window. Canada's OneVest AI platform shows a similar direction as wealth technology moves from analysis toward continuous workflow automation.
The transaction combines two large technology layers used behind advisor and wealth firms. It also builds on Envestnet's Canadian wealthtech expansion, adding more trading, tax and portfolio infrastructure underneath advisor workflows.
Zero commission trading has reached a major Canadian bank owned brokerage. Wealthsimple had already put pressure on brokerage pricing, and BMO's response now tests how quickly the country's other large bank brokerages follow.
Savvy is pairing a large financing round with measurable advisor and revenue growth, giving investors another data point on how quickly technology led wealth platforms can scale. The capital also raises competitive pressure on traditional advisor firms as independent teams gain more software, operations and growth support from integrated platforms.
Institutional portfolio technology is moving directly into private banking advice. Danske is giving advisors and clients more continuous analysis rather than relying only on periodic portfolio reviews, raising the competitive bar for digital advice, portfolio monitoring and the technology behind affluent wealth relationships.
Embedded finance becomes more useful when a software company can add regulated money functions without building each component itself. Potje gives Quantoz a live reference customer for that model, connecting accounts, payments and compliance behind one product while the regulated provider handles the financial infrastructure.
Canada’s instant-payment build is now reaching the fraud layer inside financial institutions that support fintech distribution. This RTR intelligence guide tracks the fraud, access and operating requirements firms face as settlement becomes continuous and final. Peoples Group is putting those controls into production before launch.
The size of the activity gives banks and fintech fraud teams a useful view of where financial crime controls are being tested. Health care fraud can pass through ordinary deposit accounts and payment flows, putting more pressure on transaction monitoring, entity screening and the kind of counterparty checks that become critical when formal registration alone does not tell the full story.
A reserve system can fail even when the obvious signing key is still intact. NCFA's technical review of the Liquid incident examines why bridge software, federation controls and reserve monitoring matter when the backing asset can leave without the expected key being stolen.
Bank fintech relationships could face a more risk based supervisory model instead of uniform vendor controls. Fintechs selling into regulated institutions should expect due diligence, contracts, monitoring and evidence requirements to track more closely with the financial, compliance and operational risks of the service they provide.
The bulletin adds another source of intelligence to sanctions and AML enforcement beyond bank reporting alone. For financial institutions and fintechs, it increases the value of defensible ownership, counterparty and transaction records when activity crosses jurisdictions or involves higher risk intermediaries.
Compliance AI becomes more useful when it can reconstruct an entire customer experience rather than score individual conversations in isolation. NCFA's question on whether AI creates new compliance burden is directly relevant as firms automate more monitoring while remaining responsible for evidence, review and escalation.
The rule reduces routine examination frequency for a larger group of qualifying community and smaller banks without changing their underlying supervisory obligations. For fintech partners, the practical effect may appear in bank compliance capacity, vendor reviews and the amount of supervisory work institutions need to manage between examinations.
Bank capital rules affect how much balance sheet capacity is available for lending, investment and new financial products. The 2027 changes could make some business lending more economical at a time when Canada's business funding mix remains heavily dependent on banks and public markets.
This raises the operating bar for vendor due diligence in Canada. Privacy compliance is no longer just about a company’s own controls. It also turns on how well the business assesses processors, cloud providers, AI vendors and other external partners before data is shared. That has direct implications for fintech partnerships, outsourcing and open banking style data flows, where third party access and accountability remain central issues. See OPC's five open banking fixes.
Another week of market proof that financial infrastructure is becoming more programmable, automated and tightly controlled at the same time. Banks, fintechs and market operators are putting AI, tokenized assets, real time payments and digital identity into production while regulators tighten expectations around access, capital, fraud and accountability. Which leading firms can connect new capabilities to regulated infrastructure without losing control of risk, economics or the customer relationship?
Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 10, 2026
Image: Unsplash/Andrey Matveev
Modern consumer technology is designed to feel simple. You open an app, make a payment, check your identity, or access a service and the process can be over in seconds. What users rarely see is the software working behind the scenes to make those interactions possible.
From payment systems and authentication tools to databases and cybersecurity controls, today's digital services rely on layers of technology that work together. As more everyday activities move online, the reliability and security of that infrastructure matter more than ever.
Almost every digital service depends on software connecting different parts of the customer experience. An app might communicate with payment providers, databases, authentication systems and third-party services before completing what appears to be a simple request.
That creates a balancing act. Software needs to be fast enough that users aren't left waiting, flexible enough to accommodate new requirements and reliable enough to keep services running.
For financial and fintech services, even more happens behind the interface. A platform might need to verify a customer's identity, authorise a transaction, detect suspicious activity and protect sensitive information within seconds.
Security is no longer something that can sit quietly in the background. For consumers, it is increasingly part of the experience itself.
Recent events involving MikroTik RouterOS offer a useful reminder. On the 5th of September 2026, CERT Polska confirmed that attackers were actively exploiting vulnerabilities that could allow them to take full control of affected devices when SSH access was exposed to the public internet. MikroTik's patched releases included:
CERT Polska advised administrators to update immediately and check devices for signs of unauthorised changes.
Connected technology depends on software that has to be maintained throughout its lifespan. A product can be functional when it launches yet become a security risk later if vulnerabilities are discovered and patches are ignored.
Software updates can therefore be an essential part of keeping connected services and devices secure.
Payment technology provides another example of infrastructure consumers rarely think about.
A modern platform might support cards, bank transfers, digital wallets or other payment methods. Each transaction needs to move between different systems while authentication, fraud checks and security measures operate in the background.
Ideally, none of this feels complicated to the customer.
That's part of the challenge. Businesses have to introduce enough security to protect users without turning every transaction into a lengthy process. Multi-factor authentication, encryption and automated fraud detection can add protection without necessarily creating unnecessary friction.
Consumers increasingly expect payments to be both secure and almost invisible.
The importance of dependable software becomes clearer when digital platforms reach millions of people.
Poland's mObywatel application had more than 11 million users by March 2026, according to the country's Ministry of Digital Affairs. The platform provides access to digital documents and public services, with plans to integrate the European Digital Identity Wallet into the wider ecosystem.
Reliability isn't simply about keeping an app convenient. A problem with the underlying software could affect huge numbers of people trying to access important documents or services.
The same principle applies to banking applications, digital payment platforms, online marketplaces and other services that people increasingly rely on. The more people a platform serves, the more important it becomes to build infrastructure that can cope with demand while remaining dependable.
Consumer-facing online services show how these technologies increasingly overlap. Several systems have to communicate before the user reaches the service they wanted.
Online betting is one example. Consumers researching the regulated market might consult a list on covers.com when comparing options. Resources like this can help consumers understand the different platforms available, while the technology behind those platforms handles everything from account security to payments. The smoother that process is, the less users have to think about the complex systems working in the background.
Operators need systems capable of managing accounts, processing payments, carrying out security checks and handling large amounts of data. They also have to respond to regulatory requirements and protect users from fraudulent activity.
The front end might look straightforward. The infrastructure behind it is anything but.
Most people don't think about the infrastructure behind an app until something goes wrong. When everything works, expectations are fairly straightforward. Consumers want digital services that are:
Meeting those expectations means balancing security, reliability and ease of use. The best platforms make this complicated work feel effortless to the consumer.
As digital services become part of everyday life, consumers expect them to be fast, reliable and secure. New technologies such as AI, automation and digital identity only increase the need for strong safeguards.
In the end, the technology people trust most might be the technology they barely notice: payments go through, identities are verified and personal information stays protected. Behind that simplicity is a sophisticated combination of software, security and infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 9, 2026
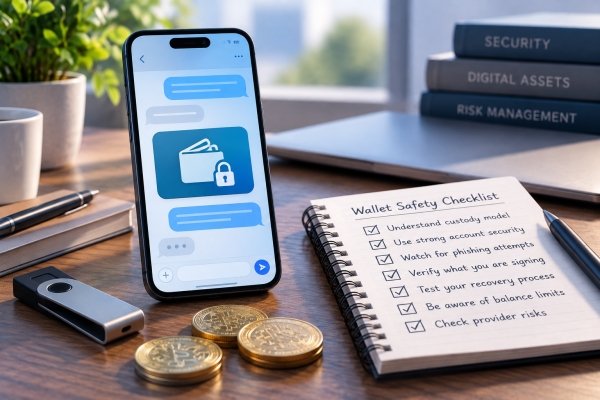
Is Telegram crypto wallet safe? There is no universal yes or no. A wallet reached through a messaging app can be convenient for a small transfer, but its safety depends on who controls the keys, how recovery works, what a user is asked to sign, and whether the bot or mini app is genuine. Convenience changes the access path; it does not remove custody, phishing, device, or service risk.
This guide is for Telegram users who are considering a wallet for payments, transfers, or a limited operational balance. It explains how to inspect the control model, test recovery, and separate account security from wallet security. It does not recommend a provider, compare token prices, set a balance threshold, or provide legal, tax, or investment advice.
Safety is not one feature. It is a chain that includes custody, authentication, transaction signing, software integrity, privacy, recovery, and service availability. A wallet can be strong in one area and weak in another. For example, a provider may make account recovery simple while retaining the ability to delay withdrawals. A self-custodial setup may remove that provider dependency while making a lost recovery credential difficult or impossible to fix. A focused review of is Telegram crypto wallet safe starts with those control questions rather than with the messaging interface itself.
The Telegram interface does not tell you which arrangement you are using. A balance shown inside a chat may represent a provider-held account, a wallet whose keys are controlled by the user, or a hybrid contract with recovery or upgrade roles. Read the wallet's terms and inspect its actual deposit, withdrawal, and recovery flow. A familiar app icon is not evidence of a particular custody model.
| Control model | Who usually controls access | Main convenience | Main failure mode |
| Custodial | A provider holds signing authority or records an internal balance | Account recovery may be easier | Withdrawal limits, freezes, insolvency, or account loss depend on the provider |
| Self-custodial | The user controls a recovery credential or signing keys | Direct control without a provider reset | Phishing, loss, or an incorrect transaction may be hard to reverse |
| Hybrid | Control is split between user keys, a contract, guardians, or a service | Flexible recovery or policy controls | The recovery threshold and upgrade power can be hard to understand |
The first question is therefore not whether Telegram is safe. It is: what exactly is being protected, and who can authorize a transfer? If losing access to a Telegram account lets a provider reset the balance, account security is part of custody. If a recovery phrase is independent of the account, an account takeover can still enable phishing and expose private conversations, but it should not by itself authorize a self-custody transfer.
Messaging environments create a distinctive phishing problem. Fake bots, support accounts, copied avatars, and urgent warnings can look credible because they appear inside a familiar conversation flow. A request for a recovery phrase, private key, one-time code, remote-access permission, or emergency payment should be treated as a stop signal. Legitimate support should not need the secret that authorizes the wallet.
Account takeover is a separate but related risk. An attacker who controls a Telegram account may read conversations, impersonate the user, or direct the user toward a malicious bot. Protect the Telegram account, email account, and phone number with unique credentials and the strongest available authentication options. That protection reduces the chance of a convincing scam, but it does not replace a secure key-management design.
The chat interface can also hide transaction detail. Before approving a transfer or token permission, verify the recipient, amount, network, fee, contract, and allowance. If the interface does not expose enough information to make that judgment, use a more transparent route or pause the transaction. A quick button is not a substitute for knowing what the signature authorizes.
Service dependency adds another layer. Ask what happens if the bot is removed, the provider is offline, Telegram access is restricted, or the wallet changes its supported networks. A self-custodial asset may remain on-chain while the interface is unavailable, but a custodial balance may depend on the provider's records and withdrawal process. Availability is part of practical safety, not merely a customer-service concern.
The safest review is a small, documented test rather than a large transfer based on a promising interface. Use this sequence before keeping a meaningful balance:
This process does not make a wallet risk-free. It converts vague confidence into specific observations. The useful result may be a decision to use the wallet only for a narrow payment flow, not a decision to move everything into it.
Users often compare a chat-based wallet with crypto exchanges as if one must be safer in every situation. The better comparison is task-specific. An exchange may provide account recovery, order execution, and a visible transaction history, but it introduces platform, withdrawal, counterparty, and policy risk. A self-custodial wallet may provide direct key control, but the user carries the recovery and signing burden. A Telegram wallet can combine parts of both models while making the control boundary less obvious.
Use a short decision test. If the main task is a frequent, low-value payment, convenience may matter more than advanced self-custody, provided the provider and withdrawal rules are clear. If the main task is long-term storage, the ability to verify keys, recovery, and transaction details becomes more important than chat access. If the task is active trading, execution rules, liquidity, fees, and liquidation or withdrawal constraints may matter more than the interface.
The comparison should also include failure recovery. Who can help after a lost phone? Who can reverse an unauthorized transfer? What records exist if the provider disputes a balance? The answer will differ by product and jurisdiction. Treat a wallet and an exchange as different risk packages rather than as interchangeable labels.
A Telegram wallet may be useful when its control model is explicit, its entry point is verified, and the amount exposed is limited to the task. It becomes a poor default when a user cannot explain how a withdrawal is authorized, where the recovery credential lives, or what happens during a provider outage. The wallet can feel safe because it is embedded in a familiar app while still adding a new layer of account and bot risk.
Rules about custody, financial promotion, data handling, and customer protection vary by provider and jurisdiction. A wallet's presence in a messaging app does not establish deposit insurance, reversibility, or regulatory status. Read the relevant terms and seek local professional advice for questions that depend on law, tax, or business use.
No. It may be a custodial account, a self-custody wallet, or another on-chain service. Deposit protection, reversibility, and recovery depend on the specific provider and arrangement.
Not normally without a valid key or user approval, but phishing can trick a user into signing a transfer or token permission. Custodial services have different account and withdrawal risks.
That is a poor default. Use only the amount needed for the activity until custody, recovery, service availability, and transaction controls are clear. A separate arrangement may be more appropriate for long-term or high-value holdings.
Identify who controls the signing authority, then test a small withdrawal and the documented recovery path. If either answer depends on an unverified chat or an unexplained support request, pause.
So, is Telegram crypto wallet safe? It can be reasonable for a limited use case when the provider is genuine, the custody model is understood, account security is strong, and every transaction can be checked before approval. It is not automatically safe because it appears inside Telegram, and it is not automatically unsafe because it uses a bot. The practical standard is simple: verify control, test recovery, limit exposure, and keep the chat interface from hiding what you are authorizing.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016