




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Fintech Financing | May 22, 2025
Image: Keep Announces 108M funding
On May 20, 2025, Toronto-based fintech Keep revealed that it raised C$108 million in new funding to reinvent small business finance in Canada. The funding round includes C$33 million in equity financing led by Tribe Capital, plus C$71 million credit facility from Treville Capital, and C$4 million in venture debt from Silicon Valley Bank.
Founded by Oliver Takach and Helson Taveras, Keep is specifically designed for Canadian small and medium sized businesses (SMEs or SMBs) and provides an integrated financial suite of tools, such as automated expense management, a rewards-based business credit card, multi-currency accounts, and flexible global bill payments.
Oliver Takach, CEO Keep said in a CEO letter:
Keep was born from that frustration. I went into the branch. Twice. I signed personal guarantees. I paid fees no one could explain. And in the end, they still wouldn’t give me a business credit card.”
Canada’s small business sector is the backbone of the economy, contributing more than 40% of GDP and accounts for over 98 percent of all employer businesses. Keep estimates that the small business banking market in Canada is worth $500B, which is dominated by legacy institutions who continue to rely on paper-based underwriting, limited tools and integrations, and haven't adapted products to align with modern workflows or regulatory requirements.
Yet, many entrepreneurs remain locked out of fast, reliable credit and banking tools, which is what Keep's platform is designed to solve. Since launching in 2022, Keep has on-boarded over 3,000 SMBs across a range of industries, and has surpassed C$20 million in annualized revenue. The company also reports a 300% net dollar retention rate, reflecting strong adoption and satisfaction.
Glen Napier, CEO of James G Armour & Co.:
"With Keep, we've cut our financial admin time by 80%. The integration of their products was seamless and helped us double our revenue in just six months. What used to take weeks with traditional banks now happens instantly."
Keep operates in a competitive domestic market that includes startups like Float, Loop, and Venn, aiming to differentiate itself by providing an all-in-one model that integrates core financial tools rather than offering individual product solutions.
Investor confidence seems to agree with the strategy. The latest found has attracted both returning and new backers including Rebel Fund, Liquid2 Ventures, Cambrian, and Assurant Ventures, as well as individual investors from Stripe, Coinbase, Robinhood, Plaid, and Chime.
Takach said, "By 2027, we aim to serve 100,000 small businesses across Canada and help them save over a quarter billion dollars in fees annually.”
Backed by global investors, the Canadian fintech industry keeps getting stronger. Keep's emergence from stealth to grow founder-led financial infrastructure to support how entrepreneurs actually operate will help close gaps left by traditional banks. Domestic competition is heating up.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Open Finance Policy Development | May 22, 2025
Image: Freepik/rawpixel.com
On May 15, 2025, the Cambridge Centre for Alternative Finance (CCAF) hosted a webinar, “Open Finance in Practice: Implementation, Liability & Monetisation” with experts from Thailand, Rwanda, India, the UK, and Asia-Pacific who shared what's working and what's not, based on their practical experience. Open finance is progressing globally but real world experience shows that it is not just about technology or APIs, and successful implementation depends on clear rules, trusted governance, and strong infrastructure. These insights are especially relevant now as Canada prepares to implement its own open banking system in 2026.
Sanjay Janeja, Open Banking Lead, CCAF:
“Our data shows that regulation-led models support faster implementation and broader data sharing.”
CCAF’s Global Regulatory Innovation Dashboard (GRID) shows that countries with clear regulatory mandates, like Brazil and Australia, have progressed faster than those relying on voluntary participation. India in contrast, moved slowly at first without regulatory mandates. Canada risks similar delays unless its upcoming rules are clear, enforceable, and consistent.
Denise Dias, Regulatory and Supervisory Consultant:
“Governance is the soul of open finance.”
Governance critically defines who sets the rules, allows the accreditation of participants, and resolves disputes. Rwanda is building shared oversight between its financial and telecom regulators. Countries that define this early see smoother adoption. Canada's future governance structure needs to include clear roles for regulators, industry, and consumer protection agencies.
Rafael Mazer, Director, Fair Finance Consulting:
“Consumers should not have to wait for firms to assign blame before they are made whole.”
As more parties exchange financial data, legal clarity is paramount. The UK mandates reimbursement even before liability is settled. Oman and UAE require indemnity insurance for open finance participants. Canada needs to define who is liable, under what conditions, and how disputes will be resolved before open banking go live.
Rafael Mazer:
“This is where the claws come out.”
Camilla Bullock, CEO, Emerging Payments Association Asia:
“You cannot grow the pie if the small players cannot afford a slice.”
Thailand uses free access for consumers and capped pricing for commercial use. Brazil allows a set number of free requests per user. These models keep access open for small fintechs. Canada should consider following suit to avoid anti-competitive pricing that could exclude new entrants.
Pamela Umutesi, Lead for Open Finance, National Bank of Rwanda:
“Let your local context guide how you implement.”
Thailand focused on non financial data first because the infrastructure was already in place. Rwanda’s model prioritizes mobile money. Canada of course is considering its own requirements, including provincial data laws, legacy banking systems, and regional financial access gaps. Bottom line is that a one-size-fits-all model that works abroad will not necessarily work elsewhere.
The table below primarily covers open banking implementations, with some jurisdictions extending toward open finance (Brazil, India, Thailand).
This is an important distinction because open banking generally refers to access to 'bank account data' which is often mandated for regulated institutions. While Open Finance expands beyond banking data to include insurance, investments, pensions, government data, mobile money, and more.
| Country | Pricing Model | Regulatory Status | Governance Approach |
| Brazil | Free access below threshold | Mandated and implemented | Central bank |
| Thailand | Free for consumers; capped for firms | Mandated and being implemented | Bank of Thailand and industry consortium |
| India | Commercial pricing; no fixed rules | Voluntary, evolving | NGO-led (Sahamati); gaining government support |
| Rwanda | Pilot phase; not-for-profit approach | Mandated, not yet implemented | Multi-agency regulator framework |
| UK | Free for regulated APIs | Mandated and implemented (OB only) | Regulators (CMA, then OBIE, now JROC) |
| Australia | Free basic; optional premium | Mandated and implemented | Treasury under Consumer Data Right law |
| EU (PSD2) | Mostly free under PSD2 | Mandated and implemented (OB only) | Regulator; preparing Financial Data Access (FiDA) |
| Singapore | Voluntary pricing; no mandate | Voluntary | MAS; market-driven with government-backed standards |
| Hong Kong | Commercial rates allowed | Voluntary with phased guidance | HKMA; implementation by industry associations |
| Canada | TBD (under consultation) | Mandated, not yet implemented | Department of Finance; FCAC |
Canada has committed to implementing open banking but full rollout isn't expected until 2026. In June 2024, the Department of Finance enacted the Consumer-Driven Banking Act, the legal framework for open banking, and appointed the Financial Consumer Agency of Canada (FCAC) as the authority responsible for implementing, overseeing, and enforcing the framework. Final rules on liability, pricing, and participation are still under development.
Countries that wait too long or rely only on voluntary models are playing catch-up. NCFA supports an open finance framework in Canada that protects consumers, enables competition, and accelerates innovation. Canada should learn from the world's most successful open finance systems, which are defined by clear regulation, fair pricing, and shared governance. As the CCAF’s global tracker and research show, clear rules work. Delay does not.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Digital Banking | May 9, 2025
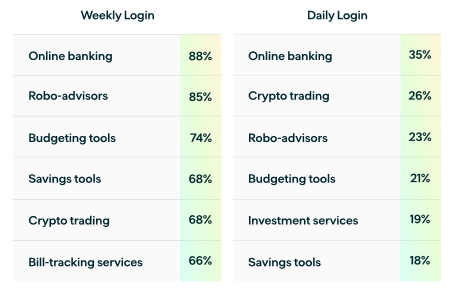
Image: Frequency of Use (Plaid x YouGov Money Talks survey report)
Between August 20-26th 2024, Plaid commissioned a national survey through the YouGov platform to understand how U.S. consumers bank, pay, and invest. The survey reveals insights of consumer preferences in digital finance, including trust in financial providers, app usage, payment methods, credit attitudes, and investment habits, based on weighted responses from 2,077 adults. Fintechs, digital finance platforms, and financial institutions need to stay up to date with the latest retail digital banking trends if they want to compete for consumer loyalty. Read 'Money Talks' (28 page PDF) report explaining these trends. Below we break-down key insights for NCFA's readers. Not yet subscribed? Sign-up for NCFA's weekly newsletter here.
Consumers continue to trust traditional banking institutions more than 100% digital platforms:
Trust and security go hand and hand, and overall, trust comes from perceived care and protection:
Consumers also shared who they rely on for financial well-being. The takeaway is that fintechs and advisory services must do more to be seen as helpful and caring, a useful partner in people’s financial lives.
Online banking is the most widely used financial tool: 99% percent of consumers are familiar with it, and 74% use it weekly.
Other commonly used tools include savings apps (68% weekly or daily), budgeting tools (85%), and peer-to-peer payment apps like Venmo or Zelle (used weekly by 50% of users). Roboadvisors are accessed more than once per week by (80%) of their users but only 1% of all consumers report using them regularly.
When asked what improvements they want most in financial apps:
60% of respondents said it is important to link their bank account with the financial apps they use.
Takeaway: Apps that are integrated, responsive, and secure are the most likely to be used often. Fintechs and banks that overcomplicate services or create friction in setup risk being overlooked, even if their offerings are advanced.
25% currently invest in cryptocurrency. Another 21% say they plan to invest in crypto or NFTs in the next year. These responder levels of engagement are equal to the 25% of people who say they will invest in stocks or trading platforms during the same period.
Crypto investors are not limiting their exposure:
Only 11% of respondents have used AI tools to support their investing decisions -> interestingly, this already exceeds the share of people using roboadvisors, suggesting that AI powered investment tools are gaining traction faster than traditional automated advice products.
Takeaway: Fintechs offering secure, easy to understand crypto access or AI investment tools can appeal to a growing investor base. Banks that avoid crypto are at risk of losing relevance with younger and self-directed investors.
Debit cards are now more commonly used than credit by younger adults. According to EY data cited in the report, 69% of Gen Z use debit cards daily or weekly. Many say they avoid credit cards because they do not want debt or do not qualify.
Buy now pay later (BNPL) services have grown 40% in usage since 2021.
Takeaway: Only 30% of respondents believe their credit score accurately reflects their financial health. 55% said they have been denied a loan due to a low score. These figures support growing interest in alternative data, such as cash flow and account history, for lending decisions.
Older adults are especially cautious. People aged 66 to 70 are 55% more likely to mistrust digital banks than those aged 22 to 25. Younger adults are more flexible. Among respondents aged 18 to 24, 36% said they would switch banks for a better digital payment experience.
Despite these trends, most people are not actively looking to change banks:
Consumers use different payment methods based on transaction size and age group:
To fund digital wallets:
Takeaway: Fintechs that want to increase adoption of pay by bank options must improve the experience. According to the report, 49% of users say they are likely to use pay by bank if the account linking process is easy.
Consumers want financial services that are clear, secure, and helpful, with trust remaining the most important factor in deciding whether to try a new app, share data, or switch banks. Traditional banks still hold an advantage in trust and reach but must modernize quickly. Fintechs have room to grow if they lead with transparency and value. Financial institutions that support financial goals and offer simple, connected experiences will stay relevant in 2025 (and beyond). Learn more about how consumers in the U.S. use, feel, bank, transact and acquire in 'Money Talks'.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Services | May 6, 2025
Image: Freepik
Two of Europe's leading digital banks, Revolut and N26 are now expanding into the telcom sector for continued growth. First it was Revolut on April 30, 2025 who announced they are launching mobile phone plan offerings in the UK and Germany, directly challenging traditional telecommunications network providers. Offering unlimited calls, texts, domestic, and 20GB of EU and US roaming, all managed inside its app without the need for a contract, all for £12.50 per month (introductory offer; UK waitlist; GER waitlist)
Just days later, Bloomberg reported that German neobank N26 also planned to launch a mobile phone service in Germany in May. These are not side pet projects but new product launches that provide key insight into how digital banks plan to fuel growth. It's easy to envision how digital finance platforms that offer banking, payments, and other services like phone plans or even internet can be rolled into a single platform and customer experience. The question for Canada is not whether consumers want more product choice and better pricing, it's whether the country (read: political will) are ready for it or not?
Revolut first dipped its toes into mobile connectivity by launching its eSIM product last year which has already become its most popular non-banking feature, with millions of data plans being activated in more than 100 countries. And now, backed by user demand and network partnerships, Revolut is launching a full mobile service. And now, N26 is doing the same. Both digital banks are offering a simple, affordable (flat rate) plans through national mobile networks and bundling everything into their apps.
In 2018, the CBC reported that Canadian mobile phone bills were among the highest globally. Even the Canadian Radio-television and Telecommunications Commission (CRTC) regulator has acknowledged concerns about the affordability of telecommunications services in Canada. It's not a new discovery, they've been saying the same thing for years. The Competition Bureau of Canada published a report confirming that Canadians want more competition in the financial sector, especially younger generation who are mobile first and ready for apps that simplify their bills, reduce fees, and improve control.
While the majority of Canadians still rely on a handful of banks and telcoms, Canada's market is still closed to this model. The top five-six banks in Canada control over 90% of all bankable assets, and the top three telcoms serve the majority of mobile customers. Mobile virtual network operator access is limited. Same thing goes for banks. Banking licensing process is long (approx 5 years) and expensive. While these conditions may protect incumbents, it makes it almost impossible for platforms like Revolut or N26 to launch integrated financial or mobile services in Canada.
Now that Mark Carney has been elected as Canada's new prime minister, there's increasing pressure to improve competition to drive affordability and fix Canada's weak and declining productivity. The convergence of banking and telecommunications checks all boxes. Canada just needs to expedite the modernization of it's digital infrastructure to support long term and sustainable growth from a more competitive sector.
Canada's policies must enable innovation for Canada to build a more robust economy and attract investment. The benefits of expanding competition and bundling the fintech-telcom sectors are many including consumer affordability and choice.
Revolut and N26 are showing that mobile and financial services can be bundled into seamless digital service platforms that offer users more control and lower fees. Canadian consumers want this to happen but past-governments have lacked the political will to act. However, with a new prime minister and economic mandate, there's hope and a window of opportunity that Canada may see increased focus on competition and productivity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Retail Banking | May 1, 2025
Retail digital banking platforms are evolving into the foundation of modern financial services driven by consumers appetite for AI driven platforms that make it easier to manage money, get personalized advice, and accessible services anytime on any device.
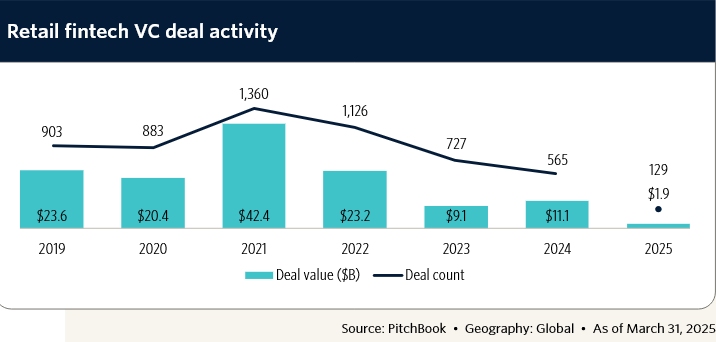
According to PitchBook Retail Fintech VC Trends, global retail fintech funding volumes reached $1.9 billion in Q1 2025, representing a 37.8% drop from Q4 2024 despite rising interest in platform-first strategies and growing AI adoption.
Although venture growth deals were the exception with median deal sizes jumping 67% to $47 million, making up 53.7% of total VC value. Klarna’s $12 billion valuation and Addi’s $170 million growth round stand out. IPO prospects for Klarna and eToro postponed listings due to market volatility ala Trump-effect.
Early stage retail fintech including median pre-seed and seed valuations fell by 50% and declined in size and count.
CCG Catalyst’s May 1 2025 snapshot of retail digital banking platforms features fintech companies are gaining traction because they stack cloud-native scale, AI tools, and modular architecture:
| U.S. Platform | Why Investors Are Interested |
| Backbase | Microservices, API-first architecture, and enterprise flexibility |
| Narmi | Open API stack and fast onboarding (under 3 minutes) |
| Lumin Digital | AI-native with strong mobile UX, cloud-native since day one |
| SoFi/Cyberbank | End-to-end infrastructure with embedded finance support |
| Temenos Infinity | Low-code platform enabling rapid interface development |
Canada’s fintech ecosystem has several growing players with potential to evolve into full service modular banking platforms or infrastructure providers:
| Canadian Company | Comparable U.S. Platform | Strategic Direction |
| Wealthsimple | SoFi | Expanding beyond investing into cash accounts, cards, and tax tools |
| Koho | Narmi | Prepaid card and banking-like functionality with open APIs |
| Neo Financial | Lumin Digital | Mobile-first, rewards-driven model with merchant integration |
| EQ Bank | Backbase | Hybrid of legacy and digital bank offering API access and high-interest accounts |
| Tandem or Brim | Apiture or Temenos | Fintechs with credit and loyalty platforms, potential to grow through partnerships |
Canadian fintech is still limited by federal regulatory complexities but opportunities are increasing as consumers move away from branch-based banking, the need for increased competition amidst Trump's economic pressures, and newly elected Prime Minister Mark Carney vowing to protect Canada.
According to the Canadian Bankers Association's 2024 report, 70% of Canadians used a mobile banking app in the last year (on average 7.4 times per month), up from 65% in 2021.
VC interest in Canadian fintech remained strong in 2024, despite a global slowdown. Fintechs with platform enabling capabilities such as embedded finance, banking-as-a-service, and open API designs continue to attract interest. Plus, the rise of U.S. plug-and-play models is a playbook for homegrown infrastructure players to serve Tier 2 banks, credit unions, and niche verticals like gig economy banking.
Digital banking platforms at the forefront are meeting customer expectations and improving operational efficiency with a few key technologies:
Digital retail banking platforms are using AI, APIs, and modular designs to deliver flexible, intelligent, and ready to scale solutions. Canadian fintechs that embrace open architecture and build for partnerships can lead not just here in Canada, but globally.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Innovation Economy | April 29, 2025
Image: Freepik
Mark Carney has been elected as Canada's 24th Prime Minister after leading the Liberal Party to win the 2025 federal election. The Liberals secured 168 seats (just shy of a majority), and are expected to form a minority government. Prime Minister Mark Carney has already spoken with President Trump about the pressing issues of tariffs, trade war and 51st state rhetoric, and the two leaders have agreed to meet in person.
While those issues are of critical importance to Canada's sovereignty, this article looks at Carney's past public comments and Liberals 2025 platform to get a sense for the implications for Canada's fintech sector under his expected leadership.
In 2019, Carney was the Governor of the Bank of England (BoE) and said the following at the Innovate Finance Global Summit:
“A new economy requires a new finance... to serve the digital economy, to support the major transitions underway across the globe and to increase the sector’s resilience”.
The newly elected Prime Minister of Canada has a deep background in finance, global networks, and a steady hand at innovation. He's expected to speed up payments modernization, support the responsible AI development, foster fintech investment, tighten crypto rules, and open more global markets to Canadian companies. The Liberal Party commitments that support innovation include financial technologies and sustainable finance, infrastructure investment, internal trade reform, red tape reduction, and a patent box regime, all told would help strengthen the economy and fintech growth.
When Carney was leading the BoE, he signalled strong support for opening payments infrastructure to non-bank providers, helping to boost innovation and competition. In Canada, the implementation of open banking and payment modernization initiatives (i.e. Real Time Rail System) have sadly faced prolonged delays. Carney is expected to speed up these rollouts to benefit consumers and competition. Open banking will give consumers control over their financial data and allow fintech companies to create new services, while the operating firms must meet high security and operational standards.
As part of its 2025 platform, the Liberal government committed to eliminating federal barriers to interprovincial trade and labour mobility by Canada Day. Reducing costs and aligning standards could benefit fintech companies that must constantly track and adjust to changing and inconsistent provincial compliance requirements, in sectors like payments, insurtech, wealthtech, and others. Streamlining trade and regulatory barriers would help fintechs expand nationally more effectively, reduce legal and operational costs, and also contribute to offering consistent services to customers and businesses from coast to coast.
Carney spoke about how emerging technologies are game-changing finance in a 2018 Mansion House speech “New Economy, New Finance, New Bank”, where he acknowledged AI's growing impact on credit and risk systems.
Under his government, Canada is expected to advance the Artificial Intelligence and Data Act to regulate high impact AI systems including financial firms using AI for credit scoring, fraud detection, or robo advising to ensure responsible AI standards are met for fairness, explainability, and consumer protection.
Immediately after securing Liberal leadership, Carney axed the controversial capital gains tax hike, directly supporting Canada's innovation economy. Under his leadership, Carney could expand access to venture capital, innovation incentives, and encourage national regulatory alignment for startups operating across multiple provinces. The Liberal platform also supports a patent box regime, focused on scaling high growth firms, retaining intellectual property in Canada, and improving commercialization outcomes from public and private R&D. The Liberal 2025 Platform outlines efforts to increase business investment and create a more competitive innovation environment, especially for sectors like fintech and AI.
Although Carney previously showed openness towards regulated forms of crypto innovation, in 2018, he spoke critically of unbacked crypto assets and called Bitcoin “neither a store of value nor a useful means of exchange”. It's expected that he'll tighten oversight of crypto exchanges, stablecoin issuance, and asset custody. Lastly, while Carney hasn't explicitly endorsed a Canadian CBDC, he has called for central banks to explore sovereign digital currencies as tools to support monetary policy and financial stability. During a 2019 speech at the Jackson Hole Economic Symposium, for example, Carney proposed the idea of a "synthetic hegemonic currency" (SHC) as a potential solution to the destabilizing dominance of the U.S. dollar in the global financial system.
Mark Carney is one of the most prominent global figures in sustainable finance. He co-founded the Glasgow Financial Alliance for Net Zero (GFANZ) and served as the UN Special Envoy on Climate Action and Finance. His leadership brings a strong focus on aligning financial systems with climate goals. The 2025 Liberal platform commits to supporting green innovation and transitioning Canada toward a low-carbon economy. This creates opportunities for fintechs in areas like ESG data services, green lending, climate risk modeling, and carbon trading infrastructure.
Carney is expected to support broader digital financial access across Canada. In his 2018 “Future of Money” speech, he emphasized the role of digital identity, financial modernization, and infrastructure in improving inclusion. While he has't directly addressed digital ID for Canada, the Liberal platform’s national digital readiness strategy includes high speed rail and northern connectivity projects that could help bring digital banking and fintech services to underserved and remote communities.
| Opportunities | Challenges |
| Launch of real time payments and open banking | Meeting tougher compliance and risk standards |
| New funding for AI, fintech innovation, and green finance | Higher expectations for responsible AI and cybersecurity |
| Stronger startup investment environment and patent box incentives | Adapting to stricter crypto and stablecoin rules |
| Global trade partnerships and reduced internal trade barriers | Competition from international fintech firms |
| Possible leadership in digital identity and CBDC projects | Regulatory complexity for multi jurisdictional firms |
| Growth in sustainable finance and ESG fintech | Evolving global standards for ESG data and disclosures |
| Growth in digital access through national infrastructure | Uneven fintech access in rural and remote communities |
Mark Carney's credentials offer an elite tier of credibility in global finance, climate leadership, and modernization of financial systems. Together with the Liberal 2025 Platform's strategic commitments to innovation, interprovincial trade liberalization, red tape reduction, and IP commercialization, his leadership is desperately needed to improve Canada's flailing productivity, upgrade its financial ecosystem, build public trust and international competitiveness.
His background also positions Canada to lead in sustainable finance, aligning innovation with global climate goals. For fintech entrepreneurs, investors, and policymakers, the Carney era is underpinned by stable governance and a clear vision, offering a mix of opportunity and responsibility.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 25, 2025
Image: Freepik/lyashenko
Most people choose to manage their finances by maintaining accounts across different banks. They often do so to take advantage of specialized offerings, such as higher interest rates for savings, better rewards for spending, or tailored features for specific financial goals like emergency funds, investments, or travel expenses. It’s also overall better for financial security to have multiple accounts, as this reduces the risk of someone losing access to all their funds in case of technical issues, fraud, or unexpected account freezes in an institution.
Of course, it’s no walk in the park to determine where you should open your next bank account, given the sheer number of options on the market. However, there are plenty of reasons to turn your attention toward digital banks in particular. Unlike traditional banks with physical branches, digital banks operate entirely online and are purpose-built for the highly tech-driven world of today. They utilize technology to offer fast, convenient, and innovative financial solutions without the hassle of in-person visits or cumbersome processes.
All of the above mentioned qualities are making digital banking an increasingly popular choice among modern consumers around the world. According to data from the American Bankers Association, for instance, up to 71% of consumers in the country now prefer digital banking. In the Philippines, digital banks have seen growth by leaps and bounds, collectively accumulating more than PHP 80 billion worth of deposits by June 2024.
If at this point you’re still unsure about letting yourself get caught up in this rising tide, then read on; this article will outline why a digital bank might be the perfect choice for you.
If you’re looking to grow your savings faster, digital banks might give you just the incentive you need. With fewer operational expenses, they can afford to give higher interest rates on savings accounts compared to traditional banks. These competitive rates can make a significant difference over time and help you maximize the returns on your deposits without requiring any extra effort on your part.
If you’re looking for the best digital bank account Philippines’s consumers go to for a rewarding saving experience, then you’ll definitely want to bank with Maya. All Maya savings accounts start with a competitive interest rate of 3.5% p.a.—and from there, you can boost it as high as 15% p.a. by paying bills and buying load through the Maya app, as well as making purchases using your Maya Card, QR, or via online checkout. There are also other savings products like Personal Goals and Time Deposit Plus, both of which have higher interest rates compared to their counterparts from other providers. It’s without a doubt the bank account that can make your savings work the hardest.
High banking fees like monthly maintenance fees and withdrawal charges can chip away at your money over time. Though the one-time cost of these fees is often not that high, the sheer quantity of fees you often have to pay at a traditional bank can make the amount snowball quickly. Digital banks, in contrast, are designed to eliminate many of these expenses. Since they operate without physical branches, they save on overhead costs and pass those savings directly to their customers. This means you can enjoy low or even no fees on services like account maintenance, fund transfers, and ATM withdrawals, which allows you to keep more of your hard-earned money.
Picture this: it’s late at night, and you suddenly need to transfer funds, check your account balance, or pay a bill. Traditional banks with fixed hours might leave you stranded until morning, but digital banks will never lock you out. Their platforms are accessible round-the-clock through your smartphone or computer—a convenience their traditional counterpart just can’t match. Whether you’re traveling across time zones or just need banking services during unconventional hours, digital banks keep you connected to your money at all times.
Navigating the world of finance doesn’t have to be complicated and digital banks excel at making their platforms intuitive and easy to use, even for those who aren’t tech-savvy. Features like clean interfaces, real-time notifications, and built-in budgeting tools transform digital financial management into a seamless experience. These thoughtful designs help you stay in control of your money without the frustration that often accompanies the experience of using traditional banking apps.
Fear of online threats like identity theft and scams is one of the biggest roadblocks preventing consumers from embracing digital finance. For this reason, digital banks will always prioritize the safety of your finances and personal information. The latest cybersecurity technologies—such as biometric authentication, two-factor verification, and encryption—form the backbone of their security systems. In addition, you can set up real-time alerts to keep you informed of every transaction, so you can act swiftly in case of suspicious activity.
Gone are the days of lengthy paperwork and multiple trips to a bank branch just to open an account. Digital banks streamline the process by letting you sign up entirely online, often in just a few minutes. With straightforward instructions and minimal documentary requirements, you can start managing your money without delay.
Why settle for standard banking when you can access tools that help you save, invest, and spend more effectively? Digital banks often lead the way in offering innovative features, like the ability to create multiple accounts for different savings goals or integrated investment options. These unique offerings cater to the evolving needs of modern customers and elevate the user experience far beyond the basics of banking.
Digital banks represent the future of personal finance, surpassing traditional banks in terms of accessibility, affordability, and innovation. As the financial landscape continues to evolve, choosing a digital bank could be the step that modernizes how you manage your money. Explore your options and see how a digital bank might fit seamlessly into your financial life.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016