





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 8, 2026 | NCFA Fintech Market Activity | Digital Banking And Data Governance
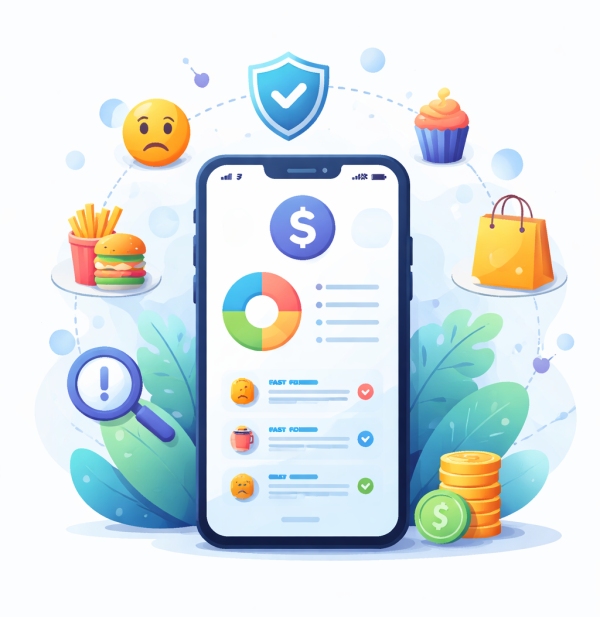
On Mar 7 2026, The Guardian posted that UK challenger bank Monzo is dealing with backlash from Monzo’s Year in review spending recap, a trust issue created by automated personalization. A customer escalated a complaint to the UK Financial Ombudsman Service after the AI recap used mocking language about food spending. The simple truth is banks can use AI to summarize spending, but it should avoid a tone that feels like judgement.
Two examples of the AI lines personalization that didn't sit well with customers after letting AI analyze their spending habits:
“Mainly, you fast fooded.”
“You like your banquets beige and boxed up.”
The customer described the wording as humiliating. The story also makes clear why tone can hurt even when the data is accurate. Spend patterns can reflect disability, illness, caregiving, job loss, stress, or crisis routines. A system that only sees categories and merchants can't understand the exact context. When it adds snark, it fills that context with judgement.
Monzo’s response was mixed. They didn't accept the complaint, but they still admitted the tone was wrong for that customer and apologized, and offered £20 as a goodwill payment. That mix reduces immediate heat, but it does not fix the underlying product risk.
“I recognise that in your case, the automated and standardised language we used was inappropriate and caused genuine upset.”
The primary lesson here is that personal spending data is too sensitive for automated copy that sounds like judgement.
Opt out doesn't fix a bad default. Banks and fintechs need controls that block mockery, shame, and moral scoring in any automated spending narrative. Teams also need to test outputs against vulnerable scenarios and worst case interpretations, not just average reactions.
Complaint handling needs a fast way to learn from these mistakes and force product improvements. A goodwill payment helps one customer, but it does not change the system. Banks and fintechs need escalation that can remove harmful language templates quickly, suppress outputs for affected customers, and pause the feature when tone crosses the line.
Automated spending recaps will continue to grow because customers want clarity and progress tracking. Banks and fintechs should keep recaps factual, let customers choose tone, and treat trust as a product requirement. When a bank speaks about a customer’s money, it needs to speak with care.
When a bank turns transaction history into a narrative, what standard should govern tone, testing for vulnerable scenarios, and escalation when a customer reports harm?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Market Insight | AI And The Future Of Work

Image: Labour market impacts of AI: New measure, early evidence (Anthropic Mar 2026)
On March 5 2026, new Anthropic artificial intelligence labour market impact research | download 17 page PDF offers a more grounded way to think about AI and jobs. Most AI labour studies ask what large language models could do in theory. This one asks what workers actually do with AI now. That sounds like a small change, but it matters. Financial institutions, fintechs, and policymakers need to know where real workflow change starts, not just where capability headlines point.
The paper introduces a new measure called observed exposure. It combines occupational task data, Claude usage data, and earlier research on which tasks language models can theoretically handle. The approach tries to separate technical possibility from real use. That makes this study potentially more useful than other broad forecasts about AI replacing jobs. To be clear, at this point the research doesn't claim mass displacement has arrived. It looks instead for early pressure points that may show up before unemployment spikes.
This report matters because it focuses on real work patterns. The authors use the US O*NET task database, Anthropic Economic Index usage data, and earlier task level exposure estimates to build their measure. They also give more weight to automated and work related uses than to lighter forms of assistance. That helps the study track where AI starts to move from drafting help into actual production work.
That said, the research has real limits, and those limits matter. The usage data comes from Claude, not from the full AI economy. A bank using Microsoft, Google, OpenAI, or internal tools may show a different pattern. The measure also tracks task exposure, not direct job loss. And the authors make clear that adoption still lags capability because of legal controls, software requirements, human review, and workflow friction. That caution strengthens the paper rather than weakening it. It keeps the analysis honest.
The most striking findings is the size of the gap between capability and real usage. In STEM (ie. computer and math) occupations, earlier work suggests language models could theoretically touch 94% of tasks. Anthropic’s observed measure puts current Claude coverage in that category at just 33%. In other words, the technology frontier sits much further ahead than the adoption frontier.
That gap matters for fintech and finance because it points to where the real bottleneck sits. The next productivity jump might not come from a bigger, better, faster or smarter model alone. It might come from firms that redesign workflows, tighten controls, connect tools to internal systems, and build trust in output quality. Which operators can close the adoption gap faster than peers.
The report finds that computer programmers rank as the most exposed occupation, with 74.5% coverage. Customer service representatives follow at 70.1%, and data entry keyers come next at 67.1%. Digital, repeatable, text heavy work moves first.
What stands out for NCFA readers is that this isn't just software engineers. Financial analysts are also among the most exposed occupations in the paper’s wider discussion. That should get the attention of banks, insurers, wealth platforms, lenders, and compliance teams. A lot of value in finance comes from summarizing information, checking documents, explaining options, processing forms, and moving data from one system to another. Those are exactly the kinds of tasks that AI enters early.
Workers in the most exposed occupations earn 47% more on average than workers in the unexposed group. People with graduate degrees make up 17.4% of the most exposed group, compared with 4.5% of the unexposed group.
Early pressure is showing up in better paid, more educated, office based roles. In practice, that means AI may alter the work of analysts, developers, researchers, service teams, and operations professionals before it touches many frontline physical jobs. For financial institutions, this points to a management challenge as much as a technology one. Firms need to rethink role design, supervision, training, and quality control inside knowledge work functions.
The research does not find a growing rise in unemployment for workers in the most exposed occupations since late 2022. That is an important result because it pushes back on louder claims that AI already causes wide labour market damage.
But the report does find an early warning sign. For workers aged 22 to 25, job finding rates into highly exposed occupations fall by about 14% compared with 2022 levels. The authors stress that this result is only barely statistically significant and open to other interpretations. So something to watch and track.
This is how labour market change often starts. Not with mass layoffs. Not with an obvious cliff. It starts when firms stop hiring as many junior people because AI now handles part of the routine work those hires once learned on. That's important for banking, fintech, consulting, and other white collar sectors that depend on apprenticeship style career ladders. If entry points narrow, firms may save money in the short run while weakening their future talent pipeline.
Firms should watch three things closely to better anticipate where the real gap may open between leaders and laggards:
For fintech builders, the market needs tools that help institutions safely plug AI into live work. Audit trails, review controls, workflow routing, structured data extraction, policy checking, and role based permissions. Companies that solve those problems help close the distance between AI capability and actual business use and adoption.
Anthropic’s research is quite useful because it shows where real adoption starts, where the biggest gaps remain, and where the cracks may start to appear and proliferate.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Insight | Regtech And Identity And Privacy

On Feb 16 2026, an interesting post at The Local Stack conducted a recent LinkedIn identity verification analysis via a real user experience of a larger fintech issue: modern identity checks now collect far more than most people expect, and the privacy tradeoff is becoming harder to ignore as regulated onboarding expands across financial services, platforms, and digital marketplaces.
Persona’s identity verification policy shows the scale of that collection. The policy lists government ID images, selfies, biometric information, NFC chip data, device data, geolocation, usage data, and checks against third party data sources. It also states that uploaded ID images may be used to train or improve the service, and that information may be shared with service providers, data partners, affiliates, and government authorities in some circumstances.
1. Identity verification now reaches well beyond document review. A current verification flow can combine document capture, face matching, biometric analysis, device signals, location data, and external database checks in one session. That means the onboarding event is no longer just a fraud control. It is a multi layer data collection workflow that carries legal, operational, and reputational risk.
2. The trust layer often sits with a specialist vendor, not the brand the user sees. A customer may think they are verifying with LinkedIn, a bank, or a fintech app. In practice, the verification is often run by a third party with its own privacy terms, data sources, subcontractors, retention rules, and model improvement rights. That gap between front end trust and back end processing is where privacy friction starts.
3. Privacy design now affects conversion. When users feel overexposed, abandonment risk rises. Firms that explain what's collected, why it's needed, who processes it, and how long it's kept are more likely to keep trust intact through onboarding. In identity verification, transparency is becoming part of product design.
Map every data field in the verification flow, not just the front end prompts. Disclose which vendor runs the check and what that vendor can do with the data. Remove optional collection that doesn't improve the actual risk decision. Review training, retention, and subcontractor clauses in vendor contracts. Put the plain language explanation before the scan starts, not after the user has already submitted a passport and selfie.
These steps become more important as Canada moves toward broader data portability and consumer directed finance. NCFA has already covered the wider privacy backdrop in North America privacy trends and the policy direction in CSA data portability consultation. Canada’s consumer-driven banking framework and the Consumer-Driven Banking Act push the market toward safer, permissioned data sharing. As that framework matures, identity credentials may become more reusable across providers, which could reduce repeated document collection while increasing pressure for stricter consent controls, narrower data use, and clearer liability when verification vendors sit in the middle.
Identity verification is moving from a hidden compliance step to a visible trust product. More onboarding flows will combine biometrics, device intelligence, and third party data. More enterprise buyers will ask whether vendors can use customer data to improve models. More regulators will look at whether the scope of collection matches the actual risk being assessed. The firms that win will not be the ones that collect the most data. They will be the ones that collect the least data needed to deliver a defensible result.
When identity checks collect more than most users expect, do the firms with the clearest privacy design earn more trust than the firms with the most aggressive control stack?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 4, 2026 | NCFA Fintech Market Activity | Regtech And Financial Crime Compliance
AI image robot analyzing financial data in office
On March 4 2026, UK based Vivox AI raised £1.3 million to scale AI agents built for AML, KYB, and KYC workflows inside regulated financial institutions.
Vivox AI ties the raise to current deployment claims across enterprise customers operating in more than 100 countries, including the UK, Europe, the United States, and Singapore. The release says complex compliance case processing time falls from about six hours to about 30 minutes, false positive screening alerts fall by up to 86%, and straight through processing reaches up to 50% for selected onboarding and due diligence workflows.
AML, KYC, and KYB work is repetitive, document heavy, and costly. Time per case, alert volume, and exception handling drive staffing levels and backlog risk. The goal is to target those exact cost drivers. Less time per case reduces analyst hours. Lower false positive rates reduce review load. Higher clean through processing reduces manual touch rates.
The product is described as separate task agents rather than one general AI layer. That design fits regulated workflows more closely because onboarding, due diligence, screening, and case handling can be controlled, tested, monitored, and audited as separate processes. In practice, compliance teams need faster file handling, cleaner audit trails, and fewer manual reviews that do not add risk insight.
Canada recently updated its Canada anti fraud policy and continues to raise expectations on prevention, detection, and reporting. That pushes more pressure through AML, KYC, and KYB operations while boosting financial crime compliance innovation.
Vivox AI is entering a category where established Canadian and Canada connected firms already cover adjacent parts of the stack. Trulioo identity verification supports global KYC and KYB onboarding. iComply compliance automation covers modular AML, KYC, KYB, and KYT workflows. Nasdaq Verafin financial crime controls serves financial institutions with AML, fraud, and investigation tools. Vivox AI’s stated position is narrower and more execution focused: task specific agents inside case work, screening, and due diligence workflows.
For operators key metrics such as time saved per case, false positive rates, exception rates, audit evidence quality, and post approval error rates will determine whether automation lowers cost or adds a second layer of review.
If compliance automation cuts a six hour case to 30 minutes and reduces false positives by up to 86%, does workflow design replace compliance team size as the main scaling lever?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 3, 2026 | NCFA Fintech Market Activity | Wealthtech And AI Operations

On March 3 2026, Canadian wealthtech based in Calgary OneVest launched its Agentic Wealth Operating System, a new platform built to automate core wealth management workflows across onboarding, account opening, fund movements, fee billing, document handling, and multi step operational tasks.
The launch is a product and workflow infrastructure improvement. OneVest’s own platform pages already position the company around advisor experience, client experience, home office tools, compliance, and workflow automation. The new operating system pushes that model further into direct task execution across the middle and back office. OneVest describes it as 'a unified intelligence layer that proactively connects advisors, operations teams, and clients'. OneVest recently closed $20M Series B to Lead Wealthtech.
OneVest is aiming at the operational layer of wealth management. Wealth firms still lose time and margin in areas such as onboarding, account setup, approvals, data re entry, billing, and document processing. These are repeatable workflows where automation can cut labour time, reduce handoff friction, and improve operating consistency.
The new launch adds an AI native execution layer on their stack which is designed to streamline execution and reduce manual steps, duplicate tasks and improve faster completion of advisor and operations work. If firms can automate account opening, fund movement workflows, billing processes, and document extraction inside the operating system, then labour cost, processing time, and error rates all become addressable.
For operators, the key test is measurable workflow impact. How much onboarding time will be saved, manual touches removed, billing accuracy, exception rates, and the number of workflows that move from staff handled to system executed.
Firms that control workflow execution inside wealth infrastructure can become harder to replace than firms that only improve the interface. If OneVest can move from software layer to operating layer, the product value and switching costs both get stronger.
As wealthtech moves from dashboards to workflow execution, does the next valuation premium go to firms that automate operations instead of firms that only modernize the front end?
Wealthtech is evolving from digital interfaces to operational automation. Client portals and advisor dashboards improved the front end. The next competition layer sits behind the screen in workflow engines, approvals, data flow, and execution control. That is where firms either scale cleanly or absorb more overhead as assets and client counts rise.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 2, 2026 | NCFA Fintech Market Insight | AI And Market Structure
On February 21 2026, India’s AI declaration (from it's AI Impact Summit 2026 held in New Delhi from Feb 18-19, 2026) got 91 countries and international organizations behind a voluntary and non-binding framework on AI access, trusted systems, workforce development, scientific use, energy efficiency, and economic growth. Canada is on the list. So are the United States, the United Kingdom, the European Union, China, Russia, Japan, and India.
That kind of participation is a strong policy marker that still makes it relevant for fintech because the document goes straight at the building blocks that determine who can deploy AI at scale and who gets left behind. Affordable compute, trusted tools, resilient infrastructure, workforce skills, and broader access to AI resources all sit closer to the practical operating requirements for financial institutions and fintechs than generic summit language usually does.
One of the interesting facts about the declarative coalition itself is ten of the 11 BRICS members also appear on the declaration list. That means roughly 90.9% of the Brics bloc also signed onto the same AI framework. On a second axis, six of the 10 named Board of Peace funding contributors also appear on the declaration list. That overlap does not make the declaration binding, but it does show India assembled broader support than a narrow Western technology coalition.
AI infrastructure is becoming a competitive input, not just a policy topic. The countries that line up early around access, trusted systems, and workforce capacity can make it easier for domestic firms to adopt AI tools across lending, compliance, onboarding, fraud controls, customer support, and internal operations. The countries that lag on compute access, skills, or deployment frameworks risk a wider productivity gap.
Canada signed onto a wide multilateral AI framework that includes both major Western economies and most of BRICS. That doesn't create immediate legal obligations. It does, however, strengthen the case for domestic follow through on AI infrastructure, talent, and trusted deployment if Canada wants its fintech and financial services firms to stay competitive as AI moves deeper into core operations.
If nearly the full BRICS bloc and much of the Western alliance can align on a voluntary AI framework, does the next real competitive divide come down to execution rather than diplomacy?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
