




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 6, 2026
Image by Karina Kensington
Payments infrastructure tends to stay invisible until someone follows the money through it. For readers who track fintech from a Canadian vantage point, the more interesting story in US online gaming right now is not the marketing noise around free coins. It is the settlement plumbing underneath those offers, and how much of it now runs on the same stablecoin and crypto rails that fintech builders argue about every week. A promotion that looks like a giveaway is, on the back end, a payments product with a specific cost structure.
That structure is worth understanding before assuming the free part is where the value sits. US sweepstakes operators advertise no-deposit signup rewards heavily, and consumer-facing guides such as PlayUSA keep a running rundown of no deposit sweepstakes options across US-facing brands, which is a useful reference for seeing how the promotions are packaged and what the terms actually say. Read a few of those listings closely and a pattern shows up: the free coin at the front is the cheap part, and the real engineering sits in the rails that move value when a player buys an optional coin package or cashes out a prize.
This piece treats the no-deposit sweepstakes offer as a payments object rather than a gambling one. We will take the model apart layer by layer, from the two-currency design at the surface down to the settlement rails at the base, and look at where stablecoins and crypto payment networks have become load-bearing. The goal is accuracy, not promotion, because the questions this raises for payment processors and fintech vendors are turning into real regulatory exposure quickly.
A no-deposit sweepstakes offer is free coins credited to a new account after signup and identity checks, with no payment required to claim them. It is the front door to a free-to-play model, and it is genuinely free at that door. No crypto, card, or bank transfer is needed to receive the bonus itself, which is exactly why it works as an acquisition tool.
This model is not a real-money online casino. Real-money iGaming is licensed and legal in only a small group of US states, and it takes wagers denominated in dollars that pay out in dollars. Sweepstakes brands run on a different legal footing. They lean on promotional sweepstakes law, which requires a free method of entry and no purchase necessary to win, and that is what lets them operate across a much wider set of states than licensed casinos can reach.
Image by Karina Kensington
For a fintech audience, the key point is that the no-deposit coin is a customer acquisition cost, not a prize. The operator gives away something with no cash value to bring a verified user into the funnel. What happens after that first session, when a share of those users decide to buy more play or attempt to redeem winnings, is where actual money movement begins and where the payment rails start to matter.
Almost every US sweepstakes brand runs a dual-currency system. The first currency is usually called Gold Coins, which have no monetary value and exist only for entertainment play. You cannot redeem Gold Coins for anything. The second currency, often labeled Sweeps Coins, is the one that carries redeemable value, and it is the currency a no-deposit bonus quietly hands you a small amount of.
The design is deliberate. Because Gold Coins are what players nominally buy in the paid packages, the operator can say purchases are for entertainment currency. The Sweeps Coins arrive as a free promotional bonus attached to those purchases, or through no-deposit rewards, daily login credits, and mail-in requests. That separation is the legal hinge the whole model swings on, and it is also the reason payment flows split into two distinct directions.
Sweeps Coins generally redeem at roughly one coin to one dollar, though rates and thresholds vary by brand, and most operators require that a Sweeps Coin be played through at least once before it can be redeemed. A player cannot take the no-deposit bonus and cash it straight out. That playthrough condition, plus identity verification, is what stands between the free coin and the redemption rail, and it shapes how and when crypto settlement actually gets used.
Here is the honest version of the headline claim. Crypto rails do not power the free bonus itself, because nothing is paid to claim it. They power the two paid edges of the model: the optional purchase of coin packages, and the redemption of prizes. Those two edges are where value crosses between the operator and the outside financial system, and they are increasingly settled with cryptocurrency rather than only cards and bank transfers.
On the purchase side, a growing number of sweepstakes and crypto-adjacent social brands accept stablecoins and other tokens for optional coin packages. On the redemption side, several offer payouts in cryptocurrency alongside bank transfers and gift cards. For a US operator, both edges are attractive because card processing for anything gambling-adjacent is expensive, prone to declines, and often blocked outright by issuers who flag the merchant category.
Image by Karina Kensington
Crypto payment rails route around several of those problems at once. They do not depend on a card network approving the merchant, they clear without a chargeback mechanism, and they settle in near real time. When the goal is to move a redeemed prize to a player within minutes instead of days, or to accept an optional purchase without a declined transaction, the appeal is practical rather than ideological.
Bitcoin was the first crypto option most gambling-adjacent sites accepted, but stablecoins are what turned crypto into a serious settlement layer for this model. A prize denominated in dollars loses its meaning if it is paid in an asset that can drop ten percent before it reaches a wallet. Dollar-pegged stablecoins such as USDT and USDC remove that volatility, so a redemption stays close to its dollar value between the operator and the player.
The volumes involved are large enough that fintech observers stopped treating them as a curiosity. Chainalysis data covering mid-2024 to mid-2025 put USDT transfer volume at hundreds of billions of dollars per month, with total stablecoin activity peaking above a trillion in some months. Not all of that is payments, and a recent breakdown of stablecoin payment volumes on this site is a useful corrective, since a large share of on-chain movement is trading and liquidity flow rather than genuine commerce. Prize payouts are a thin slice of that total, but they are a slice that behaves like a payment.
Layer-2 networks and payment channels have pushed the economics further. Operators using networks like Polygon or Lightning have reported cutting per-transaction fees by most of what a card or older on-chain transfer would cost. For a business paying out many small redemptions, a fee that drops from a dollar or more to a fraction of a cent changes what is worth paying out at all, and it makes small, frequent prize redemptions viable in a way card rails never allowed.
It helps to see the whole thing as a stack, because the no-deposit offer only touches the top of it while the crypto rails sit near the bottom. The table below maps each layer to its function, the rail that typically carries it, and where the financial and compliance exposure lands.
| Layer | What it does | Typical rail | Where the exposure sits |
| Acquisition | Free no-deposit coins bring in a verified user | None, no money moves | Marketing and identity checks |
| Optional purchase | Player buys Gold Coin packages for more play | Card, bank transfer, or stablecoin | Card declines, processor risk |
| In-game credit | Coins move inside the operator ledger | Internal database, off-chain | Operator solvency, terms |
| Redemption | Sweeps Coins convert to a prize | Bank payout, gift card, or crypto | Fraud, playthrough abuse |
| Settlement | Value clears to the player wallet | Stablecoin on layer-1 or layer-2 | Peg risk, wallet errors |
| Compliance | Identity, source of funds, sanctions | KYC and AML tooling | Regulatory liability |
Reading the stack from top to bottom shows why the free coin is not the point. The acquisition layer moves no money, so it carries almost no cost per user beyond verification. Everything expensive and everything regulated lives below it, in the purchase, redemption, and settlement layers, which is precisely where stablecoin rails have taken hold. A fintech reader looking for the risk should look at the bottom three rows, not the giveaway at the top.
Speed at the redemption layer feeds back into acquisition in a way that is easy to miss. When a player believes a prize will actually arrive, and arrive quickly, the free coin at the front becomes more persuasive. A no-deposit offer is only as convincing as the payout experience behind it, and slow or failed redemptions are the fastest way to lose the trust that the free coin was meant to build.
This is where crypto settlement does quiet work. A redemption that clears in minutes, at a fee measured in cents, lets an operator honor small prizes without eating a card processor markup on every payout. That in turn lets marketing promise fast redemption without the finance team objecting, and the promise of fast redemption makes the no-deposit funnel convert better. The rails at the base of the stack become a marketing feature at the top.
Retention runs on the same logic. A player who receives a fast, correct payout once is far more likely to come back, refer a friend, and eventually buy an optional package, so the redemption layer is not just a cost center but the main driver of lifetime value. Operators that settle prizes on stablecoin rails can advertise redemption speed as a differentiator, and in a market crowded with near-identical no-deposit offers, the reliability of the payout is often what separates a brand players trust from one they abandon after a single cashout attempt.
There is a harder edge to this too. Faster, cheaper, harder-to-reverse rails also make abuse cheaper to attempt, since a bonus farmed across many fake accounts can be swept out through the same fast redemption path. Operators answer with playthrough requirements, stricter identity verification, and payout thresholds, which is why the free coin never redeems instantly. The friction that annoys legitimate players is the same friction holding the fraud math together.
For a Canadian fintech and crowdfunding audience, the interesting exposure is not the gambling question but the money-movement question. The moment a US sweepstakes brand accepts stablecoins and pays out crypto, it starts to look like a business that handles value transfer, and value transfer is regulated territory on both sides of the border. Payment processors and vendors sitting between the operator and the chain inherit part of that exposure.
Image by Karina Kensington
The questions worth asking mirror the ones fintech regulators already ask of any crypto-touching payment firm. Who performs know-your-customer checks on the player, and are they strong enough to satisfy anti-money-laundering rules on the redemption side? How is source of funds handled when a purchase arrives as a stablecoin from an unhosted wallet? What sanctions screening runs before a crypto payout leaves the operator? In Canada, a firm doing this kind of value transfer would be pushed toward money-services-business registration and FINTRAC reporting, and US operators face a parallel set of obligations.
None of this is hypothetical for the vendors. Geolocation providers, payment processors, and affiliates are increasingly named as parties who share liability when a model runs afoul of state law, which changes the risk calculation for any fintech firm considering the sweepstakes sector as a client. The payment rail is not a neutral pipe. It is a regulated activity wearing a promotional coat.
Two policy currents are now running straight at this model, one from gaming law and one from payments law. On the gaming side, California passed Assembly Bill 831, signed in October 2025 and effective January 1, 2026, which bans dual-currency online sweepstakes games in the state. It reportedly passed both chambers without a dissenting vote, and it extends liability beyond operators to the vendors and partners who support them, including payment processors, geolocation providers, and media affiliates, with penalties described as misdemeanor-level and reaching into the tens of thousands of dollars per violation.
That vendor liability is the part fintech firms should read twice. A payment processor that clears stablecoin redemptions for a banned dual-currency product in California is no longer a bystander under this framing. The law treats the rail operator as a knowing participant, which is a meaningful shift for anyone who assumed payment infrastructure sat outside gambling enforcement.
California is also unlikely to be the last state to move. Several legislatures have weighed similar restrictions on dual-currency sweepstakes, and a handful already limit or block the model, so a vendor building rails for these operators is underwriting a product whose legal footprint may shrink state by state. That is a different risk profile from a stable, licensed payments client, and it deserves to be priced as such.
On the payments side, the federal GENIUS Act, enacted in 2025, set out a tiered framework for payment stablecoins in the United States. That regime governs exactly the dollar-pegged assets sweepstakes operators use for settlement, and as issuers come under clearer supervision, the rails those operators depend on inherit new compliance expectations around reserves, redemption rights, and disclosures. The two currents together mean the model is being squeezed from the gaming side and formalized from the payments side at the same time.
It is tempting to describe all of this as crypto revolutionizing an industry, and that framing would be wrong in both directions. Stablecoins have not created the no-deposit sweepstakes model, which existed for years on card and bank rails, and they are not the reason the offers are generous. What they have done is lower the cost and raise the speed of the two paid edges, which quietly improves the unit economics of the whole funnel and lets the free coin at the front stay generous.
The measured view lines up with what payments researchers already found about these rails in general. One Bank of Canada staff paper on stablecoins as a means of payment concluded that they can increase transaction speed and support innovation, while offering weaker consumer fraud protection and posing higher payment-system risk, and that they currently serve niche use cases rather than replacing mainstream payment methods. A sweepstakes prize payout is exactly that kind of niche use case: a place where speed and low cost matter enough to accept the trade-offs.
For fintech readers, the takeaway is not to chase the sweepstakes boom or to dismiss it. It is to recognize that a promotional product most people file under entertainment has become a live demonstration of stablecoin settlement at consumer scale, complete with the fraud, compliance, and regulatory tensions that the payments industry has been debating in the abstract. The free coin is a distraction. The rails underneath it are the story, and they are being written into law in real time.
Do you need cryptocurrency to claim a no-deposit sweepstakes offer?
No. A no-deposit offer is free coins credited after signup and identity verification, with no payment of any kind required. Crypto only becomes relevant later, if a player chooses to buy an optional coin package or redeem a prize, and even then most brands still offer card, bank, and gift-card options alongside crypto.
How are Gold Coins different from Sweeps Coins?
Gold Coins have no cash value and exist only for entertainment play, so they cannot be redeemed for anything. Sweeps Coins carry redeemable value at roughly one coin to one dollar and can be exchanged for prizes after being played through at least once. A no-deposit bonus typically includes a small amount of both.
Why do sweepstakes operators prefer stablecoins over Bitcoin for payouts?
A prize is denominated in dollars, so paying it in a volatile asset risks the value moving before it reaches the player. Dollar-pegged stablecoins such as USDT and USDC hold their value between the operator and the wallet, which keeps a payout close to its stated amount. They also settle quickly and at low cost on layer-2 networks.
Does the California AB 831 ban affect payment processors?
Yes, according to reporting on the law. AB 831 bans dual-currency online sweepstakes in California from January 1, 2026, and extends liability to vendors that support them, a category that includes payment processors, geolocation providers, and media affiliates. That makes the payment rail a named party rather than a neutral intermediary.
Are sweepstakes casinos the same as legal online casinos?
No. Real-money online casinos are licensed and legal in only a small number of US states and take wagers in dollars. Sweepstakes brands run a free-to-play model under promotional sweepstakes law, which is what lets them operate more widely, though several states now restrict or ban the dual-currency version outright.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 3, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Capital Formation, Digital Securities, Private Markets, Fintech And Innovation

On July 2, 2026, a Vancouver private investment platform listed on the TSX Venture Exchange Parvis signed a binding agreement to acquire Atlas One Digital Securities, a registered exempt market dealer operating across Canada.
The deal hasn’t closed. Completion still requires customary closing conditions, regulatory approvals, and TSX Venture Exchange approval.
Atlas One was founded in Vancouver in 2020 and received EMD registration through the CSA Regulatory Sandbox in January 2021. It has helped more than 40 issuers raise over $115 million across real estate, private equity, and alternative assets.
This acquisition isn't mainly about Parvis getting a dealer licence, since it already has exempt market dealer capability through Parvis Investment Services. The stronger motivation is scale. Atlas One adds issuer relationships, investor reach, operating history, and another Canadian private markets team.
Parvis CEO David Michaud said Atlas One brings “a strong issuer network and a national investor base.” Atlas One CEO George Nast pointed to “greater product breadth, stronger compliance capabilities, and scale.”
This transaction is about combining two regulated private market operators so the business can serve more issuers and investors with fewer disconnected handoffs.
Private investment platforms can launch websites, investor portals, and digital onboarding, but private placement distribution remains the hard part.
A raise can still involve separate issuer outreach, dealer relationships, KYC, suitability checks, subscription documents, payment handling, investor updates, and reporting. Dealers need enough volume to justify diligence, supervision, and compliance work. Smaller issuers can struggle when the economics don’t work for intermediaries.
Technology can help, but only when it works with regulation rather than around it. EMD selling group rules show how dealer coordination, settlement, and distribution mechanics can affect exempt market fundraising.
The Parvis and Atlas One agreement belongs in that conversation. The challenge is whether regulated private market distribution can become easier to run at scale.
The Atlas One agreement follows Parvis’s planned U.S. expansion.
In May 2026, Parvis signed a binding letter of intent to acquire FavorPoint Capital, a FINRA registered broker dealer. Parvis said that deal was intended to help Canadian issuers access U.S. private capital markets.
Together, the Atlas One and FavorPoint deals suggest Parvis is trying to build regulated private market distribution across Canada and the U.S.
That strategy depends on more than adding companies. It requires issuer supply, investor reach, dealer permissions, compliance processes, reporting, and enough operating scale to make private raises easier to run.
While the transaction still needs approvals. Parvis also has to integrate people, issuer relationships, investor records, compliance processes, and technology. It's important work because private market platforms can’t scale on marketing alone. They need clean operations behind the investor experience.
Watch for:
The proposed deal fits areas mapped in NCFA’s Financial Innovation Map, such as capital formation, private market access, digital securities, exempt market distribution, alternative assets, and investor onboarding.
Parvis and Atlas One won’t fix Canada’s private capital market on their own. If approved however, it could show whether a Canadian platform can combine issuer access, regulated distribution, onboarding, reporting, and investor reach without adding more complexity for investors.
If Canadian private market platforms combine issuer networks, investor access, regulated distribution, and reporting in one place, will more companies raise capital outside traditional venture and public markets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 3, 2026
Image by Idris Halloway
Most of the fintech intelligence that crosses a Canadian analyst's desk arrives pre-labeled by sector: lending, open banking, payments, insurance. US social casinos rarely get filed under any of them, which is part of why the category is easy to underrate. Strip away the cartoon coins and the free-spin marketing, and what remains is a consumer payments business with a money-in flow, a money-out flow, and a compliance perimeter that looks familiar to anyone who has ever built a wallet or a checkout.
That reframing matters because the US market has grown large enough to work as a live demonstration of payment ideas the Canadian sector is still rolling out. Before treating social gaming as a novelty, it helps to see how the products are actually packaged for players. GamingToday keeps a running reference on sweepstakes-style gaming options that lays out how these titles present coins, prizes, and purchase tiers, which is a sensible way to read the consumer surface before you go looking for the plumbing underneath it.
This piece reads the boom the way a payments team would rather than the way a gambling columnist does. It walks through the money-in side, the identity layer, the money-out side, and the embedded-finance framing that ties them together, then asks the partner-risk question that US bank regulators are now putting to any firm that touches these flows. Throughout, the vantage point is Canadian, because the RTR launch and the country's open-banking timeline make the US experience unusually relevant reading for a payments desk in Toronto or Vancouver.
The first mental switch is to stop counting players and start counting transactions. A social casino does not earn money from people playing free rounds. It earns money at two points only: when a user chooses to buy a package of virtual coins, and, in the sweepstakes variant, when a user redeems an accumulated prize balance back into real value. Everything between those two points is engagement, and engagement is free to the player and nearly free to the operator.
Size the market and the reason for attention becomes obvious. Analyst estimates for the global social casino category in 2025 span a wide band, from roughly nine billion dollars to more than twenty billion, depending on where each firm draws the boundary between social slots, poker apps, and sweepstakes brands. The definitions are messy, but the direction is not in dispute: this is a multi-billion-dollar consumer segment whose entire revenue base is card charges, account transfers, and payouts. For a payments professional, that makes it a large real-world test of exactly the rails and controls the industry argues about in the abstract.
The revenue mix is what separates social casinos from most mobile games. By several industry counts, a large majority of new social casino releases now ship with in-app purchases, and the sale of virtual coins, not advertising, supplies most of what they earn. A game that monetizes through purchases rather than ads is, functionally, a merchant. It has a checkout, an average order value, a decline rate, and a chargeback problem, and those metrics behave the way they do in any high-frequency, low-ticket consumer business.
Precision here prevents the whole analysis from drifting. A social casino is a free-to-play product. The core loop uses a virtual currency, often called Gold Coins, that has no cash value and cannot be redeemed for anything. Players can buy more of it to keep playing, but they are buying entertainment time, not a stake. This is legally and mechanically distinct from a real-money online casino, which takes wagers in dollars and pays winnings in dollars, and which is licensed in only a small number of US states.
The sweepstakes variant adds a second currency, usually called Sweeps Coins, that can be redeemed for prizes, and it reaches players through no-purchase methods as well as through a bonus attached to coin packages. That free-entry mechanism is the legal hinge that lets sweepstakes brands operate in far more states than licensed casinos can. It is also the feature that draws the most regulatory attention. Real-money online casinos are not legal in California, and the state's Assembly Bill 831, effective January 1, 2026, restricts the dual-currency sweepstakes model directly, extending exposure to the vendors and partners who support it.
For a payments reader, the takeaway is narrow and important. The money-in flow, buying Gold Coins, exists in both the plain social model and the sweepstakes model. The money-out flow, redeeming a prize, exists only in the sweepstakes model, and it is the flow that carries the heavier compliance weight. Keeping those two flows separate in your head is the difference between understanding the sector and repeating marketing copy about free coins.
Buying a coin package looks trivial to a player: pick a tier, tap a saved card or a mobile wallet, receive coins instantly. Underneath, it is one of the harder acceptance problems in consumer payments. Card networks and issuing banks treat anything gambling-adjacent as elevated risk, even when the product is legally a game rather than a wager. That classification drives higher decline rates, tighter merchant category coding, and processor pricing that reflects the risk of chargebacks and reputational exposure.

Image by Idris Halloway
The consequences shape the whole business. An operator that loses even a small share of attempted purchases to false declines is leaving revenue on the table at its single point of monetization, so payment optimization is not a back-office concern for these firms but a growth lever. Many run several processors in parallel and route each transaction to whichever is most likely to approve it, a practice payment teams recognize as orchestration. Mobile wallets help, because tokenized wallet transactions approve at higher rates and reduce stored-card exposure, which is why the checkout you see is usually a wallet button rather than a raw card form.
Account-to-account options sit at the edge of this flow and are growing. Paying directly from a bank account through an open-banking connection or a pay-by-bank rail sidesteps card interchange and card-network risk rules entirely. For an operator squeezed on card acceptance, an account-to-account purchase is cheaper and harder for an issuer to block, which is one reason the social gaming sector watches open-banking payment initiation as closely as any retail category does.
The industry talks about identity as a compliance chore, but for a payments team it is really part of the acceptance stack. Before a sweepstakes brand can let value flow out, it has to know who the account holder is, and that verification has to be strong enough to satisfy anti-money-laundering expectations on the redemption side. Weak onboarding produces fraud losses and payout disputes; onboarding that is too heavy kills conversion at signup. The tension between those two failure modes is the same one every neobank and wallet provider manages.
What makes social casinos instructive is the sequence. Because the free coins require no payment, a user can sign up and play with almost no friction, and heavier identity checks are deferred until the moment money is about to move out. That deferred-verification design, light at the top of the funnel and strict at the cash-out gate, is a pattern payment and lending firms use widely, and the social casino version runs it at very large scale with real fraud pressure behind it. Watching how these operators tune the verification gate is a practical lesson in balancing conversion against loss.
The stakes rise on the redemption side because that is where the model resembles regulated value transfer. Source-of-funds questions, sanctions screening, and duplicate-account detection all land at the payout step. A payments provider evaluating one of these brands as a client should read the strength of that gate as carefully as it reads the purchase flow, because the redemption path is where the regulatory liability actually concentrates.
Step back and the whole arrangement is an embedded-finance story. The game company is not a bank and does not want to become one, yet it offers a checkout, a stored-value balance, and a payout capability that together behave like financial services wrapped inside entertainment. That is the definition of embedded finance: financial functions delivered inside a non-financial product, through partners who supply the regulated pieces behind the scenes. NCFA's own plain-language primer on embedded finance frames the category as banking brought to the customer rather than the customer sent to the bank, and a social casino is that idea taken to its consumer-entertainment extreme.
The value chain looks the same as it does in any embedded-finance case. There are providers who hold the regulated licenses, enablers who supply the middleware and orchestration, and distributors, here the game brands, who own the customer relationship and the interface. Industry projections put the embedded-finance market on a steep growth path, with one widely cited forecast pointing to roughly US$776 billion by 2029 at a compound annual rate near twenty-four percent, and social gaming is one of the noisier consumer expressions of that curve.
Seeing the sector this way changes which risks matter. The interesting exposure is not whether a given game is fun or fair. It is that a chain of payment providers, processors, wallet vendors, and identity firms is quietly powering a product with a shifting legal footprint, and each of those partners inherits part of the risk. That is precisely the arrangement regulators have started to examine, and it is where the Canadian reader should pay closest attention.
Prize redemption is where social casinos meet the most active frontier in payments: getting money to a person quickly and cheaply. A player who wins expects the value to arrive fast, and a slow or failed payout is the quickest way to lose that player's trust and any future purchases. So the redemption experience is not a courtesy, it is a retention mechanism, which puts direct commercial pressure on the operator to use the fastest rail available.

Image by Idris Halloway
Traditional payout rails make this hard. A bank transfer can take days, a card refund is slow and reversible, and a gift card shifts cost around without solving speed. The rails purpose-built for this problem are the real-time payment systems now spreading worldwide: in the United States, instant networks that clear in seconds around the clock, and in Canada, the Real-Time Rail that Payments Canada is bringing online in phases through 2026 on the ISO 20022 messaging standard, with irrevocable settlement any time of day. A payout that lands in seconds, at a low flat cost, is exactly what a redemption flow wants.
The irrevocability of those rails is a double-edged design. Instant, final settlement is wonderful for a legitimate payout and dangerous for a fraudulent one, because there is no chargeback to claw a bad transfer back. That is why the identity gate discussed earlier tightens precisely at the cash-out step, and why operators pair fast rails with playthrough conditions and payout thresholds. For a Canadian payments desk preparing RTR use cases, the social casino payout problem is a preview of the fraud and speed trade-offs the domestic rail will face across many industries.
It helps to lay the pieces side by side, because the player sees a simple game surface while the payments team sees a stack of distinct decisions. The table maps each visible touchpoint to what the player experiences and to the question a payments professional should ask about it.
| Touchpoint | What the player experiences | The payments question underneath |
| Signup and free coins | Instant, no payment, start playing | How light can onboarding be before fraud enters |
| Coin purchase | Tap a wallet, coins appear | Which processor approves it, at what decline rate and cost |
| Stored coin balance | A number in the app | Is this stored value, and who holds the liability |
| Identity verification | A prompt before cash-out | Is the check strong enough for AML on payout |
| Prize redemption | Money arrives, ideally fast | Which rail, how fast, and is it reversible |
| Partner chain | Invisible | Which licensed firm carries the regulatory duty |
Read down the right column and the pattern is clear. Nothing on the player-facing side reveals where the money, the liability, or the compliance duty actually sits. Every meaningful risk lives in the second column, in the partner arrangements the interface is designed to hide. A payments reader who only watches the game surface will miss the entire business.
The reason this matters beyond curiosity is that the firms enabling these flows are the same kinds of firms bank regulators are scrutinizing hardest right now. Through 2024, US banking agencies issued a joint statement on the risks in bank arrangements with third parties and asked for comment on bank-fintech partnerships, signaling that the regulated institution behind an embedded product cannot treat the partner relationship as someone else's problem.
Image by Idris Halloway
The principle those agencies set out reads directly onto the social casino chain. In the Federal Reserve's federal guidance on third-party risk management, issued with the FDIC and the OCC in 2024, the agencies state that engaging a third party does not diminish or remove a bank's responsibility to operate in a safe and sound manner and to comply with applicable requirements. Translate that to a game brand's payment stack and it means the licensed provider at the base of the chain owns the compliance outcome, no matter how many enablers and distributors sit between it and the player.
For any payment firm weighing social gaming as a client, that reframes the diligence. The question is not only whether a specific brand is above board today, but whether the provider can supervise a partner whose legal footing may narrow state by state as measures like California's restriction spread. A rail that clears a redemption for a product later ruled offside is not a neutral pipe in the eyes of these frameworks. It is a supervised activity, and the cost of getting the partner assessment wrong is measured in enforcement, not just churn.
The useful conclusion for a Canadian reader is not to chase the sector or to dismiss it, but to treat it as free field research. The US social casino market is running, at consumer scale, the exact experiments the Canadian sector is about to formalize: instant irrevocable payouts, account-to-account purchasing, deferred identity verification, and financial features embedded inside a non-financial brand. Each of those is a line item in Canada's open-banking and Real-Time Rail rollout, and the US market is stress-testing them in public right now.
The risks travel just as well as the techniques. The same speed that makes a real-time payout delightful makes a fraudulent one unrecoverable. The same embedded-finance structure that lets a game offer a slick checkout spreads regulatory duty across a chain of partners who may not all understand what they are carrying. A Canadian provider that reads the US boom carefully gets to learn those lessons before the domestic rail is fully live, which is a far cheaper way to learn them than through a domestic incident.
Filed correctly, then, US social casinos belong on the payments desk, not the entertainment page. They are a large, fast-moving, real-money demonstration of embedded finance under regulatory pressure, and the plumbing they run on is the same plumbing the Canadian sector is building. The free coins are the distraction. The transaction flows, the payout rails, and the partner-liability questions underneath them are the reading that repays the attention.
Why would a payments professional study social casinos at all?
Because the product is a consumer payments business dressed as a game. Its entire revenue comes from coin purchases and prize redemptions, so it exercises card acceptance, identity verification, and fast-payout rails at large scale under real fraud pressure. That makes it a working case study in the same problems any wallet, checkout, or neobank has to solve.
How do social casino coin purchases move through the card networks?
They move like any high-risk, low-ticket merchant charge. Card issuers treat gambling-adjacent purchases as elevated risk, which raises decline rates and processing costs, so operators often route transactions across several processors and lean on mobile wallets to lift approval rates. Account-to-account and pay-by-bank options are growing because they sidestep card interchange and network risk rules.
What makes prize redemption a real-time payments problem?
Players judge a brand by how fast a prize arrives, so operators want the quickest rail available, which points toward instant systems like the US real-time networks and Canada's coming Real-Time Rail. Those rails settle in seconds and are irrevocable, which is ideal for a genuine payout and risky for a fraudulent one, so identity checks tighten at the cash-out step to compensate.
How does embedded finance apply to a social casino?
The game company offers a checkout, a stored-value balance, and a payout capability without being a bank itself, relying on licensed providers and middleware behind the scenes. That is embedded finance by definition: financial services delivered inside a non-financial product. The same provider, enabler, and distributor value chain seen across embedded finance applies directly to the sector.
What should a Canadian payment provider check before working with a social gaming brand?
Start with the strength of the identity and source-of-funds gate on the redemption side, since that is where anti-money-laundering liability concentrates. Then assess the brand's legal footing state by state, because measures restricting dual-currency sweepstakes are spreading. Under current third-party risk frameworks, the licensed provider keeps the compliance duty regardless of how many partners sit in between.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Wealthtech And Investing, Digital Identity And Trust, Risk Compliance And Regtech, Fintech And Innovation
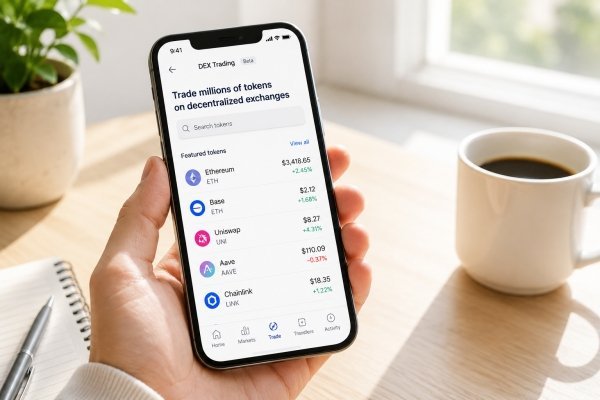
On July 2, 2026, Wealthsimple launched DEX trading in beta, giving eligible clients a way to trade on-chain tokens directly inside the Wealthsimple app.
The beta gives clients access to millions of tokens, starting with Ethereum-based assets. Base and Solana support are planned. The service charges a flat 0.85% trading fee and currently includes $0 network fees, which Wealthsimple Web3 Inc. covers during the early release.
This isn't the same product as Wealthsimple's centralized crypto account. When a client makes a first DEX trade, the app creates a separate self-custody wallet. The app holds DEX assets separately from centralized crypto holdings. They aren't insured, and don't have the same regulatory oversight as Wealthsimple's listed crypto offering.
A normal DEX user has to manage a wallet, fund it, connect it to a decentralized exchange, check token contracts, manage network fees, understand slippage, approve transactions, and protect private keys. As a result, there are a lot of steps that add complexity.
The beta removes much of that setup from the user experience. Its help guide says clients can search for DEX-labelled assets in the Discover tab, create a DEX wallet during the first trade, and buy or sell eligible DEX tokens directly in the app.
Behind the scenes, the app converts the funding asset into USDC. It then withdraws the funds to the self-custody wallet and routes the order through a third-party DEX aggregator before executing the trade.
Centralized crypto assets go through the platform's listing process, and the platform holds them on behalf of clients. DEX assets haven't gone through that centralized listing process.
Wealthsimple says a third-party vendor flags malicious tokens, and the app automatically filters them, and asset pages can display risk flags such as new asset history, top holder concentration, low holder count, low liquidity, sketchy token permissions, and artificial trading patterns.
Those flags are useful, but they aren't a safety guarantee. The help guide tells users to research tokens before trading and notes that blockchain transactions can't be reversed. If a client buys a scam or fraudulent token, the transaction can't be undone.
While the product lowers the operational barrier to on-chain markets, users still face risks that don't exist in the same way inside a curated centralized exchange custodial account.
Clients hold WS DEX assets in a self-custody wallet. They aren't covered by insurance, don't have government-backed loss protection, and aren't held by Wealthsimple on the client's behalf.
The support team can't recover the wallet or reverse transactions if something goes wrong. The user authorizes trades, and the wallet sits outside Wealthsimple's centralized crypto infrastructure.
There are also product limits during early release.
At the end of the day, there are limits to what the beta product is at this point. Embedded self-custody trading inside a controlled retail app, not a full open-wallet DeFi experience.
Wealthsimple's IPO Access launch gave eligible retail investors a way to request shares in selected Canadian and U.S. IPOs before public trading. Wealthsimple's 2025 product event added zero fee options, real gold, and private market portfolios. Wealthsimple's Fey acquisition added AI research and trading tools to the roadmap.
DEX trading adds another access layer. Clients can use one app for listed securities, crypto, IPO access, options, gold, private market portfolios, and now on-chain token trading.
Most clients won't need millions of tokens. The acid test is whether the app can make on-chain trading simple enough to try without making the risks feel smaller than they are.
One path is regulated centralized crypto access, where platforms list a smaller set of assets, hold assets through custodial arrangements, follow dealer rules, and provide clearer investor protections. Canadian crypto regulation has pushed platforms toward stronger custody, registration, and operating controls.
The other path is on-chain access, where users reach a broader token universe but also take on more responsibility for token risk, wallet access, tax tracking, execution, and irreversible transactions.
The beta sits between those paths. It keeps the user inside a mainstream Canadian app, but the assets trade through decentralized markets and sit in a self-custody wallet. That's different from both a traditional crypto exchange and a fully independent DeFi wallet.
Wallet usability becomes a core feature. Token risk intelligence becomes part of the trading interface. Slippage controls, routing quality, transaction monitoring, tax tooling, scam detection, and user education become operating requirements rather than extras.
Those areas connect directly to NCFA's Financial Innovation Map, including self-custody wallets, retail digital asset access, token risk analytics, on-chain finance, digital identity and trust, and compliance technology.
The opportunity isn't only trading more tokens. It's building the trust, data, user experience, and risk tools that let mainstream investors interact with on-chain markets without pretending those markets are safe by default.
If mainstream investing apps make self-custody DEX trading feel simple, will the next phase of retail crypto adoption depend more on token access or risk intelligence?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Crypto, Wealthtech, Capital Markets And Funding, Fintech And Innovation

On June 30, 2026, Webull Canada Crypto announced it will begin offering cryptocurrency trading after receiving approval from the Canadian Investment Regulatory Organization.
The approval gives Webull another asset class inside its Canadian investing platform, which already supports U.S. and Canadian stocks, ETFs, options, margin accounts, cash accounts, TFSAs, and RRSPs through Webull Securities Canada.
Beta access for selected clients is expected to start soon, with a wider rollout planned in the coming weeks. Webull says the crypto experience will include 24/7 trading for assets such as Bitcoin, Ethereum, Solana, XRP, Cardano, and Litecoin.
This is another regulated online brokerage aligning digital assets among the same customer experience as traditional investing.
Webull Canada Crypto Limited is regulated by CIRO. Webull Securities Canada Limited is also regulated by CIRO and is a member of CIPF.
That structure is important because crypto trading and traditional securities accounts don't carry the same investor protections. Webull's disclosure says crypto assets are not protected by CIPF, although CIPF protection may be available for eligible cash held in a crypto trading account, subject to applicable limits and policy terms.
The approval arrives after Canadian regulators spent several years moving crypto platforms toward dealer registration and CIRO membership, custody expectations, risk disclosure, and stronger client asset controls.
Regulated access is becoming the path for retail crypto distribution in Canada.
When Webull expanded brokerage services to Canada in early 2024, the initial story was low cost access to Canadian and U.S. listed equities.
The platform has since expanded around commission free trading, advanced charting, market data, options access, registered accounts, and now crypto.
Webull is building toward a multi asset retail investing platform where users can fund accounts, monitor portfolios, review reporting, and trade across asset classes without leaving the ecosystem.
Crypto increasingly looks less like a standalone destination and more like another investing capability inside regulated financial apps.
Canadian online brokers used to compete heavily on commissions, execution, research tools, and account access. In 2026, competition is about platform depth as investors want fewer disconnected accounts. Platforms want more customer activity, better retention, more data, and a wider share of the investor relationship, and eventually more personalized portfolio features.
Webull is entering a market where Wealthsimple already combines investing, crypto, cash, tax, and other financial services. KOHO adding regulated crypto trading inside its money app flashing the same pattern from a consumer finance angle.
The Canadian crypto market has gone through enforcement, registration pressure, custody scrutiny, stablecoin restrictions, and platform exits. Yet regulated distribution keeps expanding.
Canada hasn't treated retail crypto as an unregulated free for all. It also hasn't eliminated retail access. Oversight of the market is evolving toward regulated firms, clearer disclosures, tighter custody controls, and platforms that can operate within securities rules.
Webull's entry adds another regulated access point for Canadian investors and increases pressure on every platform that wants to be a primary investing destination.
The approval gives Webull permission to compete, but it doesn't guarantee adoption.
Crypto also brings higher volatility, suitability questions, security expectations, and investor education demands. A smooth user experience can't hide the risk profile of the asset class.
The advantage for Webull is that crypto can now be offered alongside the rest of its investing platform. The challenge is that investors will compare the experience not only with crypto exchanges, but with every brokerage and fintech app trying to become the main place Canadians manage investments.
Crypto trading platforms moving toward CIRO oversight shows how Canadian regulation is reshaping digital asset distribution.
Crypto custody rules are becoming a core operating issue for dealer members and digital asset platforms.
KOHO's regulated crypto rollout shows digital assets moving into broader consumer finance platforms.
Tokenization becoming a measurable business shows how digital assets are moving deeper into regulated capital markets infrastructure.
NCFA's Financial Innovation Map tracks digital assets, wealthtech, brokerage competition, capital markets infrastructure, custody, and investor access opportunities.
If every major investing platform eventually offers stocks, ETFs, options, registered accounts, and crypto, what becomes the next competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026
image: Magnific/DC Studio
When a province opens a private online gambling market, the headlines tend to chase the money: tax points, operator counts, and the size of the prize. The quieter story, and the one that matters more to the people who actually log in, is how the rules try to keep play from sliding into harm. Alberta's shift to a regulated online casino market is, underneath the commercial framing, a player-protection project. The design choices that decide whether a customer can set a hard deposit cap, lock themselves out across every site at once, or get flagged before a bad week becomes a worse one are buried in standards documents, not press releases.
That angle fits readers who follow how Canadian regulation, payments, and consumer safeguards lock together rather than chasing the latest welcome offer. The interesting question is not which brand has the loudest promotion. It is whether the protections written into the law and the regulator's standards are strong enough to hold once real money starts moving through licensed platforms.
Plenty of attention has already gone to who is lining up to operate. Data and comparison publishers such as Lineups keep running directories of the online casino options in Alberta, which gives outside observers a useful map of which brands are entering under the new framework. This piece takes the other side of that map and audits the safeguards instead: what each protection is meant to do, how it functions in practice, and who carries the duty to enforce it.
Alberta is not inventing online gambling. Residents have placed bets through offshore and grey-market sites for years, usually with no Canadian oversight, no local self-exclusion option, and no recourse when something went wrong. The case for a regulated market rests less on novelty and more on control. Once play happens on licensed platforms, the province can attach conditions to it: verified identity, mandatory limit tools, a shared exclusion list, and a regulator with the power to pull a license.
So the honest way to read this market is as a safeguards audit. A new framework is only as good as the protections it forces operators to build and the body willing to test them. The rest of this article walks each guardrail in turn, asks how it is supposed to work, and names the party on the hook when it fails. That structure matters because responsible-gaming language is easy to print on a homepage and hard to operate at scale.
Alberta split the job in two, which is a useful tell about how the province thinks risk should be managed. The Alberta Gaming, Liquor and Cannabis commission, known as AGLC, is the regulator. It registers operators and suppliers, writes and publishes the standards, audits compliance, and runs the centralized self-exclusion system. A separate body, the Alberta iGaming Corporation, holds the commercial agreements that operators need before they can legally take a bet in the province.
The point of separating the regulator from the conduct-and-manage entity is to keep the referee away from the revenue. The body chasing market growth is not the same body deciding whether an operator broke the rules. For a consumer-protection reader, that division is one of the more reassuring features of the design, because it reduces the pressure to look away from a profitable but non-compliant brand. It is also the structure the regulator can point to when a customer complaint needs an independent path that does not run through the operator's own support desk.
This dual model echoes the approach Ontario used when it launched its commercial market in 2022, which has since registered dozens of operators. Alberta watched that rollout closely and borrowed the parts that worked while trying to tighten the parts that drew criticism, including how exclusions and advertising are handled.
The safeguard with the most practical weight is the centralized self-exclusion program, and it is meant to be live from the first day of the regulated market. The mechanics are simple to describe and surprisingly hard to deliver. A person who wants to stop signs up once, and the exclusion then applies across every licensed online platform in the province at the same time. Timeframes run from six months to permanent, with options in between.
Compare that to the offshore status quo, where excluding yourself from one site does nothing on any other. Under the old arrangement, a person in a bad spiral could close one account and open three more by lunchtime. A shared list closes that gap, at least within the licensed perimeter. The regulator operates the program, and operators are required to integrate with it as a condition of registration, which is what turns a good intention into an enforceable obligation rather than a marketing badge.
The honest caveat is that a self-exclusion list only covers the sites inside it. A determined person can still reach unlicensed offshore platforms that ignore Alberta entirely. That limit is not a flaw in the design so much as a boundary on what any single province can reach, and it is one reason the market opening is paired with messaging that steers players toward licensed sites in the first place.
Self-exclusion is the emergency brake. The day-to-day controls are the limit tools every licensed operator has to offer from launch. The required set covers deposit limits, spending limits, and session time controls, plus regular activity statements that summarize a player's history so the picture is harder to ignore. The design logic is that most harm does not arrive as a single dramatic event. It accumulates quietly across many ordinary sessions, and friction introduced early is cheaper than intervention introduced late.
Limit tools work best when they are easy to set and slow to loosen. The detail that matters is the direction of friction: tightening a limit should take effect quickly, while raising one should carry a cooling-off delay so a heated moment cannot instantly undo a careful decision. Activity statements add a second layer by putting real numbers in front of a player who might otherwise round their losses down in their own memory. None of this stops a person who is determined to chase, but it narrows the path and creates record-keeping the regulator can later inspect.
For an audience that thinks about product design and payments, these controls are essentially consumer-finance guardrails applied to entertainment spending. They borrow the same logic as deposit caps and spending alerts in digital banking, and they live or die on the same question: are they switched on by default and built into the flow, or buried three menus deep where almost no one finds them.
The audit is easier to read as a table. Each row pairs a protection with how it is meant to operate and the party responsible for making it stick.
| Safeguard | How it works | Who enforces |
| Centralized self-exclusion | One sign-up blocks access across every licensed site, from six months to permanent | AGLC operates the list; operators must integrate |
| Deposit and spending limits | Player-set caps with fast tightening and delayed loosening | Operators build the tools; AGLC sets the standard |
| Session time controls | Reminders and limits on continuous play length | Operators implement; AGLC audits |
| Activity statements | Periodic summaries of deposits, wagers, and net results | Operators generate; player reviews |
| Identity and age verification | Account checks confirm the customer is of legal age and who they claim to be | Operators run checks under AGLC rules |
| Intervention duties | Staff and systems flag signs of problem play and act on them | Operators monitor; AGLC can sanction |
| Independent accreditation | Third-party review of responsible-gaming programs | Responsible Gambling Council |
| Advertising limits | Restrictions on inducements, targeting, and athlete imagery | AGLC writes and enforces the rules |
The pattern in that final column is the point. Almost every safeguard depends on a division of labor, where the operator builds and runs the tool while the regulator sets the floor and keeps the power to punish a brand that cuts corners. Protections without an enforcer are suggestions, and the structure here is built to avoid that trap.
For a fintech-minded reader, the most underrated safeguard is the one that happens before a single game loads. Verified identity and age checks are the gate. A licensed operator has to confirm that the person opening an account is a real, of-age resident rather than a minor borrowing a card or a fabricated profile. That single requirement does more quiet work than most flashy responsible-gaming features, because it anchors every later protection to a confirmed person rather than an anonymous login.
The payments trail extends that anchor. When deposits and withdrawals run through regulated channels, the money becomes traceable, limits become enforceable against a verified account, and patterns become visible. A customer who suddenly raises deposits and plays at odd hours leaves a record that a monitoring system can read. The same plumbing that supports anti-money-laundering checks also supports harm-reduction, since both depend on knowing who is transacting and being able to see the shape of their activity over time.
This is where Alberta's market intersects with the broader push for safer digital finance. The tools are familiar to anyone working in payments or regtech: identity proofing, transaction monitoring, and configurable limits. NCFA's own explainer on how Canadian online casino regulations work sets out how these checks, betting limits, and help resources fit into the national context, which is useful background for anyone weighing Alberta against other provinces. Applying the tools to gambling does not require new invention so much as honest implementation, and the regulated framework is what forces that implementation to be more than a checkbox.
The framework does not leave the burden entirely on the player to ask for help. Licensed operators carry a duty to look for signs of problem gambling and to act on what they find, rather than waiting for a customer to come forward. In practice that means behavioral monitoring: flagging sharp escalation in deposits, chasing patterns, marathon sessions, and other markers that research links to harm, then triggering an intervention such as a message, a prompt to set a limit, or a referral to support.
Active monitoring is the difference between a passive set of tools and a system that reaches toward people who would never click a help link on their own. The people most at risk are often the least likely to self-identify, so a safeguard that depends on the player raising a hand will miss them. By making intervention an operator obligation, the standards shift part of the responsibility onto the business that profits from the activity, which is the correct place for it to sit.
The unavoidable tension is that the operator is being asked to gently slow down its own best customers. That conflict of interest is exactly why an independent regulator with audit powers and an outside accreditation body both sit in the structure. Trust-but-verify only works if someone is actually verifying.
One more layer sits above the operator's own programs. The Responsible Gambling Council, a long-standing Canadian non-profit based in Toronto, runs an accreditation program that reviews whether a gambling operation actually meets recognized responsible-gaming standards rather than just claiming to. Independent review is what separates a genuine program from a glossy policy page, because the reviewer has no stake in the operator's revenue and no reason to grade on a curve.
Bringing an external standard into the framework matters for credibility. A regulator can write rules and audit against them, but a third-party accreditation adds a second set of eyes with its own published criteria. For consumers, the practical value is a signal they can read from outside the company: a program that has passed independent review has at least been measured against something firmer than its own marketing.
Safeguards inside the product only help people who are already playing. The advertising rules try to control how many people get pulled in and how aggressively. Alberta's standards restrict where operators can promote inducements and bonuses, generally limiting them to a brand's own site or to direct marketing that a player has explicitly consented to receive. Operators are also barred from targeting minors, high-risk individuals, and vulnerable groups.
One detail drew particular notice: advertisements cannot feature current or retired athletes. That choice is a direct response to a complaint heard across several markets, where celebrity and athlete endorsements were seen as normalizing betting for younger audiences who follow sports. Pulling familiar faces out of gambling ads is a blunt instrument, but it reflects a view that the supply of temptation deserves regulation alongside the tools that manage demand.
A fair audit ends with the gaps, not a victory lap. None of these safeguards eliminate harm, and pretending otherwise would undercut the whole exercise. The centralized exclusion list only governs licensed sites, so the offshore market remains a leak in the wall. Limit tools depend on default settings and honest design, and a tool that is technically present but practically hidden protects almost no one. Intervention duties ask operators to act against their own short-term incentives, which is why ongoing audits matter more than launch-day promises.
There is also the simple reality that regulation lags behavior. New payment methods, new game formats, and new marketing channels will test the rules faster than the rules can be rewritten. The honest verdict on Alberta's market will not come from the standards as written in 2025 and 2026 but from how seriously they are enforced two and three years on, when the novelty has worn off and the pressure to relax inconvenient rules has set in. A framework like this is best judged by its worst enforcement case, not its best brochure.
Anyone who wants to see how the entry bar was actually built can read this legal analysis of Alberta's Bill 48 iGaming framework, which lays out the registration structure and consumer-protection duties that form the practical floor every licensed brand must clear before taking a bet. The Alberta model is one experiment among several, and the provinces are quietly learning from each other's mistakes.
The takeaway is not that the new market is risk-free. It is that a regulated market with verified identity, a shared exclusion list, mandatory limit tools, intervention duties, and an independent regulator is a meaningful upgrade over an offshore status quo that offered none of those things. The safeguards are real. Their value depends entirely on whether the bodies named in that enforcement column keep doing the unglamorous work of checking.
When does Alberta's regulated online casino market open?
The province set a launch for its competitive online gambling market in 2026, with the legal foundation laid by legislation passed in 2025. Exact timing has shifted during the rollout, so the safest approach is to check the regulator's current guidance rather than rely on a date quoted in an older article.
Can I exclude myself from every Alberta site at once?
Yes. The centralized self-exclusion program is designed so a single sign-up applies across all licensed online platforms in the province at the same time, with durations from six months up to permanent. This is a deliberate improvement over excluding yourself from one site, which previously had no effect on any other.
What responsible-gaming tools are operators required to offer?
Licensed operators must provide deposit limits, spending limits, and session time controls from launch, along with periodic activity statements that summarize a player's history. They are also required to verify identity and age and to monitor for signs of problem gambling rather than waiting for players to ask for help.
Are online casinos legal everywhere in Canada now?
No. Gambling regulation in Canada is provincial, so the rules differ by province, and a framework like Alberta's does not change the law elsewhere. Several provinces still rely on a single government-run platform, while others, including Ontario and now Alberta, have opened competitive private markets under their own conditions.
Where can someone in Alberta find gambling-harm support?
Alberta's GameSense program and the Alberta Health Services Addiction Helpline offer free and confidential support around the clock. Licensed operators are also required to surface responsible-gaming resources and self-exclusion options directly within their platforms, so help is reachable from inside the account rather than only through an outside search.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016