





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 17, 2026 | NCFA Market Activity | Payments And Money Movement, Embedded Finance, Competition And Market Structure
On July 15, 2026, Mastercard launched Wallet Services, a development package that helps banks, fintechs and digital businesses add contactless payments to their own iOS and Android apps. Mastercard supplies the software development kits, Secure Element applet and tokenization through Mastercard Digital Enablement Service.
The product reduces work that previously required separate operating system integrations, security approvals and EMVCo certification. Mastercard says its software kits are available wherever Mastercard Digital Enablement Service operates, covering more than 200 countries and territories. Several banks are already building with the product, although Mastercard hasn’t named them or confirmed their launch markets.
A bank can now keep tap to pay inside mobile banking instead of sending customers to Apple Wallet or Google Wallet. Payments can sit beside card controls, rewards, instalments, merchant offers and account data. Mastercard gains another role beneath the customer interface even when the issuer owns the app.
Apple created the opening. With iOS 18.1, approved developers gained access to the iPhone Secure Element and near field communication functions for contactless transactions. Canada joined the first group of supported markets. Developers can also ask users to select another app as the default contactless wallet.
Access still comes with conditions. Developers need an Apple commercial agreement, an entitlement, security approval and payment of associated fees. Apple permits more competition while retaining control over device permissions and the economics of iPhone access.
Mastercard packages that access into a bank ready product. Push provisioning already lets issuers send cards into Apple Wallet or Google Wallet. Wallet Services goes further because the bank or fintech app can become the contactless payment interface.
That fact is at the centre of competition concerns around Apple Wallet. Banks and payment companies could issue cards, but Apple controlled how contactless payments worked on the iPhone. Opening NFC access gives them a way to build their own wallet experience. Mastercard now provides the software and tokenization needed to do it.
Issuer control improves, but independence remains limited. Mastercard still manages the payment token and credential process. Apple still decides which iPhone apps receive access. Consumers must also choose the bank app over wallets they already use for cards, tickets, transit passes and identification.
Wallet Services fits a wider pattern of payment networks opening access while tightening control. Banks receive a new route to the customer, but Mastercard and Apple retain authority over the credential, security standards and device access that make the wallet work.
Mastercard benefits from that split. Banks can own more of the customer experience while Mastercard supplies tokenization, security and cross platform integration. The network can strengthen its position even when its brand isn’t visible at checkout.
Apple Wallet and Google Wallet retain the strongest consumer distribution. Visa can answer with its own tokenization and issuer software. Paze follows a different model. The bank consortium wallet focuses on online checkout, not device level contactless payments, though it reflects the same effort to retain wallet distribution. Independent providers such as Thales also sell branded NFC wallet technology to banks and fintechs.
Mastercard’s advantage comes from combining network credentials with the wallet build. Its weakness comes from the same design. Banks with Visa, Interac and Mastercard cards may not want separate wallet logic for each network. A single network product works more cleanly for a fintech running one Mastercard card program than for a large Canadian bank serving customers across several payment schemes.
Canada offers an immediate test because Apple already permits third party NFC access here. A bank could connect contactless payment with credit card controls, loyalty, fraud alerts and merchant offers inside mobile banking. A fintech could combine a prepaid or credit product with budgeting, expense management or instalment features.
The customer use case is less certain. Apple Wallet and Google Wallet already give users one place for several cards and services. A bank owned wallet needs a clear reason to replace that convenience. Better rewards, stronger controls or a more useful account experience could help. Branding alone won’t.
Coverage will shape adoption as well. Mastercard’s release focuses on Mastercard credentials. Canadian consumers often carry Visa credit cards and Interac debit cards alongside Mastercard products. Banks will need to know whether Wallet Services can exist inside a wider wallet or whether each network requires separate development and commercial terms.
Mastercard hasn’t disclosed pricing, data ownership, merchant data access, fraud liability or support for non Mastercard credentials. It also hasn’t identified the first banks or launch markets. Those omissions limit any claim that the product will change wallet competition quickly.
The technology lowers a real build barrier. Commercial success now depends on whether banks can assemble complete wallets and give customers a reason to use them.
Can banks turn contactless payments inside mobile banking into a better customer experience, or will Apple and Google remain the default because one wallet already serves every card?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 7, 2026 | NCFA Story Intelligence | Payments And Money Movement, SME Finance And Business Banking, Capital Markets And Market Infrastructure
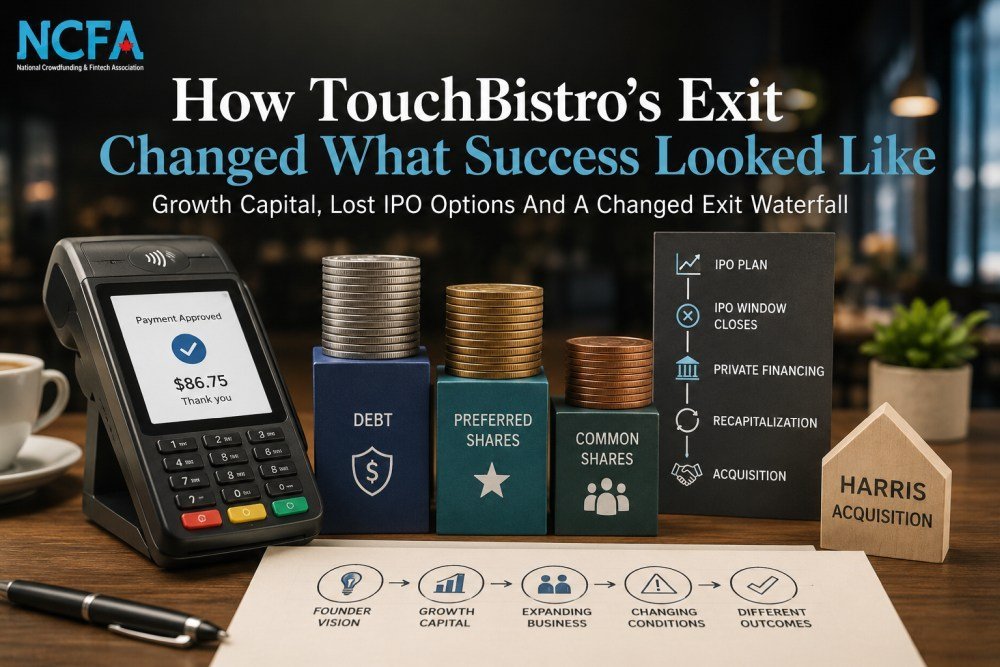
On July 7, 2026, Harris acquired TouchBistro, a Toronto restaurant technology and payments company whose point of sale, payment processing and management products serve more than 16,000 restaurants across over 100 countries. Harris, part of Constellation Software, didn’t disclose the purchase price.
The Globe and Mail later reported that Harris paid $100 million. Reporter Sean Silcoff said the transaction followed a December 2025 recapitalization that converted Francisco Partners’ debt into equity, gave the lender control of the board and reduced earlier shareholders to a minority position. He also reported a nine figure loss for OMERS and no recovery for employee common shares.
Those reported outcomes make the acquisition look like a failed exit. The operating record is more complicated. TouchBistro spent about 15 years building a global restaurant technology business, processing billions of dollars in transactions, expanding its product suite and surviving a pandemic that shut down much of its customer market.
The business had value. Its financing required more.
TouchBistro found a specific operating problem. Founder Alex Barrotti built the original product around restaurants that wanted mobile ordering, table management and point of sale software on an iPad. The narrow industry focus helped TouchBistro expand into reservations, loyalty, staff scheduling, online ordering, accounting, payments and restaurant management.
Investors saw a larger opportunity. Restaurants represented a fragmented global market with recurring software revenue, payment volume and room to sell several products into the same customer account. Venture backing could accelerate product development, international sales and acquisitions before larger competitors controlled the category.
BDC joined the shareholder base. TouchBistro’s 2017 Series C included BDC IT Venture Fund, giving the company backing from a federal Crown corporation alongside private investors. That public investment supported a Canadian company competing internationally, but it also carried a mandate to produce a financial return.
The C$72 million Series D raised the ambition. In June 2018, OMERS Ventures and JPMorgan Chase led the round, with BDC and existing investors participating. TouchBistro said it would expand research, enter more markets and double its workforce.
OMERS placed a major institutional bet. In September 2019, OMERS Growth Equity led a C$158 million Series E and invested C$85 million itself. Barclays Bank, RBC Ventures and BMO Capital Partners joined the round, while BDC, JPMorgan Chase and other existing investors participated.
The company had scale to support the pitch. OMERS said TouchBistro served more than 16,000 restaurants in over 100 countries and processed more than US$11 billion annually through its payment system. The financing supported product development, acquisitions, international expansion and hiring.
A public listing offered several advantages. It could provide new investment, establish a market price, give investors a route to sell shares and support acquisitions with public equity. It could also preserve TouchBistro as an independent Canadian company if public investors accepted the growth case.
There was no guarantee the market would cooperate. An IPO would require reliable growth, audited financial performance, predictable recurring revenue and public investor demand. The company never named an intended exchange in the sources reviewed, so the record doesn’t establish that TouchBistro rejected a Canadian listing.
The founder stepped out of the CEO role. In April 2021, Barrotti handed leadership to board chair Samir Zabaneh. He described the transition as a new stage requiring experience operating large global companies, not as a forced departure.
The operating job had changed. TouchBistro now needed to recover from the pandemic, control spending, expand payments revenue and compete with larger rivals. Leadership that was suited to founder led expansion wasn’t automatically suited to the next operating and financing phase.
A financing round doesn’t just fund the next stage of growth. It can quietly redefine which exits remain possible.
Private financing replaced the expected public route. In November 2022, Francisco Partners supplied C$150 million for product expansion, core services and acquisitions. Francisco Partners includes TouchBistro within its credit and structured solutions portfolio.
The financing bought time under new conditions. Equity absorbs losses until an exit. Debt introduces repayment, covenants, maturity dates and senior claims. Convertible instruments can later become ownership. The public announcement didn’t disclose the complete instrument, pricing, covenants or conversion terms.
The category kept getting harder. TouchBistro competed against Toast and other restaurant technology firms with their own payments, software, data and distribution advantages. Investment could finance products and acquisitions. It couldn’t guarantee that TouchBistro would outgrow a larger rival.
Cost discipline carried its own tradeoff. Silcoff reported that Zabaneh reduced costs while growth weakened. That doesn’t prove the reductions caused the later outcome. It shows the conflict management faced: preserve cash, invest against a larger competitor or raise more money into a weaker market.
A reported recapitalization reordered the company. In his public summary of the Globe investigation, Silcoff reported that Francisco Partners converted debt into equity in December 2025, took control of the board and reduced existing shareholders to a minority position.
The transaction wasn’t publicly announced at the time. TouchBistro’s full cap table, preference stack, debt balance and sale waterfall remain private. The reported control change explains the direction of the outcome, but it doesn’t provide enough information to calculate each shareholder’s recovery independently.
Venture investors judged the result against the money invested. A fund can’t treat survival, employment or customer continuity as its primary return. It needs distributions large enough to offset losses elsewhere in the portfolio and return money to its own investors.
Harris judged the operating business differently. Constellation Software and its operating groups acquire vertical software businesses that can serve specialized customers for years. They can focus on recurring revenue, customer retention, product depth, pricing and cash generation without needing a venture scale exit.
TouchBistro doesn’t prove that founders should reject venture capital. The company used institutional backing to build products, enter international markets, acquire technology and compete in a category that required significant investment. A smaller financing plan may have produced a smaller business or allowed a larger competitor to overtake it sooner.
It does show why the amount raised can’t be separated from the type of company being built and the outcomes its market can realistically support. Every round assumes a future. Higher valuations require more growth. Preferred investment adds priority. Debt adds fixed obligations and control rights. A delayed IPO, weaker market or missed target can leave a founder running the same company under very different economics.
Canada’s debate often starts with whether founders can access enough money. The early stage funding funnel is narrowing, and Canadian companies still face a limited pool of domestic investors capable of leading large rounds. Those are genuine constraints.
TouchBistro raises the question on the other side. Once money becomes available, is it structured around the company’s likely growth, customer market and exit routes? Canada’s longstanding need for flexible growth financing includes equity, debt and hybrid products. Flexibility only helps when founders and boards understand what each instrument can claim later.
Founders can’t control pandemics, public market windows or every competitive threat. They can model the consequences of a financing before signing it.
What sale price clears the preferences?
What happens if growth takes twice as long?
Which covenants transfer control after a missed target?
Could the company accept a strategic offer without leaving common shareholders with nothing?
Does the business have a credible route to the outcome its investors require?
Those questions aren’t pessimistic. They’re part of building the company.
TouchBistro built software that restaurants still use. Harris acquired its products, customer relationships and industry expertise. The work continues under a Canadian software owner.
The financial outcome followed a different logic. The expected IPO never arrived. Private credit reportedly gained control. Earlier shareholders lost priority. The eventual sale appears to have preserved the operating business without satisfying the venture investment behind it.
That is the distinction founders need to see before the next round, not after the sale.
A valuable company isn’t automatically a successful venture investment. A large exit isn’t automatically a founder win. Investment that opens the next stage can quietly close outcomes that once looked available.
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 15, 2026 | NCFA Market Activity | Cross Border Payments And FX, Banking And Credit, Digital Assets

On July 14, 2026, Flex raised US$70 million in a Series B1 led by Halo Fund and launched Flex Global, a cross border financial platform for internationally active business owners. The service combines multi currency accounts, payments, cards, private credit and stablecoin settlement while keeping the underlying digital asset infrastructure out of the customer experience.
The financing came six months after Flex raised a US$60 million Series B. Flex says it has now secured US$180 million in equity and US$300 million in debt. Reuters reported that the new round valued the company at about US$1.2 billion, based on information from a person close to the transaction. Flex didn’t disclose the valuation.
Flex Global extends the company’s private credit, business finance, personal finance, payments and financial operations platform into international accounts, currency conversion and stablecoin settlement. Flex says the service will support 32 currencies across more than 100 countries.
The customer doesn’t need to understand or manage the digital asset infrastructure. Stablecoins operate beneath a conventional financial interface while the business owner sees accounts, balances, payments and financial tools.
That design addresses a persistent gap between stablecoin payment potential and business adoption. Most companies aren’t looking for a token product. They want faster settlement, usable currencies, predictable access to funds and one record of what happened.
Flex is trying to make the underlying rail invisible while expanding the amount of the owner’s financial relationship it can control.
Flex Global is designed to let business owners hold and transfer value across markets through the same platform they use for credit, cards, payments and financial operations.
Stablecoins can provide a common settlement asset between two financial endpoints. The platform still needs to handle customer verification, currency conversion, transaction monitoring, liquidity, local payout access and reconciliation.
That operating bundle is more important than the token transfer itself. NCFA has seen the same model in Levl’s connection between bank and stablecoin rails, where the commercial product joins digital settlement with accounts, payment access and financial infrastructure.
Flex applies that mechanism to a direct owner relationship rather than selling infrastructure to another bank or payment company.
The customer value proposition is straightforward. An internationally active owner may currently use separate providers for business accounts, cards, foreign exchange, payments, working capital, expense management and personal finance. Flex wants to consolidate those products around one customer record and one financial interface.
Flex targets profitable middle market business owners whose needs often sit between small business banking and institutional private banking.
Founder and CEO Zaid Rahman has described the customer group as owners of businesses earning millions or tens of millions of dollars in annual revenue. They may manage several companies, international suppliers, personal investments, employees and private credit needs without the finance department of a large corporation.
The firm says it has onboarded a few thousand customers and is growing at roughly four times its prior year level. Reuters reported a nine figure annualized revenue run rate. The company plans to increase its team from about 110 people to more than 200 by the end of 2026.
Its platform brings several financial functions into the same commercial relationship:
Private credit gives Flex a different economic position from a payment application that earns mainly from transaction fees. The company can potentially earn across lending, interchange, payment services and software while using one product to distribute another.
Flex’s AI products support that integration. Beacon is positioned as a financial intelligence tool for owners, while the wider platform is designed to use customer financial data across credit and operating workflows.
Public disclosures don’t provide enough information to determine how much work its AI systems complete independently, how human review is applied or whether the tools improve financial outcomes. Those questions become more important as Flex handles more credit and payment activity.
The competitive group spans several fintech categories. Flex overlaps with:
The strategic difference is customer scope. Many competitors specialize in one financial job. Flex is trying to serve a narrow customer segment across several jobs.
That can improve distribution economics because the company doesn’t need to acquire a new customer for every product. It can also create operating complexity as more credit, payment, compliance and personal finance responsibilities sit inside one interface.
Stablecoin infrastructure is finding its clearest commercial role where conventional payment systems are slow, fragmented or unavailable outside banking hours.
Cross border business payments fit that profile. A company may need to coordinate foreign exchange, correspondent banks, payment cut off times, local accounts, compliance checks and reconciliation before the recipient can use the funds.
A stablecoin can shorten the settlement portion. It doesn’t complete the entire payment job.
The Noah and Cedar trade payment model shows how compliance, virtual accounts, foreign exchange and payout access must operate around stablecoin settlement before businesses have a usable product.
Flex is assembling similar functions inside an owner finance platform. The user may never hold a private key or choose a blockchain. Stablecoins become one part of treasury and payment execution rather than a separate asset decision.
That abstraction has commercial value because most businesses care about cost, speed, reliability and access to funds. They don’t necessarily care which settlement system transfers value between providers.
The model also creates dependencies. Flex must coordinate banking partners, stablecoin issuers, payment networks, liquidity providers and local market access. Customers will need clear information about where funds are held, which entity provides each service and what happens when a payment can’t be completed.
Canada’s regulatory position is becoming clearer after the enactment of its federal stablecoin framework. Implementation still depends on regulations, Bank of Canada supervision and alignment with payments, AML, securities and prudential requirements.
Canadian founders with international operations often assemble banking, cards, currency conversion, lending and treasury through separate providers. That challenge is consistent with Canada’s cross border interoperability gap, where strong domestic infrastructure hasn’t yet produced equally strong international payment performance.
Flex Global shows what a consolidated alternative could look like. It also creates a competitive question for Canadian banks and fintechs. Who owns the customer relationship when the payment rail becomes invisible and the platform spans both the business and its owner?
Flex is betting that middle market owners form a concentrated and valuable segment that conventional fintech platforms haven’t served as a complete financial category.
Cross border payments can become an entry point for accounts, cards, treasury, private credit and personal finance. Each product can supply more operating information and make the wider platform harder to replace.
The tension is execution. A product covering more than 100 countries can’t rely on one uniform banking, regulatory or liquidity structure. Availability may differ by customer location, business type, payment corridor, currency and partner.
Flex has raised enough capital to expand the platform, hire staff and acquire customers. The next proof is whether it can deliver reliable international financial services without passing the complexity underneath them back to the customer.
Will internationally active business owners consolidate banking, payments, credit and personal finance with one platform, or continue separating those services across specialized providers?
Zaid Rahman founded Flex to provide financial products for profitable middle market business owners whose business and personal needs often fall between small business fintech and institutional private banking.
FlexFinancial platform founded by Zaid Rahman
LaunchOwner focused financial products
Venture BackedInstitutional equity supports product development
United StatesProfitable middle market businesses
Business OwnersOwners with complex company and personal finances
Segment FocusPositioned between small business fintech and private banking
Flex began with a defined customer segment rather than one narrow product. That customer focus created room to add credit, payments, business finance and personal finance around the same owner relationship.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 15, 2026 | NCFA Market Activity | SME Finance And Business Banking, Embedded Finance, Payments And Money Movement, Competition And Market Structure
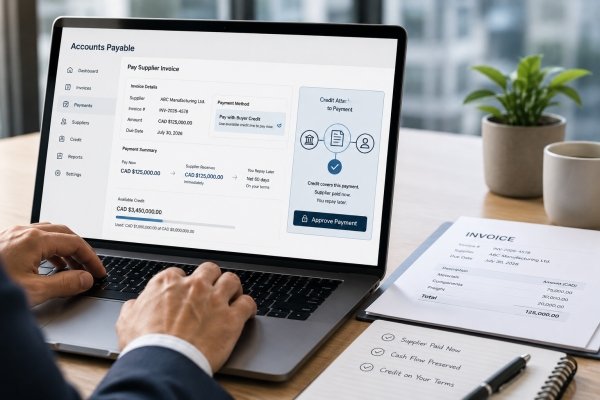
On July 15, 2026, Nasdaq Stockholm listed KEO Capital launched Workeo Canada, bringing a supplier payment and B2B working capital service to the Canadian market. Workeo lets businesses pay suppliers when an invoice is approved while extending their own payment terms to preserve cash flow. The service went live at the end of June with a Toronto team and a revolving senior loan facility of up to C$50 million from an undisclosed Big Six Canadian bank.
The product places credit inside the supplier payment decision. An approved buyer uses a revolving facility to pay an invoice or operating expense through Workeo. The supplier receives payment, while the buyer repays later under its credit terms.
That is more specific than combining payments and lending on one website. Workeo finances the buyer’s payable at the point of payment. The business doesn’t need to draw from a separate bank line, place the payment through another provider and reconcile both transactions afterward.
KEO is entering Canada with funding already attached to the operating model. That gives the company capacity to originate credit from launch rather than waiting to fund Canadian receivables from equity or offshore lending facilities.
Workeo connects buyers and suppliers through one account. Once approved, a business can use its revolving credit line to pay supplier invoices and operating expenses, extend its own payment terms and preserve cash for other needs.
The structure differs from invoice factoring. A factor generally advances money to a supplier against an outstanding receivable. Workeo primarily finances the buyer that owes the invoice. The supplier still receives payment sooner, but the credit relationship is with the purchaser.
It also differs from a standard line of credit. A conventional bank facility gives the company access to capital, but the borrower must manage the draw, supplier payment and repayment as separate steps. Workeo connects the financing to the underlying payment instruction.
The model is also different than corporate cards. Cards can extend payment time and simplify expenses, but they aren’t accepted for every supplier invoice and often require the balance to be repaid over a much shorter period. KEO hasn’t disclosed Canadian credit limits, repayment terms, pricing or underwriting requirements, so the practical advantage will depend on how those terms compare.
KEO says Workeo uses proprietary technology and blockchain infrastructure to support local payment execution. It hasn’t published enough technical information to establish which blockchain is used, how transactions settle or whether customers interact with that infrastructure directly. The payment and credit workflow is therefore more important to the Canadian launch than the blockchain claim.
The company targets midmarket and large corporate buyers in manufacturing, construction, logistics, wholesale distribution, professional services, retail and health care. It says services are available in Ontario, British Columbia, Alberta, Manitoba and Atlantic Canada, subject to provincial requirements. Quebec and Saskatchewan aren’t included at launch.
Canada offers substantial payment volume for a provider that can attach credit to commercial transactions. KEO cites more than C$9 trillion in annual domestic commercial payment value using Payments Canada data. That figure covers the value processed through several ACSS payment categories. It isn’t KEO’s addressable lending market, but it shows the scale of payment activity surrounding Canadian businesses.
The bank facility explains why KEO can launch the credit product and payment workflow together. Its Canadian subsidiary can borrow up to 80% against eligible receivables during an initial one year revolving period, with an automatic one year extension. The facility is priced at the Canadian Overnight Repo Rate Average plus about 300 basis points, or roughly 6.5% when KEO disclosed the agreement.
KEO estimates that the facility could support approximately C$375 million in annual billings. That's not booked volume or expected revenue. Actual performance will depend on customer demand, credit limits, portfolio turnover, defaults and the amount KEO draws.
The parent company guarantees KEO Canada’s obligations and must maintain at least US$60 million in tangible net worth. Those conditions show that the Canadian bank isn’t funding the portfolio without recourse to the listed company. They also make credit performance central to the economics. Losses, slower repayments or ineligible receivables could reduce the amount KEO can recycle through the facility.
KEO brings prior operating evidence. Workeo was developed by KEO World after its 2020 founding. A four year secured facility of up to US$500 million from Hayfin helped finance nearly US$1 billion in company reported credit volume, mainly in Mexico, before KEO repaid the facility in January 2026.
The company’s corporate structure also changed before the launch. Maha Capital completed its acquisition of KEO World in April 2026 and raised US$27 million through directed share issues. It then adopted the KEO Capital name and KEOC ticker in June. The transaction placed KEO World inside a Nasdaq Stockholm listed company with access to public capital and a larger balance sheet.
Canada is therefore part of a connected expansion sequence. Workeo proved credit volume in Latin America, repaid its original institutional facility, joined a listed company and secured a domestic bank line for its next market.
KEO enters an active Canadian market. It isn’t the first company to connect business spending, payments and credit.
Float’s working capital expansion combines business accounts, cards, bill payments and short term credit. Its product begins with company spending and cash management. Workeo begins with the supplier invoice and attaches revolving buyer finance to that payment.
Telpay’s acquisition of Notch connected supplier payments with receivables and cash flow software. Plooto also integrates accounts payable, accounts receivable and reconciliation. Neither publicly presents a revolving buyer credit facility attached to each supplier payment in the same way.
FundThrough’s invoice funding model addresses the opposite side of the transaction by advancing cash against supplier receivables. Banks provide lines of credit and treasury products, but often leave the business to connect financing with accounts payable operations.
KEO’s competitive position combines payment execution with credit for the buyer, funded through an institutional facility rather than customer deposits.
The commercial benefit is the SME operating relationship. Embedded working capital becomes more valuable when credit appears inside invoices, supplier payments and other operating workflows. A provider that finances the invoice can see when businesses pay, which suppliers they use and how quickly obligations are repaid. That data can improve underwriting, increase product use and make the payment account harder to replace.
Execution still needs proof. The C$50 million facility gives Workeo capacity. It doesn’t establish adoption. The next proof will come from originations, repeat use, credit performance and whether Canadian companies treat Workeo as a financing product or part of their daily payment operations.
Will Canadian businesses increasingly access working capital through the supplier payment workflow rather than managing credit and payments as separate services?
KEO entered Canada with domestic bank funding, Toronto operations and Workeo’s buyer financed supplier payment model. The launch tests the model under a different banking and regulatory structure.
Workeo CanadaOntario incorporated subsidiary · FINTRAC registered money services business
ExpansionToronto operations and five initial Canadian regions
Up To C$50MCanadian revolving senior facilityUp to 80% advance rate · CORRA plus about 300 basis points
5 RegionsOntario, British Columbia, Alberta, Manitoba and Atlantic Canada
Midmarket+Canadian corporate and enterprise buyers
Embedded Buyer FinanceCredit enters at the supplier payment instruction
Canada tests whether KEO can transfer an institutionally funded payment and credit workflow into another regulated market. The facility supplies capacity, but customer adoption, credit performance and repeat use will determine whether Workeo becomes part of daily business payments.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: July 14, 2026
Status: Strong
Organizations: Payments Canada, Bank of Canada, Wise Payments Canada, Float, KOHO, Paramount Commerce, Brim Financial, DoBusiness.com, Neo Financial, Meridian Credit Union, Tru Cooperative Bank, Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, Newton, XTM, UK HM Treasury
Payment networks are opening to more fintechs and payment service providers, but access is becoming more conditional rather than less controlled.
Canada’s expanded Payments Canada membership rules now allow eligible PSPs and provincial credit unions to enter a system once dominated by banks and a limited group of financial institutions. New members may apply to participate in the Real-Time Rail, contribute to Payments Canada governance and build services closer to national payment systems.
That doesn’t give every member the same operating position. Membership, system participation, exchange access, clearing, settlement and governance remain separate layers. Each comes with its own eligibility, technical, fraud, liquidity, safeguarding and supervisory requirements.
Canada has already started opening access across payments and financial data. Regulated non-bank firms can now enter formal membership and participation pathways instead of relying entirely on bilateral relationships with incumbent banks.
The operating model still has gates. Payments Canada membership makes a PSP eligible to apply for participation. It doesn’t automatically provide production access, a settlement account or relief from ongoing compliance. Canada’s approved RTR rules and access framework distinguishes direct settlement, agent settlement and service-provider roles, each with different economics and responsibilities.
Published standards can make entry more transparent and less dependent on institutional status. They can also increase the cost of integration, testing, fraud controls, liquidity management and continuous operations.
The evidence points to access and control developing together. Regulators and network operators are using common rules to admit more participants without requiring every entrant to hold a bank charter or decades of bilateral operating history.
Click each item to expand
Payments Canada admitted Wise Payments Canada, Float, KOHO, Paramount Commerce and Brim Financial after federal changes expanded membership eligibility to registered payment service providers.
The intake opened a formal route into Canada’s payment-system structure. It did not provide automatic production or settlement access.
By June 3, Payments Canada reported that 15 organizations had joined during 2026 following the expansion of its eligibility rules.
The wider intake shows that expanded membership is becoming an operating pathway rather than a one-time group of approvals.
Payments Canada admitted uSecure Escrow Solutions, operating as DoBusiness.com, as a PSP member on April 16, 2026.
The approval shows that access can extend beyond consumer fintech brands to specialized business payment providers.
Payments Canada has published a participation pathway for PSPs preparing to join the Real-Time Rail, Canada’s planned instant exchange, clearing and settlement system.
The pathway takes access beyond policy eligibility, although onboarding, certification and settlement arrangements still determine whether a firm reaches production.
Meridian Credit Union became the first provincial credit union admitted under the expanded membership rules, followed by other cooperative institutions in the 2026 intake.
The additions extend formal membership beyond fintech PSPs and bring more regional institutions into national payment governance and participation pathways.
Click each item to expand
Payments Canada distinguishes membership from participation in the Real-Time Rail.
This separation prevents membership totals from being treated as proof that every new member has equal operating access.
The approved RTR By-law and Rules establish the legal framework for exchange, clearing, settlement, payment finality and participant responsibilities.
Legal certainty gives prospective participants a clearer basis for investment while setting the conditions under which access can be used.
Registered PSPs must continue meeting Bank of Canada reporting, risk-management and safeguarding requirements under the Retail Payment Activities Act.
The framework replaces an informal access environment with continuing regulatory accountability.
The Bank of Canada ordered XTM to stop retail payment activity in February 2026 and later permitted a controlled restart under court-supervised monitoring.
The case shows that supervision can affect production access, customer funds and business continuity, not only regulatory filings.
The RTR framework combines ISO 20022 payment data with centralized fraud services and participant-level controls.
Common controls can support wider participation, but they also become part of the cost and technical standard for entry.
Limited direct settlement is developing as a middle layer between full sponsor-bank dependence and unrestricted central-bank account access.
The distinction determines how much control new participants gain over liquidity, counterparties and settlement economics.
The UK Payments Vision programme links future retail payment technology with decisions about governance, commercial roles, procurement and accountability.
The UK model confirms that modernizing payments is also a decision about who sets the rules, funds the system and controls access.
Canada has created formal payment system pathways for more organizations. The commercial effect will depend on how many new members complete onboarding, enter production and gain enough control to improve their products or economics.
Some PSPs may participate directly. Others may still rely on settlement agents, technical gateways or incumbent financial institutions. Those choices will affect liquidity, operating costs, fraud responsibilities and the speed at which new services can reach customers.
Governance will be another test. New members may have a voice in Payments Canada consultations and rules, but it is too early to know how much influence they will have over system priorities, liability, pricing and future access requirements.
The customer outcome is also unresolved. Wider participation could produce more choice, better payment products and stronger competition. It could also leave control concentrated among the institutions that provide settlement, connectivity, fraud services and access to customer accounts.
Published standards can replace closed institutional relationships with clearer entry requirements. They can also raise the cost of joining and operating. The result will depend on whether qualified new participants can build differentiated services and reduce reliance on incumbent intermediaries without weakening security or consumer protection.
Do you agree the evidence is strong?


Click Agree or Disagree. Your vote is recorded anonymously and aggregate results are tracked.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Payments Canada says Canada’s Real-Time Rail (RTR) By-law and Rules received all necessary approvals on June 30, 2026, take effect August 24, 2026, and support a planned Q4 2026 launch. RTR is Canada’s new real-time exchange, clearing and settlement system for instant, data-rich payments.
The approved Rules establish participant roles and the legal operating framework, but they do not provide automatic access. PSP participation can also require RPAA registration where applicable, Payments Canada membership, a direct or agent settlement model, ISO 20022 integration, centralized fraud services, testing, certification and continuous operations.
Coverage includes the RTR By-law, RTR Rules, public policies, PSP participation pathways, direct and indirect settlement, centralized fraud controls, ISO 20022, payment finality, testing, phased launch and the capabilities the framework can support.
Use this Regulatory Intelligence page to understand what is now approved, identify the operating path that fits your role, follow the dependencies behind each capability and open the official documents needed for implementation.
RTR is the result of a decade-long modernization effort, not a 2024 initiative. The journey includes early design work, vendor selection, missed launch targets, a 2023 delay acknowledgement, a 2024 program restart, legal consultation, rule approval and the current transition toward production.
This is the overview readers need before entering the detailed framework. It separates the changes now settled in the approved legal framework from the implementation work that still determines who can participate, how they connect and what they can offer.
The By-law and Rules establish the formal basis for payment-message exchange, clearing, settlement, participant roles, compliance, recourse and system operation. Implication: planning can proceed against approved rules rather than draft policy.
Canadian Payments Act changes and RPAA registration allow eligible PSPs to seek Payments Canada membership and RTR participation. Implication: eligibility opens the route; it does not grant automatic membership, direct settlement or production access.
Organizations may pursue direct settlement, use a settlement agent, build customer products through an RTR participant or provide connectivity and software services. Implication: control, cost, time and continuing obligations differ materially by pathway.
Direct settlement requires a Bank of Canada RTR settlement account; other participants may rely on a settlement agent. Implication: liquidity, funding, contracts, resilience and operating responsibility change with the settlement model.
Confirmation of Payee, Central Fraud Analytics, the Central Risk List and Central Fraud Reporting complement participant controls. Implication: firms must integrate, contribute data, make documented decisions and support continuous fraud operations.
Technical specifications, ISO 20022 mapping, security, testing, certification, operational readiness and 24/7 support remain production gates. Implication: time and cost now shift from rule uncertainty to execution readiness.
Choose the role you want to play, confirm whether RPAA registration applies, and map the Payments Canada membership, settlement, fraud, testing and 24/7 operating work that follows.
Start with the customer result you want to deliver. Then compare direct participation with partner, software, connectivity or managed settlement routes before committing to the highest-cost model.
Rule approval removes one source of uncertainty. The next signals are participant approvals, settlement agreements, certification, pricing, product launches, customer adoption and fraud performance.
Select any item to see what it requires, what it enables and where to go next. Follow the highlighted connections from legal authority and operating rules into participation, controls, customer use cases and infrastructure opportunities. For product nodes, the right panel also points to the numbered shared-rail functions shown directly below this map.
Select the role closest to the operating model being considered. The pathway below shows the sequence of gates, the regulatory and operating work that increases cost or time, what the route unlocks and where a lighter model may be available.
Move from the RTR rules into the distinct regulatory, implementation, competition and innovation questions that affect market entry and commercial deployment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
