




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 27, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Risk Compliance And Regtech, Wealth And Asset Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026).
Cross border payments are getting clearer operating standards for retail and SME use cases. Banks, payment firms, remittance providers, fintechs and SME platforms should watch how fee disclosure, FX transparency, delivery certainty and last-mile processing become competitive requirements.
The connection gives Singapore users direct access to Vietnam’s domestic QR acceptance network without requiring merchants to install separate terminals. Singapore becomes the fourth ASEAN market and sixth jurisdiction connected to NAPAS, with outbound payments from Vietnam to Singapore planned later in 2026.
Agentic payments are moving into live financial infrastructure. Banks, payment networks, merchants, PSPs, AI providers and fraud teams should watch how consent, authentication, agent identity and liability controls evolve for AI-initiated transactions, including the broader question of whether fintechs should design for people or AI agents.
Agentic commerce needs payment controls that work inside the buying flow. Merchants, payment networks, fintechs, issuers, fraud teams and AI platforms should watch how tokenized credentials, spend limits, approved categories, agent identity and audit trails define the next payment interface. NCFA's Financial Innovation Map tracks agent commerce infrastructure as an emerging opportunity.
Canada’s instant payments system now has the legal foundation needed for launch preparation. Banks, payment service providers, fintechs, merchants and compliance teams should track how RTR rules, access, fraud controls, ISO 20022 messaging and 24/7 operations change payment product design and competition.
Wholesale CBDC work is concentrating on settlement infrastructure rather than retail money. Central banks, banks, market infrastructure firms, custodians and payment providers should watch how tokenised settlement, securities delivery and cross border liquidity use cases shape the next phase of central bank money innovation.
Canada's retail payments regime is shifting from registration into active supervision. PSPs, fintechs, payment processors, compliance teams and investors should track how incident reporting, safeguarding information, annual reports and PSP Connect submissions become part of the operating cost of regulated payment activity.
Canada's open banking framework is entering the implementation phase. Banks, fintechs, payment service providers, credit unions and technology providers should prepare for accreditation, technical integration and operational requirements as consumer driven banking moves toward production. See NCFA's Open Banking in Canada opportunity brief for the market gaps, adoption signals and infrastructure questions this framework is meant to address.
Stablecoin payment firms are building through combined cryptoasset and e-money permissions. Fintechs, banks, treasury teams, payment providers and stablecoin issuers should watch how MiCA, EMI licences, IBAN access and euro stablecoin services define regulated market entry in Europe.
Regulated retail crypto platforms are adding on-chain access while changing how custody, disclosure, risk controls and investor responsibility work. Brokers, crypto platforms, wallets, regulators and compliance teams should watch how self-custody DEX trading inside mainstream apps affects token access, suitability controls, tax reporting and Canadian crypto regulation and investor safeguards.
The case combines a licensing exit with a failed liquidity transaction, withdrawal uncertainty and possible insolvency. Regulators and users can assess the effectiveness of the wind down through access to account records, withdrawal processing, financial disclosure and the treatment of unreturned balances. Canada’s registered crypto platforms operate under different rules. The same questions apply to custody, liquidity, capital, governance and orderly customer exits. NCFA’s comparison of MiCA and UK crypto rules explains how demanding authorization standards can favour firms with stronger operating infrastructure.
MiCA is becoming the operating gateway for institutional digital asset firms. Trading firms, custodians, prime brokers, exchanges, asset managers and compliance teams should watch how authorization under a harmonized EU framework expands regulated cross-border crypto services.
Retail investing is extending into onchain financial infrastructure. Brokers, crypto platforms, wallets, custodians, exchanges, wealth platforms and regulators should watch how tokenized equities, Layer 2 networks, onchain lending and AI directed trading reshape product access, market supervision and investor protection.
Stablecoin regulation is starting to look like payment system supervision. Issuers, banks, custodians, payment firms, exchanges and compliance teams should watch how systemic designation, transition planning and cross-regulator supervision affect market access for regulated digital money.
The UK crypto market is getting a clearer operating perimeter. Crypto platforms, custodians, stablecoin issuers, intermediaries and staking firms should prepare for authorisation, capital planning, market conduct controls and compliance standards that bring crypto closer to mainstream financial regulation.
Stablecoin competition is shifting toward scale, governance and distribution. Banks, payment networks, wallets, merchants, fintechs and stablecoin issuers should watch whether shared economics, partner governance and broad platform participation become a stronger model for digital money adoption.
Tokenized securities need regulated payment and custody rails, not only issuance technology. Asset managers, administrators, custodians, stablecoin providers and tokenization platforms should watch how CASP and payment licences shape the full transaction lifecycle from subscription to redemption and payout.
Institutional stablecoin adoption is becoming part of regulated banking infrastructure. Banks, custodians, asset managers, payment firms and stablecoin issuers should watch how custody, minting, redemption and settlement services expand across institutional digital asset workflows.
Stablecoin payments are starting to connect settlement with spending controls. Merchants, payment networks, wallets, stablecoin issuers, compliance teams and fintechs should watch how programmable rules, item level controls and point of sale integration expand programmable stablecoin payments in commerce.
Agentic finance needs controls at the point of action. Banks, fintechs, payment firms, wealth platforms and compliance teams should watch how agent identity, authority, escalation, audit trails and transaction limits become core requirements for AI systems that can act on behalf of users.
Agentic finance is becoming a supervisory design question. Banks, fintechs, payment systems, trading firms, AI vendors and regulators should watch how consent, liability, agent identity, market controls, cyber resilience and accountability standards develop as autonomous systems enter financial workflows.
Market transparency increasingly depends on shared data infrastructure. Exchanges, trading venues, fixed income dealers, market data providers, asset managers and regulators should watch how consolidated bond market data improves price discovery, execution quality and market oversight.
Tokenised capital markets need legal certainty as much as technology. Issuers, investors, custodians, exchanges, fund managers and regulators should watch how bond issuance, record keeping, settlement and transfer rules adapt as fixed income markets move onto distributed ledger infrastructure.
Crypto regulation is expanding beyond market access into enforcement. Cryptoasset firms, trading venues, brokers, compliance teams and market participants should prepare for enforcement policies that increasingly align digital asset markets with established financial market conduct standards.
Crypto regulation can create financial crime pressure during market transition. CASPs, VASPs, banks, payment firms, exchanges and compliance teams should watch how licensing deadlines, customer migration and supervisory coordination affect AML controls across Europe.
Investment regulation increasingly focuses on communication as well as compliance. Asset managers, wealth platforms, advisers, fintechs and product manufacturers should prepare for disclosure requirements that prioritize clarity, comparability and consumer understanding alongside regulatory obligations.
Event contract regulation is moving from listing debates into market surveillance and data reporting. Prediction markets, exchanges, brokers, compliance teams and regulators should watch how reporting rules shape the boundary between derivatives, event markets, gambling and retail speculation.
The strongest fintech companies don't wait for certainty. They recognize patterns early, build where demand is growing and stay ready when regulation catches up. That's the value of watching the evidence, not just the headlines. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 2, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy, Payments And Market Infrastructure

NCFA has published a comprehensive guide to stablecoin regulations in Canada. It brings together the Stablecoin Act, Bank of Canada supervision and the related requirements administered by FINTRAC, Canadian securities regulators, OSFI and FCAC.
The guide explains how Canada’s framework may affect stablecoin issuance, reserve management, redemption at par, governance, data security, trading platform access, payment activity, custody and consumer protection.
Canada has enacted the Stablecoin Act, but its substantive requirements are not yet in force. Supporting regulations, registration mechanics and Bank of Canada implementation materials remain under development.
The resource organizes Canada’s stablecoin requirements as a connected regulatory framework.
A single stablecoin business model may involve several legal and supervisory layers. Depending on its activities, a firm may need to assess issuer registration, money services business obligations, payment service provider requirements, securities rules, custody controls and prudential treatment.
The guide covers:
This resource is designed for stablecoin issuers, fintech founders, crypto platforms, custodians, payment companies, banks, compliance teams, investors, policymakers and market infrastructure providers.
It is particularly useful for teams assessing:
The guide’s principal strength is its integrated view of Canada’s regulatory structure. Readers can identify which authorities are involved, what Parliament has enacted and which implementation questions remain unresolved.
It also connects regulation with market development. Clear rules for reserves, redemption, custody and compliance could support tokenized financial infrastructure, stablecoin payments and institutional settlement services.
Firms can use the guide to begin preparing legal perimeter assessments, issuer control maps, reserve policies, governance models, data security plans, redemption procedures, AML files and Bank of Canada engagement materials.
Canada’s stablecoin regime is still under development. The guide provides regulatory intelligence and planning support, but it is not legal, financial, investment, compliance or professional advice. NCFA will update the Regulatory Intelligence page as regulations, supervisory materials and implementation dates are confirmed.
Stablecoin Regulations In Canada (primary NCFA Regulatory Intelligence guide)
Deloitte And Stablecorp Bring QCAD To Banks (Canadian stablecoin infrastructure)
Tokenization Starts Looking Like Financial Infrastructure (tokenized market infrastructure)
Finance Canada Stablecoin Framework (primary government source)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking, funding opportunities and services to thousands of community members. NCFA works with industry, government, partners and affiliates to support a vibrant and innovative fintech and funding industry in Canada.
Decentralized and distributed, NCFA engages with global stakeholders and supports projects and investment across fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets, tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech.
Join Canada’s Fintech & Funding Community free, or become a contributing member to receive additional benefits. Visit NCFA Canada for more information.
| | |
|---|---|---|
| | |
Canada has now published proposed operating rules for its federal stablecoin regime. The Stablecoin Act received Royal Assent on March 26, 2026, but its substantive requirements are not yet in force. The proposed Stablecoin Regulations were published in Canada Gazette Part I on October 24, 2026 and remain under consultation.
This guide explains what is already established in legislation, what the proposed regulations would add, who may be covered and how the framework affects issuance, registration, reserves, redemption, custody, payments, trading and market access.
Coverage includes issuer scope, Bank of Canada registration, national security review, Canadian reserve custody, redemption at par, interest and rewards, governance, data security, FINTRAC obligations, RPAA payment activity, CSA value referenced crypto asset treatment, OSFI prudential rules and consumer protection.
Finance Canada has published the proposed Stablecoin Regulations and related RPAA amendments. The package now specifies issuer registration information, national security review periods, reserve assets and Canadian custody, redemption timing and fees, transaction rewards, policy requirements, reporting, cost recovery and the treatment of stablecoin payment functions.
Consultation closes December 23, 2026 at 11:59 p.m. Eastern
The proposal is not final and the regime is not yet operational. The government intends the regulations and Stablecoin Act to come into force in fall 2027 on a date or dates fixed by the Governor in Council.
Yes. Existing payments, AML, securities, prudential and consumer protection requirements can apply. The Stablecoin Act is enacted, and detailed federal regulations are now proposed, but the new issuer regime is not yet in force.
The Bank of Canada will register and supervise covered issuers under the federal framework.
The proposed regime covers registration, reserves, Canadian custody, redemption at par, governance, risk management, data security, reporting, recovery planning and restrictions on interest or yield.
Yes. Domestic and foreign non-financial institution issuers may be covered when they make fiat-backed stablecoins available to Canadians, subject to the Act, proposed regulations and any exemption based on substantially similar regulation.
No. Treatment depends on the stablecoin, issuer, activity and distribution model, including whether securities, derivatives, payments, AML or prudential rules apply.
Canada has progressed from interim securities treatment to an enacted Stablecoin Act and a detailed Canada Gazette proposal. The current phase is consultation. Final regulations, Bank of Canada guidance and legal commencement remain ahead.
Navigate the main authorities, obligations and implementation layers that make up Canada’s stablecoin framework. This reference supports the regulation-to-market pathway below by giving readers a deeper view of each regulatory component.
Canada’s federal framework now consists of an enacted Stablecoin Act and proposed Stablecoin Regulations. The new issuer regime is not yet in force. Existing securities, AML, prudential and payment rules continue to apply where relevant.
Firms should map the activity first. Issuing a stablecoin, operating a wallet, processing a stablecoin payment, trading a value referenced crypto asset and safeguarding reserve assets can trigger different regulatory layers.
The October 24 proposal makes Canada’s market entry model much more concrete. The key commercial distinction is now between becoming an issuer with reserve, custody and redemption obligations, and participating through payment, wallet, custody or compliance infrastructure.
The Stablecoin Act was enacted through Bill C-15 and received Royal Assent on March 26, 2026. Its substantive requirements are not yet in force. Once commenced, the Act would regulate domestic and foreign non-financial institution issuers that create a fiat-backed stablecoin and make it available for purchase, directly or indirectly, by persons in Canada.
The October 24 proposal supplies much of the operating detail the Act delegates to regulation, including definitions of creation and distribution control, outstanding stablecoins, closed-loop arrangements, registration information, reserve assets, custody, redemption timing and fees, policy content, significant change notices and supervisory assessment fees.
The proposal defines “create” as control over the stablecoin’s properties, including design and generation, and “make available” as control over distribution. For the definition of an outstanding stablecoin, “purchased” would mean purchased by a person whose usual residence, head office or principal place of business is in Canada.
A closed-loop stablecoin would fall outside the SCA where it can only be used within a specified merchant or merchant-group network, including transfers for use in that network, and can be redeemed in fiat only from that merchant, a member of the merchant group or a person affiliated with the issuer.
Issuer policies would need to cover governance, risk management, data security and recovery and resolution. The governance policy would also need a complaint process with a web complaint form, acknowledgment within seven days and resolution within 30 days. Risk management and data security policies would require independent review at least every three years, and all required policies must be supported by adequate human and financial resources.
Publication in Canada Gazette Part I starts consultation. It does not make the proposed regulations final or bring the Stablecoin Act into force. Final regulations would need to be published and commencement would occur on a day or days fixed by the Governor in Council.
The legal anchor was established in March. The October proposal now gives firms enough detail to begin serious entry modelling, but not enough certainty to treat fall 2027 as a fixed legal commencement date.
Applicants would use a Bank of Canada electronic system and provide detailed information about ownership, structure, stablecoin design, reserve assets, qualified custodians, third parties and technology locations. Foreign applicants without a Canadian place of business would need a person in Canada authorized to accept service.
The Minister of Finance would have 60 days to decide whether to conduct a national security review, with possible additional 60-day extensions. A review, once launched, would have a 180-day period that can also be extended in additional 180-day periods. This is separate from the Bank of Canada’s ordinary registration process.
The proposal would allow an issuer already operating immediately before commencement to continue temporarily if it applies within 30 days after the Stablecoin Act comes into force. New entrants would generally need registration before issuing.
Registration is now a market access process, not only a disclosure exercise. Ownership, reserve design, outsourcing, data location and national security review can all affect timing and entry planning.
The Bank of Canada would register and supervise covered issuers, maintain the issuer registry, monitor compliance, request information and use enforcement powers where obligations are not met. The Bank says its supervision will focus on full backing, par redemption and safe, reliable issuance.
The Stablecoin Act requires the Bank to recover its stablecoin supervision costs from registered issuers. The Gazette estimates those costs at about C$2.5 million annually. The proposed base assessment uses an issuer’s average monthly value of outstanding stablecoins: C$750,000 for C$1 billion or more, C$350,000 for C$500 million to under C$1 billion, and C$25,000 below C$500 million, subject to CPI adjustment. Tier 1 and Tier 2 issuers would also share 75% and 25%, respectively, of remaining recoverable costs; Tier 3 has no variable amount.
The Regulatory Impact Analysis estimates annualized incremental costs of the proposed Stablecoin Regulations at C$88,521 across affected issuers, or C$17,704 per regulated issuer on average under its assumptions. That estimate is distinct from Bank supervision assessments and from the broader operating cost of reserves, custody, governance and technology. Proposed administrative monetary penalties range from C$1 to C$1 million for serious violations and C$1 to C$10 million for very serious violations, subject to the detailed provisions and penalty criteria.
For smaller issuers, the important cost question is not the Gazette’s narrow incremental compliance estimate by itself. It is the combined cost of supervision, reserve operations, Canadian custody, governance, reporting and technology controls.
At the end of each day, reserve assets would need a market value equal to or greater than the par value of outstanding stablecoins and would need to be denominated in the reference currency.
Reserve assets would have to be held with a qualified custodian incorporated or formed under federal or provincial Canadian law. This would exclude financial institutions that are not incorporated in Canada from acting as the qualified custodian for these reserve assets.
The Act requires segregated, bankruptcy remote reserve assets that are protected from claims by the issuer’s or custodian’s other creditors except for claims of stablecoin holders. Issuers could withdraw reserve returns only while the reserve remains fully backed.
Canadian custody is one of the proposal’s clearest infrastructure choices. It could create domestic demand for custody, reserve banking, reconciliation and attestation services while adding an operating requirement for foreign issuers serving Canadians.
Issuers would have to redeem stablecoins one to one in the reference fiat currency and publish a clear redemption policy in both official languages.
The proposed rules also prohibit representations that a stablecoin is legal tender, a deposit or proof of deposit, publicly insured or government guaranteed. Stablecoin redemption should not be described as equivalent to deposit insurance.
Redemption is now measurable. Timing, fee ceilings, payment methods and liquidity exceptions give users and firms a much clearer standard for comparing issuer models.
The Stablecoin Act prohibits issuers from paying interest or yield tied to holding a stablecoin. The proposed regulations clarify that issuers also could not use indirect arrangements that fund payments designed to encourage holders to maintain larger balances or hold for longer periods.
Rewards programs will need to be designed around actual transaction use rather than time or balance held. Firms should assess the economic substance of arrangements rather than relying on the label attached to a reward.
The proposal draws a deliberate boundary between payment incentives and deposit-like returns. The broader international debate over stablecoin rewards and banking competition belongs in separate strategic analysis rather than being collapsed into this rule guide.
FINTRAC has stated that stablecoin issuers will be required to register as money services businesses dealing in virtual currency once the relevant changes come into force. AML obligations therefore sit alongside Bank of Canada issuer supervision rather than replacing it.
Issuers and platforms should connect issuance, reserve and redemption controls to customer due diligence, wallet monitoring, sanctions screening, transaction reporting and escalation processes.
Stablecoin use can operate at payment speed, so the compliance layer needs to be equally operational. That remains a material opportunity for Canadian regtech and blockchain analytics providers.
The October 24 package proposes amendments to the Retail Payment Activities Regulations so PSPs that perform payment functions using prescribed stablecoins can fall within the RPAA. This is separate from regulation of the issuer under the Stablecoin Act.
The proposed RPAR definition excludes closed-loop stablecoins. It would cover stablecoins issued by entities on the Bank of Canada’s stablecoin issuer list and stablecoins issued by financial institutions subject to federal, provincial or foreign requirements that are substantially similar to specified Stablecoin Act protections.
Where a PSP holds stablecoins on behalf of an end user, the proposal adds a safeguarding option using a separate entity whose sole purpose is holding end-user funds. The entity would be the registered holder on the distributed ledger, and the stablecoins and associated rights must not form part of the PSP’s estate. Safeguarding frameworks would also need procedures to give end users access to funds without delay if the stablecoin issuer becomes insolvent, including procedures for redemption into the reference fiat currency.
Covered PSPs would be subject to applicable Bank of Canada registration, operational risk management, incident response, safeguarding, reporting and national security requirements. Safeguarding frameworks are independently reviewed every three years under the RPAR. The RPAA also contains exemption mechanisms intended to reduce overlap with substantially similar regimes and securities transactions.
This creates a clearer service layer around stablecoins. A wallet, processor or infrastructure company can participate in stablecoin payments without necessarily taking on the reserve and redemption obligations of becoming the issuer.
The CSA’s interim approach applies to value-referenced crypto assets, commonly called stablecoins, on crypto asset trading platforms. The CSA has permitted certain fiat-backed crypto assets to continue trading where platforms and issuers meet terms and conditions.
Platforms should maintain VRCA due diligence files, issuer undertaking records, reserve disclosure links, risk disclosures, product monitoring, halt and suspension playbooks and client-facing stablecoin risk language.
The securities layer won’t disappear just because Canada now has a federal stablecoin framework. Trading, distribution and platform access will remain important parts of the Canadian stablecoin operating model.
OSFI’s cryptoasset exposure guideline sets regulatory capital and liquidity treatment for banks, federal credit unions, bank holding companies, federally regulated trust companies and federally regulated loan companies. Separate insurance guidance applies to insurers. The banking guideline took effect on January 1, 2026.
Banks and regulated financial institutions should assess direct and indirect stablecoin exposures, custody arrangements, issuer relationships, tokenized asset products, capital treatment, liquidity implications and OSFI notification triggers.
OSFI’s layer matters because stablecoin infrastructure may rely on banks for custody, settlement, treasury and institutional distribution. Prudential treatment can affect how quickly incumbents participate.
FCAC research shows stablecoin awareness and understanding are still policy issues. It also noted that stablecoins and cryptoassets were not covered by federal or provincial deposit insurance at the time of the research. Consumer understanding matters because stablecoins may sound safer than they are.
Issuers and platforms should test consumer disclosures, avoid deposit-like language unless legally accurate, explain insolvency and redemption risk, and make sure users understand who is responsible for each part of the product.
Consumer trust can’t be built on the word stable. It has to be earned through reserve transparency, redemption rights, clear platform roles and language people can understand.
The October 24 package is a proposal. Comments are open for 60 days. The Gazette states that representations, including attachments, will be published on the Canada Gazette website subject to its terms of use. The most decision-useful issues are those delegated to regulation rather than requirements fixed directly in the Stablecoin Act.
Registration information, transitional treatment, supervisory assessments and how requirements scale for smaller issuers.
Canadian custodian eligibility, reserve flexibility, redemption timing, liquidity exceptions and the 1% fee ceiling.
RPAA scope, foreign issuer recognition, transaction rewards, regulatory overlap and international interoperability.
Deadline: December 23, 2026 at 11:59 p.m. Eastern. Use the official Canada Gazette consultation. Changes to the Stablecoin Act itself would require legislative amendment rather than this regulatory consultation.
Canada’s framework is easier to understand beside other mature stablecoin regimes. Select a jurisdiction to compare implementation status, primary authority, regulatory model and strategic relevance for Canada.
Canada now has a detailed proposed operating model for fiat-backed stablecoin issuance by non-financial institutions. The proposal adds registration information, Canadian reserve custody, redemption timing and fees, policy requirements, reporting, cost recovery and RPAA treatment for prescribed stablecoin payment functions.
The regime is still not operational. Consultation closes December 23, 2026 and final regulations and Bank guidance remain ahead.
Stablecoin Act issuer framework with Bank of Canada supervision, Finance Canada policy direction and parallel FINTRAC, CSA, RPAA and OSFI requirements.
Canada’s key market design question is now whether the combined issuer, custody, supervision and payment requirements provide enough certainty for new entry without concentrating activity in the largest firms.
The UK has final FCA rules for non-systemic qualifying stablecoins covering issuance, backing assets, redemption, safeguarding and disclosures. Systemic payment stablecoins sit in the Bank of England perimeter.
This gives Canada a useful comparison for issuer design, backing assets, custody, redemption and how to separate retail-market and systemic payment oversight.
FCA stablecoin issuance rules inside the wider UK cryptoasset regime, with separate treatment where payment stablecoins become systemic.
The UK separates stablecoin issuance from broader cryptoasset activity while tying stablecoins to custody, disclosure and conduct rules.
MiCA creates a harmonized EU regime for cryptoassets, including asset-referenced tokens and e-money tokens. The stablecoin elements were among the earliest parts of MiCA to apply.
For Canada, the EU is the strongest example of a large market using a passportable stablecoin and cryptoasset framework across multiple member states.
Single-market cryptoasset regulation with specific stablecoin categories for ARTs and EMTs.
MiCA gives Europe an integrated market structure advantage. Canada does not have equivalent passporting, so interoperability and provincial coordination matter more.
The U.S. framework now has a final OCC rule covering payment stablecoin issuer activities, reserves, redemption, risk management, custody, applications, supervision and foreign issuers under OCC jurisdiction.
For Canada, the comparison is increasingly practical rather than theoretical because the U.S. regime is scheduled to take effect months before Canada’s intended fall 2027 implementation.
Federal payment stablecoin legislation with permitted issuer categories, federal and state supervision and separate treatment for foreign issuers.
Canadian interoperability will depend on whether the Bank of Canada eventually recognizes substantially similar foreign regimes and which Canadian obligations continue to apply after recognition.
Singapore’s framework focuses on single-currency stablecoins pegged to the Singapore dollar or G10 currencies and issued in Singapore, with strong emphasis on reserve backing, redemption and disclosure.
It is useful for Canada because it shows how a smaller financial centre can set a high-trust stablecoin regime without trying to cover every possible cryptoasset activity at once.
MAS single-currency stablecoin framework connected to Payment Services Act amendments and digital payment token oversight.
Singapore’s approach is narrow and trust-centred. Canada can use a similar discipline while accounting for securities and federal-provincial overlays.
Hong Kong has an active licensing regime for fiat-referenced stablecoin issuers, with HKMA supervision and a policy objective tied to virtual asset market development and financial stability.
For Canada, Hong Kong is a useful comparison because it connects stablecoin licensing with a broader digital asset market strategy and clear issuer licensing.
Dedicated stablecoin issuer licensing under the Stablecoins Ordinance.
Hong Kong is treating stablecoins as part of financial centre strategy. Canada’s framework will need a clearer market-development lane if it wants domestic issuance, not only control of foreign tokens.
Japan permits stablecoin issuance through regulated channels such as banks, trust companies and fund transfer service providers, with stablecoins treated through payment services and electronic payment instrument rules.
The Japanese model anchors stablecoin issuance in regulated financial institutions and payment functions rather than a broad open issuer perimeter.
Payment Services Act and related rules for electronic payment instruments, with issuance through regulated financial channels.
Japan offers a more institution-led comparison. Canada’s non-financial issuer mandate is broader, so its controls need to be clear enough for market trust.
The FSB’s global stablecoin recommendations seek consistent regulation, supervision and oversight of global stablecoin arrangements while allowing jurisdictions to implement domestic approaches.
This is important for Canada because cross-border stablecoin use depends on compatible standards for governance, risk management, redemption, reserve assets, data sharing and regulatory cooperation.
High-level recommendations rather than domestic law. They set a baseline for authorities designing local frameworks.
Canada’s framework should be easy for other authorities to recognize. That matters for cross-border use and domestic credibility.
The main difference between leading jurisdictions is not whether stablecoins, payments, AML, digital assets and consumer protection are regulated. Most serious markets are building rules across those areas. The practical difference is how clearly those rules connect. Jurisdictions with coordinated rulebooks, visible implementation timelines and clear supervisory entry points give firms a better path from compliance planning to market launch.
Market structureStablecoin regulation is converging around reserve quality, redemption rights, issuer governance and disclosure. The strategic difference is market design. The EU offers passporting, Hong Kong and Singapore connect licensing to financial-centre strategy, Japan limits issuance to regulated financial channels, and the U.S. focuses on dollar stablecoin scale.
Canada’s coordination challengeCanada’s October 24 proposal now specifies many of the operating requirements firms were waiting for. The remaining coordination challenge is how Bank of Canada issuer supervision, RPAA payment oversight, FINTRAC registration, CSA cryptoasset treatment and OSFI prudential rules work together in practice.
Cross-border useCanadian users and platforms will likely interact with USD stablecoins regardless of domestic issuance. The framework therefore needs rules for foreign stablecoins made available in Canada, not only rules for Canadian issuers.
Market opportunityThe opportunity is compliant settlement infrastructure. If Canada can make reserves, redemption, custody and AML controls clear, stablecoins can support programmable payments, tokenized settlement and cross-border transaction flows without relying entirely on foreign operating models.
Major jurisdictions are converging around high-quality reserves, redemption rights, issuer governance, disclosures and AML controls. They continue to diverge on market access, supervisory structure, passporting, foreign issuer treatment and how directly stablecoin policy connects to national competitiveness.
Canada’s challenge is now implementation quality. Final rules, Bank guidance, recognition decisions and practical coordination across the federal, securities, payments, AML and prudential layers will determine how easy it is for firms to launch or participate.
NCFA’s regulation-to-market pathway shows how Canada’s stablecoin framework can move from policy and supervision into market capabilities and innovation opportunities. The visual is not a legal hierarchy. It is a market-development map showing how regulatory functions connect to the operating capabilities firms need to build trusted digital money infrastructure.
These opportunity areas align with the capabilities in the pathway above. Only the published NCFA Opportunity Brief receives a primary call to action; the other nodes show where future research or Innovation Map coverage can expand.
Use these links to go deeper into the adjacent regulations, market evidence and infrastructure themes connected to Canada’s stablecoin framework.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 3, 2026 | NCFA Insight | Cybersecurity And Fraud, Digital Identity And Trust, Risk Compliance And Regtech, Payments And Money Movement, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data

Governments are no longer treating post-quantum cryptography as a research topic. They're now publishing migration plans.
On June 22, 2026, the White House issued an order on advanced cryptographic attacks, including the risk that adversaries collect encrypted data today so they can decrypt it later. The same day, a separate White House order advanced U.S. quantum innovation across computing, sensing, networking, applications, and industry partnerships.
That combination is the useful development marker for fintech. Governments are funding quantum capability while also pushing organizations to prepare for the security risk that follows.
The financial sector doesn't need to know the exact year a cryptographically relevant quantum computer arrives before it starts planning. Long time customer data, payment credentials, digital identity systems, API certificates, custody systems, vendor software, archived records, and cryptographic keys may remain sensitive for years.
Quantum readiness is therefore becoming an operating requirement. Not someday. Now.
The policy picture is getting clearer.
NIST finalized its first three post quantum cryptography standards in August 2024. The standards are FIPS 203 for ML-KEM, FIPS 204 for ML-DSA, and FIPS 205 for SLH-DSA. NIST says organizations should begin migrating systems to quantum resistant cryptography.
NCFA has already tracked how post quantum cryptography is entering implementation, with payments, digital identity, secure messaging, APIs, and financial data all exposed to the migration challenge.
Canada has started, too. The Canadian Centre for Cyber Security published a roadmap for migrating Government of Canada non classified IT systems to post quantum cryptography, covering stakeholders, phases, milestones, governance, and departmental planning.
Financial authorities are paying attention too. The Bank for International Settlements published a quantum readiness roadmap for the financial system, and the G7 Cyber Expert Group issued a roadmap for the financial sector's transition to post quantum cryptography.
The practical message is this. Start with awareness, find where cryptography is used, assess risk, plan migration, and work with vendors before deadlines become urgent.
The hardest quantum risk is not only future system compromise. It is long term data.
Financial institutions protect account records, payments data, identity documents, loan files, custody records, private market documents, insurance records, tax files, transaction histories, and compliance archives. Some of that data must stay confidential for years or decades.
That creates the harvest now, decrypt later problem. An attacker can collect encrypted data now and wait for stronger decryption capability later.
For fintechs, this impacts the planning window. A company doesn't need to be systemically important to hold sensitive data. A payments provider, open banking intermediary, wallet provider, identity service, lending platform, wealthtech app, regtech vendor, or crypto custodian may all depend on cryptography that was never designed for a quantum era.
Post quantum migration starts with discovery.
Most organizations know they use TLS, certificates, signing keys, databases, cloud services, APIs, authentication systems, payment connections, and vendor platforms. Fewer have a current inventory of which cryptographic algorithms protect each system, which assets must remain confidential long term, and which vendors control the upgrade path.
That's why cryptographic inventory keeps appearing across official guidance.
A fintech should be able to answer basic questions:
Without that inventory, migration plans become guesswork.
Fintech security is rarely managed by one company anymore.
A single product may rely on cloud hosting, identity verification, payment processors, data aggregators, card issuing platforms, custodians, wallet technology, fraud systems, CRM tools, analytics software, email providers, certificate authorities, and outsourced compliance systems.
That makes post quantum readiness a vendor risk issue.
A fintech can upgrade its own code and still remain exposed through a vendor that cannot explain its cryptographic dependencies. Banks and credit unions face the same issue in reverse. They may need to ask whether fintech partners can support post quantum requirements before onboarding, renewing, or expanding contracts.
The procurement question changes from "is this vendor secure today?" to "can this vendor survive a cryptographic transition without disrupting our product, customers, or regulatory obligations?"
Quantum readiness touches more than cybersecurity teams.
In payments, cryptography protects authentication, transaction integrity, messaging, API connections, certificates, and sensitive account data.
In digital identity, it protects credentials, signatures, documents, device binding, verification records, and trust chains.
In crypto and digital assets, it touches wallets, custody, private keys, signing systems, transaction authorization, smart contract administration, and institutional key management. BTQ's quantum safe Bitcoin and stablecoin roadmap highlights one approach to preparing digital asset infrastructure for post quantum cryptography.
In open banking, it affects API security, consent records, data sharing, third party access, and customer authentication.
In capital markets, it touches trading access, fund administration, investor records, tokenized securities, transfer agency, data rooms, reporting, and long term documents.
In AI and data systems, it affects model access, training data, confidential records, synthetic data pipelines, and secure data exchange.
That breadth is why the topic belongs with executives, product leaders, compliance teams, boards, and investors, not only cryptography specialists.
Canada's Cyber Centre roadmap gives public sector organizations a starting point. It also gives fintech and financial services leaders useful guidance that migration will take planning, governance, technical discovery, budgets, and coordination.
Canada doesn't yet have a full financial sector post quantum mandate comparable to a hard compliance deadline, but that statement should not create comfort.
Canadian fintechs operate in a global market. They sell into banks, credit unions, enterprises, governments, insurers, capital markets, payment networks, and regulated financial institutions. Their buyers may start asking post quantum questions before Canadian rules require formal answers.
A fintech that can show cryptographic inventory, vendor readiness, migration planning, and crypto agility may have an advantage in enterprise sales. A fintech that cannot answer basic questions may face longer diligence, higher security friction, or blocked procurement.
The near term opportunity is not building quantum computers. It's helping financial organizations prepare for the cryptographic transition. Quantum Bridge's USD $8M raise shows Canadian capital already backing deployment ready quantum safe security for finance, telecom, government, and defence.
Product opportunities include:
These opportunities are practical because they map to work financial firms already need to do. They need to know what they use, what they protect, which systems carry the highest risk, which vendors control dependencies, and how migration can happen without breaking production systems.
These are the kinds of tools that belong on NCFA's Financial Innovation Map, such as identity, payments, custody, regtech, data governance, and cyber resilience.
Quantum readiness won't arrive as a single upgrade.
Organizations will need inventories, test environments, migration sequencing, vendor commitments, product changes, audit evidence, customer communications, and fallback plans. Some systems will be easy to update. Others will depend on old software, hardware limits, contracts, third party platforms, or regulatory approvals.
That's why waiting for a precise quantum break date is the wrong approach for operators. Ask yourself, your team, your leadership this simpler question, "If a regulator, bank partner, insurer, enterprise buyer, or board asked tomorrow where vulnerable cryptography sits in the business, could the company answer?"
For many fintechs, the honest answer is probably no. So that's the opening to start.
Takeaway: Post quantum cryptography isn't a distant science fiction story anymore. It's becoming part of how financial organizations prove they can protect data, manage vendors, maintain trust, and keep critical services running through the next security transition.
If post quantum readiness starts with knowing where cryptography lives, should fintech due diligence now include a cryptographic inventory before major bank, payments, custody, or identity partnerships?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 3, 2026
Image by Idris Halloway
Most of the fintech intelligence that crosses a Canadian analyst's desk arrives pre-labeled by sector: lending, open banking, payments, insurance. US social casinos rarely get filed under any of them, which is part of why the category is easy to underrate. Strip away the cartoon coins and the free-spin marketing, and what remains is a consumer payments business with a money-in flow, a money-out flow, and a compliance perimeter that looks familiar to anyone who has ever built a wallet or a checkout.
That reframing matters because the US market has grown large enough to work as a live demonstration of payment ideas the Canadian sector is still rolling out. Before treating social gaming as a novelty, it helps to see how the products are actually packaged for players. GamingToday keeps a running reference on sweepstakes-style gaming options that lays out how these titles present coins, prizes, and purchase tiers, which is a sensible way to read the consumer surface before you go looking for the plumbing underneath it.
This piece reads the boom the way a payments team would rather than the way a gambling columnist does. It walks through the money-in side, the identity layer, the money-out side, and the embedded-finance framing that ties them together, then asks the partner-risk question that US bank regulators are now putting to any firm that touches these flows. Throughout, the vantage point is Canadian, because the RTR launch and the country's open-banking timeline make the US experience unusually relevant reading for a payments desk in Toronto or Vancouver.
The first mental switch is to stop counting players and start counting transactions. A social casino does not earn money from people playing free rounds. It earns money at two points only: when a user chooses to buy a package of virtual coins, and, in the sweepstakes variant, when a user redeems an accumulated prize balance back into real value. Everything between those two points is engagement, and engagement is free to the player and nearly free to the operator.
Size the market and the reason for attention becomes obvious. Analyst estimates for the global social casino category in 2025 span a wide band, from roughly nine billion dollars to more than twenty billion, depending on where each firm draws the boundary between social slots, poker apps, and sweepstakes brands. The definitions are messy, but the direction is not in dispute: this is a multi-billion-dollar consumer segment whose entire revenue base is card charges, account transfers, and payouts. For a payments professional, that makes it a large real-world test of exactly the rails and controls the industry argues about in the abstract.
The revenue mix is what separates social casinos from most mobile games. By several industry counts, a large majority of new social casino releases now ship with in-app purchases, and the sale of virtual coins, not advertising, supplies most of what they earn. A game that monetizes through purchases rather than ads is, functionally, a merchant. It has a checkout, an average order value, a decline rate, and a chargeback problem, and those metrics behave the way they do in any high-frequency, low-ticket consumer business.
Precision here prevents the whole analysis from drifting. A social casino is a free-to-play product. The core loop uses a virtual currency, often called Gold Coins, that has no cash value and cannot be redeemed for anything. Players can buy more of it to keep playing, but they are buying entertainment time, not a stake. This is legally and mechanically distinct from a real-money online casino, which takes wagers in dollars and pays winnings in dollars, and which is licensed in only a small number of US states.
The sweepstakes variant adds a second currency, usually called Sweeps Coins, that can be redeemed for prizes, and it reaches players through no-purchase methods as well as through a bonus attached to coin packages. That free-entry mechanism is the legal hinge that lets sweepstakes brands operate in far more states than licensed casinos can. It is also the feature that draws the most regulatory attention. Real-money online casinos are not legal in California, and the state's Assembly Bill 831, effective January 1, 2026, restricts the dual-currency sweepstakes model directly, extending exposure to the vendors and partners who support it.
For a payments reader, the takeaway is narrow and important. The money-in flow, buying Gold Coins, exists in both the plain social model and the sweepstakes model. The money-out flow, redeeming a prize, exists only in the sweepstakes model, and it is the flow that carries the heavier compliance weight. Keeping those two flows separate in your head is the difference between understanding the sector and repeating marketing copy about free coins.
Buying a coin package looks trivial to a player: pick a tier, tap a saved card or a mobile wallet, receive coins instantly. Underneath, it is one of the harder acceptance problems in consumer payments. Card networks and issuing banks treat anything gambling-adjacent as elevated risk, even when the product is legally a game rather than a wager. That classification drives higher decline rates, tighter merchant category coding, and processor pricing that reflects the risk of chargebacks and reputational exposure.

Image by Idris Halloway
The consequences shape the whole business. An operator that loses even a small share of attempted purchases to false declines is leaving revenue on the table at its single point of monetization, so payment optimization is not a back-office concern for these firms but a growth lever. Many run several processors in parallel and route each transaction to whichever is most likely to approve it, a practice payment teams recognize as orchestration. Mobile wallets help, because tokenized wallet transactions approve at higher rates and reduce stored-card exposure, which is why the checkout you see is usually a wallet button rather than a raw card form.
Account-to-account options sit at the edge of this flow and are growing. Paying directly from a bank account through an open-banking connection or a pay-by-bank rail sidesteps card interchange and card-network risk rules entirely. For an operator squeezed on card acceptance, an account-to-account purchase is cheaper and harder for an issuer to block, which is one reason the social gaming sector watches open-banking payment initiation as closely as any retail category does.
The industry talks about identity as a compliance chore, but for a payments team it is really part of the acceptance stack. Before a sweepstakes brand can let value flow out, it has to know who the account holder is, and that verification has to be strong enough to satisfy anti-money-laundering expectations on the redemption side. Weak onboarding produces fraud losses and payout disputes; onboarding that is too heavy kills conversion at signup. The tension between those two failure modes is the same one every neobank and wallet provider manages.
What makes social casinos instructive is the sequence. Because the free coins require no payment, a user can sign up and play with almost no friction, and heavier identity checks are deferred until the moment money is about to move out. That deferred-verification design, light at the top of the funnel and strict at the cash-out gate, is a pattern payment and lending firms use widely, and the social casino version runs it at very large scale with real fraud pressure behind it. Watching how these operators tune the verification gate is a practical lesson in balancing conversion against loss.
The stakes rise on the redemption side because that is where the model resembles regulated value transfer. Source-of-funds questions, sanctions screening, and duplicate-account detection all land at the payout step. A payments provider evaluating one of these brands as a client should read the strength of that gate as carefully as it reads the purchase flow, because the redemption path is where the regulatory liability actually concentrates.
Step back and the whole arrangement is an embedded-finance story. The game company is not a bank and does not want to become one, yet it offers a checkout, a stored-value balance, and a payout capability that together behave like financial services wrapped inside entertainment. That is the definition of embedded finance: financial functions delivered inside a non-financial product, through partners who supply the regulated pieces behind the scenes. NCFA's own plain-language primer on embedded finance frames the category as banking brought to the customer rather than the customer sent to the bank, and a social casino is that idea taken to its consumer-entertainment extreme.
The value chain looks the same as it does in any embedded-finance case. There are providers who hold the regulated licenses, enablers who supply the middleware and orchestration, and distributors, here the game brands, who own the customer relationship and the interface. Industry projections put the embedded-finance market on a steep growth path, with one widely cited forecast pointing to roughly US$776 billion by 2029 at a compound annual rate near twenty-four percent, and social gaming is one of the noisier consumer expressions of that curve.
Seeing the sector this way changes which risks matter. The interesting exposure is not whether a given game is fun or fair. It is that a chain of payment providers, processors, wallet vendors, and identity firms is quietly powering a product with a shifting legal footprint, and each of those partners inherits part of the risk. That is precisely the arrangement regulators have started to examine, and it is where the Canadian reader should pay closest attention.
Prize redemption is where social casinos meet the most active frontier in payments: getting money to a person quickly and cheaply. A player who wins expects the value to arrive fast, and a slow or failed payout is the quickest way to lose that player's trust and any future purchases. So the redemption experience is not a courtesy, it is a retention mechanism, which puts direct commercial pressure on the operator to use the fastest rail available.

Image by Idris Halloway
Traditional payout rails make this hard. A bank transfer can take days, a card refund is slow and reversible, and a gift card shifts cost around without solving speed. The rails purpose-built for this problem are the real-time payment systems now spreading worldwide: in the United States, instant networks that clear in seconds around the clock, and in Canada, the Real-Time Rail that Payments Canada is bringing online in phases through 2026 on the ISO 20022 messaging standard, with irrevocable settlement any time of day. A payout that lands in seconds, at a low flat cost, is exactly what a redemption flow wants.
The irrevocability of those rails is a double-edged design. Instant, final settlement is wonderful for a legitimate payout and dangerous for a fraudulent one, because there is no chargeback to claw a bad transfer back. That is why the identity gate discussed earlier tightens precisely at the cash-out step, and why operators pair fast rails with playthrough conditions and payout thresholds. For a Canadian payments desk preparing RTR use cases, the social casino payout problem is a preview of the fraud and speed trade-offs the domestic rail will face across many industries.
It helps to lay the pieces side by side, because the player sees a simple game surface while the payments team sees a stack of distinct decisions. The table maps each visible touchpoint to what the player experiences and to the question a payments professional should ask about it.
| Touchpoint | What the player experiences | The payments question underneath |
| Signup and free coins | Instant, no payment, start playing | How light can onboarding be before fraud enters |
| Coin purchase | Tap a wallet, coins appear | Which processor approves it, at what decline rate and cost |
| Stored coin balance | A number in the app | Is this stored value, and who holds the liability |
| Identity verification | A prompt before cash-out | Is the check strong enough for AML on payout |
| Prize redemption | Money arrives, ideally fast | Which rail, how fast, and is it reversible |
| Partner chain | Invisible | Which licensed firm carries the regulatory duty |
Read down the right column and the pattern is clear. Nothing on the player-facing side reveals where the money, the liability, or the compliance duty actually sits. Every meaningful risk lives in the second column, in the partner arrangements the interface is designed to hide. A payments reader who only watches the game surface will miss the entire business.
The reason this matters beyond curiosity is that the firms enabling these flows are the same kinds of firms bank regulators are scrutinizing hardest right now. Through 2024, US banking agencies issued a joint statement on the risks in bank arrangements with third parties and asked for comment on bank-fintech partnerships, signaling that the regulated institution behind an embedded product cannot treat the partner relationship as someone else's problem.
Image by Idris Halloway
The principle those agencies set out reads directly onto the social casino chain. In the Federal Reserve's federal guidance on third-party risk management, issued with the FDIC and the OCC in 2024, the agencies state that engaging a third party does not diminish or remove a bank's responsibility to operate in a safe and sound manner and to comply with applicable requirements. Translate that to a game brand's payment stack and it means the licensed provider at the base of the chain owns the compliance outcome, no matter how many enablers and distributors sit between it and the player.
For any payment firm weighing social gaming as a client, that reframes the diligence. The question is not only whether a specific brand is above board today, but whether the provider can supervise a partner whose legal footing may narrow state by state as measures like California's restriction spread. A rail that clears a redemption for a product later ruled offside is not a neutral pipe in the eyes of these frameworks. It is a supervised activity, and the cost of getting the partner assessment wrong is measured in enforcement, not just churn.
The useful conclusion for a Canadian reader is not to chase the sector or to dismiss it, but to treat it as free field research. The US social casino market is running, at consumer scale, the exact experiments the Canadian sector is about to formalize: instant irrevocable payouts, account-to-account purchasing, deferred identity verification, and financial features embedded inside a non-financial brand. Each of those is a line item in Canada's open-banking and Real-Time Rail rollout, and the US market is stress-testing them in public right now.
The risks travel just as well as the techniques. The same speed that makes a real-time payout delightful makes a fraudulent one unrecoverable. The same embedded-finance structure that lets a game offer a slick checkout spreads regulatory duty across a chain of partners who may not all understand what they are carrying. A Canadian provider that reads the US boom carefully gets to learn those lessons before the domestic rail is fully live, which is a far cheaper way to learn them than through a domestic incident.
Filed correctly, then, US social casinos belong on the payments desk, not the entertainment page. They are a large, fast-moving, real-money demonstration of embedded finance under regulatory pressure, and the plumbing they run on is the same plumbing the Canadian sector is building. The free coins are the distraction. The transaction flows, the payout rails, and the partner-liability questions underneath them are the reading that repays the attention.
Why would a payments professional study social casinos at all?
Because the product is a consumer payments business dressed as a game. Its entire revenue comes from coin purchases and prize redemptions, so it exercises card acceptance, identity verification, and fast-payout rails at large scale under real fraud pressure. That makes it a working case study in the same problems any wallet, checkout, or neobank has to solve.
How do social casino coin purchases move through the card networks?
They move like any high-risk, low-ticket merchant charge. Card issuers treat gambling-adjacent purchases as elevated risk, which raises decline rates and processing costs, so operators often route transactions across several processors and lean on mobile wallets to lift approval rates. Account-to-account and pay-by-bank options are growing because they sidestep card interchange and network risk rules.
What makes prize redemption a real-time payments problem?
Players judge a brand by how fast a prize arrives, so operators want the quickest rail available, which points toward instant systems like the US real-time networks and Canada's coming Real-Time Rail. Those rails settle in seconds and are irrevocable, which is ideal for a genuine payout and risky for a fraudulent one, so identity checks tighten at the cash-out step to compensate.
How does embedded finance apply to a social casino?
The game company offers a checkout, a stored-value balance, and a payout capability without being a bank itself, relying on licensed providers and middleware behind the scenes. That is embedded finance by definition: financial services delivered inside a non-financial product. The same provider, enabler, and distributor value chain seen across embedded finance applies directly to the sector.
What should a Canadian payment provider check before working with a social gaming brand?
Start with the strength of the identity and source-of-funds gate on the redemption side, since that is where anti-money-laundering liability concentrates. Then assess the brand's legal footing state by state, because measures restricting dual-currency sweepstakes are spreading. Under current third-party risk frameworks, the licensed provider keeps the compliance duty regardless of how many partners sit in between.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 2, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Wealthtech And Investing, Digital Identity And Trust, Risk Compliance And Regtech, Fintech And Innovation
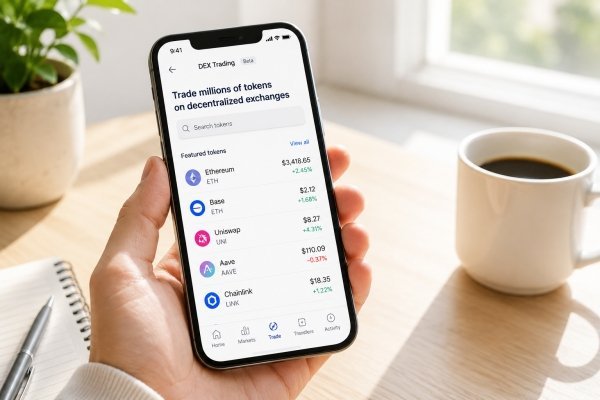
On July 2, 2026, Wealthsimple launched DEX trading in beta, giving eligible clients a way to trade on-chain tokens directly inside the Wealthsimple app.
The beta gives clients access to millions of tokens, starting with Ethereum-based assets. Base and Solana support are planned. The service charges a flat 0.85% trading fee and currently includes $0 network fees, which Wealthsimple Web3 Inc. covers during the early release.
This isn't the same product as Wealthsimple's centralized crypto account. When a client makes a first DEX trade, the app creates a separate self-custody wallet. The app holds DEX assets separately from centralized crypto holdings. They aren't insured, and don't have the same regulatory oversight as Wealthsimple's listed crypto offering.
A normal DEX user has to manage a wallet, fund it, connect it to a decentralized exchange, check token contracts, manage network fees, understand slippage, approve transactions, and protect private keys. As a result, there are a lot of steps that add complexity.
The beta removes much of that setup from the user experience. Its help guide says clients can search for DEX-labelled assets in the Discover tab, create a DEX wallet during the first trade, and buy or sell eligible DEX tokens directly in the app.
Behind the scenes, the app converts the funding asset into USDC. It then withdraws the funds to the self-custody wallet and routes the order through a third-party DEX aggregator before executing the trade.
Centralized crypto assets go through the platform's listing process, and the platform holds them on behalf of clients. DEX assets haven't gone through that centralized listing process.
Wealthsimple says a third-party vendor flags malicious tokens, and the app automatically filters them, and asset pages can display risk flags such as new asset history, top holder concentration, low holder count, low liquidity, sketchy token permissions, and artificial trading patterns.
Those flags are useful, but they aren't a safety guarantee. The help guide tells users to research tokens before trading and notes that blockchain transactions can't be reversed. If a client buys a scam or fraudulent token, the transaction can't be undone.
While the product lowers the operational barrier to on-chain markets, users still face risks that don't exist in the same way inside a curated centralized exchange custodial account.
Clients hold WS DEX assets in a self-custody wallet. They aren't covered by insurance, don't have government-backed loss protection, and aren't held by Wealthsimple on the client's behalf.
The support team can't recover the wallet or reverse transactions if something goes wrong. The user authorizes trades, and the wallet sits outside Wealthsimple's centralized crypto infrastructure.
There are also product limits during early release.
At the end of the day, there are limits to what the beta product is at this point. Embedded self-custody trading inside a controlled retail app, not a full open-wallet DeFi experience.
Wealthsimple's IPO Access launch gave eligible retail investors a way to request shares in selected Canadian and U.S. IPOs before public trading. Wealthsimple's 2025 product event added zero fee options, real gold, and private market portfolios. Wealthsimple's Fey acquisition added AI research and trading tools to the roadmap.
DEX trading adds another access layer. Clients can use one app for listed securities, crypto, IPO access, options, gold, private market portfolios, and now on-chain token trading.
Most clients won't need millions of tokens. The acid test is whether the app can make on-chain trading simple enough to try without making the risks feel smaller than they are.
One path is regulated centralized crypto access, where platforms list a smaller set of assets, hold assets through custodial arrangements, follow dealer rules, and provide clearer investor protections. Canadian crypto regulation has pushed platforms toward stronger custody, registration, and operating controls.
The other path is on-chain access, where users reach a broader token universe but also take on more responsibility for token risk, wallet access, tax tracking, execution, and irreversible transactions.
The beta sits between those paths. It keeps the user inside a mainstream Canadian app, but the assets trade through decentralized markets and sit in a self-custody wallet. That's different from both a traditional crypto exchange and a fully independent DeFi wallet.
Wallet usability becomes a core feature. Token risk intelligence becomes part of the trading interface. Slippage controls, routing quality, transaction monitoring, tax tooling, scam detection, and user education become operating requirements rather than extras.
Those areas connect directly to NCFA's Financial Innovation Map, including self-custody wallets, retail digital asset access, token risk analytics, on-chain finance, digital identity and trust, and compliance technology.
The opportunity isn't only trading more tokens. It's building the trust, data, user experience, and risk tools that let mainstream investors interact with on-chain markets without pretending those markets are safe by default.
If mainstream investing apps make self-custody DEX trading feel simple, will the next phase of retail crypto adoption depend more on token access or risk intelligence?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 2, 2026

Businesses produce large quantities of data from sales systems, customer interactions, marketing campaigns, websites and operational processes. Organising this information is necessary for identifying opportunities plus making decisions based on facts. Cloud data lakes are flexible environments where organizations store large volumes of structured and unstructured data in one place, which provides a basis for complex analytics but also business intelligence.
Traditional storage systems often require users to organize data before they store it. In contrast, cloud data lakes allow businesses to collect information from many sources and analyze it when necessary - this method helps organizations understand customer behavior, market trends, operational performance as well as potential for future expansion.
A cloud data lake is a central location for storing raw data in its original form. It allows businesses to keep information that does not fit into standard databases. Data is available from websites, mobile applications, social media, sensors, financial systems and tools for managing customer relationships.
Flexibility makes cloud data lakes useful for growth analytics. Organizations are able to combine data from different departments without long preparation periods - this creates a complete view of business activities or helps teams find connections and patterns that are otherwise difficult to see.
Gathering information from many business systems is a primary benefit of cloud data lakes. Marketing data, sales records, customer service interactions, inventory reports next to website analytics are stored together - this broad approach improves the quality and precision of business analysis.
Detailed understanding of performance across the entire organization is possible when businesses collect information from many sources. Analysts are able to study how marketing campaigns affect sales, how support affects customer retention or how inventory management relates to profit - these connections support strategic planning plus initiatives for growth.
Growth analytics require the accurate measurement of performance. Free cloud storage supports constant monitoring - collecting information from operational but also financial systems quickly - this allows organizations to follow key performance indicators and react to changes.
Revenue growth, costs to acquire customers, operational efficiency as well as product performance are measurable through integrated tools. Finding performance issues early allows managers to fix problems before they change the final results significantly.
Cloud data lakes make it simple for authorized teams to find information. Users retrieve data from a central location instead of searching through separate systems - this increases efficiency and reduces the time required for decision making.
Better accessibility also promotes cooperation between departments. Marketing teams, finance departments, operations managers but also executives use the same data. Decisions are consistent and follow the general goals of the business.
Cloud data lakes provide the storage as well as computing power necessary for advanced analytical methods. Businesses use predictive analytics, machine learning models and statistical analysis to find patterns that help future growth - these tools allow organizations to look at future opportunities rather than only looking at past reports.
Complex analytics show trends in customer purchasing, identify segments of the market that produce profit or predict demand. By using these insights, businesses distribute resources effectively and make decisions that support expansion while avoiding unnecessary risks.
Understanding how customers behave is a vital part of business growth. Cloud data lakes allow organizations to join customer information from many channels, like websites, mobile apps next to purchasing platforms - this creates a complete profile of the customer.
Preferences, habits and engagement patterns are visible when businesses have a unified view of customer activity - these insights help organizations create specific marketing campaigns, improve the customer experience plus increase loyalty. Better understanding of customers often results in higher revenue and a better position in the market.
Data volumes often increase quickly as businesses grow - Cloud data lakes scale to meet the needs of the organization, which allows companies to store and analyze large datasets without spending heavily on new infrastructure - this scalability supports long term growth without the need to replace systems constantly.
Many organizations start data projects with affordable solutions, like limited storage for testing. Businesses move to larger environments with more capacity as their needs for analysis grow. Some providers offer plans with unlimited cloud storage but companies should check usage policies or performance needs before choosing one.
Reliable and honest information is necessary for effective growth analytics. Businesses should create data governance rules that define how they collect, store, access next to maintain information. Clear policies improve the quality of data and help the company follow regulations.
Security measures like access controls, encryption plus monitoring tools protect private information. Strong governance ensures that analysis is based on accurate data, which gives decision makers confidence in the insights they use for growth strategies.
Cloud data lakes are a strong foundation for business growth analytics because they centralize information, make data accessible and support complex analysis. They allow organizations to combine data from many sources, understand customers better, monitor performance but also find opportunities for expansion.
Using governance practices and analytical tools helps businesses change large amounts of data into useful insights. A managed cloud data lake helps organizations make decisions based on facts, improve how they operate as well as create growth in a business environment that relies on data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016