




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 6, 2026 | NCFA Market Activity | Open Banking Open Finance And Data Sharing, Identity Privacy And Data Governance, SME Finance And Business Banking

On August 6, 2026, Yapily expanded bank account verification for Google Cloud customers across 11 European markets.
Businesses in Germany, France, the Netherlands, Spain, Portugal, Lithuania, Italy, Belgium, Austria, Ireland and Sweden can now confirm a bank account during onboarding through a direct bank connection instead of submitting documents for manual review.
The optional service builds on an account-verification arrangement first announced in 2025. Google can now use one Yapily connection across the selected markets rather than maintaining separate document checks in each country.
Businesses can verify a bank account without uploading documents and waiting for someone to review them.
Business account verification often requires a bank statement or another document showing the account holder’s name and banking details. Staff then review the document and compare it with the information submitted during onboarding.
Yapily replaces that exchange with permissioned information received from the customer’s bank. The company says Google Cloud customers can confirm a business bank account and receive a result in minutes.
The service can return account-holder and identity information, account numbers and other bank-sourced data from consumer, business and corporate accounts. The information available and the authentication process may still vary by bank and market.
The immediate benefit is lower administrative cost. Faster verification can reduce manual review and limit document errors. It may also keep a qualified customer from abandoning onboarding while a bank statement waits for approval.
Banks provide the underlying APIs, but most businesses will not connect separately to every institution. They will usually reach open banking through an infrastructure provider or software that has already built the connection into a business task.
Yapily connects to banks and handles differences in authentication, consent, data formats and market coverage. Google places the verification step inside its own onboarding process. The customer sees a faster way to confirm an account, not a separate open banking product.
The same structure can support verification, lending, accounting, payments and treasury workflows. A business may use open banking without choosing an open banking provider or even seeing its name.
Direct bank data inside SME finance software is already taking a similar route in Canada. Adoption grows when bank connectivity is built into software businesses already use.
Google controls the onboarding experience and the customer relationship. Yapily supplies the bank connectivity and verification infrastructure behind it.
That split can work for both sides. Google removes a manual step without building bank connections market by market. Yapily gains enterprise volume and proof that its network can support a large international customer.
A similar division of roles appears where Jack Henry embeds Google Cloud technology inside bank operations. Google provides the underlying infrastructure, while the company closest to the financial institution controls the workflow and customer relationship.
The Yapily arrangement shows where commercial power may settle as open banking becomes embedded. The infrastructure provider can be essential while the software platform controls distribution, product placement and the customer experience.
There is no public evidence that the Google-Yapily arrangement is exclusive or restricts competing providers. The issue is whether specialist infrastructure firms can retain pricing power when their services sit behind much larger platforms.
One Yapily integration simplifies Google’s side of the process. It does not, however, make European bank connectivity uniform.
Verification still depends on the quality of each bank’s API, the information it returns and the authentication process available in that market. Some institutions or account types may not support every field needed to complete the check.
Yapily says it connects to more than 2,000 banks across 19 European markets. Its documentation describes the broader Validate service as being in private beta. The Google Cloud rollout shows a live enterprise use, but it does not mean every applicant will receive the same experience across every bank.
Enterprise customers will care less about the size of a country list than the percentage of applicants who complete verification without falling back to manual review. Successful verification rates, exception handling and bank coverage will determine how much time the workflow saves in practice.
Google Cloud’s rollout shows where open banking is heading. The bank connection disappears into onboarding, while the customer experiences one less document request.
As open banking disappears into business software, how much of the value will remain with the infrastructure provider behind the connection?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
 |  |  |
|---|---|---|
 |  |  |
August 5, 2026 | NCFA Market Activity | Wealth Investing And Trading, Embedded Finance, Competition And Market Structure

On July 20, 2026, Chime launched Chime Invest inside the app its members already use for deposits, spending, savings and credit. Members can buy US stocks and exchange traded funds from US$1 or choose a managed portfolio. Neither option has an account minimum.
Chime didn't build the regulated investment stack itself. Atomic Invest provides portfolio advice, while Atomic Brokerage executes and holds the investments. Self directed trades carry no commission, although other charges may apply. Annual managed portfolio fees are zero for Chime Prime members, 0.10% for Chime Plus and 0.25% for standard members.
On August 3, Allied Universal added Chime Workplace for a North American workforce of approximately 320,000 employees. Chime says Workplace includes investing alongside earned wage access, savings and credit building. The workforce figure describes potential reach. It isn't an enrollment count, and the announcement doesn't say employees will be automatically enrolled in Chime Invest.
Chime is a financial technology company, not a bank, broker or investment adviser. The Bancorp Bank and Stride Bank provide its banking services. Chime Invest sits outside that deposit relationship. Atomic Invest is an SEC registered investment adviser, and Atomic Brokerage is a registered broker dealer and SIPC member.
The partnership lets Chime enter wealthtech without carrying every licence, control and operating function inside its own company. It also creates a commercial incentive. Chime receives compensation based on assets referred to Atomic, so it benefits when members open and fund investment accounts. The product disclosure identifies that incentive as a conflict users should understand.
Chime brings something Atomic doesn't have on its own though, which is a frequent consumer relationship. The company says an average member opens the app five times a day and completes more than 50 transactions a month. Investing now appears beside the account where many members already receive pay, spend and save. That lowers the effort required to try investing, although it does not establish that members will fund accounts or keep investing.
Investment accounts are not deposits. They can lose value and do not receive FDIC insurance. SIPC protection applies through Atomic Brokerage within its limits, but it does not protect investors from market losses.
Chime bought Salt Labs in June 2024 for its employee rewards technology and employer relationships. It launched Chime Workplace in March 2025, then connected the service to Workday and UKG. Allied Universal gives that channel one of its largest disclosed partner workforces so far.
The entry product is MyPay at Work. Eligible workers direct their pay to a Chime account and can request an advance against verified earnings. From there, Chime can offer savings, credit and investing inside the same app.
Chime doesn't charge Allied Universal or its employees to make Workplace available. Some optional products can carry fees or charges. With no employer fee, the economics depend on workers enrolling, directing pay into Chime and continuing to use its products.
Useful benchmark for this strategy First Student is North America's largest school transportation provider, with 66,400 employees and operations across the United States and Canada. It joined Chime Workplace in the first quarter of 2026 and provides Chime an early usage benchmark among a large frontline workforce. Chime reported in the Allied Universal announcement that 46% of actively enrolled First Student employees began saving within two months. Among those savers, 76% kept contributing. The figures apply only to active enrollees, not First Student's full workforce, and Chime has not published comparable Workplace investment adoption.
Chime starts with pay, spending and savings before offering investments. Robinhood is building household finance outward from trading through managed investing, family accounts, cards and other products. SoFi combines lending, deposit accounts and investing, while earned wage providers concentrate more narrowly on access to pay.
Distribution determines which app gets the first chance to turn income into spending, savings, borrowing or investment assets.
Chime entered this rollout with 10.2 million active members at March 31, 2026. First quarter revenue reached US$647 million, up 25% from a year earlier, and the company reported US$53 million in net income. It also signed four new employer partners during the quarter, including First Student. Chime's second quarter results are scheduled for release after the market closes on August 5 and were not available when this article was verified. The 2025 fintech IPO class also included Circle, eToro and Klarna, giving investors several financial platform models to compare.
Stakeholders should monitor Allied Universal enrollment numbers. Direct deposit conversion, sustained savings, funded investment accounts and assets held through Atomic will show whether Chime can extend an everyday financial account into wealth management.
Can Chime turn frequent spending and payroll relationships into funded investment accounts, and can its employer channel bring that model to people who haven't used a wealth app before?
Chris Britt and Ryan King founded Chime in 2012. The company built a mobile financial account around direct deposit, card spending, early pay and fewer consumer fees.
ChimeA consumer financial technology company
FormationA mobile alternative to traditional bank accounts
Venture BackedPrivate financing supports product and member growth
United StatesConsumer banking and payments
Everyday EarnersPeople seeking simpler access to pay and spending
Banks And FintechsPrice, convenience and trust drive adoption
Direct deposit gave Chime a recurring place in a member's financial life. That primary account position later supported credit, liquidity and savings products.
Chime Invest adds US stocks, exchange traded funds and managed portfolios to the main Chime app. Members can begin with US$1, and neither investment option has an account minimum.
Atomic Invest provides the managed portfolio advice. Atomic Brokerage executes and holds the investments. Chime promotes the service and receives compensation based on assets referred to Atomic.
Chime says self directed stock and exchange traded fund transactions carry no commission, although other charges may apply. Managed portfolio fees are zero for Chime Prime members, 0.10% annually for Chime Plus and 0.25% for standard members.
Chime lists investing among the tools included with Chime Workplace. The Allied Universal announcement does not confirm automatic enrollment, immediate investment access for every employee or how many workers are eligible.
No. Chime is a financial technology company. The Bancorp Bank and Stride Bank provide its banking services. Chime Invest is a separate investment service provided through Atomic.
Chime describes Chime Invest as a product for eligible US members. The Allied Universal announcement refers to a North American workforce but does not confirm Canadian investment access.
This article is provided for informational purposes and does not constitute investment, financial or legal advice. Product availability, eligibility, fees and terms may change. Company adoption figures are attributed to Chime and should not be treated as independently audited results.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 28, 2026 | NCFA Market Activity | Open Banking Open Finance And Data Sharing, Payments And Money Movement, Competition And Market Structure

On July 28, 2026, Credit Connect reported that UK open banking passed one billion cumulative payments and 100 billion cumulative API calls across the CMA9 banks. Both totals cover more than eight years of activity.
The report directly quotes Open Banking Limited CEO Henk Van Hulle. A matching announcement wasn't available in Open Banking Limited's newsroom when this article was prepared, so the cumulative totals are attributed to Credit Connect.
Open Banking Limited's June performance data also shows what the system's baseline is for a single month. It recorded 2.8055 billion successful API calls, a 99.50% success rate and an average response time of 349 milliseconds. Credit Connect reported that API use rose 4.4% from May and response time improved by 50 milliseconds.
June also produced 40.16 million successful open banking payment initiations. Single domestic payments declined 1.2%, while Variable Recurring Payments increased 6.7%.
The cumulative milestone gets attention, but the monthly numbers say more about the current market. Banks are processing billions of API requests while third party providers initiate more than 40 million payments a month. Open banking now supports regular payment activity alongside account information services.
The figures describe different parts of the system. An API call is a request between an authorized provider and a bank. A payment is a successful payment initiation. Open Banking Limited also reports more than 19 million active user connections, but those connections aren't deduplicated individuals. The same customer may be counted through more than one provider or brand.
Payment use has been building quickly. The FCA's 2025 open banking progress report recorded 53% year over year growth in open banking payments. Variable Recurring Payments accounted for 16% of open banking transactions at that point.
The UK now has a functioning base for account to account payments. Banks supply the required APIs, fintechs build payment services and merchants decide whether the cost and customer experience compare favourably with cards and Direct Debit.
Variable Recurring Payments are relatively new to the UK market. UK open banking update tracked approximately 3.7 million VRP transactions in March 2025, along with more than 240 regulated third party providers. It also cited a UK Finance estimate that recurring payments could save merchants approximately £1.5 billion a year.
The July numbers show continued use while the industry develops commercial VRP beyond transfers between a customer's own accounts. Customers can authorize businesses to initiate repeat payments within agreed limits without approving every transaction separately.
On June 2, 2026, the FCA supported the launch of the UK Payments Initiative, an industry operated scheme for commercial Variable Recurring Payments. The FCA expects other commercial schemes to compete with it.
The initiative has substantial industry backing. In 2025, 31 participating firms, including banks, fintechs and payment providers, agreed to fund the initial operator. Proposed uses cover utilities, rail, government agencies, charities and regulated financial services.
The remaining question is how the economics are divided. Banks incur costs to provide premium APIs, while payment providers need pricing low enough to compete for merchants. In January 2026, the FCA and Payment Systems Regulator said they wouldn't prioritize a competition investigation into the proposed centralized access fee model at that stage.
The one billion payment total gives the industry a larger customer base on which to build. It doesn't determine who captures the revenue. Banks may charge for premium access, payment firms may win merchant distribution and software platforms may package recurring payments into billing, treasury and account management products.
The original open banking system was built around a market competition order applied to nine large banks. Commercial schemes now bring more providers, products, pricing agreements and customer relationships into the system.
The FCA expects a new Future Entity to set common API standards, monitor performance, oversee certification and support commercial schemes. Its role will influence whether payment providers receive consistent access across participating banks.
The UK payments playbook connects commercial VRP delivery with retail payment rules, Faster Payments improvements and the future regulatory structure for open banking.
Reliability is already measurable. June's weighted API availability reached 99.80%, while successful calls reached 99.50%. Those averages are interesting, although a customer experiences the individual bank connection used for a particular service or payment.
Fraud still remains part of the operating model. Open Banking Limited's fraud monitor found that roughly one in 6,000 open banking payments was fraudulent in 2025, compared with one in 2,500 across the wider payments industry. Authorized push payment fraud accounted for more than two thirds of reported open banking fraud cases.
The direct Canadian relevance is the connection between data access and payments. Canada is developing consumer driven banking, payment system participation and future write access through separate rules and institutions. The UK experience shows where those files eventually meet through commercial pricing, recurring payment permissions, technical standards, liability and scheme governance.
As commercial VRP expands, who should control access pricing and liability when banks, fintechs and merchants all depend on the same connection?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

We're opening up more and more APIs to partners, fintech services, and client applications. The only question is whether we're confident these same APIs aren't opening up new paths for attackers.
Just a few years ago, a bank mostly dealt with its own systems. A customer would log into the app, check their balance, make a transfer. The whole journey stayed inside the perimeter of a single organization.
Today, one customer might simultaneously use a mobile banking app, a budgeting service, an accounting platform, a payment provider, and an AI assistant that analyzes their spending. All of these services exchange data through APIs - interfaces that let different systems talk to each other according to a set of established rules.
Open Banking isn't just a regulatory requirement or a new integration channel - it's a shift in the trust model itself. A bank used to be responsible for security within its own infrastructure. Now it hands off part of its data to dozens of external services, and those services, in turn, rely on the bank. The more participants in the ecosystem, the more points there are where trust is either reaffirmed or cracked, every single day.
Attackers are less and less interested in finding a weak spot inside any one bank. Today, hackers target the interaction between systems itself. The longer the chain - bank, fintech, payment hub, partner app - the more places there are for something to go wrong.
Common examples include:
An API can perform flawlessly on the functional side - fast, stable, no errors in the logs - and still carry a critical vulnerability. Functional correctness and cybersecurity don't always go together.
Banks and fintech companies generally don't neglect API security. They go through certifications, run automated scans, do code reviews and QA. But none of these tools answer the one question that matters most: can this specific API's logic be bypassed in a way its developer never anticipated? Scanning catches known vulnerability patterns; code review and QA confirm the code does what it was built to do. Neither one thinks like an attacker who isn't hunting for a bug in the code, but for a logical gap in how the API interacts with other systems.
That's why most attacks on financial APIs today aren't about technical mistakes - they're about logic: the sequence of actions, the boundaries of authority, the trust placed in data coming from the client. It's also why modern Cybersecurity Solutions for Fintech increasingly go beyond formal compliance with standards, testing real-world abuse scenarios at the points where multiple systems meet.
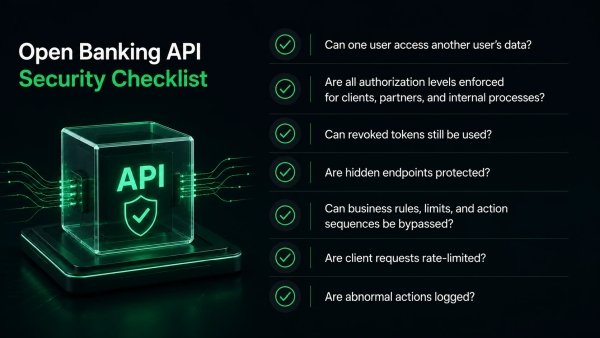
Here's a short checklist for reviewing every external API in your ecosystem:
If you don't have a confident answer to any of these, that's reason enough to look closer.
It's worth telling apart three things that often get lumped together. Vulnerability scanning looks for known vulnerabilities by signature, catching familiar vulnerability classes, common misconfigurations, and known dangerous patterns. Automated testing checks whether the code performs its intended functions correctly. Separate from both is API Penetration Testing (https://datami.ee/services/pentest/api-penetration-testing/) - manual testing in which a specialist plays the role of a real attacker: combining requests, tweaking parameters, hunting for unusual sequences of actions that a scanner, in most cases, won't flag as anomalous, because each individual request looks legitimate on its own.
It's also best if this kind of testing is handled by an external team. In-house specialists tend to know their own API inside and out - and that's precisely what makes it hard for them to spot an unconventional abuse scenario, since day-to-day work with a system's logic doesn't train you to look at it through the eyes of someone deliberately trying to break it. External specialists bring experience from other architectures and payment integrations, so they're more likely to catch the gaps a team had written off as unimportant.
A bank can offer the most convenient digital service and the best partner API on the market. But if even one partner or customer stops trusting the security of the data exchange, the benefits of Open Banking vanish almost instantly. Trust here isn't a bonus feature - it's the baseline condition, and without it the whole structure loses its meaning.
That's why investing in API protection in the financial sector isn't just about regulatory compliance - it's about sustaining trust across the whole ecosystem: between bank and fintech, fintech and customer, and customer and every new service they let into their data.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: July 14, 2026
Status: Strong
Organizations: Payments Canada, Bank of Canada, Wise Payments Canada, Float, KOHO, Paramount Commerce, Brim Financial, DoBusiness.com, Neo Financial, Meridian Credit Union, Tru Cooperative Bank, Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, Newton, XTM, UK HM Treasury
Payment networks are opening to more fintechs and payment service providers, but access is becoming more conditional rather than less controlled.
Canada’s expanded Payments Canada membership rules now allow eligible PSPs and provincial credit unions to enter a system once dominated by banks and a limited group of financial institutions. New members may apply to participate in the Real-Time Rail, contribute to Payments Canada governance and build services closer to national payment systems.
That doesn’t give every member the same operating position. Membership, system participation, exchange access, clearing, settlement and governance remain separate layers. Each comes with its own eligibility, technical, fraud, liquidity, safeguarding and supervisory requirements.
Canada has already started opening access across payments and financial data. Regulated non-bank firms can now enter formal membership and participation pathways instead of relying entirely on bilateral relationships with incumbent banks.
The operating model still has gates. Payments Canada membership makes a PSP eligible to apply for participation. It doesn’t automatically provide production access, a settlement account or relief from ongoing compliance. Canada’s approved RTR rules and access framework distinguishes direct settlement, agent settlement and service-provider roles, each with different economics and responsibilities.
Published standards can make entry more transparent and less dependent on institutional status. They can also increase the cost of integration, testing, fraud controls, liquidity management and continuous operations.
The evidence points to access and control developing together. Regulators and network operators are using common rules to admit more participants without requiring every entrant to hold a bank charter or decades of bilateral operating history.
Click each item to expand
Payments Canada admitted Wise Payments Canada, Float, KOHO, Paramount Commerce and Brim Financial after federal changes expanded membership eligibility to registered payment service providers.
The intake opened a formal route into Canada’s payment-system structure. It did not provide automatic production or settlement access.
By June 3, Payments Canada reported that 15 organizations had joined during 2026 following the expansion of its eligibility rules.
The wider intake shows that expanded membership is becoming an operating pathway rather than a one-time group of approvals.
Payments Canada admitted uSecure Escrow Solutions, operating as DoBusiness.com, as a PSP member on April 16, 2026.
The approval shows that access can extend beyond consumer fintech brands to specialized business payment providers.
Payments Canada has published a participation pathway for PSPs preparing to join the Real-Time Rail, Canada’s planned instant exchange, clearing and settlement system.
The pathway takes access beyond policy eligibility, although onboarding, certification and settlement arrangements still determine whether a firm reaches production.
Meridian Credit Union became the first provincial credit union admitted under the expanded membership rules, followed by other cooperative institutions in the 2026 intake.
The additions extend formal membership beyond fintech PSPs and bring more regional institutions into national payment governance and participation pathways.
Click each item to expand
Payments Canada distinguishes membership from participation in the Real-Time Rail.
This separation prevents membership totals from being treated as proof that every new member has equal operating access.
The approved RTR By-law and Rules establish the legal framework for exchange, clearing, settlement, payment finality and participant responsibilities.
Legal certainty gives prospective participants a clearer basis for investment while setting the conditions under which access can be used.
Registered PSPs must continue meeting Bank of Canada reporting, risk-management and safeguarding requirements under the Retail Payment Activities Act.
The framework replaces an informal access environment with continuing regulatory accountability.
The Bank of Canada ordered XTM to stop retail payment activity in February 2026 and later permitted a controlled restart under court-supervised monitoring.
The case shows that supervision can affect production access, customer funds and business continuity, not only regulatory filings.
The RTR framework combines ISO 20022 payment data with centralized fraud services and participant-level controls.
Common controls can support wider participation, but they also become part of the cost and technical standard for entry.
Limited direct settlement is developing as a middle layer between full sponsor-bank dependence and unrestricted central-bank account access.
The distinction determines how much control new participants gain over liquidity, counterparties and settlement economics.
The UK Payments Vision programme links future retail payment technology with decisions about governance, commercial roles, procurement and accountability.
The UK model confirms that modernizing payments is also a decision about who sets the rules, funds the system and controls access.
Canada has created formal payment system pathways for more organizations. The commercial effect will depend on how many new members complete onboarding, enter production and gain enough control to improve their products or economics.
Some PSPs may participate directly. Others may still rely on settlement agents, technical gateways or incumbent financial institutions. Those choices will affect liquidity, operating costs, fraud responsibilities and the speed at which new services can reach customers.
Governance will be another test. New members may have a voice in Payments Canada consultations and rules, but it is too early to know how much influence they will have over system priorities, liability, pricing and future access requirements.
The customer outcome is also unresolved. Wider participation could produce more choice, better payment products and stronger competition. It could also leave control concentrated among the institutions that provide settlement, connectivity, fraud services and access to customer accounts.
Published standards can replace closed institutional relationships with clearer entry requirements. They can also raise the cost of joining and operating. The result will depend on whether qualified new participants can build differentiated services and reduce reliance on incumbent intermediaries without weakening security or consumer protection.
Do you agree the evidence is strong?
Click Agree or Disagree. Your vote is recorded anonymously and aggregate results are tracked.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 4, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Digital Assets Blockchain And Tokenization, Cybersecurity Fraud And Financial Crime, SME Finance And Business Banking, Capital Markets And Market Infrastructure, Policy Regulation And Governance, Risk Compliance And Regtech, Data Privacy And Governance

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-19, 2026, June 20-26, 2026, June 27-July 3, 2026).
AI training data now carries an auditable collection burden across source choice, legal basis, sensitive data and model output controls. Canadian fintechs using European personal data should map what is scraped, why it is needed, who controls the processing and how records can be filtered or removed before consultation language becomes supervisory practice.
Fund innovation depends on regulatory speed as well as product design. Asset managers, exchanges, fintechs, wealth platforms and regulators should watch how dedicated approval pathways and product specific guardrails influence the pace of retail investment innovation without reducing investor protection.
Swift is testing whether tokenized deposits can extend today's banking infrastructure into always available cross border payments without replacing existing settlement systems. The pilot results will provide an early benchmark for bank led tokenized payment networks.
Always on market design is moving beyond crypto. Exchanges, brokers, clearing firms, liquidity providers, risk teams and regulators should watch how 24/7 trading changes oversight, operations, margin, surveillance and market resilience.
Credit infrastructure is consolidating around data depth, identity coverage and alternative underwriting. Lenders, fintechs, credit bureaus, SME finance platforms and regulators should watch how alternative data, fraud controls and AI assisted decisioning affect credit access for thin file borrowers and small businesses.
Hong Kong is replacing a widely used authentication method across online securities and regulated virtual asset trading. Brokers and platforms also need stronger monitoring, client notifications and incident response procedures, while senior management may be held accountable for losses caused by inadequate controls.
The findings connect payment design directly to fraud exposure, customer friction and trust. Lower fraud by transaction count is encouraging, but higher losses by value and rising first-quarter fraud show why scale requires stronger authentication, transaction risk data and coordinated controls. These operating results add important context to the UK’s payment milestone and Canada’s trust framework.
Financial institutions and technology providers will gain a structured environment for testing AI security tools against European requirements. Firms serving the European market should prepare to demonstrate model safety, operational resilience and secure deployment before advanced systems enter critical financial operations.
AI cyber risk is now a financial stability issue. Banks, fintechs, payment firms, infrastructure operators, software vendors and supervisors should watch how AI vulnerability discovery, third party concentration, open source dependencies and cyber resilience planning become part of financial sector oversight.
Circle's trust charter places a major stablecoin issuer inside the U.S. federal banking framework. The pace of implementation, custody adoption and any future expansion into reserve management will show whether trust banks become the preferred operating model for regulated stablecoin infrastructure.
The paired licences let one regulated provider connect crypto conversion, asset transfers, conventional payments and payment accounts. Firms pursuing similar models across Europe will need to determine when MiCA authorization must be combined with payment permissions as their products cross from digital assets into fiat payment execution.
Crypto platforms are moving toward regulated multi-asset investment access. Exchanges, brokers, dealers, crypto platforms, regulators and investors should watch how derivatives, equities and crypto converge inside licensed investment platforms.
MiCA is becoming a market access gate for global digital asset firms. Banks, payment companies, custodians, stablecoin issuers, exchanges and compliance teams should watch how full EU authorizations shape cross-border crypto services, institutional distribution and regulated stablecoin infrastructure.
Eltropy is turning agentic banking into a platform market rather than a closed vendor product. The commercial question is whether shared controls, integrations and distribution can make specialized financial agents easier for smaller institutions to adopt.
Regulated AI adoption needs control infrastructure, not only models. Banks, insurers, telecoms, fintechs and compliance teams should watch how agent oversight, inference monitoring, shared IP and enterprise control planes become part of Canadian AI governance.
AI in retail finance is becoming a competition, consumer protection and fraud issue at the same time. Banks, fintechs, wealth platforms, insurers, lenders and compliance teams should prepare for AI agents, personalization, delegation, identity controls and new forms of consumer harm.
Large fintechs are testing direct charter strategies again. Lenders, BNPL firms, embedded finance platforms, banks, investors and regulators should watch whether major payment and credit firms choose bank partnerships, owned charters or hybrid models for the next stage of regulated growth.
Regulators are increasing both the reach and speed of financial misconduct enforcement. Firms now face faster detection, coordinated action across jurisdictions and far less time to correct weak promotion, reporting and compliance controls.
This week’s intelligence points to a more mature phase of financial innovation. Stablecoins are entering regulated banking structures, tokenized deposits are nearing live payment use, regulators are setting terms for continuous markets, and AI governance is becoming a practical operating requirement. In Canada, the Real Time Rail rules, PSP access model and planned Q4 launch show how domestic payment modernization is entering the same execution stage. Advantage will favour institutions that can combine trust, regulatory readiness and delivery at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Fintech Market Activity | Consumer Finance And Lending, Payments And Money Movement, Artificial Intelligence And Data, Fintech And Innovation
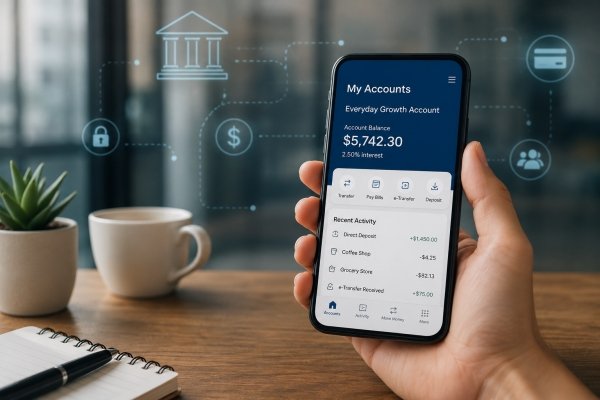
On July 7, 2026, Haventree Bank launched its Everyday Growth Account, adding direct digital deposits to a Schedule I bank known for alternative mortgages and insured GICs. The account pays 2.50% interest, has no monthly fee, no minimum balance, CDIC coverage, bill payments, Interac e-Transfers, EFTs, direct deposit, joint accounts, and up to eight accounts per user. Haventree is offering it through a new digital banking app.
This is not only a savings account launch. It is a competition test for Canadian banking. Haventree is using its bank charter, deposit protection, and digital distribution to compete for everyday balances at a time when consumers are switching more, open banking is advancing, and mortgage competition is becoming more data driven.
Haventree is a Canadian owned Schedule I bank, federally regulated by OSFI under the Bank Act. The bank says its current products include mortgage solutions and GICs, offered through brokers and financial partners. Its accessibility plan describes the bank as having about 290 employees and specializing in alternative mortgage solutions and insured GIC deposits.
Haventree already has regulated bank status, a mortgage business, broker relationships, GIC deposits, CDIC membership, and OSFI supervision. The new account now adds a direct daily relationship with consumers. Broker and partner channels can bring mortgages and GICs. A digital account can bring deposits, cash behaviour, app engagement, and future product paths.
For a smaller bank, direct deposits bring not only funding, but also customer data, trust, and a starting point for deeper relationships.
The timing is better than it would have been a few years ago.
Environics and Hay Research found that 24% of Canadians switched to a new financial institution in 2025 when opening a new account, the highest level in the study’s 20 year history. The study is based on more than 45,000 Canadians.
A related switching study report noted that online account opening accounted for 55% of switchers in 2025, up from 22% in 2013.
The research doesn't mean consumers will move primary accounts quickly, but it shows the market is less fixed than the old banking loyalty story suggests. A 2.50% rate can attract attention.
The harder challenge is whether customers will move direct deposits, bill payments, savings buckets, and idle cash into a new account. A strong interest rate starts the conversation, but habit decides whether balances stay.
Haventree enters a crowded field. Consumers can already compare EQ Bank, Oaken, Tangerine, Simplii, Wealthsimple Cash, KOHO, Neo, PC Financial, and other digital money products. The competitive paths however are different.
KOHO’s bank licence push shows a fintech trying to gain more control over banking operations. Wealthsimple’s banking feature expansion shows a financial platform adding spending, credit, and loan tools around an existing customer base. EQ Bank’s account expansion shows a digital bank adding more daily account use cases.
Haventree comes from the regulated bank side. It doesn't need to become a bank. It needs to make consumers care that it already is one.
Fintechs often compete on product design and speed while working around banking dependencies. Smaller banks can compete from inside the regulatory perimeter, but they still need a modern product experience and a clear reason for customers to switch.
Canada’s banking market is opening from both directions. OSFI’s streamlined approvals framework gives targeted new entrants a clearer route into the federal banking system. At the same time, existing federally regulated banks such as Haventree are adding digital distribution.
Open banking adds the next pressure point. Consumer driven banking is progressing through implementation, with read access and data mobility as the first phase. Canada’s proposed Consumer Driven Banking rules cover accreditation, consent, liability, security, service levels, fees, and violations.
If consumers can compare accounts, share data, verify income, connect budgeting tools, and switch products with less friction, smaller banks will need stronger digital channels before portability improves. And it's pretty clear that Haventree isn't waiting for open banking to mature before building that channel.
Haventree’s mortgage base also matters because lending competition is changing. Mortgage and credit competition are no longer only about branch reach, rate sheets, and broker relationships. Digital onboarding, document automation, income verification, alternative data, cash flow analysis, and AI assisted underwriting are changing how lenders assess borrowers and manage files.
EQ Bank and FundMore’s mortgage lending work highlights how AI tools can help optimize mortgage processing. FundMore and Senso AI also point to a broader lending trend where better data can shorten manual review, improve risk assessment, and support more responsive credit decisions.
For Haventree, direct deposits could become more than funding if the account gains adoption. Daily banking relationships can create useful customer context across savings, GICs, mortgages, and future credit products. That does not mean deposits automatically feed underwriting. It does mean the strategic value of account relationships rises as lending becomes more data driven.
With the launch now in market, the model needs operating proof. Useful evidence will include account openings, average balances, direct deposit uptake, e-Transfer activity, bill payment use, app engagement, GIC conversion, mortgage cross sell, customer acquisition cost, and whether Haventree adds cards, budgeting, credit, or open banking powered tools.
If those indicators grow, this becomes more than a product launch. It becomes evidence that smaller Schedule I banks can use digital accounts to compete directly for deposits while fintechs try to gain more control inside banking.
If they can't , it becomes a reminder that bank status and a competitive rate are not enough. Digital banking competition is won through trust, product depth, switching convenience, and repeated use.
If smaller Schedule I banks can win deposits through digital accounts, will Canada’s next banking competition come from fintechs becoming banks, or banks adopting fintech distribution before open banking makes switching easier?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016