




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 25, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Artificial Intelligence And Data, Fintech And Innovation
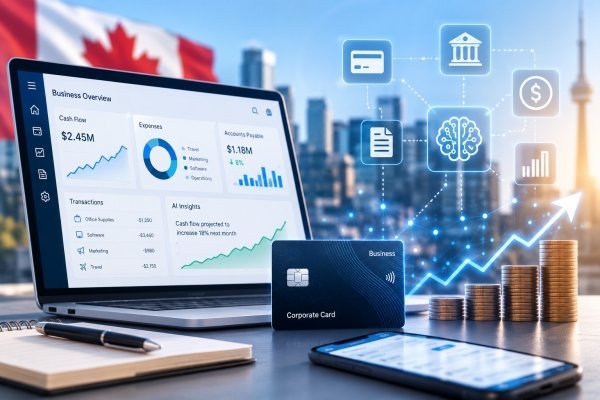
On June 24, 2026, Float Financial announced a CAD $85 million all equity Series C led by Inovia Capital, with continued participation from Goldman Sachs Alternatives and Garage Capital, and new investment from BDC Capital and Northleaf. Float says the round raises its valuation by 70% and brings total capital raised since inception to CAD $300 million, including debt and equity financing.
The financing gives Float more capital to expand its AI finance workflow layer, grow across Western Canada and Quebec, and hire across product, R&D, sales, and marketing. The company now serves more than 7,500 Canadian businesses and says revenue has grown more than 120% since its Series B.
Float’s own growth data shows how quickly Canadian business finance is moving from point solutions into connected operating platforms. Business account balances are up more than 4.5x, volumes across five products are up more than 100%, and nearly one third of customers now use more than one Float product which suggests Float is expanding inside existing finance teams rather than only adding new accounts.
Float gives Canadian businesses tools for corporate cards, expense management, bill pay, reimbursements, foreign exchange, business accounts, reporting, and working capital credit. The Series C adds more fuel to Float Intelligence, the company’s AI layer for automating finance workflows.
Rob Khazzam, CEO and co-founder of Float, framed the round around infrastructure:
“We are not building a single feature. We are building the infrastructure that powers how Canada does business - and proving that the best financial tools for Canadian businesses don't have to come from somewhere else.”
Canadian businesses want fewer disconnected finance tools. They need better control over spending, faster approvals, clean reporting, cash visibility, cross border payments, and finance workflows that don't depend on manual work.
Float says its platform is trusted by companies including Cohere, Knix, Neo, Jane, and Rebel. The Jane customer quote in the release points to the same theme: Canadian companies want AP, expense, and finance tools built for the Canadian market, not adapted from U.S. systems.
If Float keeps expanding across cards, accounts, payments, credit, and AI finance workflows, Canadian businesses may get a stronger local alternative to the tools many finance teams stitch together today.
Float secured $100 million in debt financing to expand SME finance in Canada before this Series C.
EQ Bank launched a Business Card, adding spending, cashback, interest, and cash flow tools to its SME banking stack.
Relay secured $50 million to grow its SMB finance platform.
Payments Canada admitted new payment service providers, including Float, as access to payment infrastructure opens to more fintech operators.
Canadian SMB banking research highlights high fees, credit friction, and outdated financial systems as ongoing barriers for business owners.
If Canadian businesses adopt one platform for spending, payments, cash, credit, and AI finance workflows, which institution owns the primary operating relationship: the bank, the fintech, or the software layer?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 24, 2026 | NCFA Insight | Capital Markets And Funding, Venture Funding And Building, Fintech And Innovation
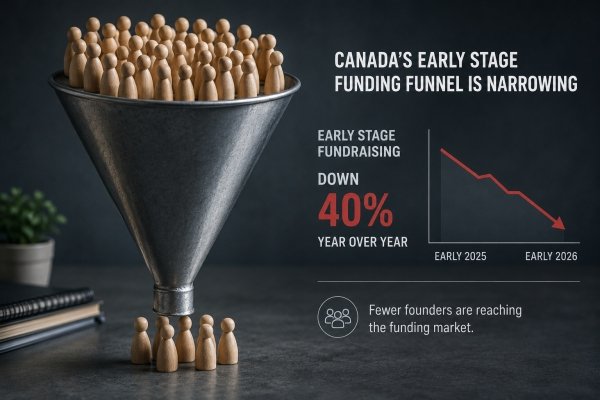
On June 24, 2026, RBCx published its Canadian VC 2026 Mid-Year report, showing that Canada’s early stage funding squeeze at venture funds is now also a startup company reality. RBCx says its Early Stage Banking team works with more than 1,200 pre seed and seed stage companies headquartered in Canada each year, and its current dataset covers more than 2,100 founder conversations.
The figures report that not only less capital is being raised, but fewer founders appear to be reaching the market at all. RBCx tracked 162 companies raising a combined $510.7 million in January 2025. By March 2026, only 61 companies were actively raising, with total capital sought down to about $189.8 million.
Average raise size held near $3 million from September 2024 to March 2026. That makes the data more troubling, not less. The market is not simply producing smaller seed rounds. It appears to be producing fewer founders who can raise them.
RBCx’s data suggests that early stage capital, which is often treated as the entry point into the venture system, is becoming harder to reach.
If fewer pre seed and seed companies are actively raising while average round size holds steady, the impact affects breadth of market.
Stronger or better connected founders may still complete rounds, but the number of companies entering the funding conversation appears to be shrinking.
A smaller early stage funnel means fewer companies get the chance to test markets, build traction, reach Series A, or become future scaleups. The risk is not only lower fundraising volume. It is a thinner innovation pipeline.
The company level data also connects back to the fund level pressure NCFA covered earlier this year in Canadian VC Fundraising Contracts And Concentrates In 2025. RBCx previously found that Canadian venture firms raised just over $2 billion in 2025, while the top five funds captured 83% of total capital raised.
RBCx’s mid year update says the top five funds captured 80% of total capital raised by 2025, while all other funds combined dropped from $4.5 billion at the 2021 peak to $444 million, close to a 90% decline.
When capital concentrates around fewer funds, founders face fewer decision makers, narrower investor funnels, and less room for non consensus ideas. That is especially important at the earliest stages, where conviction often depends on relationships, sector belief, and willingness to take risk before the metrics are obvious.
RBCx estimates that emerging managers raised about $2.8 billion over the past three years, compared with an expected $4.3 billion based on historical averages. That leaves a 36% funding shortfall.
Matt Roberts, Managing Director, Venture Coverage at RBCx, described the issue directly:
“Emerging managers are the engine of early-stage innovation in Canada. They’re willing to take on the riskier bets by backing first-time founders solving problems the market hasn’t fully recognized yet.”
His quote explains why this is a capital formation issue, not only a venture industry issue. Emerging managers often fund the companies that don't yet fit the pattern recognition of larger funds. When those managers cannot raise successor funds, Canada loses part of the market that is most willing to back first time founders, new categories, and early signals.
Canadian VC fundraising contracted and concentrated in 2025, with less new capital available for initial investments.
A built in Canada startup moved to the U.S., showing how capital access, customer depth, and market scale can influence where promising companies choose to grow.
Canada’s productivity challenge increasingly connects to capital formation, innovation scale, and the ability to turn new companies into durable economic output.
Targeted entrepreneurship funding remains an active policy tool as Canada tries to close founder capital gaps across underrepresented groups.
NCFA’s Financial Innovation Map tracks capital formation, alternative funding, venture infrastructure, and founder financing opportunities across Canada’s innovation ecosystem.
If Canada rebuilds early stage breadth, more founders can test markets, attract first capital, and create the next set of Series A candidates. That requires more than headline capital. It requires LP support for emerging managers, stronger growth stage confidence, and funding pathways that let founders raise before they fit the safest investor pattern.
Fewer funded companies may improve selectivity, but it can also remove the messy experimentation that produces outlier companies. If the ecosystem only funds the obvious companies, Canada may reduce failure rates while also reducing the number of breakout opportunities.
If average seed rounds remain stable but far fewer founders are raising, is Canada becoming more selective or simply losing the breadth and risk appetite needed to build the next generation of scaleups?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open finance can move SME capital access beyond static applications and backward looking credit files. The opportunity is to use permissioned business, financial, invoice, payment, accounting and treasury data to support better working capital, credit, invoice finance and treasury decisions.
Market sizing should not rely on one broad fintech TAM figure. The more reliable assessment is that several adjacent markets are converging: SME lending, embedded finance, invoice finance, working capital, open finance infrastructure and AI assisted credit decisioning.
The strongest opening is not simple cash flow underwriting. It is the decision and action layer that turns permissioned SME data into capital access: embedded working capital, real time credit, invoice finance automation and treasury optimization.
UK open finance experiments, CFIT SME prototypes, Canada Consumer Driven Banking implementation, Competition Bureau SME financing findings, embedded finance distribution, AI credit decision controls, invoice data standards, and early evidence that SME treasury optimization becomes a purchasable product rather than only a dashboard feature.
Evidence currently supports four venture scale paths. Connected SME data, cash flow underwriting and AI decisioning are enabling layers. They should not be treated as standalone product paths unless evidence later shows a distinct purchasable product category.
Capital inside SME workflows and platforms
SMEs often need capital at the point of activity: invoices, payroll, inventory, supplier payments, marketplace sales or software workflows. Embedded working capital uses platform context and permissioned financial data to offer capital where the need appears.
The innovation is not embedding a loan button. It is combining workflow data, financial data, repayment capacity and AI assisted decisioning so capital can be offered with better timing, fit and controls.
Platforms may prefer to partner with existing lenders or build lending directly, reducing room for specialist infrastructure providers.
Which embedded workflows create the clearest budget: accounting, PSPs, invoicing, marketplaces, payroll, procurement or vertical software?
Dynamic credit decisions from live business data
Real time SME credit uses fresh cash flow, account, payment, invoice, accounting and business data to support faster approvals, dynamic limits and ongoing reviews. It is different from mature cash flow underwriting when the credit product updates as business conditions change.
Potential buyers include lenders, banks, embedded finance providers, PSPs, accounting platforms and credit infrastructure providers.
If real time credit remains only a faster version of existing underwriting, the innovation window may be too narrow.
Can connected data support dynamic limits, early warnings, covenant style monitoring or instant credit decisions without creating unacceptable bias, privacy or model risk?
Receivables finance using invoice and payment data
Invoice finance automation uses invoice, accounting, buyer, payment and fraud data to decide whether receivables can be financed. The opportunity is stronger when systems verify invoice validity, buyer reliability, payment timing and repayment risk without manual PDF workflows.
This path may be distinct enough to survive as a child opportunity if evidence grows around invoice intelligence, receivables verification and automated funding decisions.
Invoice finance may remain a lender workflow improvement unless automation clearly reduces fraud, friction, cost or access barriers for SMEs.
Are lenders and platforms using live invoice and accounting connections to automate financing decisions, or only digitizing existing manual workflows?
Capital allocation and liquidity decisions
SME treasury optimization goes beyond monitoring. It uses connected financial data and AI assisted decisioning to help SMEs decide when to borrow, repay debt, hold cash, pay suppliers, finance invoices, invest surplus cash or allocate liquidity across accounts and payment rails.
This is currently earlier than embedded working capital, but it may become the most differentiated open finance path if evidence shows SMEs adopting decision products rather than dashboards.
If products remain cash flow dashboards or alerts without trusted action, this should remain an enabling feature rather than a product path.
Will SMEs delegate capital allocation, liquidity and financing actions to AI assisted treasury tools with human oversight?
Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 23, 2026 | NCFA Fintech Market Activity | SME Finance And Business Banking, Payments And Money Movement, Fintech And Innovation

On June 18, 2026, EQ Bank launched the EQ Bank Business Card, a reloadable prepaid Mastercard for Canadian small business owners that adds business spending tools to its digital Business Banking suite. For EQ Bank, the card turns the Business Account from a place to hold cash into something owners can use every day.
The product (unavailable in Quebec) offers:
The card extends EQ Bank’s Business Banking platform, which launched in October 2025 with a fully digital Business Account, Business GICs, free everyday transactions, up to 10 sub accounts, and Canada based customer support.
The new card connects to the Business Account and gives owners a real time view of balances and transactions. EQ Bank is trying to turn business banking into a working cash management service, not just a place to hold deposits.
Dan Broten, SVP and Head of EQ Bank:
“Canadian small businesses and entrepreneurs are managing so much in real time, from cash flow and payments to expenses and savings - and their banking needs to keep pace with the demands they're navigating.”
A prepaid business card works differently from a credit card. EQ Bank is targeting owners who want control over spend, access to existing funds, and value on balances without taking on credit checks, paperwork, monthly fees, or annual fees.
The cashback threshold signals the intended user. A business spending at least $10,000 per month is likely focused on cash flow, foreign exchange costs, and financial control rather than rewards alone.
For Canadian SMEs still dealing with high fees, credit friction, cash flow pressure, and fragmented digital workflows, the card is aligned with the push for better banking options for Canadian SMEs.
Loop and EQ Bank launched a multi currency SME credit card to help Canadian businesses manage cross border transactions.
Float’s SME banking research highlighted high fees, credit friction, and outdated financial systems as barriers for Canadian small businesses.
Canadian SME loan competition is under review as debt financing remains concentrated among incumbent financial institutions.
EQB’s PC Financial acquisition shows how the bank continues expanding its consumer banking and payments footprint.
NCFA’s Financial Innovation Map tracks SME finance and business banking opportunities, including cash management, approvals, forecasting, and liquidity gaps.
If EQ Bank can turn deposits, spending, interest, cashback, foreign exchange, and account visibility into one simple workflow, it may strengthen its claim as a challenger option for Canadian small businesses. The advantage wouldn't come from the new card, but from making daily business money management less fragmented.
The tension is that SME financial workflows are messy. Owners still rely on multiple tools for accounting, payroll, lending, payments, and reporting. A better card helps, but the bigger market question is whether digital banks can become the primary financial operating system for Canadian SMEs or whether specialized fintech tools keep owning the workflow around the bank account.
If Canadian SMEs can earn interest, spend, manage cash, and avoid fees from one digital banking stack, what else must a challenger bank add before it becomes the primary operating account?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 23, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Regulation And Policy
On June 22, 2026, Minister Rechie Valdez announced $173.7 million in renewed funding for the Women Entrepreneurship Strategy. The funding supports women entrepreneurs across Canada through the Women Entrepreneurship Loan Fund, the WES Ecosystem Fund, the Women Entrepreneurship Knowledge Hub, and program operations.
Capital gaps only disappear when financing, networks, and support actually reach the founders who face the gaps. The announcement isn't just another program renewal. It shows that Ottawa still sees access to capital, networks, data, and growth support for women entrepreneurs as an active market gap rather than a solved policy file.
The new funding includes $59 million for the Women Entrepreneurship Loan Fund, which supports partner organizations delivering loans of up to $50,000 to women business owners and entrepreneurs. It also includes $100 million for the WES Ecosystem Fund, $7 million for the Women Entrepreneurship Knowledge Hub, and nearly $8 million over five years for program operations.
The Loan Fund has already delivered more than 1,600 loans through partner organizations. Since its 2018 launch, the broader WES initiative has supported more than 500,000 women entrepreneurs. The federal WES program page also notes that only 17.8% of Canadian small and medium sized businesses are owned by women.
Those numbers give the announcement its real weight. The funding isn't meant to be only a social inclusion measure. It's capital infrastructure for a founder segment still underrepresented in business ownership, financing access, and growth networks.
Minister Valdez said women entrepreneurs “create jobs, strengthen communities and contribute to a Canada that is strong for everyone.” That is the public message. The operating issue is more specific: growth requires more than a loan.
Women founders need access to credit, but they also need buyers, mentors, procurement routes, export support, investor relationships, and data that helps programs see what is working. That's why the WES package includes ecosystem funding and the Women Entrepreneurship Knowledge Hub alongside loan capital.
This connects directly to NCFA’s long running focus on women partners, women entrepreneurs, and capital access. When women are missing from capital decision making, financing gaps can persist even when the quality of founders isn't the problem.
BDC launched a $250 million inclusive entrepreneurship initiative to support entrepreneurs facing systemic barriers, including women, Indigenous, and Black led firms.
Canada renewed the $189 million Black Entrepreneurship Program as a separate targeted initiative for Black entrepreneurs and Black owned businesses.
BKR Capital raised a $20 million first close for Black Innovation Fund II, targeting a $50 million final close.
J.P. Morgan’s women powered business report showed rising women led growth companies, equity investment, exits, and crowdfunding activity in the U.K.
Research on female entrepreneurship has long pointed to financial capital, human capital, and network access as connected growth constraints.
If WES funding reaches women entrepreneurs with real growth potential, the payoff may go beyond business starts. It could strengthen regional innovation pipelines, improve founder diversity in high growth sectors, and give more women led companies access to the networks they need to scale.
The challenge is execution. Loan capital can help, but it doesn't automatically solve procurement access, export readiness, investor networks, revenue growth, or later stage financing. The strongest test is whether renewed WES funding helps more women owned businesses move from support programs into durable commercial growth.
If targeted entrepreneurship funding continues, how should Canada measure whether women founders are gaining growth capital, not just program access?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 22, 2026
Retail distribution networks use systems for transportation and storage to move products from manufacturers to consumers. Organizations that grow across different regions require the ability to manage large amounts of inventory. Shipping containers are central to this process because they are a standardized and reliable tool for moving goods through the supply chain.
Logistics for retailers are different now because containers are efficient plus require less manual handling - these units are versatile, which allows businesses to transport and store products with consistency across ships, trains and trucks.
Shipping containers are efficient because they create a uniform system for moving goods. Workers can transfer containers between different vehicles without unloading the products - this process is direct, which reduces delays but also limits the chance that items will break.
Moving many goods in one container is a way to manage costs. Retailers combine shipments to fill the available space - this practice reduces total expenses and helps products arrive at distribution centers at the correct time.
Shipping containers are scalable solutions for retailers that are growing. Businesses increase their capacity - adding more containers as demand rises - this allows for growth without the need for large investments in permanent buildings.
Some companies go to buy used shipping container Vancouver to expand their capabilities - this choice is an affordable way to grow while keeping logistics flexible. Owners can place containers in specific locations to meet new inventory needs.
Moving inventory successfully is a requirement for retail operations. Shipping containers allow businesses to move large quantities of merchandise to warehouses and stores in an organized way. Regular schedules are easier to maintain when products are available.
Handling inventory is simpler when using containers - Products stay together in one unit until they reach their destination - this method removes unnecessary steps as well as helps retailers process shipments with speed and accuracy.
Shipping containers are useful for storage within retail networks. They serve as units for inventory that is waiting for distribution for short or long periods - this flexibility allows businesses to manage changes in consumer demand without building larger warehouses.
Organizations often choose to purchase shipping containers to create more storage space near their facilities - these units are a practical way to hold extra inventory while keeping the products easy to access.
Reliable supply chains are possible when the movement of cargo is secure. Shipping containers are made of strong materials that protect products from weather, theft and impact - these units provide a controlled environment for goods that travel long distances.
Predictability is better when distribution networks use standardized containers. Retailers can coordinate with transportation providers or warehouses more easily when everyone uses the same system. Consistency reduces interruptions and helps deliveries arrive on time.
Distribution centers are more productive when they buy shipping container. Receiving is simpler because shipments arrive in organized units. Personnel at the warehouse can unload and sort products quickly when the inventory is structured.
Space is used better within a facility when shipments are in containers. Goods move through the building with fewer steps - this efficiency leads to faster order fulfillment next to higher productivity for the warehouse.
Modern distribution networks use technology to improve how they monitor goods. Shipping containers can have tracking devices and sensors that provide information about their location and status - this data helps retailers make decisions plus fix problems quickly.
Managing inventory is more effective when technology is part of the container system. Retailers see where containers are in the supply chain, which leads to better planning and accurate delivery times. Visibility is helpful for operational performance and customer service.
Shipping containers are important for retail distribution because they support transportation, storage but also inventory movement. Their design helps retailers simplify logistics while reducing costs - these units are a significant tool for businesses that want to improve their operations and meet the needs of their customers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 14, 2026
Family-owned businesses across Canada offer a strong opportunity for entrepreneurs because many are already profitable, trusted locally, and ready for ownership transition. Instead of starting from zero, buyers can acquire an established business with customers, staff, systems, and reputation already in place, especially as more owners consider retirement or succession.
Family-owned businesses play an important role in Canada’s economy. They often operate in local communities for years or even decades, serving loyal customers and building strong reputations through consistent service and personal relationships. Many are owner-operated businesses where trust, reliability, and long-term commitment matter just as much as the products or services they provide.
For buyers, this creates a significant advantage. A family-owned company in Canada may already have an established customer base, experienced employees, dependable supplier relationships, equipment, and stable revenue. It may also benefit from a recognizable local brand and years of goodwill within the community. These are valuable assets that usually take considerable time and investment to develop from scratch.
For entrepreneurs researching acquisition opportunities, Canadian business for sale on Yescapo can be a useful starting point for finding established companies with existing operations, customer relationships, and market history. Instead of buying only physical assets, buyers gain access to business knowledge, working systems, and relationships that have often been built over generations.
This is particularly important in industries where reputation drives success. Local retailers, construction companies, restaurants, service providers, and manufacturing businesses often rely on repeat customers and word-of-mouth referrals. A well-established family business may therefore offer a competitive position that would be difficult and expensive for a new startup to achieve.
One of the biggest opportunities in Canadian family businesses comes from succession. Thousands of owners are approaching retirement after spending decades building successful companies, yet many do not have family members interested in continuing the business. Children may choose different careers, relocate, or simply prefer not to take on the responsibilities of ownership.
As a result, many profitable businesses enter the market despite having healthy financial performance and loyal customers. They are being sold not because they are struggling, but because the owner wants to retire, reduce day-to-day responsibilities, or ensure the company continues under new leadership.
For entrepreneurs, this creates a unique entry point into business ownership in Canada. Buying a family-owned business with established operations can provide immediate access to customers, revenue, trained staff, and existing systems while avoiding many of the challenges involved in launching a company from zero.
Understanding the seller’s motivation is an important part of the process. In succession transactions, owners often care deeply about preserving the company’s reputation, protecting employees, and maintaining relationships with long-standing customers and suppliers. Buyers who respect that legacy and present a clear plan for the future may find it easier to negotiate a successful acquisition and ensure a smoother transition after the sale.
Starting a new company usually means building everything from the ground up. The founder must test demand, find customers, create systems, hire staff, develop supplier relationships, and survive the early stage when cash flow is uncertain.
Buying a family business in Canada offers a different path. The buyer can study real financial records, customer history, contracts, equipment, employee structure, and market position before making a decision. This makes the process more practical and less based on assumptions.
A startup may offer full creative freedom, but it also carries higher uncertainty. A family business may come with older systems or traditional ways of working, but it also provides an existing customer base and proven business model.
For many buyers, the question is simple: why build market trust from zero when an established business for sale in Canada may already have it?
Family businesses are often attractive because they are built around long-term relationships. Many have repeat customers, local recognition, supplier trust, and employees who understand the business well. This can make the transition easier for a new owner.
Another advantage is stability. Many Canadian family businesses operate in practical sectors such as trades, retail, food, manufacturing, distribution, professional services, hospitality, and local services. These businesses often solve everyday needs rather than depend on trends.
A buyer may also find hidden growth potential. Some family businesses are profitable but underdeveloped digitally. They may have weak websites, limited social media, no online booking, outdated branding, or little paid advertising. A new owner can modernize the business without changing its core.
This is why many investors search for profitable businesses for sale Canada listings. They want companies that already work, but still have room to grow.
Family-owned businesses can be found across many industries and provinces. Some operate in large cities such as Toronto, Vancouver, Calgary, Montreal, and Ottawa. Others are based in smaller communities where local trust is especially important.
Common examples include restaurants, cafés, bakeries, convenience stores for sale, construction companies, repair shops, cleaning businesses, accounting firms, dental or wellness clinics, manufacturing companies, logistics businesses, landscaping companies, and specialty retail stores.
Buyers often look for businesses that are simple to understand and have steady demand. A local business for sale Canada opportunity may be attractive if it has repeat customers, reliable employees, clean financial records, and clear room for improvement.
Businesses with recurring revenue can be especially valuable. Examples include maintenance companies, B2B services, subscription-based services, commercial cleaning, bookkeeping, and companies with long-term contracts.
Retiring business owners are one of the main reasons family business transition is becoming important in Canada. Many owners have strong companies but no clear successor. They may be ready to step back, but they do not want the business to disappear.
This can create a more flexible acquisition process. Some sellers may agree to stay involved during a transition period, introduce the buyer to customers and suppliers, and train the new owner. This helps protect business continuity.
For buyers, this is valuable because the seller’s knowledge is often one of the most important assets in a family business. Understanding customer relationships, staff dynamics, supplier terms, and daily operations can reduce risk after the sale.
A good transition plan can make the difference between a smooth acquisition and a difficult one. The best deals usually include clear handover support, communication with employees, and a plan for preserving customer trust.
Before buying a family-owned business, due diligence is essential. The buyer should review financial statements, tax records, revenue trends, profit margins, debts, leases, supplier agreements, employee contracts, equipment, inventory, licences, customer concentration, and legal issues.
It is also important to understand how dependent the business is on the current owner. Some family businesses rely heavily on the founder’s personal relationships. If customers only trust the owner, revenue may fall after the sale unless the transition is handled carefully.
A buyer should also check whether family members work in the business and what will happen after the acquisition. Staff roles, responsibilities, salaries, and expectations should be clear before the deal is completed.
Buying an established business in Canada can be a strong opportunity, but only if the buyer understands the real numbers, the risks, and the operational structure.
Many family businesses have strong foundations but outdated systems. A new owner can often grow the company by improving marketing, technology, pricing, customer service, and operations.
For example, a local service company may have loyal customers but no strong online presence. A buyer could improve the website, SEO, Google Business Profile, paid ads, online reviews, and booking systems. These changes can increase leads without changing the core service.
A retail business might benefit from e-commerce, better inventory management, updated branding, or stronger social media. A B2B company could grow by improving sales processes, customer follow-up, and recurring contracts.
The opportunity is not always about changing the business completely. Often, it is about keeping what works and modernizing what holds the company back.
Many buyers assume they need the full purchase price in cash, but business acquisition Canada deals can be structured in several ways. Buyers may use personal savings, bank financing, investor capital, seller financing, or a combination of these.
Seller financing can be especially relevant in family business succession. This means the seller allows the buyer to pay part of the price over time. It may help the buyer complete the deal and give the seller confidence that the new owner is committed to the business.
Some deals also include an earn-out, where part of the final payment depends on future performance. This can be useful when the seller and buyer need to bridge a valuation gap.
Clean financial records make financing easier. A profitable small business Canada opportunity with strong documentation is usually more attractive to lenders and investors than a business with unclear accounts.
Family businesses can be excellent acquisitions, but they are not risk-free. Some may have outdated systems, informal agreements, weak financial reporting, or operations that depend too much on the founder.
There may also be emotional complexity. A family business is often personal to the seller. Decisions about employees, branding, customers, and legacy may matter deeply. Buyers need to handle the process with respect and clarity.
Another risk is hidden underinvestment. Some owners delay upgrades before selling. Equipment, premises, technology, or staffing may need improvement after acquisition. Buyers should factor these costs into the purchase price.
The best approach is practical: verify the numbers, understand the people, check the contracts, and plan the transition carefully.
Buying a family-owned business in Canada can be a strong strategy for entrepreneurs who want an established company rather than a startup. It offers access to customers, revenue, staff, systems, and local reputation from the beginning.
This strategy is especially attractive for buyers who are good at operations, marketing, modernization, and relationship management. They can take a business that already works and make it stronger.
However, it is not the right path for everyone. Buyers need patience, due diligence, capital, and the ability to manage people and change. A family business may be established, but it still needs leadership.
For the right buyer, Canadian family businesses can offer one of the most practical routes into entrepreneurship through acquisition.
The hidden opportunity in family-owned businesses across Canada lies in the gap between retiring owners and entrepreneurs looking for established companies. Many of these businesses have customers, revenue, employees, reputation, and operational history already in place.
Instead of starting from zero, buyers can acquire a profitable local company and improve it through better marketing, stronger systems, digital tools, and modern management. The opportunity is not only to buy a business, but to continue its legacy and unlock its next stage of growth.
For entrepreneurs searching for Canadian business opportunities, family-owned businesses may be one of the most overlooked paths to ownership.
They often have loyal customers, local reputation, proven operations, trained employees, and steady revenue. This gives buyers a stronger starting point than launching a new company.
Business succession is the process of transferring ownership from the current owner to a new owner. In family businesses, this often happens when the founder retires or no family member wants to take over.
Buying can be better if the buyer wants existing customers, cash flow, and a proven business model. Starting may be better for someone with a unique idea or limited acquisition capital.
You should check financial records, tax documents, debts, leases, supplier agreements, employee contracts, customer concentration, licences, equipment, and how dependent the business is on the current owner.
Yes. Buyers may use personal funds, bank loans, investor capital, seller financing, or earn-out structures. Clean financial records usually make financing easier.
Common examples include restaurants, cafés, retail stores, construction companies, cleaning businesses, clinics, manufacturing companies, repair shops, logistics businesses, and local service companies.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016