




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 20, 2026 | NCFA Market Activity | Quantum Security And Digital Finance
Image: Pixabay/geralt
On Mar 18, 2026, the 2025 ACM A.M. Turing Award recognized Gilles Brassard and Charles H. Bennett for foundational work in quantum information science, including the development of quantum cryptography. The award carries a $1 million prize and marks one of the highest global honours in computing.
Brassard’s work established early methods for secure communication using quantum mechanics, a field now directly tied to the future of encryption. While he didn't develop today’s post quantum standards, his research helped define how information can be secured against quantum-enabled attacks. That body of work went from advanced research to execution in August 2024 when NIST finalized the first post quantum cryptography standards for encryption and digital signatures used across financial systems.
As ACM President Yannis Ioannidis stated:
“Their work is an important foundation for the field of quantum computing and has fundamentally changed how we process, transmit, and secure information.”
Post quantum cryptography (PQC) refers to new encryption methods designed to remain secure even if future quantum computers can break today’s widely used systems today, such as RSA and elliptic curve cryptography that currently protect payments, digital identity, secure messaging, APIs, and financial data.
On Aug 13, 2024, NIST finalized three post quantum cryptography standards and announced that organizations should begin transitioning to them as soon as possible. NIST states these standards support encryption and digital signatures used to secure electronic information, including financial transactions and sensitive data.
NIST also states that no one knows exactly when a cryptographically relevant quantum computer will arrive, but some experts estimate it could be possible in less than 10 years. That uncertainty increases the risk because encrypted data can be collected today and targeted for future decryption under the harvest now, decrypt later threat model.
Canada has already set execution timelines. The Canadian roadmap for post quantum cryptography migration requires departments to begin planning in April 2026, report progress annually, transition high priority systems by the end of 2031, and complete remaining migration by the end of 2035. Canada’s national strategy for quantum communication and cryptography states that advances in quantum computing could undermine current encryption and threaten digital systems and data security.
For financial services, encryption now affects what gets built and what gets bought. Payments, identity, onboarding, APIs, messaging, custody, and long term data all rely on encryption that may need to be replaced or upgraded.
Quantum also reaches into blockchain based finance like stablecoins, tokenized deposits, wallet infrastructure, custody controls, and smart contract connected payment flows all depend on digital signatures and key management. NCFA’s earlier coverage of quantum safe stablecoins points to a market approaching US$250 billion and highlights how quantum safe controls are already being added to stablecoin settlement systems.
Buyers are starting to ask direct questions. Where is encryption used in the product. Which parts rely on current standards. What is the plan to upgrade. These questions and decisions are part of core financial workflows now and show up across payments messaging, identity systems, API access, document signing, custody, and stored data.
Vendors that can clearly show where encryption sits in their systems and how they plan to upgrade it will have an advantage as requirements tighten.
NIST standards are finalized and Canada has set migration timelines starting in April 2026, with high priority systems due by the end of 2031 and full migration by the end of 2035. That puts a clock on encryption used across payments, identity, APIs, messaging, custody, and long term data.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 19, 2026 | NCFA Feature | AI Finance Policy
On Jan 27 2026, the UK Financial Conduct Authority launched the Mills Review into the long term impact of AI on retail financial services to examine how AI could reshape consumers, firms, markets, and regulation through to 2030. NCFA flagged the review earlier in NCFA Weekly Fintech Intelligence Jan 24-30, 2026.
On Mar 4 2026, Innovate Finance submitted its response to the Mills Review, setting out where the UK fintech industry believes deployment will stall unless policy and infrastructure move faster. The paper cites Bank of England and FCA data showing 75% of firms now use AI, up from 58% in 2022. The issue is no longer whether AI adoption will happen. It is what still blocks firms from using AI inside live financial workflows at scale.
AI is clearly evolving from chatbot assistance to execution at scale. The submission describes AI agentic systems that can act on behalf of users. One example is an AI bot that handles everything from comparing mortgage deals to submitting the application and coordinating with conveyancers under user permission.
The value is no longer only in the model itself (ie. speed, quality, cost, expertise), but rather the full operational chain from customer permission to data access to execution to payment. That's why industry is focused on a stacked layer of tech solutions from Open Finance and Digital ID to payment access and rulebook friction to ensure AI can fully complete financial tasks.
The same logic applies to industry concerns over gatekeepers. As AI agents begin to initiate and route transactions, control moves to the layer that connects the agent to the payment method and the financial product. If that layer becomes concentrated, a small number of providers can influence access, routing, and competition.
The response uses real commercial examples and market data, highlighting that AI in finance is already underwriting, trading, core banking, and compliance.
The next phase isn't whether or not firms can build AI tools. It is whether regulation and infrastructure will allow them to use those tools in broader customer and transaction flows.
The stronger points made is that AI in finance won't scale on model quality alone. It will however scale on the stack around the model. That means smart data, Open Finance, Digital ID, fraud data sharing, wallet infrastructure, and payment access. Without those layers, AI stays stuck in narrow support roles. With them, it can move into lending, advice, payments, and automated execution.
That is why the response is more useful than another generic values and ethics based AI policy statement. It identifies where deployment slows, where control could become concentrated, and what has to move together if the UK wants AI to scale significantly inside financial services.
Canada is also building its next AI strategy. The federal government launched an AI Strategy Task Force in September 2025 as part of a 30 day national sprint, and later said it heard from more than 11,000 Canadians and 28 task force members. The Canadian process is broad. It is focused on national AI leadership, trust, safety, adoption, and public interest.
That broad approach is already raising execution questions. NCFA covered this earlier in its analysis of Canada’s AI strategy and capital flight risk, which argued that deployment, investment, and commercialization need clearer direction.
The UK industry response to the Mills Review is more targeted. It focuses on what is blocking AI deployment inside financial services today. Open Finance, Digital ID, payment access, wallets, third party model assurance, and rulebook friction sit at the center of that response.
Canada is still discussing the national direction of AI while UK fintech industry is already laying out what has to change for AI to work inside live financial workflows. The lesson for Canada is straightforward. AI policy cannot move on its own. Open Finance, Digital ID, wallet policy, payments modernization, and data access frameworks need to move with it or adoption in regulated finance will stay limited.
There is also a market structure lesson. If agent led payments grow, whoever controls the interface between the agent, the wallet, and the payment rail can control distribution. Policymakers who want competition and innovation to hold need to keep that layer open.
The industry response to the Mills Review is not just a call for clearer AI rules. It argues that the next barrier sits outside the model. Data access, identity, payments, and regulatory clarity now decide whether AI in finance stays at the support layer or moves into execution. The firms and jurisdictions that solve those bottlenecks will have the advantage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 19, 2026 | CIX Summit | NCFA Community Partner Update

The CIX Summit, Powered by Elevate, is almost here! This one day strategic conference for investors and founders takes place in Toronto on March 25, and this is the final window to secure your spot. If you are raising capital or actively investing, this is where founders and investors meet for conversations that can move toward real deals.
NCFA is a community partner because CIX brings a concentrated mix of high growth startups, active investors, and decision makers into one room, in one day.
CIX is built around access. Founders get in front of investors. Investors get direct exposure to companies that are actively building and raising. That opportunity gets tighter as the event gets closer. The strongest attendees lock in meetings early and show up with a clear plan.
NCFA has already covered the 2026 CIX startup award winners, the Wealthsimple Innovator of the Year recognition, and the CIX Summit 2026 agenda release. At this stage, the only question you need to ask yourself is whether you need to be in the room?
NCFA is sharing a 20% community partner discount on CIX Summit passes for its community.
Use CIXNCFA20 for 20% off. CIX runs on March 25, 2026 in downtown Toronto.
Secure your spot through CIX Summit 2026 ticket details and March 25 venue information.
If you are serious about raising, investing, or building relationships that can move a deal forward, register now.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 19, 2026 | NCFA Market Activity | Digital Assets
On Mar 18, 2026, licensed S&P 500 perpetual trading went live on Hyperliquid through Trade[XYZ]. The product gives eligible non US investors 24/7 access to leveraged long or short S&P 500 exposure without expiry. A core global equity benchmark now trades onchain 24/7.
S&P says its linked ecosystem drives $1T daily trading across futures, options, ETFs, and structured products. Moving that benchmark into a perpetual format allows liquidity to form before traditional sessions open. Early demand for the product already looks real. Decrypt reported $10M open interest shortly after launch, while S&P’s release says Trade[XYZ] markets on Hyperliquid have already cleared $100B volume since October 2025 and are running at more than $600B annualized.
Price discovery no longer has to wait for markets to open. If more benchmark trading starts off hours on crypto venues, traditional exchanges risk following market moves instead of leading them. Even a modest change in where liquidity shows up first can change how volatility spreads across markets.
Investors now have a route to benchmark exposure at any hour, across borders, on a venue built for continuous trading. That changes expectations around access, monitoring, and response time for exchanges, brokerages, data analytics and risk teams. It also raises risk with reports that the product can offer leverage up to 50 times, which means off hours trading can bring sharper liquidations and sweeping moves when order books are thin.
The global implication is bigger than one listing. A major index owner has opened a new channel for benchmark access on chain. That puts pressure on incumbents that still depend on fixed sessions, regional access, and legacy infrastructure. If this model gains traction, exchanges will need to defend their role not just on liquidity depth, but on speed, availability, and product reach.
Canadian fintechs, dealers, market infrastructure firms, and regulators should pay attention to how benchmark access is changing. If clients start expecting round the clock exposure and faster market response, organizations that stay tied to old windows may lose ground. Firms that build around new access patterns, stronger risk tools, and better market visibility will have a chance to capture more of the next layer.
This is not just a crypto wrapper on a known index. It is an early sign that benchmark distribution is starting to move onto new rails. The firms that adapt early can help shape where liquidity, data, and customer activity go next.
The next phase will depend on where liquidity builds and how quickly institutions respond. If trading depth increases on these venues, more benchmarks, sectors, and asset classes will follow into perpetual formats. That would push exchanges, clearing systems, and regulators to respond to a market that no longer operates in sessions. However, if liquidity remains thin, these products will stay a niche trading layer. The open question is how fast global capital markets will adjust to always on access?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 18, 2026 | NCFA Insight | Digital Assets And Tokenization
On Mar 17, 2026, the U.S. Securities and Exchange Commission issued a formal interpretation on how federal securities laws apply to certain crypto assets and certain crypto asset transactions with aligned support from the CFTC read the SEC’s March 17 press release on the joint crypto interpretation (and Fact Sheet).
This is a significant U.S. digital asset policy interpretation because it gives the market something it's lacked for a long time: a public classification system, a public lifecycle test, and public treatment of core activities such as staking, wrapping, and airdrops.
The old question of 'is it a security?' no longer sits only at the token level.
The SEC now says the answer can depend on the category of asset, the way it is sold, the promises around it, and whether those promises still matter later in the market.
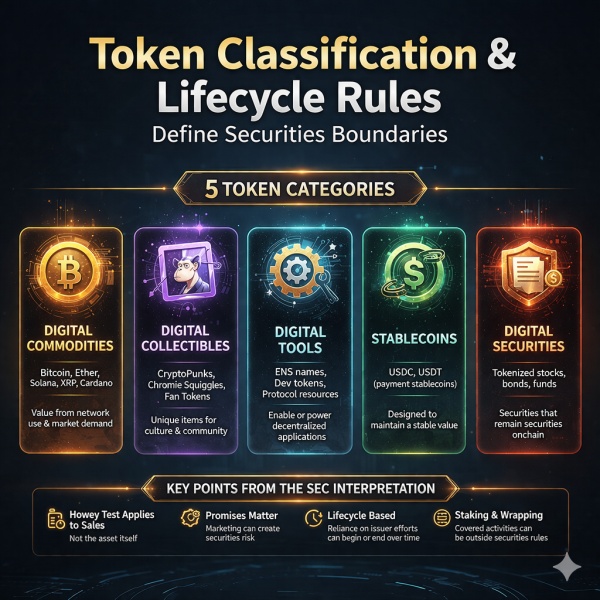
The release classifies crypto assets into five categories based on characteristics, uses, and functions: (1) digital commodities, (2) digital collectibles, (3) digital tools, (4) stablecoins, and (5) digital securities. It's a framework that crypto firms can actually use in product design, listing review, and compliance planning.
Some of the examples are worth noting. In the published interpretation, the SEC lists Aptos, Avalanche, Bitcoin, Bitcoin Cash, Cardano, Chainlink, Dogecoin, Ether, Hedera, Litecoin, Polkadot, Shiba Inu, Solana, Stellar, Tezos, and XRP as examples of digital commodities. It says these assets gain value from how the network operates and from market supply and demand, not from a team whose efforts drive profit expectations.
On collectibles, it points to CryptoPunks, Chromie Squiggles, Fan Tokens, WIF, and VCOIN.
On tools, it cites Ethereum Name Service domain names and CoinDesk’s Microcosms NFT Consensus Ticket.
The point is not that every asset that looks similar gets a free pass, and the SEC is now saying publicly that many crypto assets are not securities in themselves.
The SEC separates the token from how it is sold. It applies the Howey test to the transaction, not just the asset. A token that is not a security can still be sold as part of an investment contract if a team’s promises create an expectation of profit.
The interpretation then separates the asset from the contract and explains how that link can end. A non security token is no longer subject to an investment contract once buyers no longer rely on the issuer’s promises.
This can happen in two ways. The issuer fulfills what it said it would build, such as delivering functionality or completing roadmap milestones. Or the issuer abandons those efforts, making it unreasonable for the market to keep relying on them. In both cases, the investment contract can fall away, even though the issuer may still face anti fraud liability for earlier statements.
This directly addresses the secondary market problem. A token’s status in later trading does not depend only on how it was launched. It also depends on whether buyers still rely on the issuer’s promises at that point in time.
The SEC ties securities treatment directly to what issuers say. Statements in agreements, websites, whitepapers, and social media can create a reasonable expectation of profit.
That risk increases when issuers make explicit promises tied to roadmaps, milestones, funding plans, and how their work will drive value.
Token design and marketing cannot be separated. If the sales narrative links price appreciation to team execution, the offering can be treated as an investment contract.
For founders and counsel, that is the message. Product design, legal design, and communications design now need to be built together from day one.
The SEC says covered protocol staking activities don't involve securities transactions when structured as described. It covers self staking, custodial and non custodial staking, delegated and nominated staking, and liquid staking.
The interpretation is that rewards and penalties come from protocol rules, not from a team managing profits. That includes liquid staking models where users receive tokens tied to their staked position. If returns come from how the network operates, not from a promoter’s decisions, the activity is less likely to be treated as a securities transaction. That gives exchanges, custodians, and staking providers clearer ground for product design.
The SEC also says wrapping a non security crypto asset doesn't create a security when the wrapped token is redeemable one for one, the underlying asset stays locked for the holder, and value comes from that underlying asset. This supports cross chain use, custody design, and token mobility.
It also confirms that certain airdrops do not involve an investment of money under the Howey Test when recipients do not give anything in return. Common uses include rewarding early users, supporting governance, and building network participation. This does not make all airdrops safe, but it gives builders a clearer framework to separate distribution from securities risk.
The SEC aligns its position on stablecoins with the GENIUS Act. It says qualifying payment stablecoins issued by permitted issuers will not be securities once the law is in force. It also states that some covered stablecoins already fall outside securities treatment under its interpretation. This gives issuers and institutions clearer direction on how stablecoins are treated at the federal level.
Tokenized securities get a clear boundary. A security remains a security whether it is issued offchain or onchain. The SEC describes both issuer led tokenization and third party tokenization of existing assets. In both cases, moving an asset onchain may improve issuance and settlement, but it does not change its legal status.
This interpretation affects different parts of the market in different ways.
This interpretation shows what a more usable framework looks like in practice. While it doesn't solve every unanswered question, it's helpful and moves the debate from slogans to structure. Markets develop faster when participants can classify assets, model lifecycle risk, and design products in lie with public rules instead of trying to read the regulator’s mind from old enforcement cases.
The SEC doesn't replace the Howey Test but it makes Howey more operational for crypto markets. That's the real change. The release gives the industry a public map for classification, a public test for when securities treatment begins and ends, and public treatment of activities that sit at the center of token network design. If you're looking for more of a legal analysis here.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 18, 2026 | NCFA Fintech Market Activity | Banking Distribution And Market Expansion
On Mar 17 2026, BMO announced a multi year expansion of new financial centers in the United States, adding more than 130 locations in California and about 15 in Arizona over the next five years. BMO already operates more than 220 financial centers in California, so the new build represents growth of more than 50% in that state.
Seven California financial centers are scheduled to open in 2026, with three in Greater Los Angeles, two in the Bay Area, and two in San Diego. In Arizona, the bank plans to expand in Phoenix and Tucson.
BMO is betting on distribution by putting more capital behind in person, advice led banking in high growth U.S. markets at a time when many firms still talk as if digital channels alone will carry the next phase of growth.
BMO describes each new site as a modern financial advice hub covering personal and business banking, commercial banking, and wealth management. It is expanding to deepen relationships, cross sell more products, and win over higher value clients who still want face to face advice for borrowing, business growth, and wealth decisions.
This also shows that branch strategy is splitting by market. Some regions still face access pressure from branch closures, which NCFA has covered in rural cash access, while banks such as BMO are still adding physical advice hubs in faster growing urban markets.
That's the strategic point. Digital tools lower servicing cost, but physical distribution remains important when banks compete for trust, complex financial needs, and local business relationships.
BMO is also signalling confidence in the long term value of U.S. regional expansion. The bank says the new network across California and Arizona is expected to support hundreds of jobs over five years, while also investing in renovations and relocations across its existing footprint.
If TradFi banks invest in physical centers for advice, trust, and higher value relationships in growing urban markets is it because digital banking plus AI services are at risk of missing the mark?
In growth markets, a physical footprint can still be a customer acquisition and advisory asset if the banking experience moves from transaction counter to relationship hub.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 17, 2026 | NCFA Market Insight | AI And Operating Model Reset
On Mar 16 2026, reports that Meta may cut 20% or more of its workforce alongside plans for up to $135 billion in AI related capital spending point to an emerging pattern in how large technology firms operate in the era of AI. Companies are increasing AI investment while reducing headcount and restructuring teams to improve efficiency. Multiple large firms now follow the same pattern.
The sequence is becoming consistent across large technology and fintech firms, and the playbook is as follows.
Increase AI and infrastructure spend.
Reduce or flatten headcount.
Reassign work to automation.
Improve margins and operating leverage.
Rinse and repeat as necessary
Markets reward this because cost discipline becomes visible.
Meta is not alone.
While expanding AI infrastructure, Amazon has cut several hundred roles across AWS and other units.
Google cut hundreds of roles across Assistant, hardware, and engineering teams as it reallocates resources toward AI priorities.
Microsoft cut about 3% of its workforce while continuing to increase AI investment across cloud and enterprise products.
Dominoes? AI spending rises while workforce structures tighten around a new cost model.
And last month, fintech showed the same logic.
Block cut more than 4000 roles in an AI led cost reset while repositioning around automation and efficiency. Investors now expect fintech firms to translate AI into margin improvement, not just new features.
Payments, lending, and financial operations are structured workflows, which makes them easier to redesign around automation.
Fewer headlines at scale but the playbook is apparent.
Shopify requires teams to justify hiring against AI capability. Teams must show AI cannot do the work before adding people.
The new operating model mirrors fewer hires, higher output per employee, and clearer cost control.
The immediate impact of AI is not revenue growth. It is cost structure.
AI increases capital spending while reducing labour intensity, which alters operating leverage across digital businesses.
In fintech, this shows up as:
* automated fraud detection replacing manual review
* automated underwriting reducing analyst workload
* AI support systems replacing large service teams
The cost per decision falls. That is the first advantage.
This pattern will likely not stop at just large tech firms.
Public fintech and payments companies are now under similar pressure to show that AI improves efficiency.
Firms with large cost bases and heavy reliance on manual processes are the most exposed. That includes payments platforms, neobanks, and global processors where margins depend on operational scale.
Companies such as PayPal, Adyen, and other listed payment firms face imminent change. Investors will look for evidence that AI reduces cost per transaction, improves fraud outcomes, and increases operating leverage.
The question is no longer whether these firms use AI. It is whether AI measurably improves their cost structure.
Meta contemplating mass job cuts at scale further highlight a clear cost reset that's defining how digital businesses operate. Amazon, Google, and Microsoft reinforce the pattern. Block shows how it applies in fintech. Shopify demonstrates how it's taking up mental space and decisioning in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016