





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 18, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, Wealthtech And Investing
Image: Unsplash/Stephen Dawson
On June 18, 2026, Wealthsimple announced Wealthsimple Predict, a standalone app that will give Canadian retail investors access to prediction market trading through Kalshi.
The app is in beta and expected to launch this summer. At launch, Wealthsimple says it will offer access to nearly 4,000 event contracts trading on Kalshi, limited to the categories Wealthsimple is authorized to offer in Canada a range of event contracts across economic indicators, financial markets, and climate. Those contracts must also meet Wealthsimple's listing standards.
This is a distribution milestone for Canadian prediction markets. In March, Prediction Markets Tighten as Wealthsimple Enters tracked Wealthsimple's regulatory approval as Canada began testing a narrower, supervised route for event contracts. So with this active launch plan, that story is evolving from approval to retail access.
CIRO and the CSA reminded firms in April that event contracts remain subject to existing securities and derivatives rules. CIRO has said two dealer members are authorized to facilitate Canadian client access to event contracts. Public reporting and dealer materials indicate those firms are Wealthsimple and Interactive Brokers Canada.
Wealthsimple's own education material says event contract trading is legal in Canada under specific conditions, with guardrails around authorization, product categories, investor protection, and trading rules. Canada's version isn't simply a copy of U.S. political or sports prediction markets. It is starting with economic, financial, and climate contracts inside a regulated dealer pathway.
Event contracts are simple in structure but hard to operate well. Wealthsimple describes most prediction markets as binary contracts where users choose yes or no, and correct contracts pay $1 minus fees. Prices can act as probability estimates, but only when contracts are clear, liquid, supervised, and resolved properly.
Kalshi brings the exchange infrastructure. Wealthsimple brings Canadian retail distribution, education, onboarding, account experience, and investor guardrails. The combination is important for adoption. A prediction market with good contracts but weak distribution stays niche. While a prediction market connected to a large investing platform can test whether event contracts become useful market information, not only speculative trading activity.
NCFA's Innovation Opportunities in Regulated Event Contract Infrastructure brief identified the same gap. Regulated prediction markets need compliance, surveillance, market data, onboarding, dispute resolution, payout, risk, and investor education infrastructure. Wealthsimple Predict is a live validation point for that opportunity thesis.
The open question is whether or not event contracts will become sustainable information markets in Canada. If liquidity develops inside permitted categories, prices could help investors read market expectations around inflation, rates, climate outcomes, tariffs, currencies, and economic risk. If liquidity remains thin or contract design is weak, the information value will be limited.
As regulated prediction markets reach Canadian retail investors, will their main value come from trading activity, or from the real time probability data they produce for investors, policymakers, and markets?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 16, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization
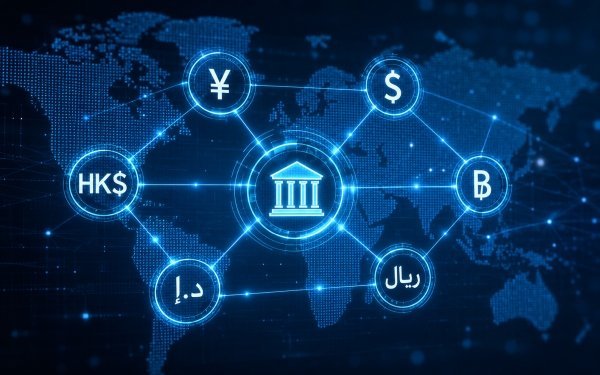
On June 14, 2026, the Financial Times reported that China is preparing mBridge for commercial rollout (subscription needed), with central banks from mainland China, Hong Kong, Thailand, the United Arab Emirates and Saudi Arabia involved.
The participating central banks haven't yet published a matching launch announcement. The Bank for International Settlements said mBridge reached minimum viable product stage in 2024 and that more central banks and commercial banks could join the legal framework and perform real transactions on the platform.
mBridge is important to watch because it tests a different model for cross border settlement. Instead of routing payments through long correspondent banking chains, participating central banks and commercial banks use a shared multi CBDC platform for payment and foreign exchange settlement. That makes the project a practical test of whether wholesale CBDC rails can reduce cost, settlement delay and liquidity friction in trade corridors where participating jurisdictions already have strong commercial ties.
mBridge began in 2021 with the BIS Innovation Hub, the Hong Kong Monetary Authority, the Bank of Thailand, the Central Bank of the UAE and the Digital Currency Institute of the People’s Bank of China. Saudi Arabia joined as a full participant in 2024. BIS also identified more than 26 observing members, including the European Central Bank, IMF, World Bank, Reserve Bank of India, Bank of Korea, Bank of France and the Federal Reserve Bank of New York’s New York Innovation Center.
The project has already gone beyond lab testing. The HKMA said the 2022 pilot involved 20 banks across four jurisdictions and completed more than 160 payment and foreign exchange transactions totaling over HK$171 million. It was among the first multi CBDC projects to settle real value cross border transactions on behalf of corporates.
BIS later said the MVP platform allowed participating jurisdictions to undertake real value transactions, subject to their own readiness. The project also created a governance and legal framework, including a rulebook, to match its decentralized operating model. That's why the current story isn't whether CBDCs can be piloted. It's whether participating jurisdictions can turn mBridge into operating payment infrastructure?
mBridge should be read alongside Project Agorá tests real money bank settlement rails. Agorá is testing tokenized commercial bank deposits and wholesale central bank money with major Western central banks and more than 40 commercial banks. mBridge is testing a direct multi CBDC settlement network among participating jurisdictions.
The difference is important for Canadian banks, exporters, fintechs and policymakers. Agorá is closer to upgrading existing correspondent banking through tokenized deposits and shared workflows. mBridge is closer to building a parallel wholesale settlement arrangement for selected currency corridors. Both are trying to reduce payment friction, but they reflect different governance choices, legal assumptions and geopolitical incentives.
The commercial test is liquidity, compliance and repeat usage. If real trade flows begin routing through mBridge, banks and payment firms will have to assess whether lower cost and faster settlement justify the legal, operational and supervisory work needed to connect to a new network.
The sensitive issue is whether a new wholesale settlement network can preserve anti money laundering controls, sanctions compliance, legal certainty and supervisory visibility across jurisdictions with different policy goals. Debate around mBridge's geopolitical implications has followed the project for years. See: mBridge could affect sanctions enforcement and payment routing.
In 2024, BIS General Manager Agustín Carstens said the BIS handoff of mBridge to participating central banks was not politically driven and was not a sign of project failure. He also said mBridge was not mature enough to operate commercially at that time and rejected the claim that it was designed as a BRICS sanctions workaround.
That tension remains central. If mBridge enters commercial use, participating institutions will need to prove that faster settlement isn't at the expense of enforceable controls, transaction monitoring, governance accountability or cross border legal clarity.
If wholesale CBDC networks start carrying real trade flows, how should Canada position payment modernization so Canadian banks, exporters and fintechs can participate in the infrastructure race instead of only reacting to it?
CBDCTracker, these Central Banks have Launched a CBDC or Pilot Initiative
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 6, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026).
Citi is combining traditional securities infrastructure with blockchain based issuance, custody, and settlement for private company equity. The launch adds another proof point that tokenized infrastructure is changing how markets operate, especially as banks, exchanges, and market operators compete to define how private assets move onto digital rails.
Digital asset access is being packaged for banks, brokerages, fintechs, and platforms that do not want to build the full crypto stack themselves. The control point is the embedded infrastructure that handles custody, liquidity, compliance, settlement, and connectivity behind the customer experience.
Tokenized real world assets are moving into bank distribution channels. DBS is turning physical gold into a digital product that can sit inside a retail banking app, while also testing institutional market access through its digital exchange.
Stablecoin supervision is moving from broad policy debate into operating rules. Issuers, custodians, exchanges, auditors, compliance vendors, and payment firms need to track how reserve custody, internal controls, audits, and service provider oversight become part of stablecoin market access.
Card networks are building trust infrastructure for AI driven payments. Visa’s updates add another network level proof point that identity, authorization, fraud controls, tokenized credentials, and settlement will shape how AI agents are allowed to transact.
Recurring payment rails are becoming a financial inclusion tool when they help users pay for digital services without relying on credit cards. Brazil’s Pix Automático data shows how local real time payment infrastructure can support subscriptions, platform access, and digital commerce growth.
Agentic payments are moving from checkout experiments into network infrastructure. Payment firms, AI platforms, stablecoin providers, banks, and identity vendors now have to solve authorization, spending limits, settlement, fraud controls, and liability for machines that can transact without a human at every step.
Large banks are building their own tokenized money infrastructure rather than relying on third party stablecoin networks. Payment providers, treasury platforms, and financial institutions now face a more competitive settlement environment as bank money, stablecoins, and tokenized commercial bank deposits compete for transaction flow.
Circle Payments Network continues to add distribution. Business accounts, treasury platforms, and payment providers are becoming part of the stablecoin settlement infrastructure rather than simply connecting to it.
Circle is extending its infrastructure footprint from stablecoins into Bitcoin collateral. Builders now have another institutional grade option for collateral and tokenized asset applications.
AI agents are moving from recommendation and discovery toward financial execution. Coinbase for Agents puts user controlled account access, payments, trading, and workflow automation into the same agentic finance conversation as network trust controls, stablecoin settlement, fraud prevention, and responsible AI governance.
AI supervision in finance is evolving from broad risk discussion toward operating practices for boards, senior management, compliance teams, model owners, technology vendors, and supervisors. Financial institutions need to track how governance, documentation, human oversight, cyber controls, and third party dependencies become part of responsible AI adoption.
Always-on markets need reference data that does not stop when traditional exchanges close. Exchanges, tokenized asset platforms, derivatives venues, market makers, and risk teams now have another pricing source to evaluate as real-world assets trade across crypto-native market infrastructure.
Prediction markets are starting to need the same financial plumbing as capital markets. Market makers, exchanges, payment providers, banks, and compliance teams now need infrastructure that can handle deposits, margin, settlement, risk controls, and regulated access without slowing down trading activity.
Prediction markets are moving from platform experimentation and court fights into formal rule design. Kalshi, Polymarket, DraftKings, Flutter/FanDuel, exchanges, market makers, compliance teams, sports leagues, and retail users now have a clearer process to debate which contracts belong in derivatives markets and which remain too close to gaming, misconduct, or public interest risk.
Financial crime compliance is increasingly becoming an existential regulatory issue rather than a supervisory issue alone. Payment firms, e-money institutions, fintechs, compliance teams, and investors should watch how regulators use governance, safeguarding, ownership, and financial crime controls as indicators of firm viability. The action signals that supervisory concerns can now lead to intervention measures that effectively remove a regulated firm's ability to continue operating.
Canada is pulling AI chatbots into platform safety regulation. AI firms, social platforms, trust and safety teams, identity providers, and compliance vendors should watch how age assurance, safety controls, reporting duties, and enforcement rules develop as digital safety becomes part of regulated online infrastructure.
Financial supervisors are beginning to treat AI as both a productivity tool and a threat multiplier. Banks, insurers, payment firms, fintechs, and security providers should expect greater scrutiny of fraud controls, cyber resilience, operational risk management, and third party technology oversight as regulators adapt supervision to an AI enabled threat environment.
Banking access is moving back onto the policy agenda as branch closures, digital exclusion, SME credit access, and local service gaps put pressure on financial providers. Banks, fintechs, credit unions, open finance firms, and data providers should watch whether the review leads to new access rules, credit data reforms, or stronger expectations around community banking infrastructure.
As advanced analytics become embedded in public institutions, governance questions increasingly extend beyond model performance. Procurement authority, accountability, oversight, operational dependence, switching costs, and public trust all influence how critical decision systems are adopted and maintained. The organisations that govern these systems may become as important as the organisations that build them.
The common thread is not AI, stablecoins, tokenization, or payments. It is access. Access to financial infrastructure, access to payment rails, access to private markets, access to banking services, access to digital assets, and increasingly access to machine driven financial execution. The next competitive battleground may not be who builds the best financial products, but who controls the rules, permissions, trust layers, and infrastructure that determine who can participate and under what conditions. Recent developments suggest those boundaries are on the move. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 11, 2026 | NCFA Story Intelligence | Payments And Market Infrastructure
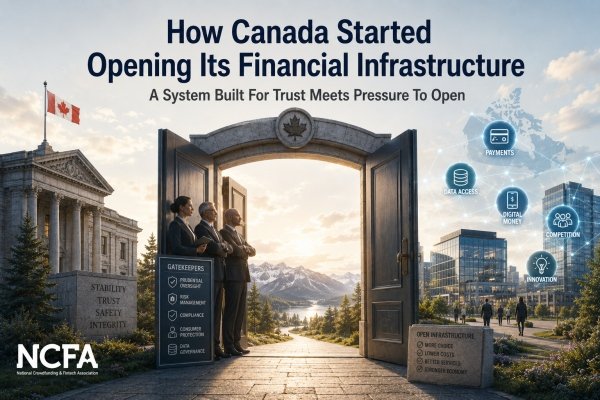
On June 3, 2026, Payments Canada announced that 15 organizations had joined its membership in 2026 following expanded eligibility rules. The latest intake included Beem Credit Union, Ebury Partners Canada, Shaype, Libro Credit Union, and Newton. Earlier additions included Wise Payments Canada, Float, KOHO, Neo Financial, Paramount Commerce, Brim, Meridian Credit Union, Tru Cooperative Bank, DoBusiness.com, and other newly eligible participants.
The membership announcement is the latest chapter, not the whole story. The story is how Canada moves from a tightly controlled payments model toward wider participation in the infrastructure that moves money, shapes competition, influences product design, and affects the choices available to consumers and businesses.
Canada builds its payments foundation around safety and trust.1 The Canadian Payments Association is created in 1980 under what is now the Canadian Payments Act. Payments Canada now owns and operates national payment systems including Lynx and the Automated Clearing Settlement System. The design reflects a clear priority: money movement is critical infrastructure, and critical infrastructure has to be reliable.
For a long time, that model works well enough for most people. Consumers trust their banks. Businesses use established payment tools. Settlement happens in the background. Most Canadians never need to think about who has direct access to the rails because the system mostly shows up as cards, transfers, bill payments, payroll, and cheques.
The market changes faster than the rails. Digital commerce grows. Mobile payments spread. Online transfers become a daily habit. Payments Canada’s 2025 trends report says Canada processed 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments representing 86% of transaction volume.2
Fintechs start building around systems they can’t fully access. KOHO, Neo Financial, Float, Wise Payments Canada, Paramount Commerce, Brim, and Newton grow because customers want simpler financial products. The problem isn’t demand. The problem is that many new firms still depend on infrastructure controlled by others.
Competition becomes the pressure point. Critics of Canada’s payments model argue that control by a small number of large institutions has contributed to high fees, delay, and limited competition. Reuters reported this criticism when the Bank of Canada began payment service provider registration under the Retail Payment Activities Act.3
The fintech argument becomes practical. If firms outside the largest banks can’t connect on fair terms, they often need intermediaries, workarounds, sponsorship relationships, or slower product paths. That affects costs, margins, speed to market, and the ability to challenge incumbents with better consumer and business experiences.
Ottawa starts changing the legal frame. Finance Canada says amendments to the Canadian Payments Act made on June 20, 2024 expand Payments Canada membership eligibility to Bank of Canada supervised payment service providers, credit union locals that are part of a credit union central, and designated clearing and settlement system operators.4
The Bank of Canada brings PSPs into supervision. Under the Retail Payment Activities Act, the Bank registers and supervises payment service providers and focuses on operational risk, incident response, safeguarding end user funds, and reporting. As of September 8, 2025, PSPs must have risk management and funds safeguarding frameworks in place.5
Real Time Rail becomes the execution test. Payments Canada says the Real Time Rail is planned for launch in Q4 2026 and will support instant, data rich payments through a new exchange, clearing, and settlement system.6 The promise is simple: money should move faster, carry better data, and support new products.
The delays create frustration because the opportunity is real. Payments Canada selected Interac as the exchange solution provider in 2021, when the system was expected to launch in 2022.7 NCFA has tracked the execution question through RTR delay coverage and RTR productivity analysis.
The first wave of PSP members makes the policy visible. Payments Canada welcomes Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim as new payment service provider members in January 2026.8 NCFA tracks that moment when Payments Canada admits five new PSPs.
Membership is not only about access to rails. Payments Canada’s by law changes update membership requirements and support new eligible members as Canadian Payments Act amendments come into force.11 Membership gives new firms a closer role in the rules, standards, and modernization discussions that shape the system.
That changes the politics of infrastructure. A fintech that has to build around the system is one kind of participant. A fintech that can join, comply, learn the rules, and contribute to modernization discussions is another. The same applies to credit unions, FX firms, and other payment providers that want a role in Canada’s next financial infrastructure chapter.
Consumer driven banking brings the same access debate to financial data. Finance Canada says the framework is meant to let Canadians securely access and share financial data with financial service providers, without fees for accessing and sharing that data, while reducing reliance on risky practices such as screen scraping.12 The Bank of Canada says it will administer the framework so Canadians and businesses can securely share financial data with approved providers of their choice.13
But the friction does not disappear just because the law changes. Tier one banks, fintechs, data aggregators, and policymakers still have to work through scope, liability, accreditation, implementation timelines, commercial terms, and API performance. NCFA’s open banking commercialization roadmap frames the next phase as real API usage, accreditation, liability, and business model design, not just a policy announcement.
Stablecoins pull the payments debate into digital money. Bill C 15 gives Canada a legal framework for stablecoins and consumer driven banking, moving both into the financial policy stack. NCFA framed that moment in Bill C 15 gives Canada a digital finance framework.
The payment infrastructure question is no longer only about bank rails. Stablecoins, payment service providers, RTR, consumer driven banking, and Bank of Canada oversight are starting to occupy the same policy conversation. NCFA’s question post on stablecoins as payment infrastructure shows why digital money now belongs in the same access debate.
Canada’s payments story now connects directly to productivity. The Bank of Canada has warned that weak productivity threatens living standards, and NCFA has linked payments modernization to execution, competitiveness, and growth. Faster settlement, better data, lower friction, and more competition are not abstract infrastructure benefits. They affect how firms operate every day.
Cross border capability becomes part of the same test. Canada’s payment system cannot only work well at home. Canadian businesses, newcomers, exporters, marketplaces, and financial platforms also need better global money movement. That is why NCFA’s cross border payments analysis belongs beside RTR, open banking, and stablecoins.
Canada’s payments infrastructure didn’t turn a corner overnight. The change reflects years of modernization work, policy debate, fintech pressure, consumer demand, and the practical reality that a digital economy needs payment systems that are safe, fast, open enough to compete, and trusted enough to scale. The result is a more diverse payments membership base than Canada had a decade ago, with fintechs, PSPs, credit unions, FX firms, and digital finance companies gaining a larger role in the systems that move money.
Opening access isn’t the finish line. It’s the starting point. Canadian fintechs, banks, credit unions, payment providers, regulators, and infrastructure operators now have to prove broader participation can become better financial services. Now is the time to get to work. Launch Real Time Rail, make consumer driven banking usable, widen the tent responsibly, improve domestic and cross border capability, lower friction for merchants and consumers, and connect these reforms to the Canadian Financial Innovation Map and pipeline Canada needs to compete.
Canada's infrastructure modernization is creating new commercial opportunities in Consumer Driven Banking. See NCFA's Open Banking in Canada Opportunity Brief for the evidence trail, product pathways, competitive benchmark and commercialization outlook.
Which part of Canada’s payments story stood out most to you?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 10, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain and Tokenization
On June 9, 2026, Eric Richmond joined Coinbase as Country Director and CEO of Coinbase Canada, giving the global crypto exchange a Canadian lead who has worked across trading, custody, regulation, and partnerships.
Shakepay named Richmond General Counsel and Head of Business Development in 2024, where his mandate covered legal, public policy, regulatory affairs, partnerships, new markets, and financial product opportunities. His earlier work also connects to Coinsquare and Tetra Trust’s regulated Canadian digital asset infrastructure, which now includes CADD, Canada’s first CAD-backed stablecoin issued by a regulated financial institution.
Coinbase Canada already has payment rails and regulatory standing. Coinbase's August 2023 Canadian launch gave Canadian users access to Interac e-Transfers through Peoples Trust, with Coinbase saying Interac was its most requested Canadian feature and that more than half of Canadian deposits in the prior month used Interac e-Transfer. In April 2024, Coinbase was approved as a Restricted Dealer in Canada, adding Canadian regulatory standing to its payment rail foundation.
Competition is tightening in the Canadian crypto market. Robinhood completed its WonderFi acquisition on June 1, 2026, bringing Bitbuy and Coinsquare into its Canadian platform strategy. Robinhood says Canadian customers will be invited into the Robinhood app, crypto trades will carry a flat 0.5% CAD trade fee, and WonderFi adds about 300,000 funded customers to Robinhood’s international base. Robinhood’s entry and Wealthsimple’s IPO Access launch are part of the current retail finance fight over access, pricing, loyalty, and who owns the customer relationship.
The Canada test is product access. Robinhood can use WonderFi as an entry point for a wider consumer finance app. Coinbase has a different challenge. It has to bring global crypto infrastructure into Canada in ways that fit local rules and user expectations. In 2023, Coinbase suspended USDT, DAI, and RAI trading for Canadian users shortly after launch, showing how Canadian rules can shape product availability even for large global platforms. That history matters now because Coinbase’s global strategy is tied more closely to USDC, Base, wallets, developer tools, stablecoin payments, and onchain financial infrastructure.
Canadian crypto adoption is real, but still shallow. Bank of Canada research found Bitcoin awareness near 93% in 2023, while ownership was about 9.9% overall and median holdings were about Can$500. Ownership was much higher among Canadians aged 18 to 34 at 19.1%. That leaves room for Coinbase, Robinhood, Wealthsimple, Shakepay, Kraken, Newton, NDAX and others to grow, with platforms competing on trust, funding rails, fees, custody, stablecoin access, and regulatory clarity.
Coinbase is moving beyond trading. Its Q1 2026 results say Coinbase holds more than 25% of total USDC in circulation, Base processed 62% of global onchain stablecoin transaction volume, and x402 has processed more than 100 million payments, with more than 99% completed using USDC. NCFA has also covered how Shopify, Coinbase, and Stripe are pushing USDC payments into mainstream commerce. Richmond’s job is to localize that broader infrastructure story for a Canadian market where crypto awareness is high, but deeper adoption still has to be earned.
Can Coinbase turn Canadian regulatory credibility, Interac rails, custody experience, USDC, Base, and global onchain infrastructure into local market share before Robinhood converts WonderFi into a broader retail finance platform?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 9, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL
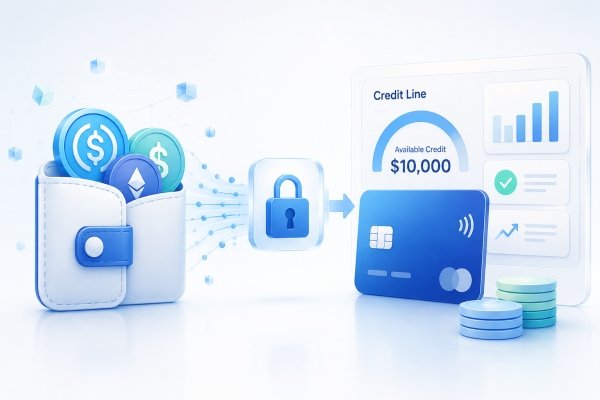
On June 9, 2026, Coinbase announced that it's expanding the role of USDC inside its financial ecosystem by a new Coinbase One Card program that allows eligible customers to secure a credit card with USDC held on the platform. Coinbase says the card can serve customers who might not qualify for a traditional unsecured credit card while continuing to participate in the Coinbase ecosystem.
The product adds another use case to a stablecoin that already supports trading, payments, transfers, rewards, and savings. Coinbase's documentation confirms the USDC security deposit model, where customers use USDC as collateral to secure their credit line.
The launch also highlights how fintech infrastructure providers are helping digital asset platforms expand into traditional financial products. According to a Cardless case study, Coinbase uses Cardless to power card program infrastructure, application workflows, servicing, and payment experiences. First Electronic Bank issues the card and American Express provides network access. The arrangement allows Coinbase to focus on customer acquisition, account balances, rewards, and product design while specialized partners handle card infrastructure and issuance.
Coinbase already has significant card activity to build from. In its Q4 2025 shareholder letter, the company reported nearly $800 million in cumulative Coinbase One Card spend and approximately $3,000 in average monthly spend per cardholder. The same filing reported $17.8 billion in average USDC balances held across Coinbase products.
The strategy aligns with the effort to make digital assets usable beyond trading. Earlier this year, Coinbase partnered with Better to bring crypto assets into mortgage workflows, allowing qualified borrowers to use digital assets during the home financing process. Together with the new card program, Coinbase is steadily expanding how digital asset balances can support borrowing, spending, and credit access.
The scale behind that strategy continues to grow across industry. Circle reported in its Q1 2026 results that USDC reached $77.0 billion in circulation and processed $21.5 trillion in onchain transaction volume during the quarter. As stablecoin infrastructure matures, questions around collateral design, credit access, and lending increasingly connect to broader discussions around tokenized collateral and cash.
If stablecoins can secure credit, platforms with large customer balances gain a new way to compete for lending relationships. The bigger question is whether consumers increasingly view stablecoin holdings as spending power, borrowing collateral, and financial reserves rather than simply digital payment assets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization
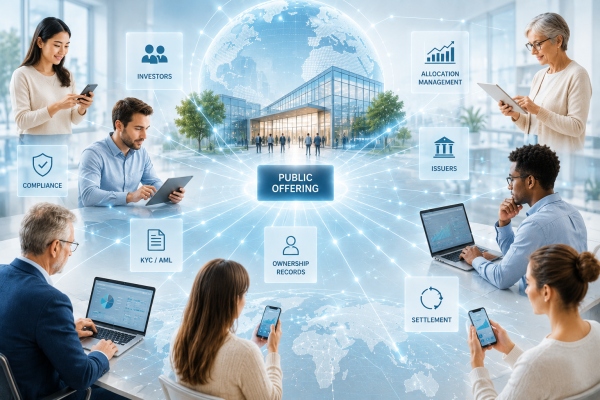
On June 7, 2026, Bybit launched IPO Express, a platform that gives eligible users access to tokenized IPO allocations starting with SpaceX. The launch arrives as SpaceX prepares for a public offering expected to value the company at approximately $1.75 trillion, making it potentially one of the largest IPOs ever. While the SpaceX name grabs attention, the bigger story is what this says about investor access, capital formation, and the growing role of digital infrastructure in public markets.
While the SpaceX name grabs attention, the bigger story is how firms are competing to expand investor access and improve IPO distribution.
Traditional IPO allocations typically flow through investment banks, brokerage firms, institutional investors, and private banking networks. Retail investors often participate only after public trading begins.
Bybit's model broadens access by allowing eligible users to subscribe through exchange infrastructure before trading starts. Investors can receive allocations and subsequently trade tokenized exposure through the platform.
The model combines several functions that have historically operated through separate systems, including investor onboarding, allocation management, compliance, custody, ownership records, and trading. Companies are now competing to modernize how investors access public offerings.
Much of the discussion around how tokenization is changing markets has focused on stocks, bonds, funds, real estate, and other assets after issuance. IPO Express focuses on an earlier stage of the investment lifecycle.
For decades, financial innovation concentrated around trading efficiency, lower transaction costs, and faster settlement. Tokenized IPO access targets a different challenge related to who gets access to investment opportunities in the first place.
Investor verification and eligibility checks now matter as much as trading access. So do allocation rules, ownership records, compliance controls, and settlement. Platforms that combine these functions in one clean workflow may earn an advantage as capital markets become more digital.
Canada has already seen similar efforts to expand investor participation through equity crowdfunding, online exempt market platforms, private market technology, and digital investment platforms.
Canada already has a live comparison point. Wealthsimple’s IPO Access for Canadian retail investors broadens access through a brokerage account, while Bybit’s IPO Express adds a tokenized layer around allocation and trading. Both are aiming to solve the same pressure in capital markets: retail investors want earlier access, cleaner digital onboarding, and a fairer shot at high demand offerings.
NCFA’s Who Gets Capital As Funding Channels Multiply? asks the same core question for Canadian markets. More channels don't automatically create better access for every founder or investor.
Tokenized IPO access brings the same access and onboarding pressure to public exchange listings. For Canada, the practical question is whether regulated platforms can use digital infrastructure to make capital raising easier without weakening disclosure, custody, suitability, or investor protection. That question fits NCFA’s financial innovation market infrastructure research, where access to capital, tokenization, compliance, and investor trust now overlap.
If retail investors can access high demand offerings through faster digital channels elsewhere, how long can domestic platforms rely on slower, relationship driven distribution models?
The competitive advantage may no longer come from who controls the allocation. It may come from who makes access easiest while still meeting regulatory requirements.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
