




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Crypto Asset Policy | Oct 15, 2025
Image: Freepik AI
In August 2025, Quebec’s Financial Markets Administrative Tribunal issued its decision in AMF v. Gagnon et al. that examined whether tokens linked to a crypto trading signal subscription service were investment contracts under Quebec’s Securities Act or not. The respondents ran an online business that sold memberships through social media and a Telegram group, offering automated buy and sell recommendations for digital currencies such as bitcoin. Investors paid recurring fees to receive trading alerts and access private chat rooms.
The tribunal found that the respondents misled subscribers and exaggerated claims about profit potential without proper registration. However, it also ruled that the tokens and the trading signals themselves weren't securities. Investors acted independently (i.e., placing their own trades), and there was no pooling of funds or shared enterprise that would meet the legal test for an investment contract in Quebec.
It's an important ruling because it draws a clear line between activities that require securities registration and those that do not. The decision has prompted discussion across Canada about how regulators should evaluate crypto asset business models (subscription required).
The tribunal focused on how the Gagnon business actually worked, not how the business is described or the types of tokens involved. The respondents sold subscriptions to a crypto signal service through social media and Telegram. Members paid recurring fees (usually in crypto) to access automated trading alerts and private discussion groups. The tribunal found that subscribers of the service acted independently because they placed their own trades, used their own accounts, and there was no pooling of funds or shared enterprise.
Because the respondents did not issue tokens, manage capital, or control investor profits, the activity did not meet the legal test for an investment contract. The tribunal said speculation alone does not make a trading service or token a security.
David Durand, Founder Durand Lawyers and NCFA Advisor, was interviewed for the Law360 article on legal classification of crypto assets, who argued that each crypto asset and business model must be assessed on its economic reality, not through one universal rule.
“The fact that securities regulations would have scant effect in protecting users on decentralized networks makes it evident that defining crypto assets as a security would provide ineffective regulatory enforcement in this respect. "[Overreaching securities regulation on the crypto asset regime would] likely create a system where onerous requirements are placed on users of such assets, with an end result of suppressing innovation [in financial technology and financial capital to leave Canada seeking more favourable environments]."
“The important point here is that the tribunal says a crypto asset is not an investment contract. However, when we criticize the act of trading an asset, we are referring to the investment contract in relation to the person and not the object or the very nature of the crypto asset. The implications are that we are moving in the right direction in terms of the fact that crypto assets were not an investment contract.”
Although the decision applies only in Quebec, its reasoning may influence regulators across Canada. The Canadian Securities Administrators have been moving toward coordinated rules for crypto trading platforms, but this ruling highlights the limits of the CSAs current approach when activities vary so widely in design.
The tribunal also said regulators need stronger evidence before using enforcement tools like freezing orders. It ruled that authorities must show clear proof before stopping a business from operating. This could set a new standard for fairness in future crypto cases.
For fintech founders, the ruling gives clearer guidance on what falls inside or outside securities law. Businesses that offer decentralized tools, such as trading signal services, software systems, or network platforms are less likely to be treated as securities, if users of those tools remain in control of their own money and avoid profit sharing and collective investment components.
For regulators, the case is a reminder to focus on real misconduct instead of labelling all crypto activity as securities by default.
The Gagnon reasoning parallels the SEC v. Ripple Labs decision in the United States, where a U.S. court drew a line between tokens sold directly by a company and those traded later on the open market. The court said that how and where a token is sold makes a difference. When people buy directly from the issuer based on its efforts, the sale can fall under securities law, but trades between independent buyers and sellers on exchanges may not.
Europe’s Markets in Crypto-Assets (MiCA) regulation offers another useful example. MiCA builds specific legal categories for utility tokens, payment tokens, and asset-referenced tokens, instead of applying one framework to all.
Canada has yet to create a similar set of purpose-based rules, leaving courts and tribunals to fill the gaps through case law.
The Quebec tribunal ruling strengthens NCFA's call for a coordinated national digital asset framework that distinguishes between token types and activities. Further, Canada can draw from both MiCA’s structured taxonomy and the functional reasoning used in Ripple and Gagnon. NCFA continues to recommend that policymakers should now focus on:
The Gagnon ruling challenges Canada’s regulatory system to evolve beyond the one-size-fits-all treatment of crypto assets. The tribunal recognized that each digital asset and business model carries distinct risks and economic activities.
One brush does not fit all. Crypto assets differ in structure, function, and purpose. Regulation must be designed for growth, not just enforcement. As NCFA recently argued in “Regulating for Growth by Understanding Innovation”, good regulation should reward experimentation, promote competition, and provide safe entry points for new entrants, not block innovators out of fear.
If Canada wants to compete in digital finance, it must build laws that reflect how crypto businesses actually work, support new ideas, and focus on misconduct, not label everything a security first.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
CZ | Oct 14, 2025
Image: Freepik/wirestock
Changpeng Zhao (known as CZ) pleaded guilty in November 2023 to a single count of violating the Bank Secrecy Act after U.S. authorities found Binance had failed to maintain effective anti-money laundering controls. He stepped down as CEO and was sentenced in April 2024 to four months in federal prison while paying a $50 million fine. Binance also paid $4.3 billion to settle related charges with the Department of Justice and other agencies.
In May 2025, Zhao stated publicly that he had applied for a presidential pardon from Donald Trump. The U.S. Senate Banking Committee confirmed the filing’s existence in a letter dated May 15, 2025, asking the Department of Justice and the White House to clarify whether the request was being considered. The senators cited potential conflicts of interest tied to Trump family business ventures connected to crypto ventures associated with Binance.
On October 10, 2025, journalist Charles Gasparino reported on X that White House discussions about a possible pardon were “heating up.” The New York Post followed with a story two days later describing alleged internal debates over optics as the Trump administration manages several crypto-related policy files.
The article references unnamed sources close to both Zhao and Trump, who claim the president is sympathetic to Zhao’s case but mindful of potential conflicts due to family business interests in the crypto sector.
No formal statement from the White House, the Department of Justice, Binance, or Zhao’s legal team has confirmed these discussions. The White House press office maintains a standard position of not commenting on active or potential pardons. Therefore, these claims remain based only on Gasparino's report and subsequent media coverage.
Even without confirmation, the story matters because a pardon could erase Zhao’s criminal record, reopening the possibility for U.S. financial institutions to engage with Binance or its affiliates under less restrictive compliance terms.
It could also influence broader perceptions of how the U.S. balances enforcement with innovation across the $4 trillion global digital asset market. The Senate Banking Committee’s letter highlights bipartisan concern about transparency in how executive clemency intersects with crypto business interests, and spotlights growing concerns between pro-market reform vs accountability for compliance gaps in digital finance.
As of October 14, 2025, verified information is limited to Zhao’s conviction, sentencing, fines, and his publicly acknowledged pardon petition. Otherwise, there is no public record or filing in the Office of the Pardon Attorney showing that any pardon has been granted or is under formal review.
Until official confirmation appears, the case stands as a reminder that anonymous political reporting must be treated cautiously, especially if it could affect markets and trust in financial governance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Cybersecurity | Oct 14, 2025
Image: Freepik
The 2025 Nobel Prize in Economics was awarded to Joel Mokyr, Philippe Aghion, and Peter Howitt for showing that economies grow when they reward new ideas, open competition, and constant renewal. Their work (and recognition) explains why some economies continue to grow while others stall, or how innovation drives prosperity.
Joel Mokyr’s research reveals that progress depends on how societies treat knowledge. When Europe opened up to new ideas, rulers across Europe competed to attract inventors, scientists, and thinkers. They funded experiments, founded academies, and allowed freedom to publish and debate. This open culture created trust and collaboration, which led to faster discovery. Insight is that innovation takes off when knowledge is shared, incentives are aligned with progress, and institutions reward learning rather than control.
Philippe Aghion and Peter Howitt built the modern model that explains how this process sustains itself. Their work on creative destruction shows that growth happens when new firms and technologies replace outdated ones. Productivity increases even as some firms exit the market. They demonstrated that competition and innovation are not opposites but partners. Economies that encourage entry and tolerate failure grow faster because resources move to better ideas. Insight is that protection slows progress, but experimentation drives renewal.
Sounds familiar, right?
A popular LinkedIn post by a specialist in regulatory policy Martyn Hopper, interpreted these Nobel insights into a practical framework for today's economies. In his aptly titled LinkedIn post, “Regulating for Growth”.
Hopper explained that innovation only turns into prosperity when three things work together:
When these conditions are in place, disruption becomes productive renewal. When they are missing, it produces dislocation, stagnation, and political frustration.
Hopper’s key insight reframes regulation itself. He says the real challenge is not cutting rules but designing them to direct energy toward innovation rather than rent-extraction (read: siphoning off profits for benefit).
Regulation is the architecture that decides who can participate, how capital flows, and whether progress is rewarded or resisted. It determines whether a system produces creation or protection, renewal or capture. This makes regulation one of the most powerful economic tools for growth.
As Canada has it's back up against the wall in terms of innovation and competition policy (despite recent shifting winds), the Nobel findings and Hopper's sensibilities, business leaders and policymakers have clear takeways.
The best performing economies are those that combine competitive markets with policies that support transition. For policymakers, the lesson is that regulation must make innovation easier, not riskier. It must reward entry and experimentation, ensure fair access to finance, and help communities absorb change. Sustained success comes from openness, agility, and willingness to reinvest in new ideas. Remember, a system without the ability to expel old and add new will eventually die on the vine.
Growth is designed through the choices made about who can compete, how ideas are financed, and how regulation treats innovation. When those choices are right, economies attract investment, scale technology faster, and sustain higher productivity.
For Canada’s fintech and financial innovation community, these insights are especially timely. NCFA’s advocacy for proportionate rules, open and fair competition, and technology-driven productivity and inclusion innovation aligns directly with the Nobel research and Hopper’s interpretation.
Canada's challenge is evolving from purely risk management towards opportunity design. Regulators can accelerate innovation by creating flexible entry routes for new players, supporting data-driven compliance, and directing finance toward startups and scale-ups that drive transformation.
It's about injecting newness and opportunity which in turn will build resilience. When innovation is supported by sound regulation, it strengthens the economy’s ability to adapt, protects consumers, and expands access to capital.
Fintech, open banking, and AI can be powerful enablers of this change if the regulatory system is built for learning and collaboration rather than delay and protectionism.
The Nobel Committee recognized that growth doesn't happen by accident. It's built through systems that enable innovation, reward competition, and manage transition. Martyn Hopper’s framework shows what that looks like in practice. Smart regulation channels capital to new ideas, supports those affected by change, and keeps markets open for renewal. For Canada’s fintech sector, this is the roadmap to back that turns creative disruption into long-term competitiveness, productivity, and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments | Oct 2, 2025
Image: Ron Morrow, Executive Director, Bank of Canada (CPA The One Conference Sep 18, 2025)
On September 18, 2025, Ron Morrow, Executive Director of Payments Supervision at the Bank of Canada, delivered a speech at the CPA The One conference titled, "Making change Accelerating payments innovation". He spoke about a vision for Canada’s payments future, one where innovation, oversight, and competition intersect. Stronger oversight and modern payment rails will make the system more competitive and inclusive.
This article unpacks select key quotes and and highlights two sides of the coin for stakeholders to see both sides and the trade-offs that come with it. For Canada, the task now is not whether to act, but how to add momentum and keep pace in a global race.
“Almost 1,500 payment service providers are now required to register with the Bank under the Retail Payment Activities Act.”
For the first time, nearly fifteen hundred retail Payment Service Providers (PSPs) are being pulled into the regulatory fold. Supporters argue that this gives consumers and businesses more confidence when using new services and helps fintechs compete on equal footing with banks. By ending the perception that startups operate in a grey zone, it could make investment in the sector more attractive.
But compliance comes with costs, and many small firms run lean without a large legal or regulatory staff like banks. What may feel like light reporting to a large bank can feel like a heavy lift for a ten person startup. In the worst case, it could drive consolidation that narrows competition instead of expanding it.
“Our job is to make sure that innovation in the payments system can proceed in a way that is safe, sound and reliable.”
Safe to say that Canadians will only embrace new forms of payments if they trust them to work without interruption and to protect their money. Regulation that sets clear expectations can provide certainty for innovators, giving them a stable foundation to build on.
Yet safety can lead to an abundance of caution that could slow innovation. Other countries, from the UK to Singapore, have shown that regulators can allow pilots and sandboxes to move quickly while still managing risk. If Canada puts too much emphasis on stability, we'll fall behind in a global race where trust and speed both matter.
“We are working to expand access so that more providers can offer services directly through Canada’s core payment systems.”
Direct access to national infrastructure is potentially transformational. If fintechs can gain access without going through a big bank, they can offer faster and cheaper payments. This would lower costs for consumers, ignite competition, and open the door for creative new services in areas like cross border transactions.
The flip side is that these core systems were designed with large, well capitalized institutions in mind. Smaller entrants may not have the same buffers to handle liquidity shocks or technical breakdowns. One major failure could undermine confidence across the entire network. The challenge is designing an access model that widens competition without weakening stability. Payments Canada who is overseeing Canada's payments modernization has delayed implementation numerous times, and industry is frustrated. In May 2025 however, they announced that the technical build will be completed by Q3 2025 and they plan to test the system throughout 2026.
“Through our work with the BIS Innovation Hub, we are exploring the potential of new technologies such as tokenization and artificial intelligence.”
Engaging with international financial innovation hubs allows Canada to stay connected to the latest fintech and payments research, including stablecoins and tokenization. It also helps Canadian fintechs align with emerging global standards, making cross border scaling easier. Last June 2024, the BIS and Bank of Canada Launched the BIS Toronto Innovation Centre.
The real risk lies in harmonization at home. Canada’s financial system is driven by a concentrated banking sector and diverse regional economies, where inter-provincial differences can create barriers to trade and investment. If newly adopted financial technologies and related reforms aren't designed to work seamlessly across all provinces and territories, Canadian markets could become further fragmented with unwanted barriers and compliance costs. Canada needs to strengthen its internal market with more competition and innovation to be able to complete with strength globally.
“Payments innovation cannot be separated from broader efforts like open banking.”
If Canada completes payments modernization while also enabling consumers to share their financial data securely (open banking, consumer driven finance), the market could see a boon of new service models and tools that bring real competition to a system long dominated by incumbents.
Skepticism is very real though with Canada lacking the political will to finally implement open banking after promising it and studying it for years. Without binding timelines, many in the industry hear speeches like this one but actions speak louder the words. For fintechs, the question remains whether it is worth investing in solutions that depend on open banking when political momentum has not yet delivered results, or opt for new pathways. The latest is that open banking in Canada will land in 2026., with further delays will have significant consequences for innovation and consumer choice in Canada.
Ron Morrow’s speech delivers a clear vision and direction for modernizing Canada’s payments landscape. Expanded oversight, broader access to rails, and participation in global innovation networks all point to a more open and competitive future. If open banking also arrives in 2026, these reforms could unlock real benefits for consumers and fintechs alike. But the devil’s advocate cannot be ignored. Here's a streamlined version of Morrow's speech, 'Cashing in on Payments Innovation' (fingers crossed)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crowdfunding | Oct 1, 2025
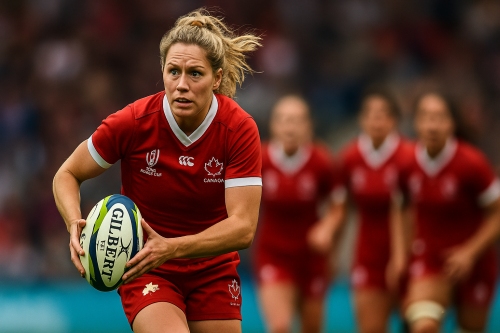
Image courtesy of AI
On March 7, 2025, Rugby Canada announced a bold public campaign to fund its women’s high performance team to England 2025. The campaign laid out a $1 million shortfall to cover the full season's program that costs $3.6 million (but the union's budget fell short). So to close the funding gap, they opened the doors to fans, alumni, and corporate donors and launched a dedicated donation portal for this effort: Mission: Win Rugby World Cup 2025 donation portal.
That night, the campaign thermometer sat at zero. By morning, it was alive as part financing tool and part storytelling engine that sparked a national movement in Canadian sport.
Rugby Canada needed more than dollars. They needed narrative. The early campaign push did three essential things well:
They didn't just ask for support but described the exact dollars missing and how each contributed dollar would map to camps, nutrition, recovery, and test matches.
Supporters weren’t just donors but they were treated as 'partners' in getting the Canadian Women's Rugby team ready for the World Cup 2025, a massive global sporting event.
Independent rugby media tracked progress. In April, RugbyPass ran a report noting the still‑open funding hole and provided key updates in how far along the drive had come, and how much further they still needed to go to achieve their mission.
As the 2025 Women's Rugby World Cup (hosted in England) drew closer and closer, media narratives framed Canada not just as underfunded underdogs but as gritty, scrappy, and deserving contenders. Sky Sports ran a feature titled “How non‑professional Canada crowdfunded its way to the final push,” saying pledges “reached 95 percent.”
Meanwhile, ESPN ran a narrative piece under the banner “Canada crowdfunded their way to the World Cup” juxtaposing the team’s funding shortfall with their on‑field ambitions.
Kudus to participating media that helped raise awareness for such an important Canadian funding drive. It really shows what's possible when the full ecosystem gets behind an initiative and drives momentum forward. There's a natural connection between executing a well timed and focused financing campaign and executing a key sports performance, and the public knows it. #ElbowsUp
When England 2025 kicked off, Canada stepped onto the pitch motivated by even greater purpose, not a team suffering by funding shortfall anxiety.
In pool play they went undefeated, carving out physical, disciplined performances that turned heads.
In the quarter final, they defeated a powerful Australia squad.
In the semi final, they shocked the rugby world by defeating New Zealand (perennial favourites) to reach their first Women’s Rugby World Cup final.
On September 27, before a packed Twickenham, Canada faced hosts England. They lost but not meekly. In the aftermath, coach Kevin Rouet and captain stressed that the match was decided on performance, not excuses, a point that resonates in Reuters’ coverage of the final.
Crowdfunding bought the players the chance to compete on equal footing, free of resource excuses. The lesson for Canada as a sporting nation was significant. When supports and fans step in to close gaps, institutions can't ignore the demand for sustainable, professionalized backing of women’s rugby.
Players adjusted their off season budgets and personal spending to show they were all in on the campaign narrative.
Coaching staff scheduled extra camps contingent on fundraising milestones, keeping the team in lockstep with the thermometer.
Each media checkpoint (50%, 80%, 95%) became a moment of drama as the story unfolded. Would the final stretch succeed or stall? That tension made the campaign itself a parallel storyline to the competition.
Critics wondered whether public fundraising blurred lines between sport and fandom but supporters embraced the risk, seeing their dollars as equity in national ambition at a time when Canada needs to buckle down and drive through the line.
When everyone's in the same boat, the winds will sail.
This was more than just a funding story. If you want one of those, feel free to read the real story of access to capital. It was about turning a resource gap (a modern day limitation) into shared ownership.
Canada’s women made their financial constraints visible, linked every dollar to performance outcomes, and invited supporters to become backers in the journey. That transparency changed how Canadians see women’s sport funding not as charity, but as investment with real returns.
The campaign also created accountability. Once the thermometer went public, the team owed backers results, not just thanks.
The story will not always be this dramatic, but the connections and motivations are real, and crowdfunding amplifies that blueprint. Define the gap, own the narrative, attach every contribution to a tangible outcome, and treat supporters as true partners.
Collaboration was at the core! Players, fans, alumni, sponsors, and media all carried their share of the work. As Canada’s women look beyond 2025, the responsibility now shifts to institutions, national sport bodies, sponsors, and public agencies to ensure future generations no longer need to crowdfund their path to the world stage, or maybe they should! #GoCanada
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Consultation | Sep 30, 2025
Image: Freepik/prostooleh
On September 25, 2025 the Canadian Securities Administrators (CSA) released for comment a proposal to harmonized Self-Certified Investor Prospectus Exemption (See: Notice and Request for Comment on Multilateral Instrument 45-111) that aims to replace a patchwork of provincial exemptions with a framework that makes it easier for more Canadians to participate in private markets and businesses to raise capital.
The comment period runs until January 5, 2026, giving NCFA members and stakeholders the opportunity contribute to one of the most important reforms for retail investor access in years.
The new rule would harmonize exemptions across multiple provinces and territories, replacing existing orders that had created pilot programs in each province. It sets an across the board investment cap of $50,000 per calendar year that can be spread across multiple issuers.
By consolidating exemptions into a single instrument, the CSA hopes to reduce legal and compliance duplication that has added cost and complexity for issuers.
This proposal builds on a broader modernization trend in Canada’s markets, including reforms such as the expansion of the Listed Issuer Financing Exemption (LIFE), which NCFA has reported as a material change for retail access to public capital raising.
Ontario has been one of the provinces piloting the model through Ontario Instrument 45-507 Self-Certified Investor Prospectus Exemption. The criteria in that order provide a clear picture of who could qualify:
To participate, an investor must complete both a Confirmation of Qualifying Criteria and an Acknowledgement of Risks form, certifying they understand the nature of exempt market securities and the absence of prospectus protections.
Notably, the Ontario pilot set the limit at $30,000 annually across issuers, while the new CSA proposal raises this cap to $50,000 across multiple jurisdictions. For the full consultation record, see the CSA Multilateral Notice for MI 45-111.
The combined effect of the newly harmonized rule would open up private markets to knowledgeable professionals who may not meet accredited investor wealth thresholds.
This includes financial analysts, accountants, valuators, and lawyers with corporate finance experience, as well as entrepreneurs and senior executives who have led companies in sectors where their industry knowledge helps them evaluate business risk. By broadening access, the exemption is intended to channel new pools of informed capital into early stage and growth businesses.
The CSA consultation does not provide any projections on the number of new investors or volume of new capital inflows that may result from these changes, and Ontario’s pilot program didn't publish any participation data. However, harmonization is expected to expand the eligible investor base and reduce administrative burdens on issuers.
For startups and small businesses, this can lower the cost of fundraising and increase the number of investors able to participate.
For investors, the proposed exemption enables participation based on knowledge and experience rather than wealth, while maintaining safeguards such as certification requirements and annual limits.
The proposed change is part of a wider trend of policy changes aimed at growing early stage financing in Canada, including Ontario's interim class orders that support early stage capital formation. More transparent reporting on participation and capital raised will be important for assessing outcomes and balancing investor protections over time.
Canada has long faced criticism for fragmented securities rules that make capital raising inefficient. By harmonizing exemptions across multiple provinces and territories, the CSA is addressing structural barriers that have limited access to early stage funding. If adopted, Multilateral Instrument 45-111 would give more Canadians the ability to participate in investment growth opportunities while providing businesses with a clearer path to attract more capital.
The comment period deadline is January 5, 2025. NCFA encourages its community to participate in this consultation by reviewing the CSA consultation materials, consider operational and investor protection details that should be refined, and submit data-driven and/or evidence-based feedback to regulators.
For background on Ontario’s pilot approach, see NCFA’s coverage of the OSC pilot self-certified investor exemption which provides additional context on the origins and mechanics of the model in Ontario. Also for further context, see the CSA consultation news release.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Advocacy | Sep 26, 2025
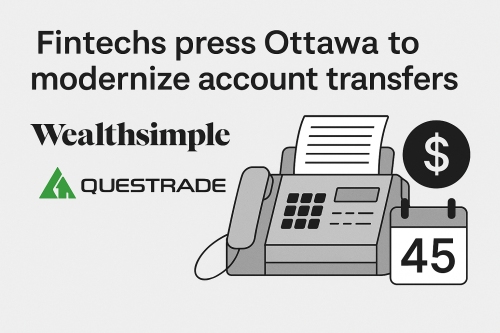
On August 12, 2025, Wealthsimple submitted its recommendations to the federal pre budget consultation, urging Ottawa to regulate how registered accounts such as RRSPs and TFSAs are transferred between financial institutions. The submission says rising transfer fees and weeks long delays undermines Canadians’ ability to manage their savings. Wealthsimple’s call was echoed by Questrade, which also urged stronger federal oversight.
Wealthsimple reported that between late 2024 and early 2025, the average transfer time was 19 days once paperwork was received. More than 13,000 transfers took longer than 45 days, and at any given time over $1 billion of client funds were stuck in transit, peaking at $2 billion in March. During this period, 45% of transfers were executed manually by the sending institution, specifically by fax and mailed cheques.
This outdated reliance on fax machines creates long delays that benefit incumbents. During this delay period, client capital is removed from their accounts by sending institutions (Read: Canadian incumbent banks), so it can be redeployed without clients receiving any benefit.
In fact, 15% of transfer requests were cancelled by clients due to the delays. Another way of putting this is investors are effectively providing interest free loans (to institutions) while paying more than $35 million in transfer fees.
Exit and transfer fees have grown from $0 to $75 a decade ago to an average of $150 per account in 2025.
With more than 40 million registered accounts in Canada, that adds up to hundreds of millions in annual costs.
Flat fees disproportionately harm younger Canadians. CRA data shows that the average TFSA balance for Canadians in their twenties is under $11,000, meaning a $150 fee can take more than 1% of their entire account.
By contrast, Canadians over 50, with TFSA balances above $25,000, are more likely to qualify for reimbursement programs offered by some institutions. Wealthsimple argues that this is a regressive structure that penalizes the very Canadians struggling most with affordability pressures.
The company itself does not charge clients who close or transfer out, and it has urged Ottawa to follow the example of other sectors such as telecom and air travel where hidden exit fees have been capped or eliminated.
The Canadian Investment Regulatory Organization (CIRO) has been studying the issue for years. CIRO's July 2025 White Paper on account transfers found that investor complaints over transfer delays have increased more than fivefold since 2015.
The paper reports widespread allegations that financial institutions intentionally slow transfers to retain business or to keep earning interest on client funds, with many investors stating that charges are too high or reimbursements are not honoured. This unnecessary friction harms consumers (and businesses alike).
CIRO has proposed modernizing the process with mandatory timelines, wider use of automation, and clearer requirements for firms to act diligently.
Wealthsimple’s pre-budget submission asks Ottawa the federal government who already regulates registered plans under the Income Tax Act to take similar steps in other industries to curb hidden fees.
From NCFA's perspective, fax machines and paper cheques are more than an inconvenience; they're systemic barriers to competition. Reform would not only protect consumers but also level the playing field for fintechs that rely on timely transfers to onboard new clients.
Why do Canadians and the government continue to accept an investment transfer system that still depends on fax machines, and why it takes pressure from fintechs to put the issue on the national agenda?
Other industries have modernized. Why has finance been allowed to remain stuck in the past? As Prime Minister Mark Carney puts it, “The premiers and I want to make Canada a global energy superpower and build the strongest economy in the G7.”
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016