





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Digital Banking | Oct 7, 2025
Image: Freepik/rawpixel.com
On October 2, 2025, Netherland-based digital banking experience platform Plumery announced Canada ready features for credit unions and is working with Vancouver-based Aequilibrium on the implementation for Canadian institutions. The release covers payments and transfers including Interac e-Transfer, support for Canadian savings and lending products, business banking tools, and bilingual English and French, privacy, data residency, and accessibility features.
In Jan 2025, Toronto-based credit union Central 1 said that Intellect Design Arena would take over its digital banking after its 2024 review. On March 3, 2025, the transfer took effect, and Intellect took over Forge, MemberDirect, and related web and mobile products while Central 1 continued to provide underlying infrastructure services. As a result, credit unions that previously used Forge now need to choose their next digital banking platform.
Plumery and Aequilibrium have built a localized version tailored to Canadian banking norms. The platform supports bill payments, cheque deposits, Interac e-Transfer, savings and lending products such as GICs and mortgages, business banking tools like bulk payments and payroll, and compliance capabilities including bilingual English and French support, data residency, privacy adherence, and accessibility features. These Canada specific digital banking capabilities are available out of the box.
Plumery's digital banking platform can be branded by the financial institution, allowing credit unions to use their own design and member experiences while using Plumery’s building blocks. They say its approach can reduce switching costs/risks by offering Canada specific features from day one while avoiding unnecessary disruption.
The partnership with Aequilibrium helps with compliance, user experience, and integration while keeping institutions in control of their brand and roadmap. For members, this can mean faster everyday banking, smoother transfers, and interfaces designed for how Canadians bank.
Ben Goldin, CEO and Founder of Plumery:
"With Forge winding down, Canadian institutions have a rare opportunity to modernise on their own terms, rather than being tied to outdated systems. Our platform provides an immediate, future ready option that puts control back in the hands of credit unions. By working with Aequilibrium, we are combining global banking innovation with local expertise to deliver experiences that meet the unique needs of Canadian credit unions’ members."
Plumery says its Canada edition is available now and that it is in conversations with several credit unions evaluating alternatives to Forge.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Payments | Oct 2, 2025
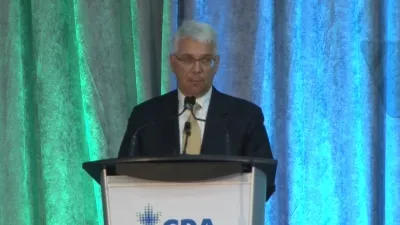
Image: Ron Morrow, Executive Director, Bank of Canada (CPA The One Conference Sep 18, 2025)
On September 18, 2025, Ron Morrow, Executive Director of Payments Supervision at the Bank of Canada, delivered a speech at the CPA The One conference titled, "Making change Accelerating payments innovation". He spoke about a vision for Canada’s payments future, one where innovation, oversight, and competition intersect. Stronger oversight and modern payment rails will make the system more competitive and inclusive.
This article unpacks select key quotes and and highlights two sides of the coin for stakeholders to see both sides and the trade-offs that come with it. For Canada, the task now is not whether to act, but how to add momentum and keep pace in a global race.
“Almost 1,500 payment service providers are now required to register with the Bank under the Retail Payment Activities Act.”
For the first time, nearly fifteen hundred retail Payment Service Providers (PSPs) are being pulled into the regulatory fold. Supporters argue that this gives consumers and businesses more confidence when using new services and helps fintechs compete on equal footing with banks. By ending the perception that startups operate in a grey zone, it could make investment in the sector more attractive.
But compliance comes with costs, and many small firms run lean without a large legal or regulatory staff like banks. What may feel like light reporting to a large bank can feel like a heavy lift for a ten person startup. In the worst case, it could drive consolidation that narrows competition instead of expanding it.
“Our job is to make sure that innovation in the payments system can proceed in a way that is safe, sound and reliable.”
Safe to say that Canadians will only embrace new forms of payments if they trust them to work without interruption and to protect their money. Regulation that sets clear expectations can provide certainty for innovators, giving them a stable foundation to build on.
Yet safety can lead to an abundance of caution that could slow innovation. Other countries, from the UK to Singapore, have shown that regulators can allow pilots and sandboxes to move quickly while still managing risk. If Canada puts too much emphasis on stability, we'll fall behind in a global race where trust and speed both matter.
“We are working to expand access so that more providers can offer services directly through Canada’s core payment systems.”
Direct access to national infrastructure is potentially transformational. If fintechs can gain access without going through a big bank, they can offer faster and cheaper payments. This would lower costs for consumers, ignite competition, and open the door for creative new services in areas like cross border transactions.
The flip side is that these core systems were designed with large, well capitalized institutions in mind. Smaller entrants may not have the same buffers to handle liquidity shocks or technical breakdowns. One major failure could undermine confidence across the entire network. The challenge is designing an access model that widens competition without weakening stability. Payments Canada who is overseeing Canada's payments modernization has delayed implementation numerous times, and industry is frustrated. In May 2025 however, they announced that the technical build will be completed by Q3 2025 and they plan to test the system throughout 2026.
“Through our work with the BIS Innovation Hub, we are exploring the potential of new technologies such as tokenization and artificial intelligence.”
Engaging with international financial innovation hubs allows Canada to stay connected to the latest fintech and payments research, including stablecoins and tokenization. It also helps Canadian fintechs align with emerging global standards, making cross border scaling easier. Last June 2024, the BIS and Bank of Canada Launched the BIS Toronto Innovation Centre.
The real risk lies in harmonization at home. Canada’s financial system is driven by a concentrated banking sector and diverse regional economies, where inter-provincial differences can create barriers to trade and investment. If newly adopted financial technologies and related reforms aren't designed to work seamlessly across all provinces and territories, Canadian markets could become further fragmented with unwanted barriers and compliance costs. Canada needs to strengthen its internal market with more competition and innovation to be able to complete with strength globally.
“Payments innovation cannot be separated from broader efforts like open banking.”
If Canada completes payments modernization while also enabling consumers to share their financial data securely (open banking, consumer driven finance), the market could see a boon of new service models and tools that bring real competition to a system long dominated by incumbents.
Skepticism is very real though with Canada lacking the political will to finally implement open banking after promising it and studying it for years. Without binding timelines, many in the industry hear speeches like this one but actions speak louder the words. For fintechs, the question remains whether it is worth investing in solutions that depend on open banking when political momentum has not yet delivered results, or opt for new pathways. The latest is that open banking in Canada will land in 2026., with further delays will have significant consequences for innovation and consumer choice in Canada.
Ron Morrow’s speech delivers a clear vision and direction for modernizing Canada’s payments landscape. Expanded oversight, broader access to rails, and participation in global innovation networks all point to a more open and competitive future. If open banking also arrives in 2026, these reforms could unlock real benefits for consumers and fintechs alike. But the devil’s advocate cannot be ignored. Here's a streamlined version of Morrow's speech, 'Cashing in on Payments Innovation' (fingers crossed)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
CBDC and Stablecoins | Sep 29, 2025
Image: Freepik
On September 19, 2025, EU finance ministers reached a compromise on the digital euro roadmap, designed to reduce dependence on Visa and Mastercard. The plan gives governments a stronger role in any launch decision and sets limits on how much citizens can hold. For official policy context, see the EU Council’s digital euro page, which outlines objectives and implementation steps.
Just six days later, nine major European banks formed a consortium to launch a MiCA-compliant euro stablecoin, targeting a 2026 launch. The group includes ING, UniCredit, CaixaBank, Danske Bank, SEB, Raiffeisen Bank International, KBC, DekaBank, and Banca Sella. Their goal is to deliver instant payments, programmable settlement, and a regulated alternative to unbacked crypto tokens.
By anchoring the stablecoin in Europe’s MiCA framework, the banks are moving early to define how regulated tokenized money will work. MiCA sets clear standards for issuers on capital, governance, and reserve management. That clarity is drawing incumbents to commit capital and credibility.
The digital euro and the bank consortium stablecoin initiative both look to rebalance power in Europe’s payments market. Today, Visa and Mastercard process around two‑thirds of all European card transactions. Policymakers want to ensure Europe can clear and settle payments domestically without relying on foreign schemes.
The central bank digital currency (CBDC) and stablecoin initiatives also intersect with Wero, the new retail wallet developed under the European Payments Initiative. Wero is designed to give merchants and consumers a unified tool for instant payments across the euro area, and a tokenized euro would strengthen its value proposition. This alignment mirrors the Canadian Real‑Time Rail project, though Europe is tying its upgrades more explicitly to digital money.
A further motivation is market share. Euro stablecoins currently total only about €620 million outstanding, compared to nearly $300 billion for U.S. dollar stablecoins. Europe risks being sidelined if it does not accelerate adoption, as global trade and DeFi increasingly rely on dollar‑based tokens.
For fintechs, these initiatives open a regulated path to experiment with programmable money, cross‑border settlement, and retail wallets. Startups may be able to integrate stablecoin rails into remittances, treasury management, or point‑of‑sale services with legal certainty.
For banks, the picture is mixed. Deposit flight is a risk if customers shift balances into tokenized wallets. Yet the banks launching the consortium also stand to gain by controlling issuance, custody, and compliance, capturing value from tokenization.
Canada has taken a more cautious approach. The Bank of Canada has said there is “no compelling case” for a retail digital dollar and is prioritizing upgrades to payment infrastructure. Policymakers are also examining how to regulate stablecoins, with oversight currently split between federal and provincial authorities. See NCFA's analysis of Canada's stablecoin race entering a critical phase for a more detailed analysis.
Europe’s actions highlight lessons for Canada. Their dual‑track model of a CBDC combined with a bank‑led stablecoin consortium shows how sovereignty and innovation can be balanced. A digital loonie could serve as a public anchor, while regulated Canadian bank or fintech stablecoins could deliver speed and programmability. Equally important, MiCA demonstrates the power of legislative clarity, something Canada lacks as fragmented oversight slows momentum.
Europe’s urgency also stems from the fact that euro stablecoins represent a tiny fraction of the global market. Canada faces the same risk if stablecoin use grows but domestic frameworks stall, Canadians may increasingly rely on U.S. dollar tokens for payments, weakening monetary sovereignty. Europe is also linking its initiatives to Wero, its new retail wallet.
Canada could also add experiments to the rollout of its Real‑Time Rail, ensuring token‑based payments integrate with domestic upgrades. Although Canadians and payment stakeholders can't afford any more delays.
If Canada followed a similar approach as in Europe, payments could become faster and cheaper, and fintechs would gain new opportunities in programmable settlement and remittances. Banks could face pressure on deposits but would gain new business in custody and compliance. If Canada hesitates for much longer, the country risks dollarization via U.S. stablecoins, reducing control over payments and data governance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 27, 2025
Image: Freepik AI
Canada is preparing for the launch of “Consumer-Driven Banking” in early 2026. This promises to be a system that will give people more control over how their financial data is shared. The main goal is to replace current risky practices, including screen scraping, with safe, consent-based data exchange. The government has made it its aim to focus on trust, clearer guidelines and regulations, to provide a system where security comes first, while still encouraging innovative services.
For more than 30 years, Interac has been the foundation of Canada’s payment system. The payment gateway is well-known for debit payments, ABMs, and the popular e-Transfer service. In 2024, Canadians sent more than one billion e-Transfers, transferring more than $132 billion.
The reach of Interac extends further than banks and credit unions. Its services are also used in online services. For instance, with online casino platforms, players rely on the same fast and trusted payments they use with their bank. The payment option allows players to access the same bonuses, gaming library, and promotions whether they use an e-wallet, cryptocurrencies, or traditional banking methods. With Interac e-transfer casinos, players can expect a fast, convenient, and highly secure way to fund their accounts with strong protections against fraud and theft.
Additionally, Interac is widely accepted for online purchases in Canada because it supports secure direct payments through Interac Online or Interac e-Transfer, which many online merchants and platforms integrate. This widespread trust and familiarity with Interac in everyday payments reflects the confidence Canadians place in its security and convenience. This acceptance and reputation for safe transactions make Interac an ideal foundation for supporting the secure, consent-based data sharing envisioned by Canada’s open banking framework
Interac already connects banks, credit unions, payment processors, and more than 1.4 million point-of-sale terminals across the country. It also has significant experience with APIs, tokenization, and authentication, which are exactly the kinds of tools that open banking requires.
Equally important is Interac’s reputation for security. With three decades of experience, Interac has well-established governance frameworks, security protocols, and operational standards. These can easily be adapted and extended to open banking APIs to accelerate compliance and risk management processes.
Standardized APIs are central to consumer-driven banking. Interac has already been running pilot projects with dozens of third-party providers that want to connect directly to financial data. The network includes shared services that are vital for open banking, such as identity verification, consent management, and secure data transfer.
It makes sense to use infrastructure that already exists. This could speed things up considerably. Instead of starting from scratch, Canada can build on a network that already processes millions of transactions every day. Interac’s reliability, low downtime, and widespread acceptance mean both banks and fintechs are more likely to support a model that is proven and trusted.
Interac’s experience helps reduce the time needed for open banking to become a reality. With ready-made standards and existing relationships across the financial sector, deployment can move faster than in countries that had to build new systems entirely. This is significant, given that the federal government has set early 2026 as the target date.
Interac also works closely with regulators. It advises on governance, security, and consumer protection, and it has teamed up with fintech incubators to test new applications in controlled environments. The focus has been on creating clear, transparent consent processes for consumers, ensuring people understand and control how their data is used.
In 2025, important steps were taken to prepare for rollout. Despite mixed reactions and backlash, Parliament passed legislation requiring accredited entities to use secure APIs, annual consent renewal for data sharing, and oversight by the Financial Consumer Agency of Canada. Major banks, including RBC and TD, continued expanding their API systems and entered new partnerships with fintechs to test services ahead of the launch.
Interac, for its part, strengthened its focus on fraud prevention. The appointment of David Bruyea as Group Head of Financial Crimes signalled an investment in protecting the system at a time when trust will be vital. With consumers still learning what consumer-driven banking means for them, Interac is positioning itself as the trusted partner that can balance innovation with security. Its long-standing role in Canadian finance, paired with ongoing developments in 2025, places it at the centre of the country’s move toward open banking in 2026.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Fintech Report | Aug 22, 2025
Image: Pulse of Fintech H1 2025, KPMG
According to the KPMG Pulse of Fintech H1 2025 report (67 page PDF) published in August 2025, global fintech investment in the first half of 2025 fell to $44.7 billion across 2,216 deals, recording the lowest H1 total since early 2020. Investors remain cautious about elevated risks around higher interest rates, capital costs, and geopolitical uncertainty. Q2 2025 was particularly weak, with $18.7 billion across 972 deals.
Investment in digital assets totalled $8.4 billion across 586 deals in H1 2025. Stablecoins attracted attention for payments and remittances in emerging markets, while tokenization platforms and infrastructure also captured capital. Circle's IPO anchored the sector’s strength, raising $1.1 billion with shares jumping 168% on day one.
AI continues to boost fintech investment. Capital flowed into both AI native startups and to incumbents embedding AI in credit scoring, fraud detection, and customer engagement. Investors prioritized business models that combined growth with efficiency and risk control. See NCFAs coverage of AI Fintechs attracting a 242% valuation premium
Regtech attracted $2.1 billion across 190 deals in H1 2025. Adoption of automated KYC, AML, and reporting tools continues to grow as financial institutions look for cost savings and regulatory agility. GenAI in risk and compliance
Insurtech raised $4.8 billion across 141 deals in H1 2025, which is already greater than all of 2024. Wealthtech funding reached $0.9 billion across 14 deals, with AI enabled platforms a recurring theme. Both sectors experienced consolidation as incumbents prefer acquisitions over building new capabilities.
Payments investment slowed to $4.6 billion across 242 deals in H1 2025, as investors grew more selective. But the sector is still foundational with capital being allocated to embedded finance, cross border platforms, and transaction monitoring. For Canada’s policy context see open banking delays and competitiveness and banks exiting merchant acquiring businesses like Moneris.
Cybersecurity specific fintech investment was just $0.1 billion across 26 deals in H1 2025. Despite heightened threat levels, most activity was concentrated at seed and early stages, reflecting investor caution toward scaling security focused fintechs.
Exit momentum is returning. Circle’s successful IPO may open the door for additional digital asset platforms to list in H2 2025, boosting the case for fintech exit activity after years of lack lustre listings.
For Canada, the data shows the window of opportunity for digital assets, AI, and regtech could attract investment with clear policy and infrastructure. The muted state of payments and open banking highlight gaps Canada must address to remain competitive. Clear rules, targeted support, and investment in digital infrastructure are critical to positioning Canadian fintech for growth in the second half of 2025 and beyond. See the crisis Canada and fintech cannot afford to waste
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open Banking | Aug 13, 2025

Image: Freepik
FCA Releases Governance Plan for UK’s new Industry-led Open Banking Standards Body
On August 8, 2025, the UK’s Financial Conduct Authority (FCA) published its FS25/4 feedback statement outlining the governance framework for a new Future Entity to oversee the open banking standards in the UK. The plan details how the Future Entity will be funded, governed, and held accountable. It will be industry led and operated, not a government agency, but will function under the FCA’s oversight. For Canada, the model demonstrates how industry expertise can be combined with regulatory accountability to support innovation and trust.
Since 2017, open banking in the UK has been run by Open Banking Limited, a government run entity created by the UK’s Competition and Markets Authority (CMA) to deliver its order requiring the nine largest banks to create interoperable APIs. Known earlier as the Open Banking Implementation Entity (OBIE), it was a time limited role to boost competition in banking, and not designed to be a permanent governance model.
The FCA’s plan replaces OBIE with the Future Entity, which will have a long term, industry wide mandate. This change moves open banking oversight from a CMA specific enforcement body to an independent standards setter governed under the Data (Use and Access) Act 2025. This legal framework means the Future Entity can later expand into open finance and other areas of data portability.
The Future Entity will be a not for profit company limited by guarantee, funded by contributions from its users and beneficiaries including banks, fintechs, and other participants. Its board will be appointed by an independent appointments committee, not directly by the government or the FCA. The FCA will regulate it as an interface body under the Data (Use and Access) Act, but will not manage its day to day operations. This allows industry to lead on technical standards while the FCA can intervene if those standards do not protect consumers or the market.
The governance approach is similar to a self regulatory organisation (SRO). It is run by industry, sets technical and operational API standards, and monitors compliance. Like an SRO, it will send reports to the regulator. The key difference is that the Future Entity will not have enforcement powers. All formal enforcement remains with the FCA. This keeps legal authority with the regulator while allowing the industry to deliver the technical work.
Commercial operators will use the Future Entity’s standards to create products and services to meet interoperability while leaving space for competition and innovation. The Future Entity itself will only operate directly if there is no commercial incentive or there is a proven market failure.
Industry participants are already working on variable recurring payments for uses such as bill payments, which is planned for 2025. The FCA will hold workshops this summer and fall 2025 to finalize operational details, with a full plan expected by the end of the year.
Canada currently has no permanent open banking standards body. The UK approach shows how Canada could move a temporary regulatory order to a more permanent industry led framework without losing accountability or slowing progress.
An industry led and funded non-profit organization, supported by contributions from all users and beneficiaries, can create shared responsibility and boost financial sustainability. With an SRO style approach, industry leads on technical delivery while the regulator retains enforcement powers, can speed innovation while protecting consumers and market stability.
Important to keep the standards setting body separate from commercial operators to streamline interoperability and ensure a level playing field (reducing risk of favouritism towards certain providers). Applying these principles from the start could help Canada avoid disruptive governance changes later and build a system that supports both innovation and public trust. Learn more about Canada's open banking journey.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 5, 2025
Image: Unsplash/itsmpl
Much is said about the cultural shift surrounding iGaming and sports betting in Canada. The more important story, however, is economic. Provincial regulation is the driving force behind Canada’s gaming success, but without financial technology, it wouldn't go this far. Fintech, in its many forms, is quietly changing the rules of engagement for players, operators, and regulators alike. The stakes are high. In 2024, Ontario’s iGaming market alone brought in over $4.19 billion in revenue. Alberta is preparing to follow. Furthermore, with open banking reforms finally on the table, fintech has the opportunity to institutionalize itself as the core infrastructure of the gaming economy.
It’s not the flashiest headline in gaming, but make no mistake: open banking is about to be the MVP in Canada’s digital economy. After years of talk, 2024 finally saw legislation begin rolling out, giving Canadians control over their financial data. Think bank account access through secure APIs, no more screen scraping or workarounds.
For gamers, it means faster onboarding. Just connect and verify, and you’re good to go. Deposits, withdrawals, and even budgeting tools are built right into your platform of choice.
It’s a system built for people who want to bet, play uninterrupted, and move on.
For years, Canada has lagged in open banking. That changed in late 2024 when the federal government outlined a framework to give consumers more control over their financial data. In practical terms, the open banking system allows verified third parties such as fintech companies to access banking information with user consent. This opens the door to real-time KYC (know your customer) checks, faster onboarding, and in-platform account linking without tedious form-filling or manual uploads.
In a gaming context, this cuts user friction and platform costs. Deposits and withdrawals can be executed securely and instantly, making regulatory audits less painful.
There is also a secondary benefit: players can better track their spending. It’s early, but this is one of the more promising angles for enforcing responsible gaming through structural incentives rather than pop-ups.
Canada’s Real-Time Rail (RTR) payment infrastructure is due for rollout in 2026. This is a case of better late than never. Its appeal is obvious. The infrastructure allows round-the-clock bank transfers and immediate settlement and offers the kind of reliability that’s been sorely lacking in batch-based systems.
The advantages are clear for online casino Ontario platforms and the upcoming regulated markets. Player deposits and withdrawals become instant, reducing the burden that customer service agents bear. In theory, this means fewer chargebacks, account freezes, and customer service escalations, all of which cost operators dearly.
It also levels the playing field. Smaller operators won’t need expensive integrations with legacy payment processors to compete. Fintech can plug them in directly to the national infrastructure.
Image: Unsplash/Luke Jones
Everyone talks about AI bluffing its way through poker tournaments. However, the most valuable use of artificial intelligence in Canada’s gaming ecosystem is quietly running in the background, scrutinising transaction patterns and flagging anomalies at a speed no human compliance officer could hope to match.
AI’s growing role in fraud detection is becoming essential. With billions flowing through digital platforms, and more Canadians participating in regulated online betting, the threat is no longer theoretical. Identity theft, money laundering, and payment fraud are risks that fintechs can’t afford to ignore.
The more serious players in Canada’s fintech sector are training machine learning models to spot irregularities based on metadata, behavioural trends, and open banking feeds. The goal is early detection before issues become public, or worse, regulatory.
Let’s give some credit where it’s due. Homegrown fintechs like Nuvei are building world-class tools. The Montreal-based firm was named Payment Provider of the Year in 2024, thanks to its open-banking-powered instant transfers.
They’re not alone. Toronto-based Koho is creating wallet infrastructure that could soon let players reload balances at Canada Post counters. Wealthsimple and Neo Financial are pushing boundaries on digital ID and account linking.
These startups are building the rails that gaming and everything else will run on for the next decade.
Much of fintech’s value to Canadian gaming platforms lies in what it quietly removes: friction, delay, and uncertainty. Players may never know what systems sit between their bank account and bet, but they feel the difference when everything works.
| Feature | What It Means In-Game |
| Open Banking | Connect your account instantly |
| Real-Time Rail | Withdraw and deposit anytime |
| Embedded Finance | Top-up without ever leaving your game window |
| Smart Risk & AI Tools | Safer play, better limits, fraud kept in the shadows |
| Local Fintech Integration | Better UX built specifically for Canadian players |
This isn’t tech for tech’s sake. It’s about giving players more time to enjoy the game, rather than dealing with unwelcome interruptions.
Image: Unsplash/Designtoasty
Canada’s gaming market is a heavily regulated, highly competitive industry where trust, speed, and data governance are the new table stakes. Fintech is now writing the script, enabling everything from smoother gameplay to provincial oversight. While few players will ever see the real-time rails or know what open banking means, their experience and the industry’s sustainability will depend on it. For all the talk of games, the real game is financial infrastructure, and fintech, quietly and methodically, is winning.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
