





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 16, 2026 | NCFA Insight | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization
On June 14, 2026, the Financial Times reported that China is preparing mBridge for commercial rollout (subscription needed), with central banks from mainland China, Hong Kong, Thailand, the United Arab Emirates and Saudi Arabia involved.
The participating central banks haven't yet published a matching launch announcement. The Bank for International Settlements said mBridge reached minimum viable product stage in 2024 and that more central banks and commercial banks could join the legal framework and perform real transactions on the platform.
mBridge is important to watch because it tests a different model for cross border settlement. Instead of routing payments through long correspondent banking chains, participating central banks and commercial banks use a shared multi CBDC platform for payment and foreign exchange settlement. That makes the project a practical test of whether wholesale CBDC rails can reduce cost, settlement delay and liquidity friction in trade corridors where participating jurisdictions already have strong commercial ties.
mBridge began in 2021 with the BIS Innovation Hub, the Hong Kong Monetary Authority, the Bank of Thailand, the Central Bank of the UAE and the Digital Currency Institute of the People’s Bank of China. Saudi Arabia joined as a full participant in 2024. BIS also identified more than 26 observing members, including the European Central Bank, IMF, World Bank, Reserve Bank of India, Bank of Korea, Bank of France and the Federal Reserve Bank of New York’s New York Innovation Center.
The project has already gone beyond lab testing. The HKMA said the 2022 pilot involved 20 banks across four jurisdictions and completed more than 160 payment and foreign exchange transactions totaling over HK$171 million. It was among the first multi CBDC projects to settle real value cross border transactions on behalf of corporates.
BIS later said the MVP platform allowed participating jurisdictions to undertake real value transactions, subject to their own readiness. The project also created a governance and legal framework, including a rulebook, to match its decentralized operating model. That's why the current story isn't whether CBDCs can be piloted. It's whether participating jurisdictions can turn mBridge into operating payment infrastructure?
mBridge should be read alongside Project Agorá tests real money bank settlement rails. Agorá is testing tokenized commercial bank deposits and wholesale central bank money with major Western central banks and more than 40 commercial banks. mBridge is testing a direct multi CBDC settlement network among participating jurisdictions.
The difference is important for Canadian banks, exporters, fintechs and policymakers. Agorá is closer to upgrading existing correspondent banking through tokenized deposits and shared workflows. mBridge is closer to building a parallel wholesale settlement arrangement for selected currency corridors. Both are trying to reduce payment friction, but they reflect different governance choices, legal assumptions and geopolitical incentives.
The commercial test is liquidity, compliance and repeat usage. If real trade flows begin routing through mBridge, banks and payment firms will have to assess whether lower cost and faster settlement justify the legal, operational and supervisory work needed to connect to a new network.
The sensitive issue is whether a new wholesale settlement network can preserve anti money laundering controls, sanctions compliance, legal certainty and supervisory visibility across jurisdictions with different policy goals. Debate around mBridge's geopolitical implications has followed the project for years. See: mBridge could affect sanctions enforcement and payment routing.
In 2024, BIS General Manager Agustín Carstens said the BIS handoff of mBridge to participating central banks was not politically driven and was not a sign of project failure. He also said mBridge was not mature enough to operate commercially at that time and rejected the claim that it was designed as a BRICS sanctions workaround.
That tension remains central. If mBridge enters commercial use, participating institutions will need to prove that faster settlement isn't at the expense of enforceable controls, transaction monitoring, governance accountability or cross border legal clarity.
If wholesale CBDC networks start carrying real trade flows, how should Canada position payment modernization so Canadian banks, exporters and fintechs can participate in the infrastructure race instead of only reacting to it?
CBDCTracker, these Central Banks have Launched a CBDC or Pilot Initiative
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 15, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Payments And Market Infrastructure, SME Finance And Business Banking
On June 15, 2026, Montreal based Nuvei announced a definitive agreement to acquire Payoneer for approximately $2.75 billion ($7.40 per Payoneer share in cash). The companies expect the transaction to close in mid 2027, after Payoneer shareholder approval, regulatory approvals, and other closing conditions.
If completed, the combined company expects about $3 billion in annual revenue. It also expects to process more than $500 billion in annual payment volume and serve over 2.4 million customers across more than 190 countries and territories.
While the price tag will certainly get some attention. The stronger story is what Nuvei is buying. Payoneer brings cross border payouts, multi currency accounts, marketplace reach, banking connectivity, regulatory approvals, and access to businesses that operate globally every day.
Payment processing is only one part of global commerce. Businesses also need to collect funds, hold balances, convert currencies, pay suppliers, settle marketplace earnings, and manage funds across borders.
Payoneer has spent two decades building that infrastructure. Its customers operate across Amazon, Walmart, Airbnb, Fiverr, Etsy, Upwork, Shopify, WooCommerce, eBay, ByteDance, and other global platforms. These businesses don't just need checkout tools. They need financial rails that help them operate in multiple currencies and jurisdictions.
Payoneer also brings regulated market access. The announcement highlights online payment licensing in mainland China and authorization in principle as a cross border payment aggregator in India under the Reserve Bank of India framework. That kind of access is tough to replicate. It takes capital, local knowledge, compliance depth, and time.
Nuvei connects businesses to local acquiring, alternative payment methods, risk tools, fraud management, and merchant services. Payoneer is closer to the operating side of international commerce. It helps businesses receive earnings, manage currencies, send payouts, and use global banking networks.
Together, the companies can cover more of the financial workflow. A merchant may start with payment acceptance. Then it may need supplier payments, foreign exchange, treasury tools, card issuance, marketplace settlements, or embedded financial services.
A provider that manages more of the money flow earns a stronger role in daily operations, otherwise a payment processor alone may just lose a merchant at renewal.
The expected combined scale gives Nuvei a larger role in global commerce infrastructure. It also puts the company in a different competitive conversation.
Nuvei is no longer competing only as a payments processor. It's trying to become a broader platform for acceptance, payouts, settlement, treasury, FX, and embedded finance. Merchants and platforms increasingly want fewer providers handling more of their financial operations. They want simpler workflows, cleaner reconciliation, faster settlement, and stronger compliance across markets.
That matters because every additional financial provider adds complexity. Merchants must reconcile transactions across multiple systems, manage separate compliance requirements, monitor third party risk, and track funds moving through different settlement networks. As Canadian payment rules place more weight on payment service provider operational risk and incident response rules, businesses have greater incentive to reduce handoffs and work with providers that can handle more of the process inside one platform.
For Canada's fintech ecosystem, the deal shows where value often forms behind the scenes. Some of the most important fintech companies are not consumer brands. They are infrastructure firms embedded behind marketplaces, exporters, software platforms, and global merchants. The acquisition also fits the larger opportunity in NCFA's Financial Innovation Map, where payments, data, digital assets, capital markets, and financial infrastructure are becoming more connected.
As payments, payouts, treasury services, FX, and embedded finance come together, will businesses keep using separate financial providers or choose platforms that manage the full flow of money across borders?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 15, 2026
Image: Unsplash/Sasun Bughdaryan
More and more Canadians are no longer leaving the business of cross-border acquisitions to institutional investors, and they are increasingly relying on technology to simplify international purchases. Whether accessing real estate market data and analyses or taking a virtual walk through properties, the evolution of PropTech has significantly altered how investors can scout, assess, and acquire assets abroad.
The appeal is evident: Investors can browse neighborhoods, compare yields, and contact service providers from their own homes, without needing to travel. Technology has helped overcome many of the conventional barriers of purchasing overseas real estate.
However, technology is only one component of the equation, and the key to making the right decision still lies with a deeper understanding of the market and local expertise.
There are a number of things that make America attractive. Firstly is scale: you have thousands of cities, many with their own driving forces, their own pricing structure, and rental possibilities. Secondly, many areas in the US have an entry price point that is lower than in the large Canadian metro cities; diversified investors can find regions that offer higher cash flow potential and a wider array of inventory to choose from.
Thirdly is the diversity of the economies, so in one city there could be employment growth from the medical field, another from technology, and another from tourism: these provide diversification across sectors, reducing concentration of risk.
Fourth is movement of currency; at various times favorable exchange rates can make buying opportunistic in US real estate and encourage purchasing. Fifth and perhaps most importantly, many investors recognize US property for long-term wealth accumulation as well as supplementing their existing real estate holdings in Canada.
PropTech has dramatically changed the way that investing is performed. Researching a foreign market used to involve many trips and scarce data points.
Digital platforms now allow immediate viewing of market statistics, population reports, rental data, and transaction records. This allows investors to view options from home and pre-qualify their search before proceeding. AI allows investors to take advantage of predictors that indicate growing jobs, rental rates, and infrastructure developments. Electronic document systems further streamline transaction processes by allowing contracts, disclosures, and loan documents to be viewed and electronically signed.
Virtual property tours enhance accessibility and allow buyers to view a property and area without actually going there. PropTech has given Canadians an experience with investing in American property that can now be performed more quickly and knowledgeably than ever before.
Image: Unsplash/Jakub Żerdzicki
Property intelligence – Data is quickly becoming one of real estate’s most prized assets. Canadian buyers are reviewing population migration trends, job numbers, school scores, and investment in infrastructure before choosing where to buy. There are fewer assumptions and more calculations involved. Rental performance indicators offer data to gauge anticipated occupancies, average rents, and overall income for a property.
Many also follow the number of building permits issued as a predictor of market confidence or for the impact that a build may have on supply. Statistics surrounding migration give further data points for regions experiencing an influx from those new to the workforce or in retirement.
News about business expansion, road improvements, or the number of crimes are all part of the picture. This approach eliminates the assumptions—there's a data-driven reason to consider some markets over others before other investors catch on.
We have a powerful arsenal of technology. Technology alone will not replace ground-level knowledge, though. As Jeff Tricoli, the prominent Southeast Florida real estate broker, puts it:
"I believe real estate is built on clarity, trust, and education. We guide clients with market insight. So every decision is informed and not speculative in manner."
However, technology cannot solve all issues. Cross-border taxation, for instance, is still a thorny subject. Investors need to be able to familiarize themselves with disclosure rules, ownership, and potential liability in two different countries.
Financing can also be tricky. Banks lend at different rates and have different criteria, and one might not be able to get good terms without more extensive paperwork. The law varies by state. Each has its own set of laws regarding what a landlord may and may not do, how to evict, and what must be disclosed to the tenant. Another problem has to do with interpreting data. The internet can flood you with information, but if you don’t interpret it correctly, you may end up making a mistake.
The market is another quick-changing variable. One that appears robust today might not be tomorrow if some new economic trend or government action destabilizes it. Ultimately, human acumen is still important. Networks of local experts—lawyers, accountants, brokers, and the like—still matter for a successful deal. Technology, in the absence of it, is certainly not a replacement for diligent investigation.
It is also reasonable to assume that PropTech will continue to evolve and exert influence. The predictive capabilities of artificial intelligence could be enhanced in such a way that investors know which neighborhoods will perform best. They will also happen to be the neighborhoods that will be in most demand in the future.
The use of blockchain will undoubtedly streamline transactions, as well as increase security with records. It is likely that data will also be more thoroughly integrated. Investors could be provided with a suite of not only market analysis tools but also financing, legal advice, and property management information.
Interest from Canadians remains strong because the United States offers size, variety, and scope for portfolio growth.
Proptech has changed the way investors look at cross-border transactions. Data analytics, virtual tours, prediction technology, and online platforms allow for easy research and access to investments.
However, tech is not a total substitute for local experience and knowledge. Legal, tax, financing, and neighborhood issues require local input. Hope this read helped you and best of luck on your journey in this way.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 6, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure, Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026).
Citi is combining traditional securities infrastructure with blockchain based issuance, custody, and settlement for private company equity. The launch adds another proof point that tokenized infrastructure is changing how markets operate, especially as banks, exchanges, and market operators compete to define how private assets move onto digital rails.
Digital asset access is being packaged for banks, brokerages, fintechs, and platforms that do not want to build the full crypto stack themselves. The control point is the embedded infrastructure that handles custody, liquidity, compliance, settlement, and connectivity behind the customer experience.
Tokenized real world assets are moving into bank distribution channels. DBS is turning physical gold into a digital product that can sit inside a retail banking app, while also testing institutional market access through its digital exchange.
Stablecoin supervision is moving from broad policy debate into operating rules. Issuers, custodians, exchanges, auditors, compliance vendors, and payment firms need to track how reserve custody, internal controls, audits, and service provider oversight become part of stablecoin market access.
Card networks are building trust infrastructure for AI driven payments. Visa’s updates add another network level proof point that identity, authorization, fraud controls, tokenized credentials, and settlement will shape how AI agents are allowed to transact.
Recurring payment rails are becoming a financial inclusion tool when they help users pay for digital services without relying on credit cards. Brazil’s Pix Automático data shows how local real time payment infrastructure can support subscriptions, platform access, and digital commerce growth.
Agentic payments are moving from checkout experiments into network infrastructure. Payment firms, AI platforms, stablecoin providers, banks, and identity vendors now have to solve authorization, spending limits, settlement, fraud controls, and liability for machines that can transact without a human at every step.
Large banks are building their own tokenized money infrastructure rather than relying on third party stablecoin networks. Payment providers, treasury platforms, and financial institutions now face a more competitive settlement environment as bank money, stablecoins, and tokenized commercial bank deposits compete for transaction flow.
Circle Payments Network continues to add distribution. Business accounts, treasury platforms, and payment providers are becoming part of the stablecoin settlement infrastructure rather than simply connecting to it.
Circle is extending its infrastructure footprint from stablecoins into Bitcoin collateral. Builders now have another institutional grade option for collateral and tokenized asset applications.
AI agents are moving from recommendation and discovery toward financial execution. Coinbase for Agents puts user controlled account access, payments, trading, and workflow automation into the same agentic finance conversation as network trust controls, stablecoin settlement, fraud prevention, and responsible AI governance.
AI supervision in finance is evolving from broad risk discussion toward operating practices for boards, senior management, compliance teams, model owners, technology vendors, and supervisors. Financial institutions need to track how governance, documentation, human oversight, cyber controls, and third party dependencies become part of responsible AI adoption.
Always-on markets need reference data that does not stop when traditional exchanges close. Exchanges, tokenized asset platforms, derivatives venues, market makers, and risk teams now have another pricing source to evaluate as real-world assets trade across crypto-native market infrastructure.
Prediction markets are starting to need the same financial plumbing as capital markets. Market makers, exchanges, payment providers, banks, and compliance teams now need infrastructure that can handle deposits, margin, settlement, risk controls, and regulated access without slowing down trading activity.
Prediction markets are moving from platform experimentation and court fights into formal rule design. Kalshi, Polymarket, DraftKings, Flutter/FanDuel, exchanges, market makers, compliance teams, sports leagues, and retail users now have a clearer process to debate which contracts belong in derivatives markets and which remain too close to gaming, misconduct, or public interest risk.
Financial crime compliance is increasingly becoming an existential regulatory issue rather than a supervisory issue alone. Payment firms, e-money institutions, fintechs, compliance teams, and investors should watch how regulators use governance, safeguarding, ownership, and financial crime controls as indicators of firm viability. The action signals that supervisory concerns can now lead to intervention measures that effectively remove a regulated firm's ability to continue operating.
Canada is pulling AI chatbots into platform safety regulation. AI firms, social platforms, trust and safety teams, identity providers, and compliance vendors should watch how age assurance, safety controls, reporting duties, and enforcement rules develop as digital safety becomes part of regulated online infrastructure.
Financial supervisors are beginning to treat AI as both a productivity tool and a threat multiplier. Banks, insurers, payment firms, fintechs, and security providers should expect greater scrutiny of fraud controls, cyber resilience, operational risk management, and third party technology oversight as regulators adapt supervision to an AI enabled threat environment.
Banking access is moving back onto the policy agenda as branch closures, digital exclusion, SME credit access, and local service gaps put pressure on financial providers. Banks, fintechs, credit unions, open finance firms, and data providers should watch whether the review leads to new access rules, credit data reforms, or stronger expectations around community banking infrastructure.
As advanced analytics become embedded in public institutions, governance questions increasingly extend beyond model performance. Procurement authority, accountability, oversight, operational dependence, switching costs, and public trust all influence how critical decision systems are adopted and maintained. The organisations that govern these systems may become as important as the organisations that build them.
The common thread is not AI, stablecoins, tokenization, or payments. It is access. Access to financial infrastructure, access to payment rails, access to private markets, access to banking services, access to digital assets, and increasingly access to machine driven financial execution. The next competitive battleground may not be who builds the best financial products, but who controls the rules, permissions, trust layers, and infrastructure that determine who can participate and under what conditions. Recent developments suggest those boundaries are on the move. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 20, 2026

Image: Unsplash/Headway
When did you last notice a sponsor banner on day three of a conference? Exactly. Multi-day events have a visibility half-life, and most brand strategies are not built to last beyond it.
The opening session energy is easy to ride. Sustaining brand presence through meals, breakouts, networking gaps, and general event fatigue is a completely different challenge.
Canada brought together close to 2,555 business events in 2025. The organizers who cracked visibility across all of that were doing something most were not. This article is about what that something looks like in practice.
Most event brands live entirely in the eyes. A logo here, a banner there, a branded tote bag everyone leaves behind on day two. The thing is, human memory does not work that way. People remember how a space made them feel far longer than they remember what it looked like.
This is where sensory marketing comes into play. When you own a scent in your registration lounge or a sound identity in your networking space, you are embedding your brand into the attendee's physical experience. Attendees may not consciously register it, but their nervous system does.
Pick one sense your brand can own consistently across all three or four days. A distinct coffee blend at your branded station. A low ambient sound identity in your lounge. Something tactile in your collateral that feels different from everything else on the table.
Consistency is what makes sensory branding stick. One well-chosen detail repeated across every touchpoint will outlast a dozen visually perfect installations that disappear into the background by midday.
Attendees build a mental map of your event space within the first few hours. Anything sitting in the same spot after that becomes part of the furniture. Your brand needs to travel with the crowd, not wait for the crowd to come back to it.
Think about where people already are. Breakfast queues, session transitions, charging corners, and the slow shuffle between keynote and lunch. Place something worth noticing in those pockets, and you are not interrupting anyone.
It does not have to be extravagant. Even something as simple as custom pens can do real work when placed at the right touchpoints across the event floor. Custom pens come in many forms, so think about your audience.
If you want something functional for a tech-forward crowd, business pens with a stylus are worth considering, notes Pens.com. If the setting is more formal, engraved pens would be a safer option.
Beyond that, rotate your brand presence between days. Move the activation, refresh the messaging, change the location. Give attendees something new to stumble into each morning.
A branded photo corner that was near the entrance on day one can migrate to the lunch area on day two. A product display that lived beside registration can reappear near the closing session. Movement creates the illusion of energy. It is this energy that keeps brands alive in people's peripheral attention.
Nobody wakes up on day two of a conference excited to visit a sponsor booth. But they will absolutely walk across a busy event floor to claim a reward or beat a leaderboard.
If your attendees skew younger, this is even more important. Conference News reported that 64% of Gen Z conference attendees actively seek immersive experiences with Instagrammable moments.
Give them a branded scavenger hunt with photo checkpoints. Build a leaderboard that updates in real time on a screen that everyone passes. Create a stamp card that unlocks something worth having at the end of day three.
The rewards do not need to be expensive. They need to feel earned. An exclusive backstage tour, early access to a session, or a branded item not available anywhere else at the event carries more weight than a generic goodie bag. When attendees are chasing something, your brand is what they are chasing.
Most brands show everything they have on day one. Full messaging, complete product story, every value proposition on the table before lunch. By day two, there is nothing left to discover, and attendees have mentally filed your brand away.
Flip that completely. Give attendees a reason to come back by leaving something unresolved on purpose. Day one, plant a question at your branded touchpoint. Something intriguing enough to linger. Day two, offer a piece of context that deepens it without fully answering it. Day three, deliver the payoff.
This borrows directly from the Zeigarnik Effect. It is a well-documented psychological principle showing that the human brain holds onto incomplete information far more stubbornly than resolved ones. An open loop in someone's mind is essentially a reservation your brand has made in their attention.
Practically, this could look like a teaser installation that changes each morning. A branded countdown with no explanation on day one. A partial reveal on day two. The full picture on day three.
Keep it visual, keep it simple, and make sure every element is unmistakably yours. Attendees will start talking about it, and that conversation is free brand visibility, traveling through every corner of your event.
Canada hosted approximately 2,555 business events in 2025, making it one of the busiest markets for professional gatherings in North America.
According to Conference News, 64% of Gen Z conference attendees prioritize immersive, Instagrammable experiences over traditional formats like panels and keynote presentations.
It is a psychological principle where incomplete information stays top of mind longer. Brands can use this to build multi-day anticipation among attendees.
| Strategy | Key Insight |
| Sensory Marketing | Brand recall builds faster when more than one sense is engaged |
| Moving Brand Touchpoints | Canada hosted ~2,555 business events in 2025, meaning competition for attention has never been tighter |
| Gamification | 64% of Gen Z conference attendees want immersive, Instagrammable experiences |
| Day-by-day Brand Storytelling | The Zeigarnik Effect proves incomplete narratives stay in memory longer than resolved ones |
Multi-day events are chaotic, exhausting, and exciting all at once. In the middle of all that, brand visibility can easily slip down the priority list. Keep it near the top. The strategies we mentioned in this piece are not complicated or expensive.
They just require some deliberate thinking ahead of time. Give your brand a plan that runs the full length of the event, and watch how differently attendees engage with it. The results are bound to speak for themselves.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 11, 2026
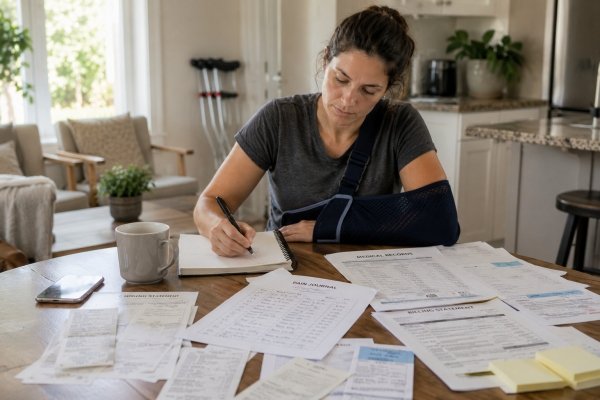
Pain and suffering is one of the most significant parts of a slip and fall claim. Unlike medical bills, pain and suffering have no receipts. What it's worth depends on how serious your injury is and how it has changed your life. Salamati Law Personal Injury Lawyer knows how to put real numbers behind what you've been through. A strong courtroom record means more than experience. It means better outcomes when pain and suffering are at stake. Knowing that connection helps you go into your claim with a clearer picture of what to expect.
The first thing courts and insurance adjusters look at is how bad the injury actually was. A minor bruise and a spinal fracture will never produce the same damages award. The worse the injury, the bigger the impact on your daily life and the stronger your case. Medical records, imaging, and doctor testimony prove the severity. An attorney who knows how pain and suffering are valued can make a real difference in what you walk away with.
The longer you live with pain and limitations, the more weight your case carries. An injury healing in two weeks carries far less weight than one lasting two years. If your injury is chronic or permanent, California law recognizes that as one of the most serious losses you can suffer. Keeping a treatment journal and staying consistent with your care shows exactly how long you've been suffering. Details about how the injury affects your sleep, your work, and your relationships carry real weight. A clear record from the day of the injury forward makes your claim significantly stronger.
When an injury stops you from doing things you used to do, that loss counts in your case. Courts recognize that losing mobility, missing work, or struggling to care for your kids is real damage. Medical experts can explain exactly how your injury limits what you can physically do. Your own words and your family's accounts put a human face on those limitations. The more specific and concrete those details are, the harder it is for anyone to dispute what you're owed.
A serious fall doesn't just hurt your body. Many people are left dealing with anxiety, depression, and trauma long after the physical wounds heal. California law recognizes those conditions as real losses you can be compensated for. But you need documented treatment from a mental health professional to back them up. Insurers will push back hard on psychological claims without formal clinical records to support them. Connecting the fall, the injury, and the mental health impact clearly and thoroughly can add significant value to your case.
California has no fixed formula to calculate pain and suffering in personal injury cases. Ultimately, courts and juries decide what your pain and suffering is worth based on what you can show them. The two most common methods for calculating pain and suffering in negotiations are the multiplier method and the per diem method. Multiplier calculations apply a set number to economic damages to estimate intangible harm. Per diem calculations assign a daily value to suffering and multiply it by duration. An experienced attorney can advise which approach best fits the facts of your case.
Severity drives everything. It determines your demand, shapes negotiations, and influences what a jury decides. Document all of it. The physical damage, what you can't do anymore, and the psychological weight of it. California law gives injured people a real path to meaningful compensation when the evidence supports it. A good attorney finds the parts of your suffering you didn't think to document and makes them count. This happened because someone else was careless. You shouldn't be the one absorbing the cost of that. Taking your claim seriously from day one is what gives you the best chance at a fair result.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 10, 2026 | NCFA Insight | Regulation And Policy, Capital Markets And Market Infrastructure
On June 10, 2026, the CFTC opened public consultation on proposed prediction market rules and the related 267-page pre-publication rule document. The proposal would create a formal review process for event contracts that touch sensitive areas such as gaming, war, terrorism, assassination, or unlawful activity.
The market is now large enough to force a real line-drawing exercise. The CFTC says total trading volume across registered prediction markets exceeded $25 billion in 2025. That remains small beside the roughly $31 trillion notional value of the broader futures market the agency regulates, but it is no longer a niche category.
The proposal targets event contracts covered by Section 5c(c)(5)(C) of the Commodity Exchange Act. The CFTC wants to amend Regulation 40.11, add Appendix F to part 40, define when a contract “involves” a listed activity, define “gaming,” and apply public interest factors to each contract under review.
Currently, a registered exchange can self-certify a contract, and contracts may begin trading quickly. The proposed framework gives the CFTC a 90-day review period for contracts that may involve one of the listed activities. The agency can request that trading pause during review, but the proposal says prediction markets are not required to follow that request. Some contracts could trade during review and later be blocked or delisted if the CFTC finds them contrary to the public interest.
The public interest test is practical. The CFTC would look at price discovery, information value, market integrity, and whether the platform can supervise the contract. That puts contract design, settlement data, surveillance, and trader controls at the centre of the review.
Sports are a key test case. The proposal treats contracts based on broad, objective sports outcomes more favourably, including final scores, point differentials, win-loss results, tournament advancement, team or individual statistics, and season-long performance metrics. The CFTC says these contracts can create useful price information when they use objective settlement criteria and are supported by suitable oversight and coordination with sports integrity bodies.
The CFTC is stricter around contracts tied to player injuries, officiating decisions, youth sports, cheating incentives, and misconduct. Injury contracts can create harmful incentives and expose medical information. Officiating contracts can put pressure on a small number of identifiable decision makers. Youth sports markets raise participant protection concerns.
DraftKings highlights why this rulemaking is needed commercially. Barron’s reports that annualized consumer trading volume on DraftKings Predictions reached $1.3 billion, up 24% from April 2026. Annualized total trading volume reached $3.1 billion, up 34%. Note, the numbers are early and based on company data.
DraftKings brings sports users, mobile distribution, pricing, promotions, and live event engagement. Kalshi and Polymarket bring event contracts, exchange style trading, collateral, liquidity, and surveillance. The CFTC proposal now pulls those models into the same regulatory conversation.
The user experience may look similar on a phone, but the rulebooks are different. Sportsbooks operate under gaming law. Prediction markets argue they are federally regulated event contract markets that support price discovery and information aggregation. The CFTC proposal tests where that argument holds, especially when sports contracts that are towing the line of integrity.
NCFA recently looked at trust questions around Polymarket influencer payments, including disclosure, paid promotion, and market credibility after a market goes live. The CFTC proposal moves the issue upstream. It asks which markets should be allowed to list in the first place.
Canada should watch closely. DraftKings already operates in Ontario’s regulated iGaming market, while prediction markets continue to test the line between financial contracts, gaming products, and information markets. The U.S. approach won't cleanly transfer into Canada, but it gives Canadian regulators, exchanges, fintechs, and other stakeholders an early view of the policy questions surrounding the table..
Will sports prediction markets become regulated financial products, sportsbook extensions, or a new category that forces regulators to redraw the line between trading, gaming, and market information?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
