





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 8, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization
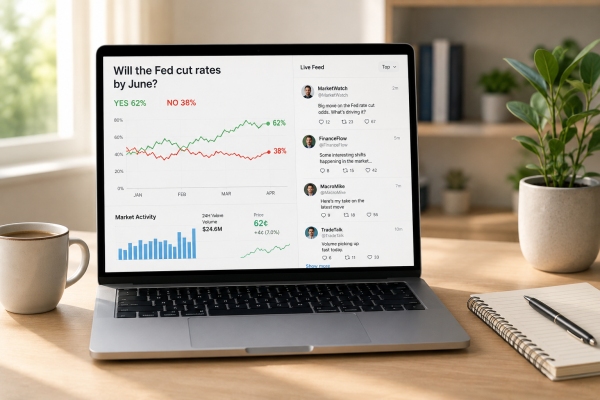
On June 5, 2026, Politico published an investigation into Polymarket's influencer marketing program. The report found that Polymarket chief marketing officer Matthew Modabber allegedly used a personal PayPal account to send at least $350,000 to content creators between January 2025 and February 2026. Politico's review identified over 490 social media posts promoting Polymarket that allegedly didn't clearly disclose paid relationships.
The investigation paints a picture far larger than a disclosure dispute. It's a rare look into how prediction markets are building distribution, visibility, and cultural relevance while simultaneously becoming one of the most discussed forecasting platforms in politics, sports, current events, and financial markets.
At least 20 creators identified by Politico promoted Polymarket after receiving payments. The report also found more than $2.5 million in transfers from the account to over 800 recipients during the period reviewed. Several influencers allegedly framed Polymarket odds as breaking news or authoritative indicators of future events. One creator told Politico that the company provided suggested post copy and encouraged promotion of specific markets.
The story reveals something many people inside fintech have quietly observed for years. Prediction markets are no longer simply markets. They are becoming media businesses.
Traditional exchanges compete for liquidity. Prediction markets increasingly compete for attention.
Polymarket's growth coincided with the 2024 U.S. election cycle, where billions of dollars flowed through election related contracts. Politico's reporting shows that influencer distribution became part of that growth strategy. The objective was not only attracting traders. It was turning Polymarket into a source people referenced when discussing politics, government decisions, sports outcomes, and breaking events.
The strategy appears to have worked. Today, prediction market odds regularly appear in mainstream media coverage. News organizations cite them. Social media users share screenshots of them. Investors discuss them. Politicians reference them. The market itself increasingly becomes part of the story.
It's a new category that's somewhere between financial infrastructure, media distribution, forecasting, and social networks.
The obvious asset is trading volume. The less obvious asset is trust. Many of the influencers highlighted in Politico's investigation promoted Polymarket as exceptionally accurate. Some described the platform as a superior forecasting mechanism compared to polling. Others highlighted successful market predictions as evidence of credibility.
This creates an unusual challenge. Prediction markets derive value from the perception that they aggregate independent information better than traditional alternatives. If users begin questioning how information reaches the market, who amplifies market narratives, or whether promotion and prediction are becoming intertwined, trust becomes harder to maintain.
The issue isn't whether influencer marketing is permitted. Many fintech companies use creators, affiliates, newsletters, podcasts, and social media personalities. The issue is whether users can clearly distinguish between market intelligence and paid amplification.
The most important opportunity may not be another prediction market. It's infrastructure that helps users understand how market information forms, spreads, and gains credibility.
As prediction markets, AI systems, social media platforms, and financial products become more connected, users need better ways to answer practical questions.
The next generation of prediction market innovation opportunities may come from building verification, disclosure, provenance, surveillance, and transparency tools around these markets.
These capabilities are still early. As prediction markets expand into politics, sports, finance, and public policy, demand for trust infrastructure should grow with them.
The Politico investigation focuses on influencer payments, disclosure practices, and marketing tactics, but the larger takeaway is that prediction markets are evolving beyond trading venues. They're becoming information platforms. That evolution creates opportunity, but it also creates responsibility. Today, Reuters posted about predication markets facing rising scrutiny over insider trading controls, reinforcing that these markets need trust infrastructure around promotion, surveillance, suspicious trading, and market transparency.
Markets that increasingly influence public understanding of events will face greater scrutiny over how information enters the system, how narratives spread, and how trust is earned. The next competitive opportunity may be proving that market intelligence can be trusted.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 30, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Regulation and Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026).
Tokenized bonds are moving from pilots into market structure work. Issuers, dealers, custodians, infrastructure providers, and regulators need practical answers on issuance, settlement, custody, disclosure, and secondary liquidity before tokenized fixed income can scale.
The value of cross chain infrastructure comes down to whether developers can route liquidity without exposing users to bridge complexity. The $230M private beta gives 0x early usage evidence, but the larger test is reliability across payments, RWAs, trading, and agent workflows when volumes move beyond controlled integrations.
Stablecoin licensing is becoming a competitive infrastructure tool for financial centres. Issuers, banks, PSPs, custodians, and regulators should track which jurisdictions turn stablecoin rules into live market access rather than policy design alone.
Tokenized money market funds are becoming part of institutional onchain liquidity infrastructure. Asset managers, custodians, PSPs, stablecoin issuers, and treasury teams should track how stablecoins connect with regulated fund products, redemption workflows, and stablecoin payment infrastructure.
Institutional DeFi is shifting toward custody controlled access models. Asset managers, custodians, exchanges, advisers, and compliance teams should track whether qualified custody plus curated onchain strategies becomes the operating model that brings DeFi exposure into regulated portfolios.
The useful signal is not simply another crypto loan product. It is committed buyer capital behind crypto backed credit, which can make the product more repeatable. The key risks remain collateral volatility, liquidation design, borrower suitability, and whether digital asset wealth can support credit access without turning into hidden leverage.
Crypto collateral can help asset rich borrowers avoid selling Bitcoin or USDC, but housing finance brings stricter expectations around suitability, custody, volatility buffers, and borrower protection. The product will need to prove it expands access without importing crypto market risk into mortgage underwriting.
Large banks are moving from stablecoin observation into direct tokenized money infrastructure. Treasury teams, payment providers, fintechs, custodians, and infrastructure operators now need to track whether commercial bank money becomes a regulated settlement layer for high value payments, liquidity management, and cross border transactions.
Western Union’s stablecoin entering a major crypto exchange channel adds another proof point for stablecoins becoming payment infrastructure. PSPs, exchanges, banks, remittance firms, and compliance teams should track how regulated issuers, fiat channels, and global payout networks connect. This adds a distribution proof point for regulated stablecoins. Western Union brings the remittance brand and global currency footprint, while Bybit brings crypto exchange access. The open question is whether USDPT becomes a settlement asset customers actually use, or another branded stablecoin competing for scarce transaction depth.
Central bank money settlement is being designed for programmable markets. Banks, FMIs, tokenized asset platforms, and settlement operators need to understand how RTGS synchronisation could connect central bank money with external asset ledgers and reduce settlement risk in digital markets.
Domestic real time payment systems are becoming exportable cross border infrastructure. Payment networks, banks, wallets, tourism merchants, and regulators are building direct QR payment links that reduce card dependence and make national payment rails usable outside their home markets.
Access to Canada’s payment infrastructure continues to widen beyond traditional banks and large financial institutions. Fintechs, payment providers, credit unions, foreign exchange firms, and digital finance companies are gaining a larger role in the systems and governance discussions that shape payment modernization.
Open banking is moving from one off payments into repeatable payment schemes with shared rules and commercial terms. Banks, PSPs, merchants, fintech platforms, and regulators should track whether recurring account to account payments become a real alternative to cards, direct debit, and closed wallet systems.
Card settlement is no longer limited to traditional banking hours or traditional settlement assets. Banks, acquirers, PSPs, stablecoin issuers, and fintech platforms should track how major payment networks use regulated stablecoins to support faster settlement, lower liquidity friction, and always on money movement.
Stablecoin remittances are moving from fintech experiments into established money transfer networks. Banks, PSPs, remittance firms, stablecoin issuers, and compliance teams should track how large networks use tokenized dollars to reduce settlement friction while staying inside regulated payment flows.
Pay by bank is becoming a practical payment rail strategy, not just a checkout concept. PSPs, banks, merchants, and fintech platforms should track how instant payment routing, risk controls, and settlement access shape competition against cards and traditional ACH flows.
Stablecoins are gaining traction in regulated payment flows, not just trading markets. Remittances remain one of the clearest real world use cases because settlement speed, foreign exchange costs, and cross border reach matter more than speculative activity. Canadian fintechs, PSPs, banks, and regulators should watch whether stablecoin based remittance models can scale while meeting compliance, safeguarding, and consumer protection requirements.
OpenPayd’s planned Nasdaq listing puts programmable money movement under public market scrutiny. PSPs, banks, stablecoin firms, embedded finance platforms, investors, and regulators should track how the listing exposes the economics, licensing footprint, transaction volume, and risk controls behind global payment infrastructure.
Crypto sanctions enforcement is moving deeper into exchange infrastructure and stablecoin flows. Exchanges, custodians, PSPs, blockchain analytics firms, and compliance teams should track how sanctions screening, stablecoin monitoring, and cross border counterparty controls become core operating requirements.
Technology policy is increasingly becoming infrastructure policy. As governments focus on AI capacity, cloud services, strategic data assets, semiconductor supply chains, and digital resilience, firms may face growing pressure to evaluate technology dependencies, procurement choices, hosting arrangements, and infrastructure risk. The result could be a more fragmented global technology environment shaped by competing sovereignty frameworks.
Consumer AI policy is moving toward practical controls for trust, consent and accountability. Banks, fintechs, AI firms, platforms and regulators should watch how user controls, complaint routes, audit trails and outcomes based duties apply when AI systems influence financial decisions or act for consumers.
The operating change is where AI work happens. If capable agents can run locally, more sensitive analysis, file handling, audio processing, and workflow automation can stay on device instead of moving through cloud APIs. That could change enterprise AI design, human oversight, privacy controls, and bot to bot workflows.
The United States is testing a lighter regulatory model for frontier AI that relies on voluntary participation, security evaluation, and industry cooperation. Financial institutions, fintechs, infrastructure providers, and AI developers should watch whether this approach accelerates deployment while maintaining confidence in systems that increasingly influence payments, capital markets, fraud controls, and critical infrastructure.
Revolut’s U.S. strategy shows why bank charters are becoming infrastructure plays for global fintechs. FDIC insured products, payment rail access, stablecoin services, and securities trading under one app could raise the competitive bar for sponsor bank dependent fintech models.
Stablecoin regulation is becoming a competitiveness question, not only a risk control exercise. Issuers, banks, PSPs, custodians, and policymakers should track whether the UK loosens its approach or keeps tougher safeguards that could limit domestic stablecoin scale.
Stablecoin supervision is becoming cross border supervision. Issuers, exchanges, custodians, payment firms, and compliance teams should expect more information sharing between regulators as stablecoin activity crosses jurisdictions, banking systems, and payment networks.
The word of the week is 'control'. Banks, payment networks, fintechs, custodians, stablecoin issuers, and AI providers are competing closer to the infrastructure layer, where settlement, custody, compliance, data, and distribution decisions get made. Which rails, licenses, partners, and operating models create durable access before the next layer of financial infrastructure gets locked in?
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 3, 2026 | NCFA Insight | Artificial Intelligence And Data, Regulation And Policy

On June 2, 2026, the Canadian Anti Monopoly Project released Parting Clouds: Creating A Competitive Marketplace For Compute that says three American companies control 85% of Canada's public cloud market. Canada wants sovereign AI. It's a gap that Ottawa needs to address before it commits more public money to AI infrastructure.
Globally, those same three firms Amazon, Microsoft, and Google, hold about 66% of the public cloud market. AI runs on compute, but most firms access that compute through cloud platforms. The more difficult it becomes to move data, workloads, and AI services between providers, the more dependent organizations become on a small number of platforms.
Compute means the physical capacity. Think data centres, chips, GPUs, servers, storage, power, cooling, and networks. Cloud is the commercial aspect that packages that capacity into services like APIs, software tools, security controls, and platform ecosystems.
Canada can fund more compute and still leave firms locked into the same cloud stacks. That concern connects to NCFA’s earlier analysis of Canada’s AI capital flight problem, where public AI investment doesn't always translate into long term domestic value especially if customers cannot move their data, workloads, models, and services without high technical and financial costs.
The CAMP report makes that point clearly. The goal isn't simply Canadian ownership. The goal is a market where customers can switch providers without rebuilding core systems. Most Canadian firms cannot replace that stack overnight.
Federal spending tells the same story. From 2019 to 2020 through 2022 to 2023, Shared Services Canada spent $310.4M on cloud services. The report says 66% went to Microsoft, 16% to Amazon, 14% to Salesforce, and 4% to other providers.
Cloud concentration already creates switching barriers through proprietary services, opaque pricing, and weak interoperability.
AI makes those barriers harder to manage. A fraud model, compliance agent, lending workflow, or payment risk tool can become tied to a provider’s data services, model tools, security layer, and deployment environment.
Moving clouds then means more than moving storage. It can mean rebuilding how the product works.
Five firms control about 75% of global AI compute power, with Google alone controlling about 31%. That concentration shows why AI sovereignty is not only about funding more capacity. It's also about keeping customers mobile before AI markets harden around the same platforms.
The name of this section is the report's strongest warning and it should affect Ottawa's strategy.
More Canadian data centres can help. Domestic compute can support sensitive workloads, national resilience, and local AI capacity. Ottawa has already backed 44 Canadian AI compute projects, but if public funding only creates protected local gatekeepers, Canada may replace one dependency with another.
The better goal is customer mobility. Can a Canadian fintech move workloads from one provider to another? Can a public agency compare cloud pricing easily? Can a startup use AI tools without being trapped inside one ecosystem? Can sensitive workloads use Canadian infrastructure without sacrificing portability?
Ottawa should fund infrastructure, but also change the market around portability, interoperability, transparent pricing, and competition.
The CAMP report recommends using public procurement to require portable data, interoperable services, and common technical standards. It also calls for closer scrutiny of egress fees, bundling, tying, discriminatory licensing, cloud credits, and acquisitions that absorb Canadian talent and intellectual property.
This approach has tradeoffs. Procurement can move faster than legislation, but it needs technical discipline. Competition enforcement can target lock in, but cases take time. Interoperability can lower switching costs, but it will not instantly match the full global scale of AWS, Azure, or Google Cloud. Domestic infrastructure can improve resilience, but only if it avoids new lock in.
Will Canada measure AI sovereignty by domestic capacity, or by real customer choice?
Will public funding require portability, open standards, and transparent pricing?
Will Canadian fintechs and AI startups be able to move workloads across providers without rewriting core systems?
Will the strategy treat cloud concentration as a competition issue, not only an innovation issue?
Will Canada build a market where providers compete on price, performance, trust, and service quality, or one where customers stay trapped because switching costs are too high?
If a Canadian fintech cannot realistically move its AI stack from one provider to another, who holds the leverage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure, SME Finance And Business Banking

A New York City sports bar has turned a Knicks NBA Finals promotion into a practical prediction market case study. According to NY Sports Day coverage of the promotion, The Jeffrey ('The bar') offered customers free drinks if the Knicks won Game 1 and placed a $5,000 position on a Knicks win through Kalshi, which could pay roughly $13,500 if the Knicks won.
The sports hook is fun. The business logic is better. The bar isn't simply betting on the Knicks with a local sportsbook. It's using a prediction market 'event contract' to run a promotion with a clear downside. If the Knicks win, the contract helps fund the free drinks. If the Knicks lose, customers pay their tabs and the bar loses the $5,000 position. The owner knows the maximum contract cost before the campaign starts.
The promotion creates two linked outcomes.
If the Knicks win, qualifying drink tabs become free and the bar gives up revenue it would otherwise collect. The Kalshi position pays on that same outcome, helping offset the waived tabs.
If the Knicks lose, the Kalshi position expires worthless, but the bar keeps normal drink revenue from customers who came in to watch the game.
It's a different use case from the prediction market stories NCFA has tracked around private market valuation odds and public market sentiment. Here, the contract supports a real world promotion with a known maximum contract cost.
This second outcome is what makes the structure interesting. The bar isn't left with only a $5,000 loss. It may also have a packed room, paid tabs, food orders, longer visits, and new customers. People may spend more because the tab could become free. That excitement is part of the promotion’s value.
The key business question is did the promotion generate enough incremental gross profit to justify the $5,000 contract cost if the Knicks lost? If yes, the losing contract is a campaign expense. If the Knicks won, the payout could help cover the free drinks liability (and possibly more). Either way, the owner puts a known price on the risk.
A traditional hedge normally offsets an existing risk. The bar created the risk by offering free drinks, then used Kalshi to offset part of that exposure.
The hedge quality depends on numbers that haven't been shared publicy like expected crowd size, average tab, food sales, qualifying drink costs, gross margin, and incremental revenue created by the promotion. If free drink liability reached $15,000 and the contract paid $13,500, the bar still carries some cost (of course the owner could choose to cap the number/cost of free drinks). If the room filled up and customers paid their tabs after a Knicks loss, the $5,000 contract loss may still be covered by extra business.
A patio restaurant could run a long weekend rain campaign. Customers get 25% off if rain exceeds a defined threshold during peak patio hours. The restaurant buys a weather contract tied to the same outcome. If it rains, the contract helps fund the discount. If it stays dry, the restaurant keeps full patio revenue and treats the contract cost as part of the campaign budget.
An event organizer could offer partial refunds if a transit strike disrupts attendance. A $3,000 event contract tied to the strike outcome could help cover refunds if the strike happens. If the strike doesn't happen, attendees pay full price and the organizer loses only the known contract cost.
A tourism operator could sell a “city wins, you save” package tied to a major festival or sports bid. If the city wins and the discount triggers, the event contract helps offset the promotion. If the city loses, customers still paid for the trip and the operator knows the campaign cost in advance.
Most prediction market coverage focuses on politics, sports, forecasting, or trading activity. The bar example points to a different use case of outcome based promotions where a business knows the most it can lose before launching the campaign.
It could make a difference for small businesses. Most small operations don't have access to custom insurance, futures contracts, or sophisticated risk tools. Prediction markets are easier to understand. A business can tie a campaign to a public event, cap the contract cost, and create a promotion customers want to talk about.
The risk is that promotion design can slide into speculation if owners do not size the contract properly. As prediction market controls tighten, businesses need clearer guardrails around contract sizing, customer disclosures, and whether the activity manages a real exposure or simply adds another bet. A useful campaign starts with the business exposure, not the excitement of the event. The bar example works as a test case because the contract ($5,000), the customer offer (free drinks), and the revenue opportunity ($13,500 + promo boost) all point to the same outcome.
If prediction markets can help small businesses run outcome based promotions with a known maximum contract cost, where should regulators draw the line between practical risk management and promotional trading?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
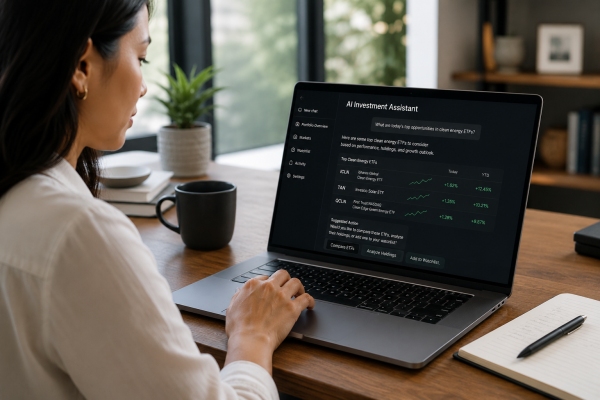
On May 26, 2026, Liquid launched Co Invest for ChatGPT and Claude, allowing users to research markets, construct portfolios, fund accounts, and execute trades from inside an AI conversation. The platform supports more than 500 markets across stocks, ETFs, commodities, crypto, FX, prediction markets, and pre IPO opportunities. Every trade still requires user confirmation before execution.
The launch is testing a new distribution model for financial services. For two decades, brokers competed to convince customers to visit websites and download apps. Liquid is testing a different idea. This is already happening in commerce. Agent driven checkout and payments are moving purchase decisions closer to AI assistants.
What happens if the customer never leaves the AI assistant?
Traditional brokerage growth follows a familiar formula. Acquire the customer. Get them into the platform. Keep them engaged. Generate more activity inside the platform.
Co Invest reverses that process. The customer already lives inside ChatGPT or Claude. Research happens there. Portfolio construction happens there. Market comparisons happen there. The trade happens there. The broker becomes the infrastructure underneath the conversation.
The launch announcement describes Co Invest as a way to move from market question to live execution inside a single workflow. If customers increasingly begin their financial decisions inside AI assistants, brokers may need to compete for agent connectivity as aggressively as they once competed for app downloads.
Much of the discussion around AI and investing focuses on autonomous trading. Liquid's current product doesn't do that. Users must still approve all trades before execution (at least for now). The assistant can research, compare, explain, size positions, and prepare orders, but it cannot freely move money or trade without permission (aka the agentic trading model).
Perhaps before markets and regulators reach fully autonomous investing, there will be a type of 'permissioned investing' that gets iterated before then. The goal isn't unrestricted authority. It's a type of controlled automation with clear limits, permissions, and accountability.
Example: A customer could authorize an agent to purchase a specific ETF under preset conditions, apply position limits, avoid leverage, stop trading after a certain loss threshold, and require additional approval for larger transactions.
This approach may appeal to regulators, brokers, and investors because it preserves accountability while reducing friction.
The benefits are easy to understand. AI agents can monitor markets continuously, enforce risk rules consistently, compare opportunities quickly, and reduce emotional decision making.
The risks are less obvious. If millions of investors eventually rely on similar models, data sources, prompts, and optimization goals, market behaviour could become more concentrated. Markets already experience crowding through index investing, quantitative strategies, and algorithmic trading. Agentic investing could introduce a new version of the same challenge if many systems begin reaching similar conclusions at the same time.
The concern is that a large number of investors could end up acting through similar decision frameworks without fully realizing it. A model that works well for one investor may create new market risks when millions of investors use similar prompts, data sources, and optimization rules. The result could be more crowded trades, sharper reversals, and less diversity in market decision making.
If AI assistants become the place where investors start financial decisions, brokers lose some control over the customer interface and relationship.
Distribution changes and brokers may need to prove itself to the AI systems that sit between customers and financial products.
That creates a different kind of competition. Brokers may be forced to compete on permission controls, API reliability, execution quality, and audit records as much as interface design.
The broker with the most reliable AI integrations may win more order flow than the broker with the best looking app.
Canada's discussions around consumer driven banking, digital identity, AI governance, retail payment oversight, and securities regulation all intersect here. If AI assistants become a gateway to investing, accountability becomes more important than automation.
Who approved the instruction? What permissions were granted? What limits were applied? What records were created? Who supervised the activity? Those questions are more important than whether the interaction started in a brokerage app or a chatbot.
Current securities rules already apply to firms using AI, and AI is creating new audit and authorization questions for financial firms. The harder challenge is determining how responsibility should be shared when AI systems increasingly participate in financial decisions and transaction workflows.
Liquid's launch doesn't answer those questions, but it provides an early look at where the industry may be heading.
If AI assistants become the primary place where investors research markets, compare opportunities, and initiate transactions, will brokers compete for customers or compete for connectivity to the agents representing those customers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 1, 2026
Image: Unsplash/Vladimir Solomianyi
For many small and mid-sized businesses, the gap between sending an invoice and receiving payment is one of the biggest threats to daily operations and steady growth.
Even when sales are healthy on paper, waiting 30, 60, or even 90 days for customers to pay can quickly drain working capital and stall planned investments.
Accounts receivable financing has emerged as a popular solution to this familiar problem, offering immediate access to cash that is otherwise locked up in unpaid invoices.
This guide explains how the model works, what types of arrangements exist, what they typically cost, and which businesses stand to benefit the most.
Accounts receivable financing, often abbreviated as AR financing, is a short-term funding method that allows businesses to access cash based on the value of their outstanding invoices.
A finance company advances a percentage of those invoices upfront, allowing the business to cover operational expenses while it waits for customers to pay.
The arrangement essentially converts a slow-moving asset into immediate working capital without the long approval timelines of a traditional bank loan.
This is particularly valuable for businesses that sell on net terms and routinely face cash flow gaps between delivery and payment.
Unlike a standard business loan, AR financing is secured directly against the value of unpaid invoices rather than broader business assets.
Approval focuses heavily on the creditworthiness of the customers who owe the invoices rather than the borrowing business itself.
This distinction means that companies with limited credit history or imperfect balance sheets may still qualify if their customer base is consistently strong and reliable.
Because the funding is tied directly to existing receivables, many providers do not classify it as traditional debt on the balance sheet.
Image: Unsplash/Scott Graham
To apply for AR financing, a business typically shares details about its accounts receivable, including aging reports, customer payment history, and the face value of outstanding invoices.
The lender then evaluates the quality of those receivables, the reliability of the customers, and the applicant's overall financial health.
Approval timelines vary widely depending on the type of provider chosen for the financing arrangement.
Traditional banks often take a week or longer due to extensive underwriting requirements, while specialized online lenders can sometimes approve and fund applications within 24 hours of submission.
Once approved, the business receives an upfront advance that usually falls between 70 and 95 percent of the eligible invoice value, with the remainder held in reserve.
After the customer pays the invoice, the lender releases the held-back balance minus any agreed-upon fees.
If the financing is structured as an asset sale, the lender also takes responsibility for collecting payment directly from the customer.
If it is structured as a loan, the business continues to manage collections and simply repays the advance once the invoice clears.
The market is served by a wide variety of lenders, and businesses comparing account receivable financing companies will encounter several distinct product structures.
Understanding the differences between these structures is essential to choosing the right fit for a given business model and cash flow pattern.
Invoice factoring is the most well-known form, where a business sells its unpaid invoices to a third-party factor at a discount.
The factor then takes over collection duties and assumes the day-to-day relationship with the customer for payment purposes.
This option suits businesses that want to outsource collections entirely and accept slightly higher fees in exchange for that operational convenience.
It works particularly well in industries like transportation, staffing, and manufacturing, where invoicing volume is high, consistent, and often spread across many customers.
Invoice discounting works similarly to factoring but allows the business to retain full control of customer collections and communications.
The unpaid invoices serve as collateral for a cash advance, while the business continues to manage payment reminders confidentially and on its own terms.
This structure appeals to businesses that prefer to keep their financing arrangements private and outside the awareness of their customers.
It is also a good choice for companies with established credit control processes and trusted client relationships that they do not want to disrupt.
Asset-based lending, often called ABL, is a broader financing solution that allows a business to secure a line of credit or loan against multiple types of assets.
Accounts receivable can be combined with inventory, equipment, or other tangible assets to expand the borrowing base.
This structure is particularly useful for larger businesses with diverse asset pools and ongoing working capital needs throughout the year.
It also offers more flexibility than a single-purpose factoring agreement when funding requirements fluctuate significantly with seasonal or project-based demand.
Selective receivables financing lets a business choose which specific invoices to fund rather than committing the entire sales ledger.
This gives owners precise control over how much they borrow, which customer relationships are involved, and when the financing is needed.
It is well-suited to companies that only need occasional cash flow support rather than a continuous funding facility.
Many growing businesses use it to manage seasonal demand spikes, large one-off opportunities, or unexpected expenses without locking themselves into longer commitments.
The primary cost of AR financing is the factoring or financing fee, which typically ranges between 1 and 5 percent of the invoice value.
The exact percentage depends on factors such as invoice age, customer creditworthiness, total volume, and industry risk profile.
Other potential costs can include set-up fees, administrative service charges, and interest on outstanding advances when the arrangement is structured as a loan.
Effective annual rates often fall between 15 and 35 percent, which makes AR financing relatively expensive compared with traditional bank loans but far more accessible.
Businesses that sell to other businesses on net 30 to net 90 terms typically gain the most from this type of arrangement.
Industries with predictable invoicing patterns, such as construction, transportation, staffing, healthcare, manufacturing, and professional services, are especially well represented among AR financing users.
Companies that struggle to qualify for traditional bank loans often find AR financing more accessible because approval rests largely on customer credit rather than the business owner's own credit profile.
Fast-growing firms also use it to bridge the gap between aggressive expansion and slower-paying customers without taking on long-term debt.
Accounts receivable financing offers a practical and increasingly mainstream way for businesses to unlock cash that is otherwise trapped in unpaid invoices.
With several product structures, advanced rates between 70 and 95 percent, and approval criteria centred on customer credit rather than the business itself, it provides a level of flexibility that traditional lending cannot easily match.
Before signing any agreement, business owners should compare providers carefully, read all fee schedules, and confirm whether the arrangement uses recourse or non-recourse terms.
Done well, AR financing can stabilize cash flow, support steady growth, and remove much of the stress that comes with waiting for slow-paying customers.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 1, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing
On May 28, 2026, Saris announced a $28.8M USD Series A to scale its agentic workflow platform for banks and credit unions. 8VC led the round, with participation from Audacious Ventures, Homebrew, Btech Consortium, and Service Ventures. Saris builds AI agents for lending, compliance, and operations, where financial institutions still spend staff time on document review, data validation, exception handling, and repetitive back office work.
Saris is a Canadian and US based AI fintech, not a Canada only vendor. The company’s hiring page describes a Canada and US hiring footprint, with hybrid workspace options in Montréal, Toronto, and San Francisco. This affects the business model. Saris can draw from Canadian AI and fintech talent while selling into the larger US banking market, where 8VC and enterprise partners can help open doors.
The Canadian link also sits in the founder story. Danial Jameel, Alice Dinu, and James Dang previously built Oohlala Mobile, later Ready Education, which Y Combinator lists in its Summer 2016 batch with a Montréal location. That history gives Saris a stronger base than a typical first time AI startup. Selling workflow software into regulated institutions takes trust, implementation discipline, and patience.
Saris now has more capital to compete in the US banking market, deepen integrations with Fiserv, Encompass, and MeridianLink, and grow the team that trains and deploys its AI agents. The strategic question for Canada is how much of that growth, talent, and customer expansion stays connected to the domestic fintech ecosystem.
Saris trains agents on each institution’s workflows and systems, then applies them to repeatable tasks across lending and operations under human supervision. Based on company reported figures, Saris’ agentic workflows automate up to 70% of consumer, mortgage, and commercial lending tasks and reduce costs by up to 35%. The platform also more than doubles output without adding headcount.
MeridianLink’s partner page says Saris works directly inside MeridianLink to automate document review, field validation, discrepancy remediation, post closing QA, and fraud alert resolution across consumer lending, DL4, and quality control workflows. MeridianLink also reports 99.8% field accuracy, 10x faster file review, and 3x underwriter and loan officer capacity, with one customer clearing a 600 loan backlog in four days.
So how does Saris stack up to competitors. Its target market extends beyond Canadian financial institutions, and its product fits banks and credit unions that already use systems such as Fiserv, Encompass, and MeridianLink.
US founded nCino brings global platform scale. More than 2,700 customers globally use nCino’s platform, including enterprise banks, regional banks, community banks, credit unions, challenger banks, building societies, and independent mortgage banks. That scale gives nCino a distribution advantage with institutions that want a broad cloud banking platform across lending, account opening, portfolio workflows, and customer engagement.
Saris does not need to replace the full operating platform. Its opening is file review, document checks, exception handling, and throughput inside systems institutions already use. That gives Saris a more focused sale where banks and credit unions already run core platforms or loan origination systems but still rely on staff to clear repetitive work.
Canadian based thirdstream is more domestic and onboarding focused. More than 50 financial institutions use thirdstream’s onboarding platform, including banks, credit unions, brokerages, and trust companies. Its strength is in Canadian account origination, identity verification, automated decisioning, real time account funding, and document management.
Toronto based Boss Insights sits closer to lending data infrastructure. Its platform gives financial institutions business lending data infrastructure across accounting, sales, banking, payroll, tax, analytics, monitoring, and customer portal capabilities. Boss Insights lists 1 API and 1,000 plus integrations, which places it closer to open finance, borrower data, and commercial lending intelligence than Saris’ document and workflow automation layer.
Saris looks strongest where banks and credit unions want targeted AI automation without a full platform replacement. Saris can draw from Canadian talent and a Montréal founder history while selling into larger US banking budgets. The question is whether customer relationships, implementation teams, and product leadership stay connected to Canada as the company grows.
Danial Jameel, cofounder and CEO of Saris:
“Our vision is a future where humans and AI work side by side in financial services.”
Saris’ raise shows financial AI moving into the parts of banking where cost, controls, and customer turnaround times get measured. AI can lower operating costs, but financial firms still need evidence that models remain fair, secure, monitored, and accountable. That operating pressure also runs through AI compliance and governance costs.
Should Canadian AI funding and fintech policy focus more on regulated proof points inside banks, credit unions, payments, lending, compliance, and capital markets rather than broad AI adoption metrics?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
