





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


CZ | Oct 14, 2025
Image: Freepik/wirestock
Changpeng Zhao (known as CZ) pleaded guilty in November 2023 to a single count of violating the Bank Secrecy Act after U.S. authorities found Binance had failed to maintain effective anti-money laundering controls. He stepped down as CEO and was sentenced in April 2024 to four months in federal prison while paying a $50 million fine. Binance also paid $4.3 billion to settle related charges with the Department of Justice and other agencies.
In May 2025, Zhao stated publicly that he had applied for a presidential pardon from Donald Trump. The U.S. Senate Banking Committee confirmed the filing’s existence in a letter dated May 15, 2025, asking the Department of Justice and the White House to clarify whether the request was being considered. The senators cited potential conflicts of interest tied to Trump family business ventures connected to crypto ventures associated with Binance.
On October 10, 2025, journalist Charles Gasparino reported on X that White House discussions about a possible pardon were “heating up.” The New York Post followed with a story two days later describing alleged internal debates over optics as the Trump administration manages several crypto-related policy files.
The article references unnamed sources close to both Zhao and Trump, who claim the president is sympathetic to Zhao’s case but mindful of potential conflicts due to family business interests in the crypto sector.
No formal statement from the White House, the Department of Justice, Binance, or Zhao’s legal team has confirmed these discussions. The White House press office maintains a standard position of not commenting on active or potential pardons. Therefore, these claims remain based only on Gasparino's report and subsequent media coverage.
Even without confirmation, the story matters because a pardon could erase Zhao’s criminal record, reopening the possibility for U.S. financial institutions to engage with Binance or its affiliates under less restrictive compliance terms.
It could also influence broader perceptions of how the U.S. balances enforcement with innovation across the $4 trillion global digital asset market. The Senate Banking Committee’s letter highlights bipartisan concern about transparency in how executive clemency intersects with crypto business interests, and spotlights growing concerns between pro-market reform vs accountability for compliance gaps in digital finance.
As of October 14, 2025, verified information is limited to Zhao’s conviction, sentencing, fines, and his publicly acknowledged pardon petition. Otherwise, there is no public record or filing in the Office of the Pardon Attorney showing that any pardon has been granted or is under formal review.
Until official confirmation appears, the case stands as a reminder that anonymous political reporting must be treated cautiously, especially if it could affect markets and trust in financial governance.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Bank of Canada | Oct 14, 2025
While almost everyone knows and/or has come to the same conclusion at one point or another, to hear the Bank of Canada's Senior Deputy Governor Carolyn Rogers deliver the same warning at the Canadian Club in Toronto on October 9, 2025, signals that perhaps the political critics against introducing more innovation and competition in the banking industry are going to have to acquiesce or Canada's economy and living standards will continue to crumble. The Bank of Canada's speech veers from the institutions usual restraint, which was published under the speech title, 'Productivity's competitive edge'.
In short, Rogers said while Canada’s banking system remains stable, it is also highly concentrated, a structure now holding back innovation, competition, and national productivity. Below we break down some of the key and relevant quotes.
1. “It would also be hard to argue, on any objective measure, that Canada’s banking system is anything other than an oligopoly.”
Rogers’ statement cut through years of careful language. Six institutions dominate almost every part of the financial system. When a few players control access to credit, payments, and capital, competition (and thus productivity) slows. Oligopolist margins stay high not from efficiency but from market power.
Consumers face limited choice, and startups face unfair barriers that restrict their ability to grow.
Over time, and in the face of growing geopolitical risk, the impact of stagnation ripples across the economy as productivity weakens, innovation slows, and the cost of doing business is stubbornly high.
2. “The six largest banks collectively hold about 93 percent of all banking assets.”
It's immensely profitable for banks to scale without real competition. When a handful of banks dominate that are protected by the government, the incentive to innovate diminishes.
New entrants face steep obstacles that make entry prohibitively expensive. Customer mobility is low because switching banks is difficult, and incumbents have little reason to compete on service or cost.
This level of concentration kills inertia before it's had a chance to get off the ground. A sort of regulatory conservatism where policy focuses on maintaining stability instead of competition and encouraging growth.
It also contributes to the misallocation of capital, with funding often directed toward established low-risk assets instead of dynamic and productive new ventures.
3. “Many argue that this level of concentration has clear negative impacts on productivity, innovation, capital allocation, cost and consumer choice.”
The adverse impacts of this prolonged conservative approach is visible in every part of the financial system. Weakened competitive pressure keep fees high and innovation limited. Fintech firms and non banks are stifled by access restrictions and a lack of infrastructure sharing.
The dominance of large incumbents has created a drag on productivity, discouraging foreign and domestic investment in innovative financial technologies and systems. Regulators, under constant lobbying pressure from powerful incumbent players, risk capture and caution.
Consumers end up paying more, while the wider economy suffers from slower capital formation and lower economic growth.
4. “Greater contestability, more new entrants and more innovation in our financial sector would lead to competition that’s good for consumers, for productivity and for our economy.”
Rogers' speech didn't stop at the problems. She pointed directly at the solutions that are actively in Canada's financial innovation pipeline that would open markets and increase contestability (read: competition).
Real Time Rail and open banking were designed to do just that. Both initiatives aim to make payments faster and more accessible while empowering consumers to use their data to get better services.
Yet both have been slowed by lack of political urgency. Every delay reinforces the oligopoly’s power and widens Canada’s productivity gap with other advanced economies.
5. “We should lean into it.”
Rogers closed by calling for action. Canada’s stability is valuable, but without competition, it becomes stagnation. Stability alone cannot deliver growth or innovation.
The future depends on whether policymakers are willing to favour market openness, accountability, and the kind of innovation that allows new participants to compete on equal ground.
While Canada’s policymakers have inched towards open banking and Real Time Rails, political will remains uncertain. The government signalled intent in previous statements, and regulators have continued to prepare the technical frameworks.
However industry and fintech groups and business leaders need visible deadlines, transparent implementation plans, and strong data rights today, not years from now after already waiting half a decade.
But rhetoric could be changing into real momentum because Canada's back is up against the wall and success depends on whether political leaders, not only regulators, commit to timelines, accountability, and measurable progress.
The federal economic budget is due this fall, and if the statement lacks specific commitments, the oligopoly will remain untouched yet again. If it includes firm milestones, open access, and clear delivery dates, Canada could finally begin to modernize its financial infrastructure and restore productivity growth.
By calling Canada’s banking system an oligopoly, the Bank of Canada directly linked banking concentration to productivity. Real Time Rails and open banking are are linchpins to unlock competition, expand consumer choice, and modernize how money moves. The National Crowdfunding and Fintech Association of Canada continues to advocate for more competition, access to capital, and policy frameworks that enable fintech innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Agentic AI Framework | Oct 6, 2025
iMAGE: Unlocking the right Agentic AI use cases (Deloitte, Sep 2025)
In September 2025, Deloitte released a research report titled, "Unlocking the Right Agentic AI Use Cases", outlining a structured way for evaluating where autonomous AI systems can deliver the most value. The report emphasizes that agentic AI is less about replacing jobs and more about transforming how organizations reason, decide, and learn at scale.
In this article, NCFA applies the framework to several common fintech processes from transaction monitoring to smart contract audits, and ranks how suitable they are for agentic AI adoption today and in the future as governance, transparency, and learning systems evolve.
Deloitte’s research includes 7 criteria to help developers determine how suitable agentic ai is for automating a particular process - see the table below.
| Criterion | Definition | Low End (Less Ideal) | High End (More Ideal) |
| 1. Reasoning and context | How much the process requires understanding across variables | Follows strict rules or thresholds | Requires judgment and context (e.g., fraud review) |
| 2. Autonomy and escalation | Degree of independent decision-making | Executes instructions only | Decides next actions, knows when to involve humans |
| 3. Goal orientation | Clarity of outcome or success metric | No clear endpoint | Defined goal (e.g., complete onboarding) |
| 4. Multistep nature | Whether multiple systems or tasks must be performed | Single-step task | Coordinates multiple systems sequentially |
| 5. Cyclic repetition | Frequency and feedback loops | One-time task | Repeats with measurable feedback loops |
| 6. Explainability | Transparency of reasoning | Opaque or black-box logic | Traceable reasoning with audit trails |
| 7. Continuous learning | Ability to learn and adapt | Static model | Improves through ongoing data input and correction |
Each process is scored out of ten points using Deloitte’s agentic AI use case suitability framework. The first score reflects current use case suitability in today’s environment. A second estimate indicates how use case suitability could rise in the future as digital governance, explainable systems, and automation standards mature over time.
Identity checks, risk screening, and document verification already rely on structured rules and data. Agentic AI fits naturally here, automating repetitive verification while escalating edge cases. As more jurisdictions adopt digital ID systems, this process could / will reach full autonomy with minimal human input.
Fraud detection already uses machine learning but agentic AI adds reasoning and adaptive responses. It can correlate patterns across payments, wallets, and behavioural data in real time.
With digital audit trails and explainable decision logs this process could operate fully autonomously under continuous supervision frameworks.
Matching incoming and outgoing payments is structured but still requires manual exception handling. Agentic systems can monitor ledgers, spot mismatches, and self-correct using feedback loops. As accounting platforms integrate autonomous verification standards, reconciliation could become a closed-loop agentic process with automated approvals.
Preparing reports for regulators involves collecting, validating, and submitting structured data. Agentic AI can manage workflows and track compliance deadlines. As regulators adopt machine-readable filing systems and trust frameworks, the need for human review will decline, allowing safe automation of most submissions.
Auditing blockchain contracts involves reasoning through logic and risk. Agentic AI can already identify anomalies and test execution scenarios. When standards for autonomous assurance and self-certifying code mature, agents could perform initial audits before human validation.
Today, human advisors must ensure advice suitability and fairness. Agentic AI can model goals and risk preferences, but oversight rules limit autonomy.
As explainability improves and regulators enable digital fiduciary models, these systems could autonomously generate and monitor recommendations.
Managing liquidity involves reasoning across cash flows, forecasts, and risk exposure. Agents can simulate scenarios and suggest rebalancing actions. Once real-time regulatory supervision and audit logs are common, agentic systems could adjust positions within safe parameters.
Tracking, transferring, and redeeming digital tokens are structured, rules-driven tasks. Agentic AI can monitor compliance and manage lifecycle events. As token standards and programmable compliance mature, these agents could manage portfolios with built-in governance.
Support interactions often follow clear procedures with measurable outcomes. Agentic AI can handle queries, resolve issues, and escalate complex cases. As conversational transparency and emotion modeling improve, these agents could manage most client interactions autonomously.
Scenario modelling tests business resilience under stress or uncertainty. Agentic AI can run continuous simulations, adjusting parameters as markets shift. In the future, these systems could interface with policy dashboards to flag emerging risks automatically.
This use case suitability assessment highlights how agentic AI can strengthen the efficiency, accuracy, and competitiveness of financial operations. Processes with structured data and repeatable outcomes like KYC, transaction monitoring, and reconciliation show the highest use case suitability today. These are areas where autonomous systems can already perform safely under human oversight.
For policymakers and regulators, the above examples demonstrate the importance of establishing auditable, explainable AI frameworks that allow more automation without compromising accountability.
For startups and financial institutions, the opportunity lies in targeting 'low lying fruit' (high-use case suitability functions) first to achieve measurable productivity and risk-management gains.
As data ecosystems become more interoperable and governance standards mature, the next stage of AI adoption will evolve from task-level automation to agentic collaboration. In this model, autonomous agents interact with systems, policies, and humans to drive continuous decision-making improvements.
This evolution could redefine the boundaries between financial service providers, regulators, and technology developers. Canada’s leadership potential lies in balancing innovation with responsible oversight, establishing itself as a trusted hub for explainable and accountable AI-driven finance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Regulation | Oct 6, 2025

The European Union’s transparency and copyright rules for general purpose AI models formally took effect on August 2, 2025. Enforcement faced resistance from industry and calls for delay but regulators seem intent on sticking with the original timelines.
Global tech leaders such as, OpenAI, Microsoft, Google, Anthropic, and Amazon have signed the EU Code of Practice for General Purpose AI Models, a framework quickly emerging as the new benchmark for responsible AI and a blueprint for innovators in Canada’s fintech and technology ecosystem.
The EU AI Act, published as Regulation (EU) 2024/1689 in the Official Journal of the European Union, moved into its second phase of implementation this summer. The new rules apply to general purpose AI models (GPAI) trained on large-scale data that can generate text, images, and audio. These models must now meet defined transparency and documentation requirements to operate in the European market.
In July 2025, the European Commission released the Code of Practice for General Purpose AI Models, available on its AI transparency portal. Although its voluntary, the Code itself translates the Act’s broad principles into operational commitments that technology providers can follow, and is becoming a global reference for responsible AI development.
The Code asks developers to be clear about how their AI systems are built. They must publish short summaries of training data and explain the steps taken to reduce bias and misinformation. It marks the first time transparency in AI has been defined as a regulated standard rather than a voluntary goal.
It also sets new expectations for how copyrighted material is handled. Companies must confirm that training data was obtained legally and that rights holders who chose to opt out were respected. They are encouraged to build safeguards that stop AI models from reproducing protected content and to keep a public channel open for complaints.
Finally, the Code highlights safety and security as core responsibilities. Models that use very large amounts of computing power must undergo risk assessments, maintain strong cybersecurity protections, and keep records of any misuse or technical incidents. This brings AI oversight closer to the risk management standards already used in finance.
The European Commission’s list of signatories includes OpenAI, Microsoft, Google, Anthropic, Amazon, IBM, and Mistral AI. Their participation gives the voluntary Code practical weight and sends a message that transparency and accountability are compatible with innovation.
Meta has not signed, citing uncertainty about enforcement and consistency across European member states. It shows the divide between companies moving early to align with transparency and those waiting for further legal clarification. Early signatories are setting examples that others may have to follow once regulation tightens.
Companies that publish their data summaries and risk documentation not only comply with regulation but also strengthen their position with investors and partners. For companies that can responsibly demonstrate how they legally sourced their data to train their models, it can influence purchasing decisions in regulated sectors like finance, health, and insurance.
For AI developers, transparent practices can also lead to improved internal knowledge. Knowing exactly what data was used to train a system and where risks exist improves quality and helps teams innovate with confidence. Transparency is evolving from a compliance task into a type of competitive strategy.
Canada’s Artificial Intelligence and Data Act (AIDA) was part of Bill C-27, which died on the Order Paper when Parliament was prorogued in January 2025. For now, Canada's Voluntary Code of Conduct on the Responsible Development and Management of Advanced Generative AI Systems is still Canada's main AI policy reference. The Code is endorsed by companies such as Cohere, OpenText, BlackBerry, and Telus, and encourages transparency and human oversight in the use of generative AI. While not legally binding, it mirrors much of the EU’s direction and provides a practical foundation for organizations preparing for future legislation.
Canadian firms that sell or integrate AI systems in the European market must already comply with the EU AI Act transparency and copyright rules. The regulation applies outside the EU as well, meaning any company offering AI services or products in Europe must meet the same standards as European providers. This includes publishing training data summaries, documenting data sources, and ensuring lawful use of copyrighted material. For fintechs and technology companies, aligning early with EU standards is not just about compliance. It can help position them as credible and trusted partners in markets that increasingly link transparency with competitiveness.
AI transparency and innovation are now hand in hand in the EU. While enforcement of the new framework will happen gradually, the market impact is immediate with companies now competing not only on performance but on integrity. Companies building transparency into product design, investor communications, and risk management will benefit by transforming responsible AI from an obligation to a strength.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments | Oct 2, 2025
Image: Ron Morrow, Executive Director, Bank of Canada (CPA The One Conference Sep 18, 2025)
On September 18, 2025, Ron Morrow, Executive Director of Payments Supervision at the Bank of Canada, delivered a speech at the CPA The One conference titled, "Making change Accelerating payments innovation". He spoke about a vision for Canada’s payments future, one where innovation, oversight, and competition intersect. Stronger oversight and modern payment rails will make the system more competitive and inclusive.
This article unpacks select key quotes and and highlights two sides of the coin for stakeholders to see both sides and the trade-offs that come with it. For Canada, the task now is not whether to act, but how to add momentum and keep pace in a global race.
“Almost 1,500 payment service providers are now required to register with the Bank under the Retail Payment Activities Act.”
For the first time, nearly fifteen hundred retail Payment Service Providers (PSPs) are being pulled into the regulatory fold. Supporters argue that this gives consumers and businesses more confidence when using new services and helps fintechs compete on equal footing with banks. By ending the perception that startups operate in a grey zone, it could make investment in the sector more attractive.
But compliance comes with costs, and many small firms run lean without a large legal or regulatory staff like banks. What may feel like light reporting to a large bank can feel like a heavy lift for a ten person startup. In the worst case, it could drive consolidation that narrows competition instead of expanding it.
“Our job is to make sure that innovation in the payments system can proceed in a way that is safe, sound and reliable.”
Safe to say that Canadians will only embrace new forms of payments if they trust them to work without interruption and to protect their money. Regulation that sets clear expectations can provide certainty for innovators, giving them a stable foundation to build on.
Yet safety can lead to an abundance of caution that could slow innovation. Other countries, from the UK to Singapore, have shown that regulators can allow pilots and sandboxes to move quickly while still managing risk. If Canada puts too much emphasis on stability, we'll fall behind in a global race where trust and speed both matter.
“We are working to expand access so that more providers can offer services directly through Canada’s core payment systems.”
Direct access to national infrastructure is potentially transformational. If fintechs can gain access without going through a big bank, they can offer faster and cheaper payments. This would lower costs for consumers, ignite competition, and open the door for creative new services in areas like cross border transactions.
The flip side is that these core systems were designed with large, well capitalized institutions in mind. Smaller entrants may not have the same buffers to handle liquidity shocks or technical breakdowns. One major failure could undermine confidence across the entire network. The challenge is designing an access model that widens competition without weakening stability. Payments Canada who is overseeing Canada's payments modernization has delayed implementation numerous times, and industry is frustrated. In May 2025 however, they announced that the technical build will be completed by Q3 2025 and they plan to test the system throughout 2026.
“Through our work with the BIS Innovation Hub, we are exploring the potential of new technologies such as tokenization and artificial intelligence.”
Engaging with international financial innovation hubs allows Canada to stay connected to the latest fintech and payments research, including stablecoins and tokenization. It also helps Canadian fintechs align with emerging global standards, making cross border scaling easier. Last June 2024, the BIS and Bank of Canada Launched the BIS Toronto Innovation Centre.
The real risk lies in harmonization at home. Canada’s financial system is driven by a concentrated banking sector and diverse regional economies, where inter-provincial differences can create barriers to trade and investment. If newly adopted financial technologies and related reforms aren't designed to work seamlessly across all provinces and territories, Canadian markets could become further fragmented with unwanted barriers and compliance costs. Canada needs to strengthen its internal market with more competition and innovation to be able to complete with strength globally.
“Payments innovation cannot be separated from broader efforts like open banking.”
If Canada completes payments modernization while also enabling consumers to share their financial data securely (open banking, consumer driven finance), the market could see a boon of new service models and tools that bring real competition to a system long dominated by incumbents.
Skepticism is very real though with Canada lacking the political will to finally implement open banking after promising it and studying it for years. Without binding timelines, many in the industry hear speeches like this one but actions speak louder the words. For fintechs, the question remains whether it is worth investing in solutions that depend on open banking when political momentum has not yet delivered results, or opt for new pathways. The latest is that open banking in Canada will land in 2026., with further delays will have significant consequences for innovation and consumer choice in Canada.
Ron Morrow’s speech delivers a clear vision and direction for modernizing Canada’s payments landscape. Expanded oversight, broader access to rails, and participation in global innovation networks all point to a more open and competitive future. If open banking also arrives in 2026, these reforms could unlock real benefits for consumers and fintechs alike. But the devil’s advocate cannot be ignored. Here's a streamlined version of Morrow's speech, 'Cashing in on Payments Innovation' (fingers crossed)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crowdfunding | Oct 1, 2025
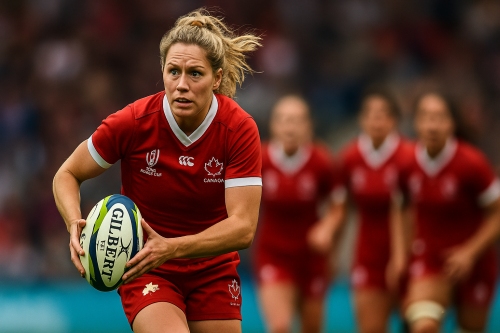
Image courtesy of AI
On March 7, 2025, Rugby Canada announced a bold public campaign to fund its women’s high performance team to England 2025. The campaign laid out a $1 million shortfall to cover the full season's program that costs $3.6 million (but the union's budget fell short). So to close the funding gap, they opened the doors to fans, alumni, and corporate donors and launched a dedicated donation portal for this effort: Mission: Win Rugby World Cup 2025 donation portal.
That night, the campaign thermometer sat at zero. By morning, it was alive as part financing tool and part storytelling engine that sparked a national movement in Canadian sport.
Rugby Canada needed more than dollars. They needed narrative. The early campaign push did three essential things well:
They didn't just ask for support but described the exact dollars missing and how each contributed dollar would map to camps, nutrition, recovery, and test matches.
Supporters weren’t just donors but they were treated as 'partners' in getting the Canadian Women's Rugby team ready for the World Cup 2025, a massive global sporting event.
Independent rugby media tracked progress. In April, RugbyPass ran a report noting the still‑open funding hole and provided key updates in how far along the drive had come, and how much further they still needed to go to achieve their mission.
As the 2025 Women's Rugby World Cup (hosted in England) drew closer and closer, media narratives framed Canada not just as underfunded underdogs but as gritty, scrappy, and deserving contenders. Sky Sports ran a feature titled “How non‑professional Canada crowdfunded its way to the final push,” saying pledges “reached 95 percent.”
Meanwhile, ESPN ran a narrative piece under the banner “Canada crowdfunded their way to the World Cup” juxtaposing the team’s funding shortfall with their on‑field ambitions.
Kudus to participating media that helped raise awareness for such an important Canadian funding drive. It really shows what's possible when the full ecosystem gets behind an initiative and drives momentum forward. There's a natural connection between executing a well timed and focused financing campaign and executing a key sports performance, and the public knows it. #ElbowsUp
When England 2025 kicked off, Canada stepped onto the pitch motivated by even greater purpose, not a team suffering by funding shortfall anxiety.
In pool play they went undefeated, carving out physical, disciplined performances that turned heads.
In the quarter final, they defeated a powerful Australia squad.
In the semi final, they shocked the rugby world by defeating New Zealand (perennial favourites) to reach their first Women’s Rugby World Cup final.
On September 27, before a packed Twickenham, Canada faced hosts England. They lost but not meekly. In the aftermath, coach Kevin Rouet and captain stressed that the match was decided on performance, not excuses, a point that resonates in Reuters’ coverage of the final.
Crowdfunding bought the players the chance to compete on equal footing, free of resource excuses. The lesson for Canada as a sporting nation was significant. When supports and fans step in to close gaps, institutions can't ignore the demand for sustainable, professionalized backing of women’s rugby.
Players adjusted their off season budgets and personal spending to show they were all in on the campaign narrative.
Coaching staff scheduled extra camps contingent on fundraising milestones, keeping the team in lockstep with the thermometer.
Each media checkpoint (50%, 80%, 95%) became a moment of drama as the story unfolded. Would the final stretch succeed or stall? That tension made the campaign itself a parallel storyline to the competition.
Critics wondered whether public fundraising blurred lines between sport and fandom but supporters embraced the risk, seeing their dollars as equity in national ambition at a time when Canada needs to buckle down and drive through the line.
When everyone's in the same boat, the winds will sail.
This was more than just a funding story. If you want one of those, feel free to read the real story of access to capital. It was about turning a resource gap (a modern day limitation) into shared ownership.
Canada’s women made their financial constraints visible, linked every dollar to performance outcomes, and invited supporters to become backers in the journey. That transparency changed how Canadians see women’s sport funding not as charity, but as investment with real returns.
The campaign also created accountability. Once the thermometer went public, the team owed backers results, not just thanks.
The story will not always be this dramatic, but the connections and motivations are real, and crowdfunding amplifies that blueprint. Define the gap, own the narrative, attach every contribution to a tangible outcome, and treat supporters as true partners.
Collaboration was at the core! Players, fans, alumni, sponsors, and media all carried their share of the work. As Canada’s women look beyond 2025, the responsibility now shifts to institutions, national sport bodies, sponsors, and public agencies to ensure future generations no longer need to crowdfund their path to the world stage, or maybe they should! #GoCanada
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | Sep 30, 2025
On September 29, 2025, California Governor Gavin Newsom signed the Transparency in Frontier Artificial Intelligence Act into law (Senate Bill 53), the first binding U.S. law directed at frontier AI developers.
The law requires companies with the largest models to:
Unlike last year’s failed SB 1047, the new law does not require third-party audits or shutdown mechanisms. Instead, it focuses on transparency. Starting in 2027, anonymized summaries of incidents will be published annually to inform the public.
Developers that cross the extreme compute threshold of 10^26 FLOPs (computer system that can process a hundred trillion trillion mathematical operations) OR exceed $500 million in annual revenue.
The response has been mixed. Anthropic backed the compromise version after negotiations, while Meta set up a state-level PAC and OpenAI pushed for federal or international alternatives.
Critics warn that duplicative state rules could fragment compliance.
But still, California has a history of rules spreading nationally, from privacy to environmental standards. OpenAI, Anthropic, Meta, and Google DeepMind are among the large AI labs likely affected by SB 53. Three of which are based in California with DeepMind is headquartered in the UK but parent company Alphabet is in Cali.
Globally, the EU AI Act regulatory framework is already in force and more comprehensive, applying risk-based obligations across industries. Canada’s Artificial Intelligence and Data Act stalled earlier this year, leaving the country with a voluntary code of AI ethics. Other U.S. states may also look to California’s model as a template for their own AI laws.
For AI finance fintechs, it's pretty clear to see that California has drawn a line in the sand to publish safety processes, disclose updates, and prepare reporting systems. Canadian startups and scale-ups serving California clients will need to align to ensure compliance, and these same steps could form the basis of a future Canadian law if Ottawa revives its AI plans. NCFA has published numerous articles on how AI is reshaping fintech to highlight opportunities and risks.
California’s new AI law shows how U.S. states are moving ahead with governance while Washington is moving in the opposite direction on immigration. The two policies together are forcing companies to rethink where they build and hire.
On September 21, 2025, USCIS raised H-1B visa fees for the first time in nearly two decades. The registration fee jumps from $10 to $215, the petition filing fee increases to $780, and employers must also pay a $600 asylum surcharge on each petition. In addition, a $100,000 payment applies to every new H-1B petition filed after September 21, 2025.
For large technology firms submitting thousands of registrations, lottery costs alone now reach six figures (i.e. registration, petition and asylum fees), and with the $100,000 payment layered on top, sponsoring one skilled worker requires an unprecedented financial amount before salaries are even considered.At the same time, Senate Bill 53 requires large AI developers in California to comply with the AI transparency and safety law. For startups and scale-ups already facing higher labour costs from the visa changes, the compliance load makes expansion in California more expensive than some alternatives.
For Canada, this combination creates an opening. The federal government has kept immigration channels and recently launched Canada's first ever tech talent strategy in 2023, while luckily leaving it's own AI governance as a voluntary code of conduct instead of a binding law. Companies that find U.S. rules and visa costs too heavy can find both talent and policy breathing room north of the border. WELCOME TO CANADA!
As a caveat to the message that Canada welcomes top entrepreneurs, the reality is that Canada’s Start-up Visa (SUV) program which was created to bring global founders into the country is currently plagued with a backlog of more than 42,000 applications as of July 2025 with wait times longer than four years as reported by Betakit. As a result, the government added a three year open work permit so entrepreneurs can start working while waiting for permanent residency, but the backlog itself remains a major barrier. Ottawa also introduced a cap of 2,000 SUV applications in 2025 and plans to reduce it further to 1,000 in 2026. By comparison, Canada’s Innovation Stream under the Tech Talent Strategy remains far more flexible and designed with urgency in mind; it's LMIA (Labour Market Assessment Impact) exempt and can be processed in weeks.
Instead of blunt national cuts, Ottawa could manage qualifying organizations application caps that grow or shrink depending on their results. Incubators, angel groups, and venture funds with stronger records of scaling companies, creating jobs, and raising capital could endorse more entrepreneurs, while newer or weaker ones would be limited until they prove outcomes. This approach would raise quality of applicants while keeping the door open to founders from diverse regions. Coupled with the open work permit, it could restore SUV as a credible and inclusive option for entrepreneurs choosing where to build.
Canada now has a limited window to attract both talent and innovation by pairing flexible immigration with a pragmatic approach to AI governance. Ottawa's next steps will determine how long that window stays open.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
