





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 20, 2026 | NCFA Resource | Risk Compliance And Regtech, Artificial Intelligence And Data

On June 18, 2026, IOSCO published a Supervisory Tech (SupTech) report called 'Mapping the Use of Technology in Financial Supervision', a global survey of 49 authorities on how regulators are using technology to improve financial supervision. The report maps where SupTech is already being used, what is driving adoption, and which barriers are slowing progress.
SupTech is becoming part of regular ongoing supervision, and is no longer an experiment. Regulators are using technology to improve efficiency, receive and analyze information faster, and strengthen oversight across investor protection, market conduct, capital markets, and emerging areas such as digital assets.
The report gives regulators, fintech firms, and regtech providers a global benchmark for how supervisory technology is being adopted. It covers strategy, budgets, leadership, data, cloud infrastructure, AI, cybersecurity, digital assets, cooperation, and workforce planning.
IOSCO found that efficiency is the main driver of SupTech adoption, followed by faster access to information and stronger supervisory capabilities. AI applications, improved data access, and cloud infrastructure are the leading technology enablers.
Consumer and investor protection and capital markets supervision are the most developed use cases. Digital assets are less mature today, but interest is rising. That gap matters because market activity is moving faster than many supervisory tools.
The report also shows why implementation is hard. Cyber risk, third party dependencies, operational risk, funding gaps, and skills shortages remain major constraints. Many authorities have strategies under way, but full implementation is still uneven.
This resource is useful for securities regulators, policy teams, regtech firms, fintech compliance teams, financial institutions, digital asset platforms, market surveillance teams, and researchers tracking regulatory modernization.
It is especially useful for organizations building or assessing tools for market monitoring, fraud detection, complaints analysis, digital asset oversight, supervisory analytics, data collection, and AI enabled supervision.
The strength of this resource is its global scope. The survey covers authorities across all IOSCO regions and gives readers a baseline for comparing SupTech maturity, priorities, and constraints.
It is also useful because it avoids hype. The report shows that many regulators are still using mid level technologies and practical tools. Advanced analytics and machine learning are important ambitions, but funding and implementation capacity remain real limits.
The limit is that it's survey based, not a product guide. It doesn't rank vendors, provide implementation playbooks, or prove which tools produce the best supervisory outcomes. Its value is in the benchmark, the use cases, and the policy signals.
IOSCO SupTech Report (primary report)
IOSCO SupTech Media Release (announcement summary)
AI Agents Enter Governed Financial Workflows (AI governance and controls)
MIT AI Risk Repository For Fintech Governance (AI risk taxonomy resource)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 25, 2026
After a crash, stop your vehicle and turn on your hazard lights. Check everyone for injuries and call 911 if anyone is hurt. Move out of traffic if it's safe, then exchange names, licence, and insurance details with the other driver. Take photos of the scene, the damage, and any visible injuries. Collect contact info from witnesses. See a doctor within a day or two, even if you feel fine, and report the collision promptly.
You're driving home along Crowchild Trail when the car ahead stops short, and suddenly your morning turns into a screech of brakes and crumpled metal. Your heart is pounding, your hands are shaking, and your mind goes blank. What now? Those first rattled moments are the hardest, and that's the whole reason a plan helps.
Knowing what to do after a car accident in Calgary can protect your health, your wallet, and your legal standing long after the tow truck leaves. What you do at the scene, and in the days that follow, tends to shape your insurance payout and any claim you might file. If injuries are involved, a Richard Edwards car accident lawyer can walk you through your options once the dust settles.
This guide breaks the process into plain, manageable steps. We'll start at the scene, work through the first critical days, and cover how to handle insurers and protect your rights from there.
A collision throws your day into chaos, but the actions that follow have a clear order. Think of it as three phases: securing the scene, gathering proof, and looking after your health. Working through these steps to take after a car accident keeps you safe, satisfies Alberta law, and lays the groundwork for any claim down the road.
Your first job is to avoid a second collision and tend to anyone who's hurt. Leaving before you've handled the basics can lead to demerit points or worse under Alberta law, so stay where you are until the essentials are done.
Memories blur, and stories shift over time, so good documentation pays off later. The more you gather now, the smoother things go with insurers or lawyers.
One thing to skip: don't apologize or admit fault, even casually. A simple "I'm sorry" can be twisted later. Fault gets sorted out through proper investigation, not roadside conversation.
Alberta sets clear thresholds for reporting. You're legally required to file a report if anyone is injured or if total property damage tops $5,000, a figure the province has confirmed stays unchanged for 2026.
| Situation | What to Do |
| Injuries or a death | Call 911 immediately; police will attend |
| Damage over $5,000, no injuries | Report at a Collision Reporting Centre |
| Suspected impaired or hit-and-run driver | Call 911 right away |
| Minor damage under the threshold | Exchange info; reporting may not be required |
Here's the catch with adrenaline: it can hide real pain for hours. Injuries like whiplash, concussions, and soft-tissue damage often surface a day or two later, so a prompt medical visit guards both your health and your record.
Your health and the scene are squared away. Now comes the part most people dread: money and paperwork.
Once you're safe and checked over, attention turns to recovering your losses. This stage feels the murkiest, since it mixes paperwork, deadlines, and conversations with adjusters whose goals don't always line up with yours. A bit of preparation makes a real difference.
The sooner you notify your insurer, the better. Most Alberta policies give you a window to report, often around 30 days, though checking your own policy beats guessing. Knowing how to file a car accident insurance claim keeps you organized from day one.
A word of caution: your insurer may ask for a recorded statement. You're expected to cooperate, but you don't have to give a recorded statement before getting advice. Those recordings can resurface during settlement talks, so it's smart to pause first.
Every standard auto policy in Alberta includes Section B, or "no-fault" accident benefits. These pay out regardless of fault and kick in quickly, covering early costs while any larger claim works its way through. They come straight from your own insurer.
| Benefit | Typical Coverage |
| Medical and rehabilitation | Up to $50,000 over two years |
| Physiotherapy, massage, chiropractic | Capped sub-limits per discipline |
| Disability/income replacement | Up to $400 per week, if eligible |
| Death and funeral benefits | Limited support for families |
Section B handles immediate costs, but it doesn't replace a claim against an at-fault driver. The car accident claim process Alberta drivers navigate gets more involved here, with two moving parts to track:
Sorting out fault, future care costs, and lost income can quickly outgrow a do-it-yourself approach. So how do you know when it's time to bring in a professional?
A crash is jarring, but the path forward gets manageable once you break it into steps: secure the scene, document everything, look after your health, and handle the paperwork with care. Calm decisions early on tend to pay off when claims and deadlines arrive.
Some situations call for a steadier hand. Knowing when to hire a car accident lawyer usually comes down to the stakes:
You don't have to sort through all of it alone, and you don't have to decide everything today. Take the first steps, protect your health, keep good records, and reach out for guidance when the situation calls for it. Handled thoughtfully, even a rough day on the road becomes something you can recover from, both physically and financially.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 23, 2026

The MSB license in Canada (Money Services Business registration) is one of the most important regulatory requirements for companies operating in financial services, fintech, and crypto-related sectors. It is administered by the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) and is designed to ensure transparency, prevent money laundering, and support compliance with anti-terrorism financing laws.
As financial technologies evolve, Canada continues to refine its regulatory framework, making the MSB registration process essential for both domestic and international companies offering money-related services in the Canadian market.
An MSB (Money Services Business) in Canada is not a traditional “license” in the way gambling or banking licenses are issued. Instead, it is a mandatory registration with FINTRAC for businesses that provide specific financial services.
Once registered, a company is recognized as a regulated financial entity and must comply with Canadian AML (Anti-Money Laundering) and CTF (Counter-Terrorist Financing) regulations.
Businesses that typically fall under MSB regulation include:
If a business performs any of these activities in Canada—or serves Canadian clients—it may be required to register as an MSB.
The governing body responsible for MSB registration is FINTRAC (Financial Transactions and Reports Analysis Centre of Canada).
FINTRAC’s role includes:
Failure to comply with FINTRAC regulations can result in severe penalties, including fines, criminal charges, and business restrictions.
Many companies mistakenly believe MSB registration only applies to banks or large financial institutions. In reality, the scope is much broader.
You likely need MSB registration if your business:
If you send or receive funds on behalf of clients, including cross-border transfers, registration is mandatory.
Crypto exchanges, trading platforms, custodial wallet providers, and even some DeFi services may fall under MSB rules.
Any business converting fiat currencies (e.g., CAD to USD, EUR to CAD) must register.
Payment gateways and fintech companies handling third-party payments are typically considered MSBs.
Issuing prepaid cards, digital wallets, or stored-value accounts can also trigger MSB obligations.
Registering as an MSB is only the first step. Businesses must comply with ongoing regulatory obligations under Canadian law.
Every MSB must implement a full Anti-Money Laundering compliance program, including:
MSBs are required to maintain detailed records of transactions, including:
Records must be stored securely for a minimum period, usually five years.
Companies must report specific types of transactions to FINTRAC:
MSBs must verify customer identities using reliable documentation and risk-based approaches. This includes enhanced due diligence for high-risk clients.
The MSB registration process is relatively straightforward but requires accuracy and compliance readiness.
Before applying, the company must be legally incorporated in Canada or have a registered Canadian entity.
A full AML compliance program must be prepared, including policies, risk assessments, and reporting structures.
The business submits an online application through FINTRAC’s registration portal, providing:
FINTRAC reviews the application and may request additional information. Once approved, the company is officially registered as an MSB.
After approval, the business must continuously comply with reporting and audit requirements.
One of the most significant developments in Canadian regulation is the inclusion of cryptocurrency businesses under MSB rules.
Crypto companies must register if they:
This makes Canada one of the more structured jurisdictions for crypto regulation compared to many other countries.
However, crypto MSBs face additional scrutiny, including:
Despite strict regulations, obtaining MSB registration offers several advantages:
Companies can legally operate in Canada and serve Canadian customers.
Being registered with FINTRAC improves credibility with banks, partners, and investors.
Many financial institutions require MSB registration before opening business accounts.
Canadian MSB registration can support expansion into other regulated markets.
While beneficial, MSB compliance also presents challenges:
Businesses must invest in compliance infrastructure to avoid operational risks.
Failure to comply with MSB regulations can result in serious consequences, including:
FINTRAC actively monitors and enforces compliance, making adherence essential.
The MSB license in Canada is a critical requirement for any business involved in financial services, especially in the rapidly growing fintech and cryptocurrency sectors. While it is not a traditional license, MSB registration with FINTRAC ensures that companies operate within a transparent, secure, and regulated financial environment.
For businesses aiming to expand into Canada’s financial ecosystem, understanding MSB requirements is not optional—it is a fundamental step toward long-term success and regulatory compliance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 22, 2026 | NCFA Insight | Artificial Intelligence And Data, Risk Compliance And Regtech
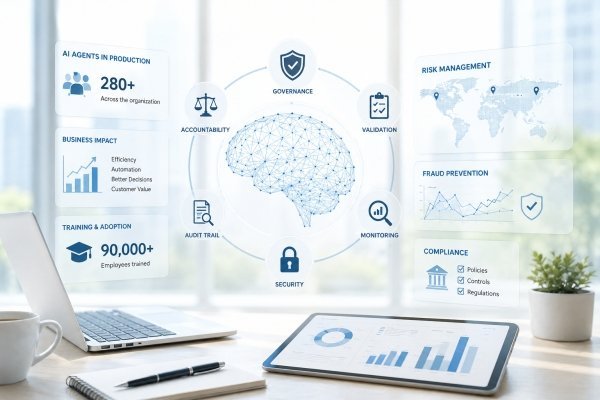
On June 22, 2026, Banco Santander reported that its AI first strategy generated €35 million in business value in Q1 2026, with expected value of more than €200 million by year end and a target of more than €1 billion between 2026 and 2028. That's a regulated bank putting numbers around AI execution.
The more interesting part is how Santander is trying to get there. The bank has extended AI access to all 185,000 employees, reported more than 280 AI automation agents in production, and previously described its ambition to become an AI native bank.
Ricardo Martín Manjón, Chief Data & AI Officer at Banco Santander, put the strategy plainly:
“For me, being AI-first means applying AI where it can have tangible impact.”
For Canada, the timing of this announcement is important because Santander recently received approval to operate as a federally regulated bank in Canada. So its AI operating model more than a global case study. It's a preview of how new banking competitors may bring AI, governance, fraud controls, and measurable operating discipline into regulated Canadian markets.
The first AI cycle rewarded access. Banks tested foundation models, launched copilots, built internal assistants, and looked for productivity wins. That phase is maturing fast. Models are easier to access. Cloud tools are easier to use. Building a convincing demo is no longer the hardest part.
The harder test is operating AI inside a regulated financial institution without losing control of risk, data, decisions, accountability, or customer trust.
That's where Santander’s publicly released data become strategically useful. Specifically, the update points to measurable business value, enterprise wide access, employee adoption, automation agents, and governance controls across ethical, legal, cybersecurity, and risk requirements. This is what AI moving from lab work into operating infrastructure looks like.
One underappreciated piece of the story is Santander AI Lab’s open source work. Its Gen Fraud Graph project is described as an Apache 2.0 open source initiative for generating synthetic fraud graphs and advancing fraud detection capabilities. The technical repository is also available on SantanderAI’s GitHub.
Fraud detection is one of the fastest ways to expose whether financial AI can be trusted. It touches financial crime, AML controls, identity checks, transaction monitoring, customer friction, model risk, and auditability. A model that performs well in a slide deck but cannot be tested, explained, monitored, or reviewed isn't ready for regulated scale.
Synthetic fraud graphs help solve a practical problem. Banks need realistic fraud scenarios to test detection systems, but they cannot freely share customer data or investigative information. Synthetic environments provide a safer way to benchmark performance, validate models, and document results.
The choice of fraud is revealing. Santander didn't launch its open source thread with a marketing assistant or a generic productivity tool. It highlighted infrastructure connected to risk.
Fraud teams need speed, but they also need evidence. Compliance teams need explainability. Risk teams need controls. Boards need accountability. Regulators need confidence that systems can be monitored and challenged.
For fintechs, this move by Santander is both a warning and an opportunity. AI claims won't be enough in fraud, AML, onboarding, underwriting, customer service, complaints, trading, surveillance, or compliance workflows. Buyers will increasingly ask for testing evidence, audit trails, human review, data controls, drift monitoring, and proof that the system works under pressure.
Recent work from IOSCO, OSFI, the European Union, the FCA, and other supervisory bodies points in the same direction. Institutions want measurable results. Customers expect accountability. The result is a growing focus on how AI systems are tested, monitored, explained, and challenged. That's why AI is creating a new compliance burden at the same time it creates productivity gains.
Santander reports more than 280 AI agents operating across the organization alongside enterprise wide training, governance controls, and measurable business outcomes. The same operating question now appears across AI agents entering financial workflows, customer onboarding, fraud detection, transaction monitoring, and compliance operations. The challenge is proving that it can operate safely inside regulated environments, and fraud amplifies the challenge immediately.
AI clones, biometric breaches, faster payments, and cyberattacks are weakening older trust signals, which raises the value of new verification controls for financial trust. Synthetic fraud graphs fit into that bigger problem because they give teams a safer way to test detection systems without exposing customer data or live investigations.
For banks, fintechs, payments firms, and infrastructure providers, that changes the economics of competition. Access to advanced models is becoming easier. Building a prototype is becoming easier. Producing evidence that a system can be trusted under real operating conditions remains difficult.
The first AI race was about capability. The next one is quickly focusing on proof.
If access to advanced AI becomes commonplace, will governance infrastructure and proof of control become more valuable than proprietary models in regulated financial services?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 13, 2026 | NCFA Fintech Whisperer | Capital Markets And Market Infrastructure, Lending Consumer Credit And BNPL, Regulation And Policy, Risk Compliance And Regtech, Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026).
European supervision is becoming more operational and technology focused. Banks, fintechs, crypto asset firms, infrastructure providers, and compliance teams should watch how DORA, MiCA, and EMIR oversight changes vendor governance, resilience testing, supervisory reporting, third party risk management, and regulatory accountability.
Supervision is becoming more data driven, technology enabled and cross border. Securities regulators are building stronger tools for market surveillance, fraud detection, investor protection and digital asset oversight, which raises the operating bar for firms whose compliance, reporting and risk controls still depend on slow manual processes.
Prediction markets are moving from niche trading communities toward mainstream financial distribution. Retail platforms, exchanges, regulators, investors, and market operators should watch how event contracts evolve as a new information, forecasting, hedging, and market intelligence layer. Distribution may become as important as market design in determining adoption. See: Innovation Opportunities In Regulated Event Contract Infrastructure.
Post trade risk reduction is becoming part of capital markets infrastructure. Dealers, clearing participants, platforms, and regulators should watch how compression, optimization, exposure reduction, and capital efficiency tools are treated as supervised infrastructure rather than back office utilities.
Bond transparency reform is creating demand for new market data infrastructure. Trading venues, asset managers, dealers, data providers, and regulators should watch how fixed income reporting, consolidated data, and transparency tools reshape price discovery and execution quality across European bond markets.
Agentic AI is moving into capital markets workflow. For dealers, asset managers, pension funds, and credit trading desks, the issue is no longer only faster market search. The next phase is how supervised AI tools support pricing, liquidity discovery, execution preparation, and workflow decisions inside regulated markets.
Natural language tools tied to pricing, trade data, and workflow systems could change how institutional traders search markets, compare bonds, assess liquidity, and act on data inside regulated trading environments.
Stablecoins are being embedded directly into payment and remittance infrastructure. Payment firms, PSPs, remittance operators, banks, liquidity providers, and compliance teams should watch how regulated stablecoin settlement, API connectivity, and cross border liquidity become part of the operating stack for high volume regional payment networks.
Search is becoming regulated digital infrastructure. Publishers, fintechs, platforms, marketplaces, advertisers, AI search providers, and compliance teams should watch how ranking rules, data portability, publisher protections, and user choice requirements change discovery, distribution, and competition across search and AI enabled information access.
Institutional digital asset infrastructure is entering bank charter channels. Banks, custodians, wealth platforms, crypto firms and regulators should watch how national trust bank approvals shape custody, staking, lending support, capital requirements and supervisory expectations for digital asset services.
MiCAR is shifting crypto firms from fragmented national registrations toward regulated infrastructure choices. VASPs, exchanges, brokers, fintechs, custodians, and compliance teams should watch how licensing pressure turns custody, wallet services, settlement, liquidity, and operating controls into market access requirements across Europe.
AI linked lending platforms continue to connect consumer credit origination with capital markets distribution. Pagaya’s latest transaction shows how underwriting models, loan supply, securitization channels, and institutional demand are combining into repeatable credit infrastructure.
Canadian bank capital policy is shifting from maximum conservation toward controlled lending capacity. Banks, lenders, fintech partners, investors, and policymakers should watch how lower buffer requirements affect credit availability, capital planning, risk appetite, and competitive conditions across the financial system.
Canada is moving privacy, AI, consumer data, and platform accountability into the same regulatory agenda. Financial institutions, fintechs, AI vendors, data brokers, and digital platforms should watch how consent, deletion rights, automated decision transparency, children’s data protections, and guidance for onboarding, data use, AI and partnerships affect product design and data governance.
The review could affect how fintechs, derivatives firms and market infrastructure providers engage with US regulated markets. Firms should watch for changes that reduce unnecessary compliance friction while maintaining market integrity, customer protection and risk oversight.
The useful evidence is the transmission channel, not a prediction that CBDC will launch. Digital money competition affects deposits, funding costs, liquidity treatment, lending capacity, and central bank balance sheet operations. Operators, founders, and investors should watch how CBDC, fintech deposits, stablecoins, and payment infrastructure reforms change competition for bank funding.
The week's strongest market and regulatory signals weren't new products. They were changes to the infrastructure underneath financial markets. Bank capital rules, prediction market access, stablecoin rails, and compute markets all point to the same outcome. Firms that control access, distribution, liquidity, and critical infrastructure may increasingly determine who can compete and who cannot.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: June 19, 2026
Status: Strong
Organizations: CIRO, FCA, DTCC, DTC, NYDFS, Prometheum Capital, BitGo, Anchorage Digital, Circle France, AMF, Citi, Cross River, Figure
Crypto custody regulation is changing from asset safekeeping into market infrastructure control. The answer is no longer only about who holds private keys. It is about who can support client asset segregation, stablecoin reserves, broker dealer workflows, tokenized securities, DeFi access, collateral controls, audits, and recoverability when something breaks.
Canada is already part of the pattern. CIRO’s custody guidance builds on the wider Canadian platform supervision path outlined in regulatory updates for crypto asset trading platforms. The global direction is similar. Crypto custody is becoming a gatekeeper for regulated market access.
The same pattern appears in tokenized markets. If real world assets, stablecoins, tokenized funds, and private market instruments are becoming infrastructure, then custody becomes part of the operating layer. That is why the evidence connects directly to tokenization as financial infrastructure, not only crypto storage.
Click each item to expand
CIRO issued guidance on custody expectations for Dealer Members operating crypto asset trading platforms. The framework is effective immediately and uses a tiered, risk based structure.
The FCA’s CP26/8 consultation proposed amendments to client asset and market rules so they work for cryptoasset activities and the wider UK crypto regime.
NYDFS proposed updates to align its stablecoin regime with the federal GENIUS Act framework while maintaining New York’s stablecoin standards.
Click each item to expand
DTCC said DTC’s tokenization service plans initial limited production trades in July 2026, with launch planned for October 2026.
Citi launched tokenized depositary receipts to connect private companies and investors.
Circle France received approval to provide custody and transfer services for USDC and EURC across the European Economic Area under MiCA.
Click each item to expand
Prometheum Capital launched Digital Brokerage Solutions for broker dealers and RIAs using traditional brokerage account workflows.
Anchorage Digital launched Stablecoin Solutions for Banks, combining minting, redemption, custody, fiat treasury management, and settlement.
Cross River committed up to $250M in asset purchases to support Figure’s crypto backed loans.
Click each item to expand
BitGo announced pricing of its IPO, with shares expected to trade on the New York Stock Exchange under the ticker BTGO.
Canadian crypto platform registration evidence shows that custody remains part of market access, not a separate technical service.
NCFA’s tokenization evidence shows that custody is becoming part of the same market infrastructure stack as settlement, collateral, cash movement, and ownership records.
Do you agree the evidence is strengthening?


Click Agree or Disagree. Your vote is recorded anonymously and aggregate totals tracked.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Businesses still repeat identity, ownership, onboarding and compliance checks across banks, PSPs, lenders, marketplaces and software platforms. The opportunity is to let verified business identity, KYB records, authority, ownership and trust credentials move securely across institutions with consent and controls.
Portable business identity sits between digital identity, KYB, beneficial ownership, data portability and compliance automation. Market estimates vary by scope, but the direction is consistent: regulated firms need more reliable business identity data, while businesses need less repetitive onboarding across platforms.
The strongest opening is portable KYB and business identity profiles that reduce repeated onboarding while preserving control, consent, verification quality and auditability. The buyer may be a bank, PSP, marketplace, lender, regtech provider or business platform that wants lower onboarding friction without weaker compliance.
Consumer driven banking rollout, CSA data portability testing, GLEIF vLEI adoption, beneficial ownership rules, KYB automation, open finance standards and evidence that SMEs or platforms will pay for reusable business identity tools.
Evidence points to three venture paths. Each one addresses a different constraint that prevents business identity and compliance data from moving safely across financial ecosystems.
Reusable business onboarding and ownership records
Businesses repeatedly submit incorporation documents, ownership records, director information, tax data, licenses and compliance evidence to every new financial provider. Portable KYB profiles could reduce this duplication while keeping institutions in control of risk decisions.
The venture opportunity is not to eliminate due diligence. It is to make verified business information easier to reuse, refresh, audit and share under clear permission rules. Potential buyers include banks, PSPs, lenders, marketplaces, wealth platforms and compliance service providers.
Regulated firms may decide that relying on third party KYB records creates more liability than efficiency unless assurance standards mature.
Will banks, PSPs or platforms rely on portable KYB outputs, or only use them to accelerate internal review?
Verified entity, authority and credential control
Business identity wallets would let companies hold and present verified entity information, authority credentials, licenses, beneficial ownership attestations and role based permissions. The vLEI model shows how legal entity identity can become cryptographically verifiable in digital interactions.
This path may be most valuable where businesses need to prove who they are, who can act for them and what authority has been granted across payments, procurement, lending, filings and platform onboarding.
Wallet adoption may remain fragmented if issuers, registries, platforms and regulators do not converge around interoperable standards.
Which credential creates enough value to drive wallet adoption: entity identity, authority to act, beneficial ownership, tax status or licensing?
Platform trust, compliance status and risk portability
Many businesses build trust repeatedly across marketplaces, lenders, PSPs, procurement networks and software ecosystems. A trust passport network would let selected trust attributes travel with the business, including verification status, permissions, payment history, platform standing and risk signals.
This path is broader than compliance. It may support B2B marketplaces, SME finance, embedded finance, cross border trade and agent commerce. It is earlier because governance and liability questions are harder than the technology.
Platforms may refuse to share trust data if they view it as proprietary, competitively sensitive or too risky to rely on elsewhere.
Which trust attributes are portable enough to matter and safe enough for another platform to rely on?
Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
