





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 19, 2026 | NCFA Feature | AI Finance Policy
On Jan 27 2026, the UK Financial Conduct Authority launched the Mills Review into the long term impact of AI on retail financial services to examine how AI could reshape consumers, firms, markets, and regulation through to 2030. NCFA flagged the review earlier in NCFA Weekly Fintech Intelligence Jan 24-30, 2026.
On Mar 4 2026, Innovate Finance submitted its response to the Mills Review, setting out where the UK fintech industry believes deployment will stall unless policy and infrastructure move faster. The paper cites Bank of England and FCA data showing 75% of firms now use AI, up from 58% in 2022. The issue is no longer whether AI adoption will happen. It is what still blocks firms from using AI inside live financial workflows at scale.
AI is clearly evolving from chatbot assistance to execution at scale. The submission describes AI agentic systems that can act on behalf of users. One example is an AI bot that handles everything from comparing mortgage deals to submitting the application and coordinating with conveyancers under user permission.
The value is no longer only in the model itself (ie. speed, quality, cost, expertise), but rather the full operational chain from customer permission to data access to execution to payment. That's why industry is focused on a stacked layer of tech solutions from Open Finance and Digital ID to payment access and rulebook friction to ensure AI can fully complete financial tasks.
The same logic applies to industry concerns over gatekeepers. As AI agents begin to initiate and route transactions, control moves to the layer that connects the agent to the payment method and the financial product. If that layer becomes concentrated, a small number of providers can influence access, routing, and competition.
The response uses real commercial examples and market data, highlighting that AI in finance is already underwriting, trading, core banking, and compliance.
The next phase isn't whether or not firms can build AI tools. It is whether regulation and infrastructure will allow them to use those tools in broader customer and transaction flows.
The stronger points made is that AI in finance won't scale on model quality alone. It will however scale on the stack around the model. That means smart data, Open Finance, Digital ID, fraud data sharing, wallet infrastructure, and payment access. Without those layers, AI stays stuck in narrow support roles. With them, it can move into lending, advice, payments, and automated execution.
That is why the response is more useful than another generic values and ethics based AI policy statement. It identifies where deployment slows, where control could become concentrated, and what has to move together if the UK wants AI to scale significantly inside financial services.
Canada is also building its next AI strategy. The federal government launched an AI Strategy Task Force in September 2025 as part of a 30 day national sprint, and later said it heard from more than 11,000 Canadians and 28 task force members. The Canadian process is broad. It is focused on national AI leadership, trust, safety, adoption, and public interest.
That broad approach is already raising execution questions. NCFA covered this earlier in its analysis of Canada’s AI strategy and capital flight risk, which argued that deployment, investment, and commercialization need clearer direction.
The UK industry response to the Mills Review is more targeted. It focuses on what is blocking AI deployment inside financial services today. Open Finance, Digital ID, payment access, wallets, third party model assurance, and rulebook friction sit at the center of that response.
Canada is still discussing the national direction of AI while UK fintech industry is already laying out what has to change for AI to work inside live financial workflows. The lesson for Canada is straightforward. AI policy cannot move on its own. Open Finance, Digital ID, wallet policy, payments modernization, and data access frameworks need to move with it or adoption in regulated finance will stay limited.
There is also a market structure lesson. If agent led payments grow, whoever controls the interface between the agent, the wallet, and the payment rail can control distribution. Policymakers who want competition and innovation to hold need to keep that layer open.
The industry response to the Mills Review is not just a call for clearer AI rules. It argues that the next barrier sits outside the model. Data access, identity, payments, and regulatory clarity now decide whether AI in finance stays at the support layer or moves into execution. The firms and jurisdictions that solve those bottlenecks will have the advantage.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mar 18, 2026 | NCFA Fintech Market Insight | Payments And Consumer Finance And Tax
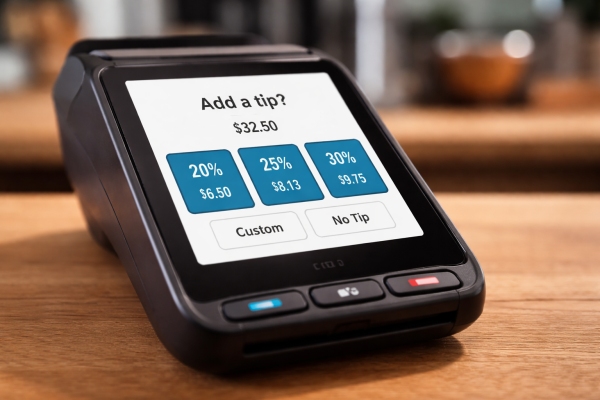
On Mar 17 2026, H&R Block Canada revealed tipping survey results putting new numbers behind a growing consumer reaction to tip prompts at checkout. Two thirds of Canadians or 67% say Canada should abolish tipping culture. Another 93% say they feel annoyed when a card machine prompts for a tip in places where tipping was not previously expected, and 89% say tipping is out of hand and is applied to goods and services they do not think warrant tipping.
This backlash isn't just frustration. It's now changing behaviour and pushing customers away.
The survey also connects tipping culture to tax and compliance.
H&R Block’s 2025 survey found 84% of Canadians know tips are taxable income, but 47% assume people are not declaring all tips. The evolution from paying/receiving cash tips to digital tips changes how income shows up for tax purposes, especially when tips flow through employers and platform operators.
Digital tipping changes the paper trail. When tips move through a card terminal or POS system and the business pays them out through payroll, the tip can show up like other income on a paycheque, with deductions such as tax, EI, or CPP applied before the employee receives it and then reflected on tax slips. That is different from cash tips left on a table, where the worker has to track and report them. Gig work is different again. Even when an app collects tips and passes them on, gig workers are often treated as self employed, so they still have to report the full amount themselves at tax time.
This is a payments design problem that's now hitting brand trust. The tip prompt is part of the checkout experience, and the checkout experience is increasingly built and configured through payment processors, point of sale providers, and embedded finance stacks. When consumers feel pressured, they blame the merchant, but they also blame the payment flow. The numbers show that tip prompts can create real revenue risk for merchants if 41% of customers are willing to avoid tip pushing businesses.
For fintechs selling point of sale and payment tools, this is an opening to compete on trust and customer experience. Firms that give merchants better controls, clearer disclosure, and safer defaults can reduce backlash while still supporting gratuities where they make sense.
Fintechs that serve gig platforms (or merchants) can help by making tip reporting clearer in worker dashboards and by separating tip flows in a way that matches how income is treated.
Merchants will tune tip prompts more carefully because customer resentment is measurable. Payment platforms will face more pressure to treat tip design as a trust issue, not a digital cash lever. Regulators and tax authorities will face more questions about consistency and clarity as tipping moves further into digital rails.
If 67% of Canadians want tipping abolished and 41% avoid tip pushing businesses, do payment platforms start competing on tip prompt design the same way they compete on fees and checkout conversion?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 13, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Open Banking Open Finance And Data Sharing, Payments And Market Infrastructure, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026).
Regulators are aligning competition rules and data protection in a way that directly affects how AI systems access, process, and govern data. For fintechs and financial institutions building on platform infrastructure, data strategy, consent design, and compliance architecture are becoming tightly coupled decisions.
Large platforms, AI firms, fintechs, and financial institutions that depend on platform distribution, data access, identity layers, or app infrastructure face a more active compliance environment. Platform terms, profiling practices, interoperability rules, and access conditions can change through ongoing regulatory review. Firms with high dependency on a small number of gatekeepers face increased operating risk, while firms that diversify distribution, strengthen direct customer relationships, and build adaptable data and compliance architectures will be better positioned.
The next edge will come from firms that can operationalize data standards, identity rails, and compliance workflows across jurisdictions rather than wait for policy intent alone to close the gap.
This deal says scale in cross border payments is moving toward platforms that already combine distribution, compliance support, and endpoint reach. For smaller wallet, remittance, and banking partners, the harder question is no longer whether they can connect. It is whether they still control enough of the customer relationship or economics once a larger stack sits in the middle.
This brings Ripple inside the licensed payments system in Australia. It can handle more of the payment flow itself instead of relying on partners. That includes onboarding, compliance, FX, and payout. For banks and fintechs, this means a digital asset firm can now compete more directly on cross border payments with full regulatory coverage, not just as a crypto overlay.
This impacts payment processors, merchant platforms, and consumer fintechs that want to own checkout and settlement. A payment aggregator license pulls merchant onboarding, refunds, and settlement into one accountable layer, so competitors and partners should expect tighter expectations on merchant screening and operational controls as volumes grow.
This impacts fixed income platforms, treasury and collateral systems, and anyone building workflows that touch Government of Canada collateral. Dealer funding and hedging capacity affects liquidity and trading costs.
This impacts capital markets fintechs that want distribution through regulated channels. When a top tier exchange brand commits to a tokenization partner, procurement and diligence tighten fast. Builders should prepare for deeper questions on governance, surveillance, custody controls, and how tokenized assets move without breaking compliance reporting and investor protections.
This raises the execution standard for digital onboarding, disclosures, promotions, and support flows. For fintechs, good UX is no longer enough on its own. Firms need evidence that customers understand what they are seeing and can act on it without avoidable confusion.
Ottawa is pushing affordability through multiple channels at once, including taxes, housing, and core banking fees. For banks, that puts more pressure on legacy fee revenue and raises the importance of better alerts, cash flow tools, and low cost account design. For fintechs, it strengthens the case for products that help users avoid failed payments, manage short term liquidity, and lower everyday banking friction.
Banks lose part of a high margin penalty fee and face more pressure to compete on better alerts, balance visibility, payment controls, and products that help customers avoid failed payments in the first place. Direct product and revenue implications across consumer banking.
This opens a formal rulemaking lane around one of the fastest growing grey areas in digital markets. It matters for exchanges, brokers, market makers, and fintech platforms. How far regulated market structure will let them scale before they run into tighter product boundaries.
This guidance impacts how Canadian DIY investment platforms can design tools and user experiences. Online brokers and fintech wealth platforms now have clearer room to provide decision support, portfolio models, and guided interfaces, but they must build stronger safeguards to ensure those tools do not cross the line into regulated investment advice (a condition of the OEO regulatory exemption).
Public payment rails can widen access, but they can also compress private platform economics and add pressure onto merchant pricing. For banks, fintechs, and payment providers, the real issue is not only whether public rails expand. It is how pricing design changes volume, margin, and who absorbs the cost.
A charter application signals a potential change in funding and balance sheet strategy for an AI lending platform and it can reshape partner economics for banks and credit unions that currently fund originations.
This is more than a weak quarter. It puts credit quality, funding resilience, and covenant headroom back at the center of the non prime lending story, which matters for alt lenders, securitization partners, credit investors, and fintechs selling underwriting, servicing, collections, and portfolio monitoring tools into the consumer lending stack.
This matters for brokers, carriers, and digital asset clients because premium payments are a treasury workflow. Once stablecoins clear premiums across real counterparties, buyers and carriers will ask harder questions about controls, reconciliation, and how funds move from premium collection to coverage without losing traceability.
This roadmap puts Europe closer to a tokenised market structure built around central bank money rather than private settlement workarounds. It matters for banks, FMIs, tokenisation platforms, and securities infrastructure teams because the market is now moving from exploratory work toward live design choices on standards, networks, and governance.
This opens a cleaner path for brokers and institutional desks that want crypto execution without rebuilding their stack around proprietary APIs. Once crypto routing uses the same FIX plumbing as other asset classes, firms will put more weight on consistent controls, audit trails, and operational readiness across both traditional and digital venues.
Payment networks are scaling distribution and wallet reach. Tokenized market structure is moving closer to institutional use. Canada’s NSF fee cap also cuts into a legacy bank revenue line and raises the value of tools that help customers avoid failed payments. The strongest fintechs and financial institutions are combining regulatory discipline, strong rails, and practical financial workflows that reduce friction for users.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 11, 2026 | NCFA Fintech Insight | Capital Markets Infrastructure
On March 11 2026, the European Central Bank released the Appia roadmap for Europe’s tokenised finance. The plan runs through 2028 and sets out how the Eurosystem will explore tokenized wholesale financial markets while keeping central bank money at the center of settlement. The ECB says Pontes, a near term interoperability layer, is expected to launch in the third quarter of 2026, while Appia will guide the longer term design of a more integrated tokenized financial ecosystem. While Europe is still studying the final model, the roadmap highlights that ECB is treating tokenization as a market infrastructure question.
The ECB is working in two stages. Pontes is the near term step. The Eurosystem’s DLT settlement page says Pontes is designed to connect distributed ledger platforms to existing Eurosystem settlement services so euro transactions on those platforms can settle in central bank money. The ECB has said Pontes is expected to launch in Q3 2026.
Appia is the longer term view. The ECB says it will explore how a broader tokenized financial ecosystem could develop over time, including questions around architecture, governance, standards, and integration. In other words, Pontes is addressing immediate settlement demand, while Appia looks at where wholesale tokenized finance may go next.
The roadmap focuses on wholesale financial markets, not everyday consumer payments. The money used in these systems would move between regulated financial institutions such as banks, central counterparties, and settlement providers.
This is an important distinction because retail CBDC proposals raise questions about public accounts, privacy, and how people use digital money day to day. The ECB roadmap is different. It is about how tokenized securities, deposits, and other financial assets could settle safely between institutions using tokenized central bank money.
It's a wholesale CBDC model that moves central bank money on distributed ledger infrastructure. The goal is to modernize market infrastructure, not replace cash or consumer bank accounts.
Tokenization allows financial instruments such as bonds, funds, deposits, and collateral to exist as programmable digital representations on distributed ledgers. That can reduce reconciliation steps and shorten settlement chains. But tokenized markets still need a settlement asset that participants trust.
The ECB is making clear that it wants central bank money to remain that anchor. That is a big difference from models that rely mainly on private stablecoins or commercial bank liabilities. Central bank money carries the lowest credit risk in the system because it is a direct claim on the central bank itself.
The ECB’s Appia overview says the initiative is the cornerstone of the Eurosystem strategy to provide central bank money within tokenized wholesale financial markets. It also says tokenized central bank money under Appia would go beyond the interoperability model delivered by Pontes and would be more integrated into a wider new financial ecosystem.
Europe is entering a wider global race around tokenized market infrastructure. The BIS Project Agorá is exploring how tokenized commercial bank money and tokenized wholesale central bank money could work together on a common digital payments platform. The BIS says that work is aimed at improving cross border payments while keeping central banks at the core of final settlement.
Hong Kong is also moving quickly. The HKMA’s November 2025 Project Ensemble update says its pilot environment will be progressively enhanced through 2026 to support settlement in tokenized central bank money on a 24/7 basis (see Standard Chartered CEO Backs Tokenized Finance in Hong Kong). The HKMA has also used tokenized bond issuance, including HK$800M in tokenised green bonds in 2023 and about HK$6B in 2024.
That means the ECB is joining a growing group of major institutions that now see tokenized settlement as a serious part of future market design.
As NCFA recently noted in its analysis of how tokenized infrastructure is changing market operations, Canada has already taken early steps through stablecoin policy work, open banking progress without a confirmed implementation date, and payment modernization efforts. But the foundations for tokenized markets are still incomplete. Canada’s Real Time Rail is not yet live and is expected after 2026. Canada also still needs clearer legal recognition of digital ledger registers for securities, stronger real time settlement across institutions, and digital identity standards that work across ledgers while supporting KYC and AML requirements.
Canada has strong institutions and credible capital markets, but it doesn't yet appear to have a public multi year wholesale tokenized settlement roadmap comparable to Appia. If other jurisdictions define the standards and operating models first, Canadian firms may end up adapting to systems built eleswhere.
Pontes is expected in 2026. Appia runs through 2028. Those dates don't automatically mean Europe has committed to one final settlement model today. However they do mean that a major central bank is now putting dates, structure, and policy intent around tokenized wholesale finance market infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Regulation And Policy, Lending Consumer Credit And BNPL, Sustainable Finance And ESG
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026).
This is for AI first fintechs, SaaS platforms, and builders selling usage heavy products because AI cost recovery is moving out of finance spreadsheets and into the billing stack itself. This means markup, model pricing, and token usage can all be baked directly into a single workflow.
This affects crypto custody, brokerage, and compliance tooling teams, plus firms that run secondary market controls, because it pushes more of the crypto perimeter into client asset rule design while tightening where firms must look for core market mechanics requirements.
This changes the operating timetable for lenders, brokers, and claims handling firms, and it pulls more pressure onto complaint intake, identity checks, fraud controls, and customer communications. Fintechs offering claims workflow solutions, onboarding checks, and redress automation now need to map product readiness to the late March rules and the 3 to 5 month build window.
This opens an official lane that matters for remittance firms, merchant payments providers, instant payments infrastructure teams, and institutions building Canada India payment flows. Once payment system operators are invited into the file, the discussion moves closer to real operating design, not just diplomacy.
This opens a new regulated advice lane between generic guidance and individual advice. It affects banks, pension providers, wealth platforms, and fintechs building support flows, because firms now have a near term path to turn customer guidance into a permissioned product with real conduct and authorisation consequences.
This is important for issuers, dealers, custodians, and market infrastructure teams because a central bank backed trial now shows how tokenized bonds and central bank settlement money can run through an on chain workflow, which raises expectations on governance, auditability, and integration before this model can scale beyond pilots.
A major exchange operator is tying its regulated futures roadmap to crypto spot reference prices while pushing tokenized equities distribution through a large crypto customer base.
This is for banks, payment infrastructure firms, tokenization platforms, and securities settlement providers. The BOJ is linking blockchain, tokenized central bank money, and core settlement design to active pilots, sandbox work, and future upgrades to BOJ NET, which raises the bar for how seriously the market should treat settlement infrastructure moving on chain.
This raises the enforcement baseline for broker dealers and their vendors. If you create or sell onboarding, surveillance, AML, or case management tooling, expect more pressure to prove risk based controls, faster SAR decisioning, and audit ready evidence because regulators are treating gaps in thinly traded securities monitoring as a serious control failure.
This is a positive announcement for fintech vendors that sell to government, defence, banks, and critical infrastructure. AI evaluation, cybercrime response, and resilience checks start to converge across buyers.
As Canada and Australia open the door to more pension investment, investors will want simple, auditable reporting and quick due diligence, especially for payments, AI, and critical supply chain projects.
This delay ties up cash for importers and their banks. When refunds take weeks to process, treasury teams need tighter visibility into duty exposure, eligibility tracking, and cash forecasting, and that opens room for fintech tools that automate reconciliation and working capital decisions created by policy whiplash.
This could impact how payments teams operate. If merchants can query verified payments events in natural language and automate workflows on top of unified data, AI payments will run the operating layer for routing, fraud, disputes, and cost control, which raises expectations on data quality, lineage, and accountability across the payments stack.
The Fed is opening a controlled access point for a crypto linked institution inside the U.S. payments system. That sets a live precedent for how non bank and digital asset firms may be handled under account access rules, even where service scope stays tightly constrained.
This for issuers, acquirers, sponsor banks, card fintechs, and treasury teams because stablecoins are moving closer to core network settlement, not just crypto side rails. Once a global card network starts wiring a bank issued stablecoin into settlement flow, teams need a clearer view on treasury design, reconciliation, network rules, and what faster money movement looks like in practice.
This pushes stablecoins deeper into everyday card economics, not just niche crypto wallets. It matters for issuers, program managers, fintech developers, and infrastructure teams because card issuance, settlement, and reconciliation are starting to move into the same onchain operating stack at global scale.
Singapore is placing climate transition planning inside supervised financial risk management rather than limiting it to public reporting. The approach gives Canadian regulators and institutions a comparator for connecting climate data, portfolio decisions, customer engagement and governance while avoiding blunt exclusions that could restrict financing without reducing underlying risk.
Core financial infrastructure continues to move closer to programmable systems while regulators tighten the rules around how firms operate and protect customers. Stablecoins are entering card settlement, tokenized bonds are moving through central bank backed pilots, and AI usage is starting to show up directly inside billing and payments operations. At the same time, regulators are opening new product lanes and expanding oversight of crypto custody, advice models, and consumer finance practices. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 5, 2026 | NCFA Market Insight | AI And The Future Of Work

Image: Labour market impacts of AI: New measure, early evidence (Anthropic Mar 2026)
On March 5 2026, new Anthropic artificial intelligence labour market impact research | download 17 page PDF offers a more grounded way to think about AI and jobs. Most AI labour studies ask what large language models could do in theory. This one asks what workers actually do with AI now. That sounds like a small change, but it matters. Financial institutions, fintechs, and policymakers need to know where real workflow change starts, not just where capability headlines point.
The paper introduces a new measure called observed exposure. It combines occupational task data, Claude usage data, and earlier research on which tasks language models can theoretically handle. The approach tries to separate technical possibility from real use. That makes this study potentially more useful than other broad forecasts about AI replacing jobs. To be clear, at this point the research doesn't claim mass displacement has arrived. It looks instead for early pressure points that may show up before unemployment spikes.
This report matters because it focuses on real work patterns. The authors use the US O*NET task database, Anthropic Economic Index usage data, and earlier task level exposure estimates to build their measure. They also give more weight to automated and work related uses than to lighter forms of assistance. That helps the study track where AI starts to move from drafting help into actual production work.
That said, the research has real limits, and those limits matter. The usage data comes from Claude, not from the full AI economy. A bank using Microsoft, Google, OpenAI, or internal tools may show a different pattern. The measure also tracks task exposure, not direct job loss. And the authors make clear that adoption still lags capability because of legal controls, software requirements, human review, and workflow friction. That caution strengthens the paper rather than weakening it. It keeps the analysis honest.
The most striking findings is the size of the gap between capability and real usage. In STEM (ie. computer and math) occupations, earlier work suggests language models could theoretically touch 94% of tasks. Anthropic’s observed measure puts current Claude coverage in that category at just 33%. In other words, the technology frontier sits much further ahead than the adoption frontier.
That gap matters for fintech and finance because it points to where the real bottleneck sits. The next productivity jump might not come from a bigger, better, faster or smarter model alone. It might come from firms that redesign workflows, tighten controls, connect tools to internal systems, and build trust in output quality. Which operators can close the adoption gap faster than peers.
The report finds that computer programmers rank as the most exposed occupation, with 74.5% coverage. Customer service representatives follow at 70.1%, and data entry keyers come next at 67.1%. Digital, repeatable, text heavy work moves first.
What stands out for NCFA readers is that this isn't just software engineers. Financial analysts are also among the most exposed occupations in the paper’s wider discussion. That should get the attention of banks, insurers, wealth platforms, lenders, and compliance teams. A lot of value in finance comes from summarizing information, checking documents, explaining options, processing forms, and moving data from one system to another. Those are exactly the kinds of tasks that AI enters early.
Workers in the most exposed occupations earn 47% more on average than workers in the unexposed group. People with graduate degrees make up 17.4% of the most exposed group, compared with 4.5% of the unexposed group.
Early pressure is showing up in better paid, more educated, office based roles. In practice, that means AI may alter the work of analysts, developers, researchers, service teams, and operations professionals before it touches many frontline physical jobs. For financial institutions, this points to a management challenge as much as a technology one. Firms need to rethink role design, supervision, training, and quality control inside knowledge work functions.
The research does not find a growing rise in unemployment for workers in the most exposed occupations since late 2022. That is an important result because it pushes back on louder claims that AI already causes wide labour market damage.
But the report does find an early warning sign. For workers aged 22 to 25, job finding rates into highly exposed occupations fall by about 14% compared with 2022 levels. The authors stress that this result is only barely statistically significant and open to other interpretations. So something to watch and track.
This is how labour market change often starts. Not with mass layoffs. Not with an obvious cliff. It starts when firms stop hiring as many junior people because AI now handles part of the routine work those hires once learned on. That's important for banking, fintech, consulting, and other white collar sectors that depend on apprenticeship style career ladders. If entry points narrow, firms may save money in the short run while weakening their future talent pipeline.
Firms should watch three things closely to better anticipate where the real gap may open between leaders and laggards:
For fintech builders, the market needs tools that help institutions safely plug AI into live work. Audit trails, review controls, workflow routing, structured data extraction, policy checking, and role based permissions. Companies that solve those problems help close the distance between AI capability and actual business use and adoption.
Anthropic’s research is quite useful because it shows where real adoption starts, where the biggest gaps remain, and where the cracks may start to appear and proliferate.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 5, 2026 | NCFA Advocacy | Data Governance
Sent by email:
Dear Minister
Power of Data
We (the undersigned – data driven tech and policy experts) very much support the letter of 4 Feb 2026 to you from CCPA – https://www.policyalternatives.ca/news-research/open-letter-to-the-honourable-melanie-joly-minister-responsible-for-statistics-canada/.
We add to that letter the following points:
1. At a time when we need more data, not less, to support evidence-based decision making and community engagement in Canada, the staffing and other cuts already started at StatsCan are misguided. Even if the cuts will “have a ‘low’ or ‘limited’ impact on existing service levels” (a position which is contestable), we echo concerns about the long-term impact on data collection, statistical reliability, and public trust in government institutions.
We ask StatsCan to outline how core programs, release schedules, and quality standards will be maintained. How do we reconcile the cuts with the Digital Research Infrastructure Strategy - https://ised-isde.canada.ca/site/ised/en/programs-and-initiatives/digital-research-infrastructure? Clarifying how “modernization” will offset reductions would strengthen confidence in the transition.
2. Our need for data is magnified by the attacks on data collection in the US, keeping in mind that in the past we have relied on much of that data. The attacks show how quickly statistical capacity can erode and how difficult it is to rebuild.
3. StatsCan plays an important coordinating role in maintaining statistical standards. Although StatsCan is not necessarily the body that should be collecting all the data we need in Canada, we suggest that StatsCan should be the body to oversee an inventory of what Canada does collect (or should be collecting) and to consult on and publish best practices for collection and governance. However, the cuts will clearly constrain an expanded governance role for StatsCan for the foreseeable future.
To provide some examples of data that is sorely needed:
(a) commercialization from Canadian universities, along the lines of the UKRI spinout registry (https://www.ukri.org/news/world-leading-register-of-uk-university-spin-outs-published); *
(b) data on emerging tech commercialization for defence (https://www.nato-pa.int/document/2024-dual-use-technologies-report-baldwin-051-esc and https://www.cigionline.org/publications/intellectual-property-is-economic-and-national-security/); and
(c) data on the outcomes of research spending.
4. Under the World Bank’s Statistical Performance Indicators, Canada’s statistical system ranks highly – https://www.worldbank.org/en/programs/statistical-performance-indicators. While we do not doubt that reform of StatsCan is needed in an increasingly tech-driven economy, wholesale cuts are not the way to do it. Expertise will be lost, collaborative connections across organizations will be lost, mistakes will be made, there will be loss of morale, and direct costs of “redundancy” will be high, when strong statistical capacity is even more essential to support productivity and competitiveness.
5. The timing could not be worse. We are facing enormous challenges, and Canada’s need for reliable data is increasing as the economy evolves. To provide but one example, Canada is increasing defence spending under a new defence industrial strategy and engaging in “nation-building” projects. As noted in the Institute for Research in Public Policy report (https://irpp.org/research-studies/how-industrial-policy-can-strengthen-canada/), these projects must be “accompanied by rigorous evaluation and good governance practices” which can only be effective when Canadian institutions, including StatsCan, collect high quality data and use it to connect action to outcomes.
6. Rebuild or shred? (‘The Doom Loop’ and the future of the global order – https://www.youtube.com/watch?v=6ULm87aidxM). This is a moment for careful planning to ensure institutional capacity is preserved and to plan for rebuilding, not shredding.
Respectfully
Signed
Kyle Briggs - https://www.linkedin.com/in/kyle-briggs/
David Durand – https://www.linkedin.com/in/daviddurandavocat/
Craig Asano, CEO National Crowdfunding & Fintech Assn of Canada - https://ncfacanada.org/
Robin Ford, Robin Ford Consulting - https://www.linkedin.com/in/robinericaford/
Peter Morand, Past President of the Natural Sciences and Engineering Research Council of Canada (NSERC)
Patrick Leblond, CN-Paul M. Tellier Chair on Business and Public Policy, University of Ottawa
José Carlos Marques, Associate Professor, Telfer School of Management, University of Ottawa
* While Canada invests billions in research, we translate very little of the value created into long-term economic and social benefit for Canadians. StatsCan recently attempted to survey Canadian universities on their commercialization activities but was unsuccessful. StatsCan removed the report from the website following complaints that the data was incomplete.
In contrast, the UK recently created a “spin-out register” of all startups commercializing IP created during publicly funded research (https://www.ukri.org/blog/university-spin-out-register-a-step-change-in-insights-for-all/). This register is already providing valuable insights that are helping UK policy makers make better funding decisions.
Canada’s world-class research institutions could contribute far more to Canada’s economy and economic security (https://www.cigionline.org/publications/intellectual-property-is-economic-and-national-security/), but without high-quality data, we struggle to identify and fix the problems.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
