




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Tokenization | July 21, 2025
Image: Freepik
On July 16, 2025, the U.S. Securities and Exchange Commission (SEC) held a private meeting with Ethereum-linked groups including ERC-3643 Association and Chainlink Labs to explore standards for compliant tokenized securities. At the same time, SEC Chair Paul Atkins confirmed that the agency is reviewing an innovation exemption that could allow programmable compliance frameworks to operate with targeted regulatory relief. It's a new development that confirms growing regulatory support for tokenized finance, further raising the bar for Canadian policymakers to respond.
In a major development during Crypto Week, the SEC held a private session with Ethereum-aligned groups, such as the ERC‑3643 Association, Chainlink Labs, the Enterprise Ethereum Alliance, Etherealize, and LF Decentralized Trust to explore the use of public blockchain infrastructure for regulated securities.
The meeting focused on how blockchain systems can follow existing rules for verifying identities, tracking ownership, and controlling who can buy or sell tokenized securities. The groups shared technical solutions that help meet these requirements while still using decentralized public blockchains.
Dennis O’Connell, president of the ERC‑3643 Association said the SEC showed a “noticeable shift in tone” and openness to openly source industry standards.
Two frameworks were at the center of the meeting:
Chainlink Labs in a statement:
“Only Chainlink provides the compliance, privacy, cross-chain, and data infrastructure needed to scale digital asset adoption in a single platform.”
In partnership with the Blockchain Association, Chainlink recently launched Tokenized in America, a national ranking of blockchain leadership across all 50 U.S. states.
The SEC meeting coincided with Crypto Week where rapid legislative developments were taking place in Washington. The GENIUS Act was signed into law, establishing a federal framework for stablecoin regulation, and recognizing the role of tokenized payment infrastructure. It was passed alongside the CLARITY Act, which defines treatment for digital assets, and the Anti-CBDC Surveillance State Act.
SEC Chair Paul Atkins spoke publicly about the Commission’s interest in creating an “innovation exemption” that would allow compliant tokenized securities to be piloted without full adherence to legacy rules, saying:
“If it can be tokenized, it will be tokenized.”
Sergey Nazarov, Chainlink co-founder:
Excited to see our industry reaching new heights and getting global adoption from governments because of the fundamental value that our technology provides.
The GENIUS Act is a huge step forward for stablecoins, forming the basis of on-chain payments for retail users in both… https://t.co/QlgtUgOHlu
— Sergey Nazarov (@SergeyNazarov) July 18, 2025
Canada is already evaluating stablecoins under its existing regulatory framework. The CSA classifies fiat-backed coins like USDC as “Value‑Referenced Crypto Assets” and recently allowed more time for issuers to comply. At the same time, OSFI, Department of Finance and the Bank of Canada are developing new federal rules to license stablecoin issuers to include reserve requirements, redemption, audits, and consumer protection.
However, Canada currently lacks equivalent legal tools for programmable compliance mechanisms like ERC‑3643 or Chainlink ACE. If the SEC approves a standards-based tokenization model, Canadian fintechs will face increasing cross-border friction unless policymakers adapt quickly. NCFA previously highlighted this policy gap in its advocacy post, such as Coinbase Pushes for Tokenized Equities Approval commentary. Canadian regulators cannot fall further behind.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Stablecoins | July 18, 2025
Image: Freepik/gstudioimagen
The dominoes are definitely starting to fall. Citigroup and Bank of America have confirmed they are developing or preparing to launch their own stablecoins. In back-to-back Q2 earnings calls this week, executives from both banks outlined their intentions to support stablecoin issuance for use cases like digital payments and tokenized deposits.
As reported by Reuters, Citigroup CEO Jane Fraser said on July 15 that the bank is “looking at the issuance of a Citi stablecoin” and that stablecoins would fit within the bank’s current initiatives in tokenized deposits, custody, and digital cash on/off-ramp services.
Then just a day later, Bank of America CEO Brian Moynihan confirmed that Bank of America is actively preparing to issue a stablecoin of its own. He told analysts the bank “expects to launch” a stablecoin and is in conversations with regulators about what a compliant U.S. dollar-backed version would require. Moynihan also pointed to the advancement of the GENIUS Act in Congress as a key milestone for legal clarity.
Note, JPMorgan Chase already has functional stablecoin infrastructure. JPM Coin, a wholesale payments vehicle used by institutional clients, currently moves over $1 billion in transactions daily. The bank is now expanding into tokenized deposit products for digital settlement use.
Tokenized deposits are regular bank deposits that have been turned into digital tokens. They still belong to the customer and are backed by the bank, but because they run on blockchain technology, they can move money faster and incorporate programmable rules.
Worth noting that while Morgan Stanley has not announced its own stablecoin it confirmed during its latest earnings call that it is “actively discussing” potential use cases. CFO Sharon Yeshaya said the firm is monitoring the regulatory landscape and evaluating client needs.
In a Reuters article May 23, 2025, mentioned that JPMorgan Chase, Bank of America, Citigroup, Wells Fargo, and other large commercial banks (including U.S. Bank via consortium channels) are “exploring whether to team up to issue a joint stablecoin,”, but there have been no commitments or formal statements issued yet.
Traditional banks are positioning themselves to be regulated providers of digital dollars that can be used in fast, transparent, and low-cost transactions across modern financial systems.
Stablecoins issued by large banks could compete or potentially replace legacy payment systems for cross-border transfers, securities settlement, reserve management, and cash liquidity optimization. Eventually they may support consumer payments, although bank executives have stressed that the focus is on B2B use cases first.
Bank of England Governor Andrew Bailey recently warned that privately issued stablecoins could destabilize global financial systems if left unregulated, reinforcing the urgency for banks to operate within robust legal and supervisory frameworks.
Traditional finance (TradFi) is gearing up to compete directly with crypto native infrastructure in the issuance and management of digital cash.
The rapid entry of big banks like Citi and Bank of America into stablecoins confirm what fintech leaders have predicted for years. Programmable money will enter the banking mainstream, depending on regulatory approval and market demand.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | July 10, 2025

Image: Freepik
On July 9, 2025, U.S. Securities and Exchange Commissioner Hester Peirce (aka Crypto Mom) issued a clear statement about tokenized securities: "Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral" but they are still subject to existing securities laws.
Her comments are directed at companies using blockchain technology to issue or trade digital versions of financial instruments like stocks or bonds. Major U.S. firms such as Franklin Templeton, BlackRock, and Robinhood are already exploring tokenized fund structures and products.
Hester Perice, SEC Commissioner:
“Calling a token representing a security by a different name or moving it to a blockchain does not change its fundamental nature,"
“Tokenizing securities does not render them unrecognizable to our existing rule set. If you issue or trade a tokenized version of a stock or bond, you still must comply with the relevant rules.”
Her statement confirms that registration, disclosure, custody, and investor protection rules apply whether a security is paper-based or tokenized. As more and more firms turn to blockchain to modernize capital markets, the SEC is reminding them that the legal definitions of securities have not changed.
She highlights two categories of tokenized securities and in both cases full compliance is required: (1) those issued directly by a company and (2) those created by a third party based on an existing security.
She also cautioned that third-party tokenization can raise new risks, especially if the offering is misleading or undermines investor protections.
“A third party seeking to tokenize someone else’s security must ensure that such efforts are not misleading, do not violate the securities laws, and do not compromise investor protections.”
Blockchain infrastructure can improve how markets operate. Tokenization allows for faster settlement, greater transparency, and lower administrative costs. It also enables fractional ownership, which can make investing more accessible. Restrictions can be built in and help enforce compliance automatically, some platforms may also offer 24/7 continuous trading access.
In Peirce’s view, innovation and regulation don't have to be in conflict:
“We should consider exemptions, no-action relief, or other tailored regulatory accommodations where the benefits of blockchain technology can be realized without undermining investor protections.”
The SEC’s position does not change Canadian law, but it provides useful direction for NCFA members and fintechs active in U.S. markets. In Canada, tokenized offerings must comply with securities rules. If a financial product is a security under Canadian law then it's subject to regulation.
Canadian fintechs exploring tokenization should expect scrutiny on custody, disclosures, and investor onboarding. Issuers must also ensure that the technology used does not obscure risk or circumvent investor rights. Regulatory engagement is key.
Peirce's statement shows that regulators are open to innovation but only if it maintains transparency and investor safeguards.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Banking | June 25, 2025
The National Crowdfunding & Fintech Association of Canada (NCFA) is deeply saddened by the sudden passing of Andrew Moor, President and CEO of Equitable Bank, (EQB) over the weekend of June 21–22, 2025 per the Financial post. Moor was a bold and thoughtful leader who believed in making Canada’s financial system more innovative, digital, and inclusive.
As CEO since 2009, Moor led Equitable Bank’s transformation into a technology-forward institution known for its direct-to-consumer offerings and fintech partnerships. EQ Bank, the digital arm of Equitable, became one of Canada’s most trusted alternatives to traditional banking under his leadership. His forward-looking vision earned admiration across the financial sector, including from those of us at NCFA.
Moor supported open banking frameworks, digital infrastructure reform, and meaningful collaborations between regulated banks and emerging fintechs. He served on the board of the Canadian Bankers Association and consistently advocated for innovation that benefits Canadian consumers.
His leadership helped create new paths for collaboration between incumbents and innovators, something that NCFA has long supported.
Andrew Moor’s contributions advanced financial innovation in Canada. His sudden passing is a loss to all who care about the future of finance, technology, and inclusion. NCFA extends heartfelt condolences to his family, colleagues, and the entire team at EQB.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | June 18, 2025
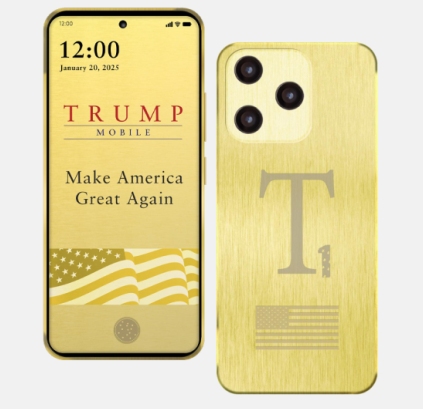
Image courtesy of Trump Mobile website
On June 18, 2025, Fortune reported that Trump Mobile is entering the U.S. wireless market with a $47.45 per month prepaid plan and a smartphone built by Chinese device maker Unihertz. Beyond the political optics, the announcement is interesting from a fintech perspective since Trump Mobile plans to use a telecom backbone to bundle lifestyle services in a way that mirrors embedded finance strategies seen in a variety of global fintech ecosystems.
The T1 smartphone is priced at $499 with a $100 down payment, and is scheduled to ship in late summer 2025. Trump Mobile is powered by Patriot Mobile, an MVNO that leases infrastructure from existing carriers. The business model relies on branding and licensing rather than owning physical networks. This setup closely resembles the way fintechs white label financial infrastructure through APIs and software platforms.
Eric Trump, EVP Trump Organization on Trump Media:
“I'm incredibly excited to step into this new digital space, hard-working Americans deserve a wireless service that's affordable, reflects their values, and delivers reliable quality they can count on. We're especially proud to offer free long-distance calling to our military members and their families — because those serving overseas should always be able to stay connected to the people they love back home. ”
The flagship product is the “47 Plan” offered at $47.45 per month. According to Trump Mobile’s website, it includes unlimited talk, text, and data, plus international calling. The bundled services also include 24/7 telehealth access and roadside assistance, which are traditionally sold separately or through insurance providers. Packaging them into a single mobile bill is a similar approach of fintech super apps.
The T1 phone has midrange specs: a 6.8-inch AMOLED 120 Hz screen, 12 GB RAM, 256 GB storage, a 50 MP triple camera setup, Android 15, a 5,000 mAh battery with 20 W fast charging, USB-C, a headphone jack, and biometric unlocking. The phone is manufactured by Unihertz in China, despite political framing that implied U.S. manufacturing. It unveils global hardware supplier realities that fintechs face when bringing physical devices to market.
According to The Wall Street Journal, the Trump family licenses its name to Patriot Mobile, which operates the network. This approach is similar to how fintech startups offer debit cards, wallets, and investment tools without becoming licensed financial institutions. The infrastructure is external, but the customer relationship is owned by the brand.
There is also a digital asset component. Reuters reported that Trump Media is applying for a cryptocurrency ETF made up of 75% Bitcoin and 25% Ethereum. Even though the potential crypto ETF isn't directly tied to the phone plan just yet, it highlights the Trump brand's ambition to combine lifestyle, media, and financial products.
Ironic as you get that earlier in 2025, the Trump administration slapped a raft of reciprocal tariffs, including a baseline 20% tariff on Chinese-made consumer electronics. According to Al Jazeera, the administration later exempted certain chips and phones but it's unknown which specific products currently qualify. If the T1 is subject to tariffs, the cost could be absorbed by Unihertz, passed to Patriot Mobile, or used to justify higher retail pricing.
Trump Mobile offers a live case study in how embedded services can be sold through telecom. For Canadian fintechs, it opens a conversation about how telcos and startups might partner to deliver subscription-based insurance, health care, or financial tools to underserved communities. Packaging multiple services into a mobile plan can improve customer stickiness, adding to predictable revenue, as also seen in bundled offerings by Koho, Neo, and other Canadian fintechs.
There should be policy concerns however, with potential conflicts of interest involving Trump's family ties to regulatory agencies. Also combining telco infrastructure with consumer finance triggers questions around cross-sector regulation, as regulators will need to consider the risks of a converging telco-fintech model as it grows.
For NCFA members, this launch offers insight into how bundled, cross-platform models can scale quickly with the right partnerships. As Canada expands open banking and explores new models of service delivery in underserved markets, this example shows how telecom-fintech convergence could work, assuming regulators allow it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | June 13, 2025
Image: Freepik/marymarkevich
Canadian regulators joined a coordinated global crackdown last week targeting unlawful finfluencers, or social media personalities promoting investments without registration or oversight. While enforcement activity is increasingly in focus, global experts and finfluencer advocates are warning that overly restrictive approaches will harm innovation, reduce access to financial education, and weaken digital financial literacy efforts.
As part of the Global Week of Action Against Unlawful Finfluencers, the Ontario Securities Commission (OSC) collaborated with regulators from the UK, Australia, the United Arab Emirates, Italy, and Hong Kong to investigate unlawful influencer activity.
The OSC reviewed 87 finfluencers and 9 issuers that used influencer promotions, and found some were offering unregistered investment advice or sharing misleading content, especially in the crypto sector. In-person warnings, gathering of evidence, and educational outreach were used to prevent retail investors being harmed.
Bonnie Lysyk, Executive Vice President of Enforcement at the OSC:
“International relationships are vital in countering this growing issue. The OSC’s recent research highlights the substantial influence social media personalities have on investor behaviour.”
In May 2025, the International Organization of Securities Commissions - IOSCO published its final report on finfluencers, to address online retail investor safety. Both the OSC and IOSCO's research on the impact of finfluencers were aligned, highlighting risks such as gamification and how social media and trading platforms can blur the line between general information and regulated investment advice.
IOSCO doesn't advocate for bans but rather outlines a series of good practices for regulators, platforms, market intermediaries, and finfluencers:
Jean-Paul Servais, Chair of IOSCO and FSMA Belgium:
“These reports set out globally aligned expectations for ethical conduct and effective oversight... ensuring that technology enhances trust, rather than undermining it,”
Not all creators are breaking the rules. According to the CFA Institute’s 2024 finfluencers appeal report, many finfluencers are filling educational gaps and helping demystify investing and financial planning for younger and underserved audiences. They create digestible and accessible content, often without commercial promotion or investment recommendations. Some are careful to include disclaimers and avoid offering specific advice.
A Wealth Professional Canada article cited Tangerine survey that discovered 60% of Canadians who follow finfluencers said they had benefited from their content. At the same time, those who acted on influencer tips were found to be 12 times more likely to experience scams.
Advocates argue that regulation should distinguish between financial education and commercial promotion. They are calling for clarity on how to remain compliant, not for the removal of content that informs and empowers.
“Most of us want to educate and uplift. But we need the rules to be clear and fair, not just fear-based.”
While Canada takes a proactive, data driven approach to enforcement of finfluencers while increasing public awareness for finfluencer risks, how do we shape up to our peer countries?
In Australia, the Australian Securities and Investments Commission - ASIC released guidance for social media influencers through INFO 269. ASIC warns that creators discussing financial products may be in breach of the law if they are unlicensed and don't follow compliance standards. The guidance supports financial literacy content as long as it avoids over promotion and includes proper disclosures.
In the United Kingdom, the Financial Conduct Authority (FCA) has focused on financial promotions. The FCA targets firms that pay finfluencers to promote investments without regulatory approval and has updated the financial promotions regime to apply to social media content.
Italy’s CONSOB and other European and Middle Eastern regulators also participated in the coordinated enforcement week. These jurisdictions are enhancing joint oversight of social media investment promotions, especially in the context of crypto and speculative assets.
In the United States, regulators such as the SEC and FINRA have pursued enforcement through existing anti-fraud provisions. While there is no finfluencer-specific guidance, recent actions have targeted offside celebrity crypto endorsements and undisclosed paid promotions.
Importantly, none of the major jurisdictions have called for bans, so global consensus is aligning with regulators to build frameworks that promote compliance, transparency, and public awareness instead.
Finfluencers are becoming as influential as traditional advisors, even more so for digitally native and younger investors. So oversight is warranted but the focus should be on compliance that doesn't undermine financial literacy and inclusion. Regulatory consensus shows that with clear rules, good practices, and global cooperation that clear rules and strategic oversight can protect investors while empowering open access to useful financial content online.
Want to stay ahead of regulatory shifts affecting digital finance and investor education? Subscribe to the NCFA newsletter for updates, insights, and expert analysis.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Policy | June 11, 2025
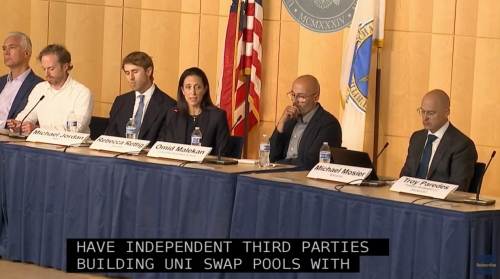
Image: June 9, 2025 DeFi Crypto Roundtable (Coindesk via youtube)
On June 9, the U.S. Securities and Exchange Commission (SEC) hosted another crypto task force roundtable series session called, "DeFi and the American Spirit", bringing together together regulators, legal experts, DeFi protocol developers, and investors to discuss how to the potential of regulating decentralized financial systems in ways that protects users without stifling innovation.
From the get-go, Chair Paul Atkins set the tone by opening the event by clearly stating that publishing code should not be treated as a crime:
“We will not regulate the act of writing open-source software. We do not prosecute the author of a hammer manual when someone misuses a hammer.”
The rest of the session built on this idea and focused on how the SEC can provide safe ways for DeFi projects to operate legally while still addressing investor risks.
In his remarks, Chair Atkins introduced the idea of a “conditional exemptive relief framework” which would allow DeFi innovators to build and launch on-chain products under limited conditions without triggering enforcement right away. This type of framework is similar to a regulatory sandbox that provides time-bound relief as long as participants meet specific safeguards.
“We are exploring a conditional exemptive relief framework that would allow experimentation under defined boundaries, similar to an innovation safe harbor.”
Commissioner Hester Peirce (aka Crypto mom) echoed this sentiment saying without a structured pathways to compliance, many innovators will either operate in legal uncertainty or offshore their projects out of the United States.
“Without a clear, conditional pathway, we are telling innovators you are on your own. That is not a message we want to send if we value the benefits of decentralized systems.”
In addition to the DeFi safe harbour, Chair Atkins also called upon his staff to modernize the current SEC rules to accommodate traditional issuers and intermediaries who want to use on-chain infrastructure.
This move shows that the SEC is looking to facilitate both new DeFi entrants and existing market players who are building tokenized products or using smart contracts to manage trading, issuance, or custody.
“I have asked the staff to consider whether amendments to the Commission’s rules and regulations would be better suited to provide needed accommodation for issuers and intermediaries who seek to administer on-chain financial systems.”
Atkins also discussed that on-chain systems can bring real benefits to the market, such as lower transaction costs, faster settlement, broader access, and the ability to create entirely new asset classes.
“I also am excited about the use of on-chain software systems by issuers and intermediaries to eliminate economic frictions, increase capital efficiency, enable new types of financial products, and enhance liquidity.”
It's clear support and endorsement of blockchain as a tool for economic growth, not just a solution for compliance challenges.
Several panelists, including Rebecca Rettig of Polygon Labs, warned that some of the most serious risks in DeFi happen off-chain. These include hidden liquidity deals, token allocations to insiders, or governance control partnerships.
“It is not always what is on-chain that creates the risk. It is often what is not disclosed, like side agreements, control over governance tokens, or preferential liquidity deals.”
Panelists argued that DeFi projects need better disclosure on how protocols are governed, how tokens are distributed, and whether any third parties receive special treatment or not.
Legal and industry experts said regulators should stop focusing on whether a token is a security and start regulating based on what the product or service actually does.
Angela Angelovska-Wilson of DLx Law said:
“We waste enormous energy litigating over whether X token is a security. The better path is regulating the activity, such as staking, custody, or lending, regardless of the label.”
Michael Jordan of the Digital Dollar Foundation agreed, saying:
“If we regulate the technology, someone will build around it. If we regulate the activity, we have a chance at real consumer protection.”
Important to understand the growing consensus that rules should distinguish between different types of financial behaviour even when the technology is similar.
Josh Garcia of Ketsal pointed out that some interfaces like custodial front ends that take custody of user funds or routes trades on behalf of users may require stricter oversight whereas protocols without admin control may require lighter regulation. Advocating for a layered regulatory approach that differentiates on function and control.
“A protocol with no privileged admin keys is not the same as a custodial front end that routes retail funds. The obligations differ, and so should the rules.”
After several Crypto Task force roundtable sessions, the SEC and participants are finally getting on the same page while focusing on conditional exemptions, regulatory modernization, and functional oversight. All together, it's a series effort to balance investor protection with lawful DeFi innovation. For fintech founders and digital asset platforms in Canada and globally, it's an important benchmark. If the U.S. begins providing clear compliance pathways and policy support for tokenized systems, then other jurisdictions will need to keep up or risk flight of builders and capital.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016