




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 2, 2026
Picture the moment a Canadian fintech dreads most. A regulator's letter arrives. A customer in Quebec, or in a newcomer community you were proud to serve, relied on a disclosure written in their own language, and that disclosure said something the English original did not. Now you are explaining to a supervisor how the wording was produced, who checked it, and why a fee, a risk, or an obligation came out wrong. There is no comfortable answer, because the honest one is this: a single AI model wrote it, and nobody verified it.
That scenario is no longer rare or hypothetical. As fintechs scale into new markets and serve multilingual communities at home, more and more compliance language, terms of service, risk disclosures, consent flows, regulatory filings, is being produced by one AI model with no accuracy standard behind it. It feels efficient. It looks clean. And it quietly builds a liability that only reveals its price later, at the point where it is most expensive to fix.
What makes this gap so dangerous is that its cost stays invisible until it is realized. A mistaken clause does not throw an error message. It sits inside your disclosure reading perfectly, right up until an audit, a customer complaint, or an enforcement review turns it into a remediation project, a forced re-disclosure, a penalty, or a stalled market launch. Regulators do not distinguish between an error a person made and one a machine made. Across Canada's framework, from FINTRAC's obligations under the PCMLTFA, to provincial securities disclosure rules, to the Retail Payment Activities Act, the accuracy of what a customer is told is a supervised matter, not a marketing preference. For firms serving official-language communities, bilingual accuracy is frequently a legal expectation rather than a courtesy.
Every one of those outcomes carries a number. Legal hours. Remediation. Re-issued documents. Delayed revenue while a launch is held. And the quiet, compounding cost of a regulator who now watches you more closely than your competitors. The bill for one wrong word is rarely small, and it almost never arrives on your schedule.
Here is what most teams have not priced in: AI models disagree with one another, and they disagree most on the language that matters most. Independent testing makes this concrete. In Intento's State of Translation Automation 2025, baseline machine systems averaged roughly 10 to 15 errors per text before customization, and synthesized industry data places single top-tier large language model hallucination rates in translation tasks between 10% and 18%. On a marketing tagline, a 12% error band is a style problem. On a regulatory disclosure, it is a liability with a dollar figure attached.
Those errors are idiosyncratic to each model: one engine mishandles a defined term, another drops a conditional clause, a third invents a plausible equivalent that does not exist in the target jurisdiction's regulatory vocabulary. And the risk compounds with length, so the longer the document, a prospectus, a payment services agreement, a full disclosure set, the more independent points of failure a single model introduces. Then there is the cost even a correct-looking output creates. Someone still has to check it. Every hour a compliance lead spends re-reading machine output they cannot fully trust is an hour billed to the single-model shortcut, a verification backlog that never appears on the invoice but is paid every single week.
The way out is architectural, not aspirational. If individual models fail idiosyncratically, then running many at once and keeping only what most of them independently produce turns disagreement into a filter. Intento's own findings point the same way: Slator's reporting on that study noted that a multi-agent workflow explicitly designed to avoid compounding hallucinations delivered the highest quality across nine of eleven language pairs, outperforming any single engine.
This is the principle behind MachineTranslation.com, an AI translation platform built for exactly this failure mode. Its SMART mechanism runs a text through 22 AI models simultaneously, evaluates the source context to determine the most accurate rendering, and returns the output the majority of those models agree on. Because hallucinations are model-specific, cross-model agreement functions as an automated audit: the outlier renderings that shift what an obligation means are structurally filtered out before anyone sees the result. Internal benchmarks put the effect at roughly a 90% reduction in critical error risk, with agreed errors falling below 2% and up to 85% of outputs reaching professional-quality standard. The point is not speed. The point is certainty, and certainty is precisely what removes the hidden costs: fewer errors to remediate, and far less of the verification backlog that quietly drains a compliance team's time.
Cross-model agreement handles accuracy at scale. For the documents where a single error is unthinkable, a regulator-facing filing, a signed customer agreement, a prospectus, certainty has to be absolute, and that is where a second pillar matters. On the same platform, human verification escalates any output to a professional reviewer, adding a validated final check on top of the machine layer. This is not theoretical. Tomedes, the language company behind the platform, documents its high-stakes work in a library of recent translation case studies spanning certified legal filings, court-ready documents, and financial materials handled under confidentiality and delivered to compliance standards. The economics are blunt: the cost of one professional reviewer is trivial next to the cost of one enforcement action. Consensus for accuracy across volume, human verification for certainty on the documents that cannot be wrong.
None of this asks Canadian fintechs to become linguists. It asks them to govern this control the way they already govern every other one. Regulators are moving in exactly that direction on AI more broadly. NCFA's own coverage of the IOSCO AI supervisory toolkit for capital markets frames the expectation plainly: where AI touches a supervised process, firms are expected to show governance, oversight, and accountability for how the system behaves.
Translating compliance content is one of those processes, and today it is often the least governed one in the building. The practical steps are small. Add multilingual accuracy to the risk register. Ask who verified the language a customer relied on, and how. Replace a single ungoverned model with an architecture that removes the error by design and validates the highest-stakes content with a human. The cost of getting the language right the first time is a rounding error next to the cost of explaining why you did not. For a Canadian fintech scaling across markets or serving communities in more than one language, that is the whole choice: money spent on prevention, or money lost to a disclosure you have to defend.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 29, 2026 | NCFA Feature | Open Banking And Open Finance, Digital Identity And Trust, Cybersecurity And Fraud, Risk Compliance And Regtech, Fintech And Innovation

On June 26, 2026, the Government of Canada published Consumer Driven Banking regulations together with new fraud prevention regulations, the most significant progress in Canada's open banking implementation since legislation received Royal Assent earlier this year.
At first glance, the two regulatory packages appear separate. One establishes the operating rules for consumer driven banking. The other requires federally regulated banks to strengthen fraud prevention for electronic funds transfers.
Together, however, they reveal something much bigger.
Canada isn't simply launching open banking. It's building the trust infrastructure needed before open finance can scale.
The problem is that millions of Canadians already share their financial information through screen scraping, a practice tracked as a core open banking risk in Bank Of Canada Signals Open Banking Timing Risk. Finance Canada estimates roughly nine million Canadians currently use screen scraping despite the security, liability, and consumer protection concerns it creates. The new framework is designed to replace that model with accredited participants, standardized APIs, consumer controlled consent, and clear accountability.
Much of the early discussion around open banking has focused on data portability. The regulations suggest Finance Canada sees the challenge differently.
Data sharing is only one part of the system.
Only after these pieces exist does secure data sharing become practical.
The Regulatory Impact Analysis estimates the framework will generate approximately $13.2 billion in net benefits over ten years, compared with implementation costs of about $457.7 million, largely through greater competition, improved consumer choice, reduced friction, and innovation.
Those numbers reinforce that Consumer Driven Banking is being treated as national financial infrastructure rather than another fintech initiative.
Some viewed the fraud regulations as a separate announcement, but the timing suggests otherwise.
As consumers gain greater control over financial data and eventually broader payment functionality, fraud risks also change. Criminals increasingly exploit social engineering, account takeover, impersonation, and authorized push payment scams rather than technical weaknesses alone.
Finance Canada's fraud framework responds by requiring federally regulated banks to establish policies and procedures to detect, prevent, and mitigate consumer targeted fraud involving electronic funds transfers.
The regulations also introduce stronger expectations around consumer controls, including the ability to manage transaction capabilities and limits, express consent before enabling electronic funds transfer functionality, and fraud reporting to the Financial Consumer Agency of Canada.
Greater consumer control must be matched by stronger consumer protection. The inherent message is that the federal government wants to make fraud prevention part of the architecture rather than an afterthought.
Reading the regulations together shows that trust is no longer treated as a policy objective. It's becoming operational and the framework combines:
None of those capabilities creates value on its own, but collectively they create an environment where consumers, banks, fintechs, and regulators can exchange financial information with greater confidence than today's screen scraping model.
The regulations therefore answer an important implementation question that has existed since Canada's open banking discussions began several years ago.
Trust is not assumed. It's engineered.
The regulations also strengthen several areas already appearing across NCFA's Financial Innovation Map.
Consumer consent requirements create opportunities for consent orchestration platforms that help consumers understand, grant, renew, and withdraw permissions across multiple financial relationships.
Accreditation requirements create opportunities for compliance operations platforms that help fintech companies prepare for accreditation, maintain operational controls, manage evidence, and demonstrate ongoing compliance.
Fraud obligations strengthen demand for behavioural fraud analytics, scam detection, mule account monitoring, transaction risk scoring, and real time payment controls.
Authentication requirements reinforce opportunities for digital identity, credential management, and secure customer authentication.
Technical standards create demand for API testing, interoperability tools, certification services, and developer infrastructure.
Liability and complaint provisions strengthen opportunities for workflow automation covering dispute management, evidence collection, case handling, and regulatory reporting.
None of these businesses exists because regulators explicitly created them, but they will emerge because every operational requirement creates work that financial institutions and technology providers must perform efficiently. And that's often where durable fintech companies are built.
The initial Consumer Driven Banking framework focuses on secure consumer permissioned data sharing. It's an intentional starting point.
Once accreditation, liability, consent management, authentication, and technical standards mature, the same infrastructure can support broader open finance capabilities, including additional financial products and, potentially, future write access.
The regulations therefore describe more than the first phase of open banking. They establish the operating foundation for future financial data ecosystems.
The opportunity is not limited to data sharing. It extends into the systems that make data sharing safe, usable, auditable, and commercially scalable.
That includes trust infrastructure, fraud infrastructure, consent systems, API reliability, compliance operations, data governance, and consumer protection workflows.
The next phase of Canada's open banking market will depend on whether these operating layers mature quickly enough for banks, fintechs, consumers, and businesses to use the framework with confidence.
That makes today's implementation decisions highly important because many of tomorrow's fintech products will inherit the rules established now.
For Canada's fintech ecosystem, this strengthens the opportunity case outlined in NCFA's Open Banking Opportunity Brief. The next iteration of value will come from tools that make consent, risk, identity, fraud controls, interoperability, and compliance easier to operate at scale.
If trust, consent, fraud controls, liability, and interoperability become core infrastructure for open banking, which product category will create the greatest competitive advantage for Canadian fintech companies over the next five years?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 26, 2026 | NCFA Fintech Whisperer | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Risk Compliance And Regtech, Payments And Market Infrastructure, Regulation And Policy, Treasury Liquidity And Cash Management

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026, Jun 13-19, 2026).
Credit unions now have a clearer way to test stablecoins, tokenized deposits and digital asset accounts inside member owned financial institutions. Banks, core providers, payments firms, fintechs and regulators should watch whether these early programmes become production deployments for real time settlement, deposit tokens and broader member access to digital assets.
Stablecoin issuer regulation is becoming an AML and identity control issue, not only a reserve or redemption issue. Issuers, banks, custodians, wallets, exchanges and compliance teams should prepare for customer identification, verification, recordkeeping and risk controls as payment stablecoin frameworks mature.
Stablecoin regulation is moving from policy design into operating rules for payment infrastructure. Issuers, banks, custodians, payment firms, exchanges, and fintechs should watch how reserve design, redemption rights, safeguarding, and systemic supervision shape market access for regulated digital money.
Tokenization platforms are entering public capital markets. Asset managers, broker dealers, transfer agents, custodians, exchanges and investors should watch how public company access, regulated ATS infrastructure and cross border digital securities permissions shape the next phase of tokenized fund and real world asset distribution.
Event contract markets are facing a sharper boundary test. Exchanges, brokers, prediction market platforms, sports leagues, tribal gaming authorities and regulators should watch whether Congress narrows the line between federally regulated event contracts and state regulated gambling.
Private market trading infrastructure needs audit rules that firms can apply before transactions scale. Companies, auditors, advisers, venues and investors should watch how PISCES treatment affects independence checks, audit committee planning, transaction readiness and the operating model for periodic private share trading.
Canadian issuer disclosure is becoming more digital by default. Public companies, transfer agents, investor relations teams, legal advisers and compliance staff need to adjust delivery controls, SEDAR+ workflows, investor notices and request handling before the new access model takes effect.
Canadian equity market structure remains tied to US implementation timelines. Trading venues, brokers, market makers, and technology teams need more time to adjust routing logic, fee models, tick increments, compliance controls, and systems that support trading in interlisted securities.
Tokenization is moving closer to regulated market infrastructure. Exchanges, brokers, clearing firms, custodians, digital asset platforms, and regulators should watch how traditional market operators and crypto venues build permissioned pathways for tokenized securities, futures access, custody, execution, and compliance. Similar infrastructure questions are also emerging in event contract markets as new regulated venues, distribution channels, and contract frameworks develop.
Bank AI adoption is moving from pilots to operating metrics. Financial institutions, fintech vendors, compliance teams, investors, and regulators should watch how large banks measure AI value, scale employee access, govern automation agents, and connect AI deployment to fraud control, onboarding, productivity, risk operations, and compute infrastructure markets.
Cross border payments are becoming a regulated corridor strategy. Exporters, payment firms, banks, compliance teams and fintechs should watch how RPAA registration, money services business obligations, local payout capability and bank account connectivity affect competition in Canada India payment flows.
Digital euro policy is becoming payment infrastructure design. The next test is how offline use, privacy controls, holding limits, fees, PSP distribution, and cash protection fit into a system that has to work across public money, private payment providers, and existing rails.
Mortgage distribution is becoming a stronger fraud, licensing, and consumer protection issue. Brokers, lenders, fintech mortgage platforms, compliance teams, and investors should watch how higher penalties, clearer licensing rules, and stronger supervision reshape risk controls in mortgage services.
Financial crime detection no longer depends only on what individual institutions can see. Banks, credit unions, payment service providers, securities dealers, fintechs and other reporting entities can now strengthen risk detection by sharing designated information, creating new opportunities for collaborative fraud controls, network analysis and anti money laundering investigations.
Regulatory enforcement is becoming more incentive driven. Banks, insurers, investment firms, credit unions and compliance teams should review how early investigation strategy, breach assessment, remediation evidence and senior accountability affect enforcement outcomes.
Audit reporting is becoming more focused on useful disclosure, controls evidence and investor readability. Companies, audit committees, auditors, governance advisers and compliance teams should prepare for updated report content, Provision 29 controls statements and revised audit workflows before the December effective date.
Firms need to know where encryption is used, which vendors are exposed, which systems protect high value data, and how long migration will take. Crypto inventory, procurement language, vendor assurance, and roadmap planning should start before compliance dates become delivery pressure.
A regulated operating company is using a tokenized money market fund for its own liquidity rather than presenting it as a future client product. That moves tokenization into daily treasury operations, where continuous access, settlement speed, custody controls and balance-sheet utility can be tested against conventional cash-management infrastructure.
Approval processes are becoming more transparent and predictable for eligible applicants entering or expanding within Canada's federally regulated financial sector. Banks, fintechs, federal credit union applicants and regulated financial institutions should watch how the framework affects application timelines, market entry, organizational changes and future supervisory expectations. For background, see NCFA's earlier coverage of the Streamlined Approvals Framework proposal.
Manitoba has put AI governance and cybersecurity inside the same statutory control structure for the public sector. The next test is implementation. Regulations will determine how far the province goes on human oversight, technical standards, incident reporting and vendor procurement, and whether those requirements become a practical benchmark for other Canadian governments.
Every week brings hundreds of announcements. Only a small number signal meaningful change. This week's developments point to new opportunities across payments, digital assets, AI, capital markets and regulation that could influence where innovation accelerates, investment flows and new business models emerge next.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 22, 2026 | NCFA Insight | Artificial Intelligence And Data, Risk Compliance And Regtech
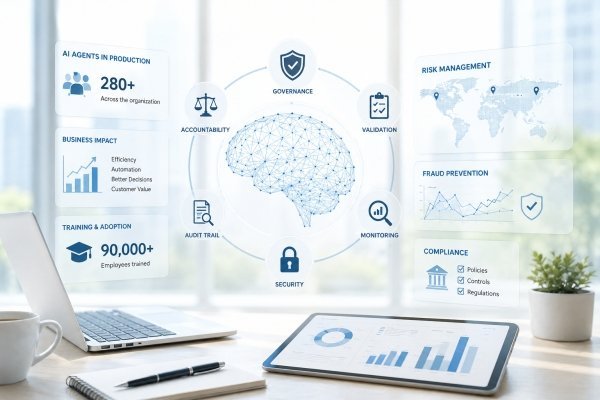
On June 22, 2026, Banco Santander reported that its AI first strategy generated €35 million in business value in Q1 2026, with expected value of more than €200 million by year end and a target of more than €1 billion between 2026 and 2028. That's a regulated bank putting numbers around AI execution.
The more interesting part is how Santander is trying to get there. The bank has extended AI access to all 185,000 employees, reported more than 280 AI automation agents in production, and previously described its ambition to become an AI native bank.
Ricardo Martín Manjón, Chief Data & AI Officer at Banco Santander, put the strategy plainly:
“For me, being AI-first means applying AI where it can have tangible impact.”
For Canada, the timing of this announcement is important because Santander recently received approval to operate as a federally regulated bank in Canada. So its AI operating model more than a global case study. It's a preview of how new banking competitors may bring AI, governance, fraud controls, and measurable operating discipline into regulated Canadian markets.
The first AI cycle rewarded access. Banks tested foundation models, launched copilots, built internal assistants, and looked for productivity wins. That phase is maturing fast. Models are easier to access. Cloud tools are easier to use. Building a convincing demo is no longer the hardest part.
The harder test is operating AI inside a regulated financial institution without losing control of risk, data, decisions, accountability, or customer trust.
That's where Santander’s publicly released data become strategically useful. Specifically, the update points to measurable business value, enterprise wide access, employee adoption, automation agents, and governance controls across ethical, legal, cybersecurity, and risk requirements. This is what AI moving from lab work into operating infrastructure looks like.
One underappreciated piece of the story is Santander AI Lab’s open source work. Its Gen Fraud Graph project is described as an Apache 2.0 open source initiative for generating synthetic fraud graphs and advancing fraud detection capabilities. The technical repository is also available on SantanderAI’s GitHub.
Fraud detection is one of the fastest ways to expose whether financial AI can be trusted. It touches financial crime, AML controls, identity checks, transaction monitoring, customer friction, model risk, and auditability. A model that performs well in a slide deck but cannot be tested, explained, monitored, or reviewed isn't ready for regulated scale.
Synthetic fraud graphs help solve a practical problem. Banks need realistic fraud scenarios to test detection systems, but they cannot freely share customer data or investigative information. Synthetic environments provide a safer way to benchmark performance, validate models, and document results.
The choice of fraud is revealing. Santander didn't launch its open source thread with a marketing assistant or a generic productivity tool. It highlighted infrastructure connected to risk.
Fraud teams need speed, but they also need evidence. Compliance teams need explainability. Risk teams need controls. Boards need accountability. Regulators need confidence that systems can be monitored and challenged.
For fintechs, this move by Santander is both a warning and an opportunity. AI claims won't be enough in fraud, AML, onboarding, underwriting, customer service, complaints, trading, surveillance, or compliance workflows. Buyers will increasingly ask for testing evidence, audit trails, human review, data controls, drift monitoring, and proof that the system works under pressure.
Recent work from IOSCO, OSFI, the European Union, the FCA, and other supervisory bodies points in the same direction. Institutions want measurable results. Customers expect accountability. The result is a growing focus on how AI systems are tested, monitored, explained, and challenged. That's why AI is creating a new compliance burden at the same time it creates productivity gains.
Santander reports more than 280 AI agents operating across the organization alongside enterprise wide training, governance controls, and measurable business outcomes. The same operating question now appears across AI agents entering financial workflows, customer onboarding, fraud detection, transaction monitoring, and compliance operations. The challenge is proving that it can operate safely inside regulated environments, and fraud amplifies the challenge immediately.
AI clones, biometric breaches, faster payments, and cyberattacks are weakening older trust signals, which raises the value of new verification controls for financial trust. Synthetic fraud graphs fit into that bigger problem because they give teams a safer way to test detection systems without exposing customer data or live investigations.
For banks, fintechs, payments firms, and infrastructure providers, that changes the economics of competition. Access to advanced models is becoming easier. Building a prototype is becoming easier. Producing evidence that a system can be trusted under real operating conditions remains difficult.
The first AI race was about capability. The next one is quickly focusing on proof.
If access to advanced AI becomes commonplace, will governance infrastructure and proof of control become more valuable than proprietary models in regulated financial services?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 13, 2026 | NCFA Fintech Whisperer | Capital Markets And Market Infrastructure, Lending Consumer Credit And BNPL, Regulation And Policy, Risk Compliance And Regtech, Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data
Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-Jun 5, 2026, Jun 6-12, 2026).
European supervision is becoming more operational and technology focused. Banks, fintechs, crypto asset firms, infrastructure providers, and compliance teams should watch how DORA, MiCA, and EMIR oversight changes vendor governance, resilience testing, supervisory reporting, third party risk management, and regulatory accountability.
Supervision is becoming more data driven, technology enabled and cross border. Securities regulators are building stronger tools for market surveillance, fraud detection, investor protection and digital asset oversight, which raises the operating bar for firms whose compliance, reporting and risk controls still depend on slow manual processes.
Prediction markets are moving from niche trading communities toward mainstream financial distribution. Retail platforms, exchanges, regulators, investors, and market operators should watch how event contracts evolve as a new information, forecasting, hedging, and market intelligence layer. Distribution may become as important as market design in determining adoption. See: Innovation Opportunities In Regulated Event Contract Infrastructure.
Post trade risk reduction is becoming part of capital markets infrastructure. Dealers, clearing participants, platforms, and regulators should watch how compression, optimization, exposure reduction, and capital efficiency tools are treated as supervised infrastructure rather than back office utilities.
Bond transparency reform is creating demand for new market data infrastructure. Trading venues, asset managers, dealers, data providers, and regulators should watch how fixed income reporting, consolidated data, and transparency tools reshape price discovery and execution quality across European bond markets.
Agentic AI is moving into capital markets workflow. For dealers, asset managers, pension funds, and credit trading desks, the issue is no longer only faster market search. The next phase is how supervised AI tools support pricing, liquidity discovery, execution preparation, and workflow decisions inside regulated markets.
Natural language tools tied to pricing, trade data, and workflow systems could change how institutional traders search markets, compare bonds, assess liquidity, and act on data inside regulated trading environments.
Stablecoins are being embedded directly into payment and remittance infrastructure. Payment firms, PSPs, remittance operators, banks, liquidity providers, and compliance teams should watch how regulated stablecoin settlement, API connectivity, and cross border liquidity become part of the operating stack for high volume regional payment networks.
Search is becoming regulated digital infrastructure. Publishers, fintechs, platforms, marketplaces, advertisers, AI search providers, and compliance teams should watch how ranking rules, data portability, publisher protections, and user choice requirements change discovery, distribution, and competition across search and AI enabled information access.
Institutional digital asset infrastructure is entering bank charter channels. Banks, custodians, wealth platforms, crypto firms and regulators should watch how national trust bank approvals shape custody, staking, lending support, capital requirements and supervisory expectations for digital asset services.
MiCAR is shifting crypto firms from fragmented national registrations toward regulated infrastructure choices. VASPs, exchanges, brokers, fintechs, custodians, and compliance teams should watch how licensing pressure turns custody, wallet services, settlement, liquidity, and operating controls into market access requirements across Europe.
AI linked lending platforms continue to connect consumer credit origination with capital markets distribution. Pagaya’s latest transaction shows how underwriting models, loan supply, securitization channels, and institutional demand are combining into repeatable credit infrastructure.
Canadian bank capital policy is shifting from maximum conservation toward controlled lending capacity. Banks, lenders, fintech partners, investors, and policymakers should watch how lower buffer requirements affect credit availability, capital planning, risk appetite, and competitive conditions across the financial system.
Canada is moving privacy, AI, consumer data, and platform accountability into the same regulatory agenda. Financial institutions, fintechs, AI vendors, data brokers, and digital platforms should watch how consent, deletion rights, automated decision transparency, children’s data protections, and guidance for onboarding, data use, AI and partnerships affect product design and data governance.
The review could affect how fintechs, derivatives firms and market infrastructure providers engage with US regulated markets. Firms should watch for changes that reduce unnecessary compliance friction while maintaining market integrity, customer protection and risk oversight.
The useful evidence is the transmission channel, not a prediction that CBDC will launch. Digital money competition affects deposits, funding costs, liquidity treatment, lending capacity, and central bank balance sheet operations. Operators, founders, and investors should watch how CBDC, fintech deposits, stablecoins, and payment infrastructure reforms change competition for bank funding.
The week's strongest market and regulatory signals weren't new products. They were changes to the infrastructure underneath financial markets. Bank capital rules, prediction market access, stablecoin rails, and compute markets all point to the same outcome. Firms that control access, distribution, liquidity, and critical infrastructure may increasingly determine who can compete and who cannot.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 19, 2026 | NCFA Resource | Artificial Intelligence And Data
On June 18, 2026, the Bank of Canada published Measuring the AI Economy, a staff working paper by Anton Korinek and Patrick McKelvey. The paper examines whether traditional economic statistics can properly capture AI production, compute growth, model training, inference output, and the value being created inside the AI economy.
The paper argues that AI activity is difficult to see through standard GDP categories because it is spread across cloud computing, software, professional services, data centres, chips, electricity, and model development. That makes AI look smaller in official statistics than it may be in production capacity.
The research builds a first macroeconomic estimate of US AI production from 2023 to 2025. It starts with compute as the core input, generated from AI chips, data centre capacity, and electricity. That compute is then split between inference and training.
Inference produces AI outputs used across the economy. Training creates model capital, which the authors treat as an intangible asset that improves future AI output.
The headline numbers are large. The authors estimate that nominal AI compute spending grew from $36.92B in 2023 to $90.46B in 2024 and $219.17B in 2025. That implies annual growth of about 145% in 2024 and 142.3% in 2025.
Physical compute output grew faster, rising about 211.9% in 2024 and 213.9% in 2025. After quality adjustments, the paper estimates AI production growth above 2,000% per year. Its early AI GDP framework estimates real AI GDP growth of about 2,600% in 2024 and 2,658% in 2025.
The authors are careful about the limits. These aren't official GDP statistics. The framework relies on strong assumptions, limited data, and uncertainty about how benchmark performance turns into economic value.
This resource is useful for fintech founders, AI companies, policy teams, investors, economists, regulators, data centre operators, infrastructure investors, and anyone tracking how AI affects productivity, capital allocation, labour markets, and public policy.
It is especially relevant for teams working on AI infrastructure, compute markets, AI governance, productivity measurement, model economics, and public sector digital strategy.
The strength of the paper is its measurement lens. It doesn't treat AI as a single software category. It treats AI production as a system built from chips, power, data centres, inference, training, and model capital. That connects directly to the market question of pricing access to scarce AI capacity.
That's valuable for NCFA readers because compute is becoming an economic input, not just a technical resource. If compute markets, energy access, chip supply, and model efficiency determine AI output, then AI policy and AI competition cannot be separated from infrastructure.
The paper also gives policymakers a warning. If official statistics do not capture AI capacity early enough, fiscal planning, productivity analysis, tax policy, and monetary policy may be working with incomplete information. The same measurement issue shows up in central bank operations, where the Bank of Canada has already examined AI adoption in central banking.
The limit is uncertainty. The authors don't claim to replace GDP. They propose a measurement framework that can support future AI satellite accounts and better statistical infrastructure.
Bank Of Canada Measuring The AI Economy (primary Bank of Canada working paper)
AI Agents Enter Governed Financial Workflows (AI governance and operations)
AI Risk Taxonomy For Audits And Controls (AI risk classification)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2026 | NCFA Story Intelligence | Fraud, Cybersecurity And Trust
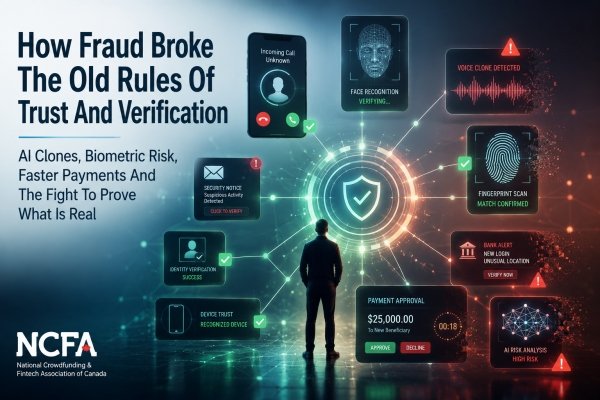
The phone rings. Many people no longer answer.
Not because they’re too busy. Because they’re not sure who is calling, what’s real, or whether the message is safe to trust. That small behaviour change tells a bigger story about finance, fraud, identity, and technology.
For years, financial trust relied on familiar signals: a voice, a face, a password, a bank name, a phone number, a regulator, a delay before money moved. AI clones, biometric breaches, deepfakes, cyberattacks, weak AML controls, and faster payments are now breaking those signals at the same time.
Financial trust used to have more time. Branch visits, paper signatures, settlement delays, call centre checks, account holds, and human review gave institutions more room to spot problems before money moved too far. The system was slower, but that slowness created time to verify.
Consumers learned to trust familiar signals. A bank logo felt official. A caller who knew account details sounded credible. A voice sounded personal. A password felt private. Those signals were never perfect, but they worked well enough when fraud was slower, less automated, and easier to recognize.
Online finance moved trust away from the branch. Banking, investing, lending, crypto, payments, and onboarding shifted into screens and apps. That created better access and faster service, but it also made customers depend on passwords, text codes, device checks, email links, and remote identity tools.
Fraudsters followed the customer online. Phishing, fake websites, account takeover, crypto wallet scams, approval phishing, QR abuse, and spoofed support channels made digital convenience feel less certain. Operation Avalanche showed how coordinated fraud response is becoming part of the market.
Voice used to feel personal. Then AI cloning made it copyable. Cloned voices bypassed Voice ID tests at Santander and Halifax, exposing weakness in systems that treated a voice as a reliable authentication signal.1
The scam no longer has to sound like a scam. A cloned voice can sound calm, familiar, urgent, or official. That changes the risk for banks, call centres, families, executives, seniors, and anyone asked to approve a transfer or share information after hearing a voice they think they know.
Biometrics raise the stakes because they cannot be replaced easily. A major India breach exposed fingerprints, facial scans, and sensitive records tied to police officers and applicants.2 A password can be reset. A fingerprint can’t.
Fintech products increasingly depend on biometric convenience. Face ID, Touch ID, palm payment, device based onboarding, and selfie checks reduce friction. They can also concentrate risk if biometric templates, face scans, or identity documents are stored poorly or exposed through vendors.
Deepfakes make fraud feel human. Deepfake scams have used AI generated voices, fake identities, digital banks, and crypto rails to trick victims and move funds quickly.3
AI makes deception cheaper to personalize. Fraudsters can imitate an executive, a family member, a bank employee, a support agent, or an investment promoter. The scam can be written better, timed better, targeted better, and delivered through channels that look more legitimate than old phishing emails.
Faster money gives fraud less time to fail. Real Time Rail, instant payments, request to pay, and faster settlement can improve cash flow and customer experience. They also shrink the window for fraud teams to stop a bad payment before it settles.
Fraud controls become part of the payment product. Real Time Rail analysis connects instant payments with centralized fraud capability, payment finality, and trust.4 Faster money only works if participants believe the system can manage faster mistakes.
Institutions are not only defenders. They are targets. CIRO confirmed approximately 750,000 Canadian investors were affected by a cybersecurity incident after a 9,000 hour forensic review.5 When regulated bodies are breached, trust damage extends beyond one account.
Third party systems can carry hidden risk. SaaS vendors can create concentration risk across fintech and financial services. A startup may inherit risk through a vendor, API, data processor, onboarding tool, cloud provider, or fraud vendor it does not fully control.
AML failure shows how controls can become business risk. TD’s more than $3 billion US AML penalty and leadership fallout showed how weak controls can limit strategy, growth, reputation, and trust.6
Canada is trying to organize the response. Canada’s first National Anti Fraud Strategy and Financial Crimes Agency push point toward more public and private collaboration on cyber risk, data sharing, and proceeds of crime recovery.7
Fraud didn’t break trust all at once. It weakened the signals people and institutions used to verify reality. The phone call. The voice. The face. The fingerprint. The login. The bank name. The official looking message. The settlement delay. The regulated institution. Each one still matters, but none can carry trust on its own anymore.
That’s the hard part for financial innovation. Canada is moving toward faster payments, consumer driven banking, digital identity discussions, AI adoption, crypto market controls, and more automated financial services. None of those systems succeed simply because they’re fast or digital. They succeed because people trust what they’re seeing, hearing, approving, and authorizing.
What trust signal do you question now that you wouldn’t have questioned five years ago?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016