





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 30, 2026 | NCFA Fintech Whisperer | Payments And Market Infrastructure, Digital Assets Blockchain And Tokenization, Artificial Intelligence And Data, Regulation and Policy, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-13, 2026, March 14-20, 2026, March 21-27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026).
Tokenized bonds are moving from pilots into market structure work. Issuers, dealers, custodians, infrastructure providers, and regulators need practical answers on issuance, settlement, custody, disclosure, and secondary liquidity before tokenized fixed income can scale.
The value of cross chain infrastructure comes down to whether developers can route liquidity without exposing users to bridge complexity. The $230M private beta gives 0x early usage evidence, but the larger test is reliability across payments, RWAs, trading, and agent workflows when volumes move beyond controlled integrations.
Stablecoin licensing is becoming a competitive infrastructure tool for financial centres. Issuers, banks, PSPs, custodians, and regulators should track which jurisdictions turn stablecoin rules into live market access rather than policy design alone.
Tokenized money market funds are becoming part of institutional onchain liquidity infrastructure. Asset managers, custodians, PSPs, stablecoin issuers, and treasury teams should track how stablecoins connect with regulated fund products, redemption workflows, and stablecoin payment infrastructure.
Institutional DeFi is shifting toward custody controlled access models. Asset managers, custodians, exchanges, advisers, and compliance teams should track whether qualified custody plus curated onchain strategies becomes the operating model that brings DeFi exposure into regulated portfolios.
The useful signal is not simply another crypto loan product. It is committed buyer capital behind crypto backed credit, which can make the product more repeatable. The key risks remain collateral volatility, liquidation design, borrower suitability, and whether digital asset wealth can support credit access without turning into hidden leverage.
Crypto collateral can help asset rich borrowers avoid selling Bitcoin or USDC, but housing finance brings stricter expectations around suitability, custody, volatility buffers, and borrower protection. The product will need to prove it expands access without importing crypto market risk into mortgage underwriting.
Large banks are moving from stablecoin observation into direct tokenized money infrastructure. Treasury teams, payment providers, fintechs, custodians, and infrastructure operators now need to track whether commercial bank money becomes a regulated settlement layer for high value payments, liquidity management, and cross border transactions.
Western Union’s stablecoin entering a major crypto exchange channel adds another proof point for stablecoins becoming payment infrastructure. PSPs, exchanges, banks, remittance firms, and compliance teams should track how regulated issuers, fiat channels, and global payout networks connect. This adds a distribution proof point for regulated stablecoins. Western Union brings the remittance brand and global currency footprint, while Bybit brings crypto exchange access. The open question is whether USDPT becomes a settlement asset customers actually use, or another branded stablecoin competing for scarce transaction depth.
Central bank money settlement is being designed for programmable markets. Banks, FMIs, tokenized asset platforms, and settlement operators need to understand how RTGS synchronisation could connect central bank money with external asset ledgers and reduce settlement risk in digital markets.
Domestic real time payment systems are becoming exportable cross border infrastructure. Payment networks, banks, wallets, tourism merchants, and regulators are building direct QR payment links that reduce card dependence and make national payment rails usable outside their home markets.
Access to Canada’s payment infrastructure continues to widen beyond traditional banks and large financial institutions. Fintechs, payment providers, credit unions, foreign exchange firms, and digital finance companies are gaining a larger role in the systems and governance discussions that shape payment modernization.
Open banking is moving from one off payments into repeatable payment schemes with shared rules and commercial terms. Banks, PSPs, merchants, fintech platforms, and regulators should track whether recurring account to account payments become a real alternative to cards, direct debit, and closed wallet systems.
Card settlement is no longer limited to traditional banking hours or traditional settlement assets. Banks, acquirers, PSPs, stablecoin issuers, and fintech platforms should track how major payment networks use regulated stablecoins to support faster settlement, lower liquidity friction, and always on money movement.
Stablecoin remittances are moving from fintech experiments into established money transfer networks. Banks, PSPs, remittance firms, stablecoin issuers, and compliance teams should track how large networks use tokenized dollars to reduce settlement friction while staying inside regulated payment flows.
Pay by bank is becoming a practical payment rail strategy, not just a checkout concept. PSPs, banks, merchants, and fintech platforms should track how instant payment routing, risk controls, and settlement access shape competition against cards and traditional ACH flows.
Stablecoins are gaining traction in regulated payment flows, not just trading markets. Remittances remain one of the clearest real world use cases because settlement speed, foreign exchange costs, and cross border reach matter more than speculative activity. Canadian fintechs, PSPs, banks, and regulators should watch whether stablecoin based remittance models can scale while meeting compliance, safeguarding, and consumer protection requirements.
OpenPayd’s planned Nasdaq listing puts programmable money movement under public market scrutiny. PSPs, banks, stablecoin firms, embedded finance platforms, investors, and regulators should track how the listing exposes the economics, licensing footprint, transaction volume, and risk controls behind global payment infrastructure.
Crypto sanctions enforcement is moving deeper into exchange infrastructure and stablecoin flows. Exchanges, custodians, PSPs, blockchain analytics firms, and compliance teams should track how sanctions screening, stablecoin monitoring, and cross border counterparty controls become core operating requirements.
Technology policy is increasingly becoming infrastructure policy. As governments focus on AI capacity, cloud services, strategic data assets, semiconductor supply chains, and digital resilience, firms may face growing pressure to evaluate technology dependencies, procurement choices, hosting arrangements, and infrastructure risk. The result could be a more fragmented global technology environment shaped by competing sovereignty frameworks.
Consumer AI policy is moving toward practical controls for trust, consent and accountability. Banks, fintechs, AI firms, platforms and regulators should watch how user controls, complaint routes, audit trails and outcomes based duties apply when AI systems influence financial decisions or act for consumers.
The operating change is where AI work happens. If capable agents can run locally, more sensitive analysis, file handling, audio processing, and workflow automation can stay on device instead of moving through cloud APIs. That could change enterprise AI design, human oversight, privacy controls, and bot to bot workflows.
The United States is testing a lighter regulatory model for frontier AI that relies on voluntary participation, security evaluation, and industry cooperation. Financial institutions, fintechs, infrastructure providers, and AI developers should watch whether this approach accelerates deployment while maintaining confidence in systems that increasingly influence payments, capital markets, fraud controls, and critical infrastructure.
Revolut’s U.S. strategy shows why bank charters are becoming infrastructure plays for global fintechs. FDIC insured products, payment rail access, stablecoin services, and securities trading under one app could raise the competitive bar for sponsor bank dependent fintech models.
Stablecoin regulation is becoming a competitiveness question, not only a risk control exercise. Issuers, banks, PSPs, custodians, and policymakers should track whether the UK loosens its approach or keeps tougher safeguards that could limit domestic stablecoin scale.
Stablecoin supervision is becoming cross border supervision. Issuers, exchanges, custodians, payment firms, and compliance teams should expect more information sharing between regulators as stablecoin activity crosses jurisdictions, banking systems, and payment networks.
The word of the week is 'control'. Banks, payment networks, fintechs, custodians, stablecoin issuers, and AI providers are competing closer to the infrastructure layer, where settlement, custody, compliance, data, and distribution decisions get made. Which rails, licenses, partners, and operating models create durable access before the next layer of financial infrastructure gets locked in?
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA weekly newsletter updates, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 5, 2026 | NCFA Insight | Artificial Intelligence And Data
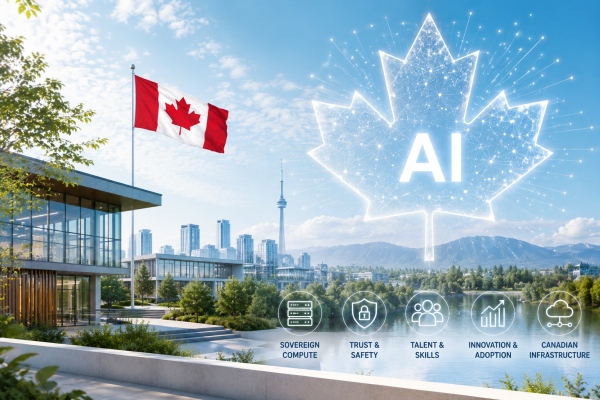
On June 4, 2026, Prime Minister Mark Carney launched AI for All, Canada’s new national artificial intelligence strategy. It targets $200 billion in additional economic growth, 250,000 new AI related jobs over five years, and a rise in AI adoption from just over 12% today to 60% by 2034.
The strategy also aims to create up to 90,000 AI related jobs and work placements for young Canadians. It supports AI skills, trust and safety, sovereign compute and cloud infrastructure, and Canadian company scale up. Canada’s AI challenge is no longer research. It is deployment.
Canada helped build the modern AI era. The country has three National AI Institutes, Vector Institute in Toronto, Mila in Montréal, and Amii in Edmonton. It also has a long record of public investment in AI research and talent.
Yet the harder problem is in the AI economy. The federal government says Canada remains among the slowest countries to adopt AI at scale. Only slightly more than 12% of Canadian businesses use AI today. AI for All sets a target of 60% adoption by 2034.
Canada has AI credibility, but it lacks broad deployment. Research output can attract talent and capital. Still, productivity gains only show up when companies redesign workflows, train workers, improve operations, and build commercial products around the technology.
This connects directly to Canada’s AI adoption gap. The next phase depends less on model breakthroughs and more on whether firms can put AI to work across finance, healthcare, manufacturing, energy, agriculture, transportation, and public services.
AI for All is a strategy with announced investments, but it’s not positioned as one simple funding package. It sets out an implementation plan built around trust, opportunity, and sovereignty.
The plan includes stronger privacy and online safety rules, AI transparency measures, expanded AI Safety Institute capabilities, entry level AI training for all Canadians, trusted AI agents for post secondary students, SME adoption support, and an AI Missions Program that starts with health.
Canada needs more firms, workers, and public institutions using AI in ways that raise productivity, improve services, and create Canadian owned economic value.
For fintech leaders, the strategy reads like an implementation roadmap. AI adoption will depend on infrastructure, skills, procurement, privacy rules, data governance, and trust. These are the same issues affecting open finance, digital identity, fraud prevention, payments modernization, and smart data infrastructure.
Financial services may offer one of the clearest adoption tests. Banks, credit unions, insurers, wealth management firms, payment companies, and fintechs already run data heavy businesses. They also rely on repeatable workflows, compliance controls, customer records, and risk systems.
AI can support fintech use cases from fraud detection and credit assessment to investment research and operational risk monitoring. That creates an opening for Canadian regtech firms, AI infrastructure companies, payment providers, lending platforms, and wealthtechs that can help institutions move from pilots to production.
The same issue appears in AI and non traditional data in financial services. Financial institutions can use AI to improve decisions, but they need governance that protects consumers and supports regulatory trust.
The strategy pushes AI into national competitiveness policy. It names compute, cloud, connectivity, data, and talent as foundations of sovereign Canadian AI.
Canada’s national AI strategy also says the federal government will continue delivering more than $2 billion in existing investments in Canadian AI compute capacity, including through the AI Compute Challenge. This isn't a single new $2 billion package in the Prime Minister’s release. It's an existing compute investment stream tied to Canada’s wider sovereignty strategy.
It also connects directly to Canada’s recent debate over cloud concentration and AI sovereignty. Compute capacity and cloud control can determine whether domestic firms can scale without deeper platform dependence.
Countries don’t capture AI value only by producing researchers. They capture value when companies scale, retain key talent, own intellectual property, and sell into global markets from a domestic base.
For Canadian fintechs and investors, sovereign AI infrastructure affects who controls data, how firms access compute, how procurement supports domestic companies, and whether Canadian AI companies can scale before larger foreign markets pull them away.
AI for All sets ambitious targets. The proof will come from adoption, scale, productivity, and trust.
Can Canadian business adoption rise from just over 12% to 60% by 2034? Can Canadian AI firms scale while keeping meaningful operations, talent, and intellectual property in Canada? Can regulated sectors deploy AI with enough transparency and accountability to earn public trust?
Canada already proved that it can build AI research strength. Yet it hasn’t proved that it can turn that strength into widespread productivity gains and globally scaled companies at the same pace as larger markets.
For NCFA members, the opportunity lies in execution. Founders can build AI tools that solve costly financial sector problems. Investors can look for firms with real workflow adoption, not only technical claims. Policymakers can reduce friction where regulation, procurement, data access, and capital formation slow responsible deployment.
AI for All is a clear shift in Canada’s AI policy. Ottawa now looks at AI as an adoption, productivity, sovereignty, and scale up challenge, not just a research agenda. Canada’s AI advantage will come from helping more Canadian firms use AI, sell AI, govern AI, and keep more of the value created by AI in Canada.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
June 3, 2026 | NCFA Insight | Artificial Intelligence And Data, Regulation And Policy

On June 2, 2026, the Canadian Anti Monopoly Project released Parting Clouds: Creating A Competitive Marketplace For Compute that says three American companies control 85% of Canada's public cloud market. Canada wants sovereign AI. It's a gap that Ottawa needs to address before it commits more public money to AI infrastructure.
Globally, those same three firms Amazon, Microsoft, and Google, hold about 66% of the public cloud market. AI runs on compute, but most firms access that compute through cloud platforms. The more difficult it becomes to move data, workloads, and AI services between providers, the more dependent organizations become on a small number of platforms.
Compute means the physical capacity. Think data centres, chips, GPUs, servers, storage, power, cooling, and networks. Cloud is the commercial aspect that packages that capacity into services like APIs, software tools, security controls, and platform ecosystems.
Canada can fund more compute and still leave firms locked into the same cloud stacks. That concern connects to NCFA’s earlier analysis of Canada’s AI capital flight problem, where public AI investment doesn't always translate into long term domestic value especially if customers cannot move their data, workloads, models, and services without high technical and financial costs.
The CAMP report makes that point clearly. The goal isn't simply Canadian ownership. The goal is a market where customers can switch providers without rebuilding core systems. Most Canadian firms cannot replace that stack overnight.
Federal spending tells the same story. From 2019 to 2020 through 2022 to 2023, Shared Services Canada spent $310.4M on cloud services. The report says 66% went to Microsoft, 16% to Amazon, 14% to Salesforce, and 4% to other providers.
Cloud concentration already creates switching barriers through proprietary services, opaque pricing, and weak interoperability.
AI makes those barriers harder to manage. A fraud model, compliance agent, lending workflow, or payment risk tool can become tied to a provider’s data services, model tools, security layer, and deployment environment.
Moving clouds then means more than moving storage. It can mean rebuilding how the product works.
Five firms control about 75% of global AI compute power, with Google alone controlling about 31%. That concentration shows why AI sovereignty is not only about funding more capacity. It's also about keeping customers mobile before AI markets harden around the same platforms.
The name of this section is the report's strongest warning and it should affect Ottawa's strategy.
More Canadian data centres can help. Domestic compute can support sensitive workloads, national resilience, and local AI capacity. Ottawa has already backed 44 Canadian AI compute projects, but if public funding only creates protected local gatekeepers, Canada may replace one dependency with another.
The better goal is customer mobility. Can a Canadian fintech move workloads from one provider to another? Can a public agency compare cloud pricing easily? Can a startup use AI tools without being trapped inside one ecosystem? Can sensitive workloads use Canadian infrastructure without sacrificing portability?
Ottawa should fund infrastructure, but also change the market around portability, interoperability, transparent pricing, and competition.
The CAMP report recommends using public procurement to require portable data, interoperable services, and common technical standards. It also calls for closer scrutiny of egress fees, bundling, tying, discriminatory licensing, cloud credits, and acquisitions that absorb Canadian talent and intellectual property.
This approach has tradeoffs. Procurement can move faster than legislation, but it needs technical discipline. Competition enforcement can target lock in, but cases take time. Interoperability can lower switching costs, but it will not instantly match the full global scale of AWS, Azure, or Google Cloud. Domestic infrastructure can improve resilience, but only if it avoids new lock in.
Will Canada measure AI sovereignty by domestic capacity, or by real customer choice?
Will public funding require portability, open standards, and transparent pricing?
Will Canadian fintechs and AI startups be able to move workloads across providers without rewriting core systems?
Will the strategy treat cloud concentration as a competition issue, not only an innovation issue?
Will Canada build a market where providers compete on price, performance, trust, and service quality, or one where customers stay trapped because switching costs are too high?
If a Canadian fintech cannot realistically move its AI stack from one provider to another, who holds the leverage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 3, 2026
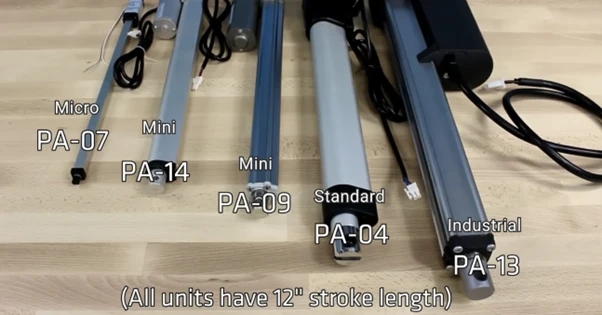
Walk through any modern facility and you're surrounded by controlled movement that most people don't examine. A hospital bed adjusting position at the touch of a button. A greenhouse vent opening in response to temperature. A conveyor gate diverting product into a secondary line without anyone pressing anything. The mechanism behind most of this is the same, and it has a name most people outside engineering have never used: an actuator.
That's changing. As automation spreads across Canadian industries, from manufacturing and agriculture to building infrastructure and healthcare, the actuator has moved from a component that engineers specify quietly to something that business decision-makers, procurement teams, and technology investors increasingly need to understand.
An actuator converts energy into mechanical motion. Depending on the energy source, that's either electrical current, compressed air, or pressurised hydraulic fluid. Depending on the application, the motion produced is either linear, a straight push or pull along a single axis, or rotary, rotation around a fixed point.
Electric linear actuators are the most relevant category for the broadest range of modern applications, and understanding how they work explains most of what matters in practice.
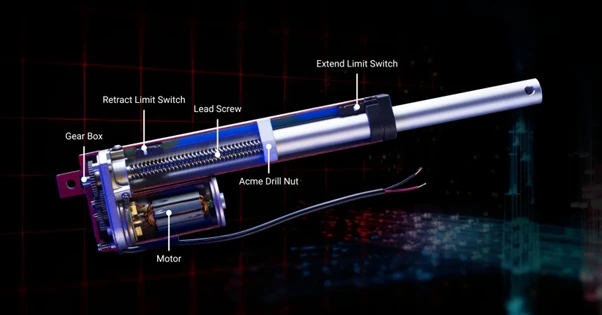
A motor drives a lead screw, a precisely threaded rod. A drive nut sits on the screw and meshes with the thread but is prevented from rotating. So when the screw turns, the nut has no option but to travel along it. The rod attached to the nut extends outward as the nut moves in one direction and retracts when the motor reverses.
What this produces is controlled, precise, repeatable straight-line movement from an electrical input. The relationship between motor rotation and rod travel is fixed by the thread pitch, so controlling the motor precisely means controlling the rod's position precisely. Stop the motor and the rod stops. Add position sensing and you know exactly where it is throughout its travel.
This is what makes electric actuation more capable than pneumatic alternatives for most modern applications. A pneumatic cylinder applies pressure in one direction and that's essentially it. An electric actuator can stop at any point in its travel, modulate force, hold a position, and communicate its status to a digital control system. For an era of networked, sensor-driven industrial automation, that's the relevant difference.
One characteristic of lead screw actuators that has real practical consequences is self-locking. With a fine enough thread pitch, the geometry prevents the load from backdriving the mechanism when the motor isn't powered. The rod holds its position without the motor running continuously.
For a patient positioning system that needs to hold position while the patient is settled. For an industrial fixture that needs to maintain clamping force after moving to position. For an adjustable workstation that shouldn't drift during the working day. Self-locking provides this without continuous power draw, which matters both for energy efficiency and for safety in applications where unexpected movement would be a problem.
Not every actuator is self-locking. Coarser thread pitches that prioritise speed over force may allow backdrive. Worth checking explicitly for any application where the load needs to stay put between operations.
The application range is genuinely wider than most people expect once they start looking at it properly.
In manufacturing, actuators drive automated clamping systems, press mechanisms, conveyor divert gates, and positioning equipment. The precision and repeatability they provide is what makes consistent product quality achievable at production scale without continuous human intervention.
Agriculture has become a significant application area. Irrigation control valves that open and close in response to moisture sensors. Greenhouse ventilation systems that regulate temperature automatically. Adjustable equipment on precision farming machinery. These are applications where automation changes operational efficiency in ways that manual operation simply can't match.
Building infrastructure relies on actuators more than most occupants realise. HVAC damper control in commercial buildings adjusts airflow continuously based on occupancy and air quality data. Flood barrier mechanisms operate remotely in response to water level sensors. Automated access control systems handle gate and barrier movement. In a large building, there may be hundreds of these operating simultaneously.
Healthcare is where the performance requirements are most demanding. Surgical tables, patient lift systems, infusion pumps, powered prosthetics. The precision, reliability, and safety standards for actuators in medical applications are substantially higher than in other categories, which is part of why the engineering in that segment has driven development that benefits other application areas.
Consumer applications are broader than most people notice. Electric recliners, adjustable bed bases, sit-stand desks, motorised kitchen cabinet lifts, automated vehicle tailgates. The quality difference between a well-engineered mechanism and a cheap one shows up immediately in how the movement feels.
The actuator selection process looks simple and isn't. Getting one parameter wrong creates problems that are often expensive to fix after installation.
Force rating first. The rated capacity needs to exceed the actual load with meaningful margin, not match it. A unit running at its rated maximum runs hotter and wears faster than one with capacity to spare. One and a half to two times the calculated load is reasonable for most applications. Direction of load matters as much as magnitude. Vertical lifting is the most demanding scenario. Horizontal pushing requires considerably less force for the same load. Angular applications pushing a hinged element through an arc have a force requirement that varies throughout the travel and needs to be assessed at the worst position, usually one of the end points.
Stroke length should match the required travel with some buffer. An actuator that runs out of stroke before the mechanism reaches its end position is a specification error that typically means replacing the unit.
Duty cycle is the parameter that catches people out most often. A unit rated for 20% duty cycle needs four minutes of rest for every minute of running. For a greenhouse vent that cycles twice a day this is irrelevant. For a production gate cycling every few minutes through an eight-hour shift it's the critical specification. Heat is what degrades over-cycled actuators, and the failure tends to arrive weeks after installation rather than immediately, making it easy to misattribute.
Environmental rating needs to match actual installation conditions. IP65 handles outdoor use in typical conditions. Agricultural environments with chemical exposure, food production settings requiring washdown, and coastal locations with salt corrosion all need higher ratings. The cost difference at purchase is small. The cost of premature failure in a difficult-to-access location is not.
Voltage is largely a practical question. 12V DC suits residential, mobile, and off-grid applications. 24V DC is standard in commercial and industrial settings where longer cable runs make voltage drop at lower voltage a real problem. Getting this right at the start avoids needing a converter in the installation.
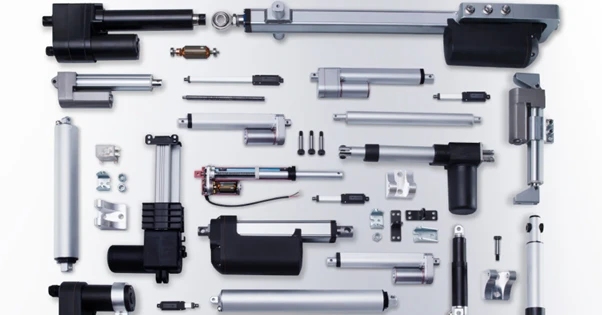
Control requirements should be established before selecting the unit. A basic extend-retract application needs only a switch. An application needing precise intermediate positioning needs position feedback, Hall effect sensors or a potentiometer, built into the actuator. An application integrating with a building management system or industrial PLC needs compatible control inputs. The linear actuator range that covers all of these specifications is wider than most buyers realise when they start looking.
Electric actuation has been displacing pneumatic and hydraulic systems across a widening range of applications for two decades, driven by the advantages in controllability, digital integration, and the elimination of fluid infrastructure. The direction of industrial automation, toward more connected, more instrumented, more precisely controlled systems, continues to favour electric actuation.
For Canadian businesses evaluating automation technology, the actuator is usually not the headline component. It's the mechanism that makes the headline component work. Getting the specification right has consequences across the operational life of the equipment it's installed in, which makes it worth understanding properly rather than treating as a procurement detail.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
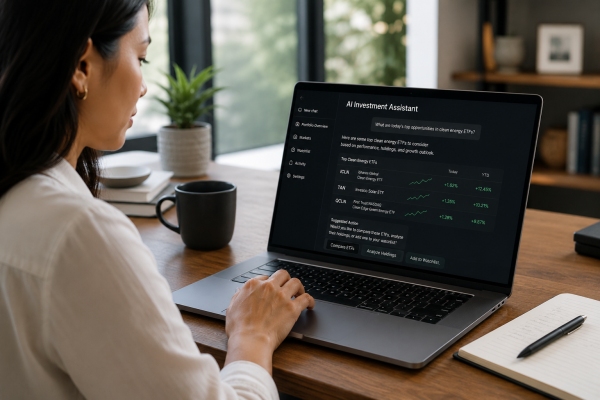
On May 26, 2026, Liquid launched Co Invest for ChatGPT and Claude, allowing users to research markets, construct portfolios, fund accounts, and execute trades from inside an AI conversation. The platform supports more than 500 markets across stocks, ETFs, commodities, crypto, FX, prediction markets, and pre IPO opportunities. Every trade still requires user confirmation before execution.
The launch is testing a new distribution model for financial services. For two decades, brokers competed to convince customers to visit websites and download apps. Liquid is testing a different idea. This is already happening in commerce. Agent driven checkout and payments are moving purchase decisions closer to AI assistants.
What happens if the customer never leaves the AI assistant?
Traditional brokerage growth follows a familiar formula. Acquire the customer. Get them into the platform. Keep them engaged. Generate more activity inside the platform.
Co Invest reverses that process. The customer already lives inside ChatGPT or Claude. Research happens there. Portfolio construction happens there. Market comparisons happen there. The trade happens there. The broker becomes the infrastructure underneath the conversation.
The launch announcement describes Co Invest as a way to move from market question to live execution inside a single workflow. If customers increasingly begin their financial decisions inside AI assistants, brokers may need to compete for agent connectivity as aggressively as they once competed for app downloads.
Much of the discussion around AI and investing focuses on autonomous trading. Liquid's current product doesn't do that. Users must still approve all trades before execution (at least for now). The assistant can research, compare, explain, size positions, and prepare orders, but it cannot freely move money or trade without permission (aka the agentic trading model).
Perhaps before markets and regulators reach fully autonomous investing, there will be a type of 'permissioned investing' that gets iterated before then. The goal isn't unrestricted authority. It's a type of controlled automation with clear limits, permissions, and accountability.
Example: A customer could authorize an agent to purchase a specific ETF under preset conditions, apply position limits, avoid leverage, stop trading after a certain loss threshold, and require additional approval for larger transactions.
This approach may appeal to regulators, brokers, and investors because it preserves accountability while reducing friction.
The benefits are easy to understand. AI agents can monitor markets continuously, enforce risk rules consistently, compare opportunities quickly, and reduce emotional decision making.
The risks are less obvious. If millions of investors eventually rely on similar models, data sources, prompts, and optimization goals, market behaviour could become more concentrated. Markets already experience crowding through index investing, quantitative strategies, and algorithmic trading. Agentic investing could introduce a new version of the same challenge if many systems begin reaching similar conclusions at the same time.
The concern is that a large number of investors could end up acting through similar decision frameworks without fully realizing it. A model that works well for one investor may create new market risks when millions of investors use similar prompts, data sources, and optimization rules. The result could be more crowded trades, sharper reversals, and less diversity in market decision making.
If AI assistants become the place where investors start financial decisions, brokers lose some control over the customer interface and relationship.
Distribution changes and brokers may need to prove itself to the AI systems that sit between customers and financial products.
That creates a different kind of competition. Brokers may be forced to compete on permission controls, API reliability, execution quality, and audit records as much as interface design.
The broker with the most reliable AI integrations may win more order flow than the broker with the best looking app.
Canada's discussions around consumer driven banking, digital identity, AI governance, retail payment oversight, and securities regulation all intersect here. If AI assistants become a gateway to investing, accountability becomes more important than automation.
Who approved the instruction? What permissions were granted? What limits were applied? What records were created? Who supervised the activity? Those questions are more important than whether the interaction started in a brokerage app or a chatbot.
Current securities rules already apply to firms using AI, and AI is creating new audit and authorization questions for financial firms. The harder challenge is determining how responsibility should be shared when AI systems increasingly participate in financial decisions and transaction workflows.
Liquid's launch doesn't answer those questions, but it provides an early look at where the industry may be heading.
If AI assistants become the primary place where investors research markets, compare opportunities, and initiate transactions, will brokers compete for customers or compete for connectivity to the agents representing those customers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 2, 2026 | NCFA Resource | Artificial Intelligence And Data

On June 2, 2026, the Bank of Canada published Canadian firm AI adoption survey data from its December 2025 Business Leaders’ Pulse. The research gives fintechs, investors, financial institutions, regulators, and policy teams a useful benchmark for assessing where Canadian businesses stand on AI use, deployment, capital spending, and employment expectations.
The resource draws on 314 firm responses. It separates personal AI use by business leaders from operational AI use inside firms. Many Canadian leaders already use AI at work, but fewer firms use AI in production, service delivery, or core business workflows.
The research helps readers compare AI awareness with real deployment:
The Bank of Canada also shows where AI use starts. Text generation ranks as the most common current application. Visual content creation and machine learning based data processing follow. Over the next three years, firms expect more use of data processing applications, which may matter more for financial services than basic content generation.
For fintechs and financial institutions, AI awareness no longer creates differentiation on its own. The harder work involves choosing real workflows, testing productivity gains, managing risk, training staff, improving data quality, and deciding where AI deserves capital spending.
Fintech founders can use the paper to test whether customer demand has reached live deployment or is still stuck in pilot mode. That helps product teams avoid building around hype alone.
Investors can use the data to assess where demand may grow for AI governance tools, workflow automation, data infrastructure, compliance technology, customer service systems, and implementation support.
Financial institutions can compare their own AI programs against broader Canadian firm expectations. The paper gives banks, credit unions, insurers, and wealth firms a clearer view of how business leaders think about investment and employment effects over the next year and the next three years.
Regulators and policymakers can use the paper to understand practical adoption barriers. Firms that do not use AI most often cite lack of usefulness for their operations. Other barriers include skills, software compatibility, ethics, cost, regulatory obstacles, and data quality.
The strength of this resource is its Canadian evidence base. It also separates personal AI use from business deployment, which makes the adoption picture more useful.
The paper also connects AI adoption with capital spending and employment expectations. Firms expect AI to have a more positive effect on capital expenditures over three years than over the next 12 months. Employment expectations look more cautious. Over three years, 18% of firms expect to hire fewer staff because of AI, while 9% expect to hire more.
The limit is survey design. The Business Leaders’ Pulse helps assess aggregate economic conditions relevant to Canadian GDP. It doesn't produce population representative estimates of firm behaviour. Readers should treat the results as useful directional evidence, not a full census of Canadian AI adoption.
Bank of Canada AI adoption survey (primary staff analytical paper on firm AI adoption, capital spending, and employment expectations)
Bank of Canada central banking AI resource (resource on AI adoption inside central banking and controlled deployment)
Canada AI productivity analysis (analysis on AI adoption, productivity, capital, and execution)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 1, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing
On May 28, 2026, Saris announced a $28.8M USD Series A to scale its agentic workflow platform for banks and credit unions. 8VC led the round, with participation from Audacious Ventures, Homebrew, Btech Consortium, and Service Ventures. Saris builds AI agents for lending, compliance, and operations, where financial institutions still spend staff time on document review, data validation, exception handling, and repetitive back office work.
Saris is a Canadian and US based AI fintech, not a Canada only vendor. The company’s hiring page describes a Canada and US hiring footprint, with hybrid workspace options in Montréal, Toronto, and San Francisco. This affects the business model. Saris can draw from Canadian AI and fintech talent while selling into the larger US banking market, where 8VC and enterprise partners can help open doors.
The Canadian link also sits in the founder story. Danial Jameel, Alice Dinu, and James Dang previously built Oohlala Mobile, later Ready Education, which Y Combinator lists in its Summer 2016 batch with a Montréal location. That history gives Saris a stronger base than a typical first time AI startup. Selling workflow software into regulated institutions takes trust, implementation discipline, and patience.
Saris now has more capital to compete in the US banking market, deepen integrations with Fiserv, Encompass, and MeridianLink, and grow the team that trains and deploys its AI agents. The strategic question for Canada is how much of that growth, talent, and customer expansion stays connected to the domestic fintech ecosystem.
Saris trains agents on each institution’s workflows and systems, then applies them to repeatable tasks across lending and operations under human supervision. Based on company reported figures, Saris’ agentic workflows automate up to 70% of consumer, mortgage, and commercial lending tasks and reduce costs by up to 35%. The platform also more than doubles output without adding headcount.
MeridianLink’s partner page says Saris works directly inside MeridianLink to automate document review, field validation, discrepancy remediation, post closing QA, and fraud alert resolution across consumer lending, DL4, and quality control workflows. MeridianLink also reports 99.8% field accuracy, 10x faster file review, and 3x underwriter and loan officer capacity, with one customer clearing a 600 loan backlog in four days.
So how does Saris stack up to competitors. Its target market extends beyond Canadian financial institutions, and its product fits banks and credit unions that already use systems such as Fiserv, Encompass, and MeridianLink.
US founded nCino brings global platform scale. More than 2,700 customers globally use nCino’s platform, including enterprise banks, regional banks, community banks, credit unions, challenger banks, building societies, and independent mortgage banks. That scale gives nCino a distribution advantage with institutions that want a broad cloud banking platform across lending, account opening, portfolio workflows, and customer engagement.
Saris does not need to replace the full operating platform. Its opening is file review, document checks, exception handling, and throughput inside systems institutions already use. That gives Saris a more focused sale where banks and credit unions already run core platforms or loan origination systems but still rely on staff to clear repetitive work.
Canadian based thirdstream is more domestic and onboarding focused. More than 50 financial institutions use thirdstream’s onboarding platform, including banks, credit unions, brokerages, and trust companies. Its strength is in Canadian account origination, identity verification, automated decisioning, real time account funding, and document management.
Toronto based Boss Insights sits closer to lending data infrastructure. Its platform gives financial institutions business lending data infrastructure across accounting, sales, banking, payroll, tax, analytics, monitoring, and customer portal capabilities. Boss Insights lists 1 API and 1,000 plus integrations, which places it closer to open finance, borrower data, and commercial lending intelligence than Saris’ document and workflow automation layer.
Saris looks strongest where banks and credit unions want targeted AI automation without a full platform replacement. Saris can draw from Canadian talent and a Montréal founder history while selling into larger US banking budgets. The question is whether customer relationships, implementation teams, and product leadership stay connected to Canada as the company grows.
Danial Jameel, cofounder and CEO of Saris:
“Our vision is a future where humans and AI work side by side in financial services.”
Saris’ raise shows financial AI moving into the parts of banking where cost, controls, and customer turnaround times get measured. AI can lower operating costs, but financial firms still need evidence that models remain fair, secure, monitored, and accountable. That operating pressure also runs through AI compliance and governance costs.
Should Canadian AI funding and fintech policy focus more on regulated proof points inside banks, credit unions, payments, lending, compliance, and capital markets rather than broad AI adoption metrics?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
