




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 4, 2026 | NCFA Insight | Digital Identity And Trust, Digital Assets Blockchain And Tokenization, Regulation And Policy
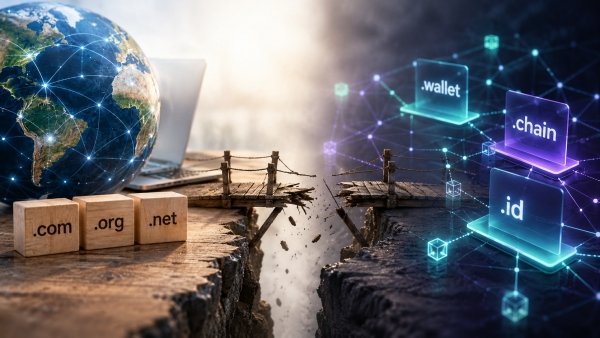
On August 10, 2026, ICANN opened a consultation on alternative naming systems that could affect how blockchain based and other naming systems work alongside the global Domain Name System. Comments are open until September 21, 2026 at 23:59 UTC.
ICANN is the nonprofit organization that coordinates the global Domain Name System, including the rules for top level domains such as .com, .org and newer gTLDs. The consultation matters most to domain registries, Web3 naming providers, digital identity firms, wallet and payment companies, cybersecurity specialists and brands that could be affected if the same name appears across multiple naming systems.
ICANN is dealing with a problem that did not exist when the DNS was designed. Alternative naming systems can create names outside the global DNS, while registry operators and potential applicants in the 2026 New gTLD Program are now interested in using some of the same top level strings in both systems. If that happens, users need confidence that the same name is controlled by the same party wherever they encounter it.
ICANN has not approved a general integration model. Its Technical Study Group is testing whether the same gTLD string can operate in both the DNS and an alternative naming system without creating unacceptable security or stability problems. The current consultation asks whether the proposed technical requirements are strong enough.
The report focuses on what ICANN calls string+controller integration. In plain language, if the same name appears in both systems, the same party should control it in both. That relationship also has to remain intact when names are registered, transferred, suspended, expire or change hands.
That becomes especially important when a name is used for identity, wallets, payments or other digital services. A human readable name only helps if users can trust who is behind it. If control changes in one system but not the other, the same looking name could point to different parties.
For fintech and digital asset firms, the risk is less about domain mechanics and more about mistaken identity. A wallet name, payment identifier or digital identity and authorization system can become easier to use, but also easier to misunderstand if two systems recognize the same string without keeping ownership aligned.
Several registry operators and potential 2026 round applicants have already asked ICANN about this kind of integration. Reviewing similar technical questions one application at a time could become expensive and slow, particularly when requests are referred for additional technical review.
The Technical Study Group was created to develop common requirements that future applicants could work from. That would not guarantee approval, but it could make the process more predictable for registries deciding whether to build services that connect conventional domains with alternative naming systems.
The consultation also comes before another policy step. ICANN says proposed registry agreement language related to these services will be published for a separate public consultation. Comments submitted now can still affect the technical work before those contractual terms are finalized.
For domain registries, Web3 naming providers, digital identity firms, cybersecurity specialists, wallet providers and affected brands, the practical questions are already clear.
Should the same party always control both versions of a name? What happens if ownership changes in only one system? And what safeguards are needed so users can tell who they are actually dealing with?
Comments close September 21, 2026 at 23:59 UTC. Affected stakeholders can submit input directly to ICANN before the deadline.
Can the same name work across two systems without creating confusion over who controls it?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 4, 2026
What is Web3 gaming? It is a broad category of games that use a blockchain for some part of ownership, trading, identity, governance, or the game economy. A player might hold an item in a wallet rather than only in a publisher database. That feature can create new forms of portability and coordination, but it can also add wallets, fees, scams, volatile assets, and irreversible mistakes to an activity many people expect to be simple entertainment.
This guide is for players, researchers, and editors trying to understand what a Web3 label means in practice. It explains what may be on-chain, what remains controlled by the publisher, and how to evaluate the trade-offs before spending time or money. It does not rank games, recommend tokens or collectibles, or provide investment advice.
Web3 gaming is not an all-or-nothing category. A project may put a collection of items on-chain while keeping the game server, combat rules, moderation, and progression system centralized. Another may use a token for governance but keep all gameplay data in a conventional database. The useful question is not whether a game uses a blockchain somewhere; it is which part of the player experience is actually controlled by the player or verified by a public network. For a concise foundation, what is web3 gaming is best answered by mapping those specific functions instead of treating the label as a genre.
| Game element | Common Web2 approach | Possible Web3 approach | Question for a player |
| Items | Recorded in the publisher database | Some items represented by tokens in a wallet | What rights does the token actually grant? |
| Payments | Publisher controls in-game currency | Tokens or NFTs can be transferred externally | What are the fees and exit options? |
| Identity | Login managed by the publisher | Wallet-based identity, sometimes combined with login | What happens if the wallet is lost? |
| Governance | Publisher sets rules and content | Token or community voting covers selected decisions | Which decisions are truly subject to a vote? |
| Continuity | Access depends on the game service | Some assets may remain visible if one interface changes | Does the item still have utility without the original game? |
The word "ownership" also needs precision. Holding an NFT usually means controlling a token record under a contract's rules. It does not automatically grant copyright, a trademark license, access to a server, a guaranteed use in another game, or a right to future development. Those rights may be defined by a license, terms of service, or a separate account system.
An on-chain item can sit outside one account database and be transferred under the token's rules. That may support a secondary market, a player identity, or a collection that is visible across tools. Portability is only useful when another game or service recognizes the asset and knows what its data means. A transferable item with no compatible use is ownership in a narrow technical sense, not automatic utility.
Public transaction records can also make parts of an economy easier to inspect. A reader may be able to observe supply, wallet concentration, transfers, or selected contract rules. This can improve transparency, but it does not make the economy fair by itself. A contract may still be upgradeable, a marketplace may control the interface, and important gameplay data may remain private.
Governance tokens can give players a voice over selected decisions. In practice, voting power may be concentrated among large holders, delegated to a small group, or limited to parameters that do not affect the core experience. Ask what the vote can change, who can propose it, and whether the result is binding. A vote count is not the same as meaningful player control.
Token incentives may create new funding or creator models, but they also change the audience's motivation. A player who wants a game may be competing with participants focused on item resale or token appreciation. That can make prices, participation, and community behavior more volatile than the gameplay itself.
Web3 features add operational steps. A player may need a wallet, a network choice, a transaction fee, an approval, and a marketplace account. Each step creates room for a wrong address, fake link, private-key theft, or an irreversible signature. A custodial onboarding flow can reduce some friction while increasing dependence on the provider. Neither model removes the need to understand what an action authorizes.
Transaction economics can also change the value of an item. Consider a deliberately simple example: a player buys a $20 item, pays a $3 network fee, and later pays a 5% marketplace fee to sell at the same nominal price. The sale returns about $16 before any price change or tax. The arithmetic is not a forecast; it shows why displayed item prices do not equal the amount a player can recover.
Liquidity is another constraint. A marketplace floor is an asking price, not a guaranteed buyer. When interest fades, the highest visible listing may be far above the price at which a sale would actually clear. A token can lose liquidity while the game remains playable, and the reverse can happen as well. Treat marketability as a separate question from entertainment value.
Smart contracts, bridges, marketplaces, and game servers can fail independently. An on-chain item may remain visible in a wallet while the game that gave it meaning shuts down, changes its rules, or removes its server access. A blockchain record can persist while practical utility disappears. This is why "you own the asset" is not a complete explanation of the player outcome.
Use the following sequence to separate a playable product from a token pitch:
This framework keeps the article's central question in view: does the on-chain feature improve the player experience enough to justify its added complexity? A game can be legitimate and still not suit a particular player. The decision should depend on the experience and rights, not on the label alone.
Market context can help explain why a game token is attracting attention, but it cannot measure whether the game is well designed. A token that appears among crypto market gainers may be reacting to a listing, a partnership announcement, thin liquidity, or speculative positioning. The ranking is a prompt to investigate the event and the market structure, not proof that players are adopting the game.
Check the pair, quote currency, time window, volume, and available liquidity before drawing a conclusion. A large percentage move in a shallow market may represent a small amount of capital. Conversely, strong player activity may not immediately appear in a token ranking if the project uses a custodial economy or has no liquid token. Keep game research and market research as related but distinct tasks.
The same distinction applies to community sentiment. A crowded chat can show that a launch is visible, not that the product is sustainable. Look for retention, repeat play, clear updates, and evidence that the economy works for ordinary players. If the only durable demand appears to come from recruiting new buyers, market risk may be replacing game design.
Web3 gaming is best understood as a bundle of design choices rather than a single genre. The same project can offer genuine player ownership in one area while retaining centralized control in another. Rights, fees, wallet security, server access, and token liquidity vary by project and jurisdiction. Read the game's terms, marketplace rules, and wallet prompts before making a consequential decision.
Not always. Some games offer custodial accounts, free starter items, or sponsored transactions. Others require a wallet and network fees. Check the actual onboarding flow instead of assuming the label tells you what is required.
No. You may control the token record while the publisher controls the game, servers, trademarks, and utility. The rights depend on the contract and the project's terms.
Only if the other game chooses to recognize the asset and can interpret its data. On-chain transferability does not create automatic gameplay compatibility.
They can expose a player to market risk, but a token or item is not automatically a sound investment. Prices, liquidity, fees, and utility can change, and the purchase may be better treated as entertainment or speculation.
What is Web3 gaming? It is gaming with selected ownership, payment, identity, governance, or economy functions connected to blockchain systems. The meaningful analysis is not how many tokens a project issues, but what the player can actually control, transfer, use, and recover.
Play the core game, map the control boundaries, calculate the friction, and test what survives when prices stop rising. That approach keeps technology in perspective and leaves room to enjoy a game without mistaking a market narrative for a guarantee.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
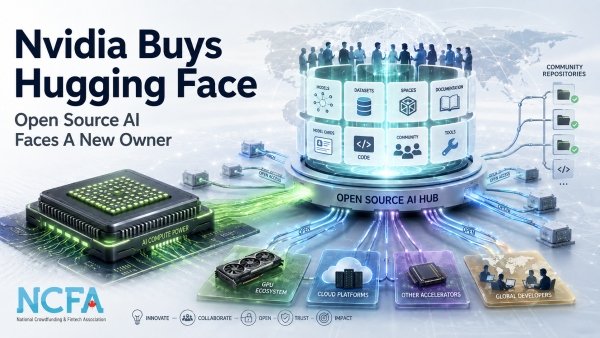
On September 3, 2026, Nvidia announced a definitive agreement to acquire Hugging Face for US$12.9303 billion. The deal would put one of the biggest platforms for open source and open weight AI alongside the company that already dominates much of the market for AI computing.
The price includes about US$11.9 billion for Hugging Face stockholders and up to US$1 billion in equity awards for employees joining Nvidia. The transaction hasn't closed. Nvidia says it expects completion in the first half of 2027, subject to regulatory approvals and other closing conditions.
Nvidia is making a very public promise with the deal. Hugging Face will remain open. Developers will still be able to choose their models, clouds, inference providers and computing platforms. Nvidia hardware will not be required.
That promise goes directly to the tension. Hugging Face became valuable because developers, startups, researchers and rival chip companies could all build there. Nvidia can make that ecosystem stronger. Ownership can also make some of those same users wonder whether an open source AI platform can feel as independent once one of the most powerful companies in AI owns it.
Hugging Face has grown into one of the main places developers find, share and use open AI models. Nvidia says more than 18 million developers, researchers and creators use the platform, along with more than 200,000 companies.
The company was worth far less only three years ago. Hugging Face raised US$235 million in 2023 at a US$4.5 billion valuation, with investors including Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Salesforce.
Nvidia is now paying close to three times that valuation. The premium makes more sense when Hugging Face is viewed as distribution, developer access and influence over how open models get discovered and deployed.
Hugging Face is valuable because millions of people already use it to decide what to build with. Nvidia is buying that relationship as much as the software behind it. The more developers stay, the more valuable the acquisition becomes.
Nvidia already has enormous power in AI computing. Reuters Breakingviews says Nvidia holds more than 80% of the AI accelerator market, while its chips have become a reference point for a growing market in GPU rental pricing.
That power is one reason the acquisition attracts attention. Nvidia will own a major open model platform while selling the hardware many of those models run on.
Hugging Face has also become important to Nvidia's competitors. Its own 2026 data says AMD and Nvidia are the two most active publishers of new open models on the Hub, with each releasing more than 200 model repositories this year.
AMD uses open models to prove its chips can run real workloads. Google, Microsoft, IBM and other companies also publish and distribute models through the platform.
The acquisition does not remove AMD, Google or other hardware and cloud providers from Hugging Face. Nvidia says support for rival silicon will continue. The tension comes from whether those companies remain just as comfortable investing there when the owner also competes with them.
Nvidia says rival chips will stay welcome. Nvidia's CEO Jensen Huang says developers will keep choosing their own models, frameworks, clouds, inference providers and computing platforms. Nvidia compute will not be required to build on or deploy through Hugging Face.
Developers are already debating what ownership could mean in practice. Some community reactions welcome Nvidia because open models create demand for compute. Others worry about future defaults, private repositories, hardware preference and whether another independent open source AI platform will eventually be needed.
Nvidia doesn't have to close Hugging Face for ownership to change how the platform feels. Developers will notice which hardware gets optimized first, which services are easiest to connect and whether rival products remain equally visible and easy to use.
Open models fit Nvidia's economics surprisingly well. Hugging Face says hardware vendors are publishing open models because a model optimized for their chips is one of the clearest ways to prove the hardware works.
Nvidia can therefore benefit even when the model itself is free to download. More open model use can create more inference and training demand across data centres, enterprises and local machines.
That dependence cuts both ways. Some of Nvidia's biggest customers, including hyperscalers and AI labs, are building their own chips. The Hugging Face deal gives Nvidia a wider developer base at a time when those customers are trying to reduce their own dependence on Nvidia hardware.
Open source AI gives Nvidia access to thousands of smaller users instead of relying only on a few giant buyers.
Nvidia can support open source AI and still benefit commercially from its growth. The company does not need every developer to buy a proprietary Nvidia model. It benefits when more models create more computing demand.
China is pushing hard in the same open model market. Hugging Face data shows Chinese labs released many of the largest open models in 2026. Qwen has become one of the most important model families on the Hub, with more than 151,000 derivative repositories.
Hugging Face says Qwen based models reached more than 2 billion downloads across repositories with declared parameter counts this year.
Chinese open models are also competing on access and cost. Hugging Face found that 59% of Chinese releases above 20 billion parameters used Apache 2.0 licences and another 22% used MIT licences during the period it studied, although some very large releases have begun adding commercial restrictions.
That gives developers another source of capable models as U.S. companies debate how open their own ecosystems should remain.
Open models are part of the technology rivalry between the United States and China. Nvidia's Hugging Face acquisition gives a U.S. company more influence over a global platform at the same time Chinese model families are winning large developer communities of their own.
One possible response to Nvidia ownership is that developers simply stay. Hugging Face already has millions of models, datasets, applications and established workflows. Rebuilding that network somewhere else would be difficult.
Microsoft's GitHub acquisition offers one useful precedent. Microsoft promised GitHub would stay open and independent, and competing developers and platforms continued using it after the acquisition.
Another possibility is that developers begin spreading their work across more places. ModelScope, GitHub, local model tools, cloud registries and private enterprise repositories already give users alternatives for parts of the Hugging Face experience.
A future competitor would not need to copy every Hugging Face feature on day one. It could win users by offering easier migration, open governance, strong model provenance or a clearer commitment to hardware independence.
Network effects make a full replacement difficult, but communities can fragment before platforms collapse. Developers can keep models on Hugging Face while using other tools for discovery, inference, deployment or discussion. Competition may arrive piece by piece rather than through one new platform.
No price increase has been announced. Nvidia says Hugging Face will remain open and hardware choice will continue. That leaves plenty of room for the acquisition to improve reliability, inference tools and enterprise deployment without raising basic access costs.
Costs could still change indirectly. Developers may pay more if the easiest experience ends up depending on premium services, Nvidia optimized infrastructure or harder to replace integrations. The opposite is also possible. Better tooling and stronger open models could lower the cost of running AI compared with closed model APIs.
The acquisition does not automatically mean higher prices. The more interesting cost risk is switching. A service can remain affordable while becoming expensive to leave because models, workflows, integrations and teams are built around it.
Startups could gain from Nvidia's reach. A stronger Hugging Face can give model companies better distribution, more reliable infrastructure and easier access to enterprise customers.
For founders trying to get an open model discovered, being close to a platform used by 18 million developers can be commercially powerful.
Startups may also have less bargaining power if distribution, compute and enterprise access become more concentrated around the same company. A startup can benefit from the platform while still wanting credible ways to deploy elsewhere.
That tension is already visible in competition for cheaper AI inference, where AMD and other hardware companies are trying to give developers alternatives to Nvidia's dominant GPU position.
The upside is distribution. The risk is dependence. Founders will care less about who owns Hugging Face than whether they can still take their models, customers and economics somewhere else when they need to.
Financial institutions face the same ownership question from a different angle. Banks and insurers are already putting AI into governed workflows where data controls, approvals, audit evidence and operational resilience are required.
Governed financial AI workflows become harder when a firm cannot easily change models, clouds or providers without rebuilding controls around them.
Portability can therefore matter more than ownership alone. A bank may be comfortable using Hugging Face under Nvidia if models can still travel across clouds and chips and the institution can keep its own data, controls and audit evidence.
Regulators are also paying more attention to AI vendor concentration and operational dependence as financial firms embed more external technology into critical work.
Financial institutions do not need every AI supplier to be independent. They do need credible ways to change suppliers, hardware and deployment environments without losing control of regulated workflows.
The deal could still produce a strong outcome for open source AI. Nvidia has the engineering resources, compute and enterprise distribution to make Hugging Face faster, more reliable and easier for companies to use.
If AMD, Google, cloud providers, Chinese model labs and independent developers keep contributing, Nvidia can own the platform while the ecosystem remains genuinely competitive.
The harder outcome is quieter. Hugging Face stays open, but developers gradually find Nvidia products easier, cheaper or better supported than alternatives. No door closes. Choice simply becomes less balanced over time.
That is why Nvidia's promise will be judged through product behaviour rather than the announcement itself.
The most valuable version of Hugging Face may be one where Nvidia owns it and its competitors still want to build there. If that happens, Nvidia gets a larger open source AI ecosystem without destroying the trust that made the platform worth almost US$13 billion.
Talking Point
Nvidia does not need to close Hugging Face to gain more influence over open source AI. The deal becomes more valuable if developers, startups and rival chipmakers keep using the platform anyway.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Activity | Digital Banking And BaaS, Regulation And Policy, Payments Infrastructure And Money Movement
On September 3, 2026, Revolut received conditional U.S. bank approval from the Office of the Comptroller of the Currency form Revolut Bank US, N.A., a federally chartered national bank headquartered in Stamford, Connecticut. Revolut says it is still working through FDIC, Federal Reserve and final OCC approvals and remains on track for a 2027 launch. U.S. customers cannot open accounts with Revolut Bank US yet.
Revolut already serves U.S. customers, but the regulated banking are with other institutions. Lead Bank supports Revolut's prepaid card accounts and banking services, while Savings Vault funds are held at Cross River Bank. Revolut controls the app and customer experience, but those partner banks hold deposits and perform key regulated functions.
Revolut says the proposed bank would offer loans, credit cards and FDIC insured deposits, alongside access to stablecoins and cryptocurrencies. Its charter application also describes deposits, savings, business credit, payments, remittances and foreign exchange. Some investment and digital asset services could still sit with affiliates or outside providers rather than inside the bank itself.
Revolut has been working toward this for months. It dropped plans to buy a U.S. bank earlier this year and chose to apply for a new national bank instead. The OCC received the Revolut Bank US application on March 4. Conditional approval six months later gets the company much closer to owning the bank behind its U.S. app.
Today, Revolut can build the app, price subscriptions and design much of the customer experience, but it still depends on banks such as Lead Bank and Cross River Bank for core banking functions. That arrangement helped Revolut enter the U.S. without taking on the full cost of becoming a bank, but it also means product changes, deposit economics and parts of the customer relationship depend on outside institutions.
With its own bank, Revolut could keep more of that customer relationship inside the company. Deposits could sit at Revolut Bank US, lending income could stay within the group and the company could build products without asking a partner bank to support every change. Revolut also says direct access to payment networks such as Fedwire and ACH could make transfers faster and cheaper.
The economics become more interesting at Revolut's current size. Its 2025 financial results included US$6.0 billion in revenue, US$1.7 billion in net profit, US$67.5 billion in customer balances and a US$2.9 billion lending portfolio. Revolut now serves more than 80 million customers worldwide and is adding roughly one million customers every 17 days.
The U.S. opportunity is still much less developed than Revolut's business in Europe and some other markets. A bank charter gives the company a chance to compete for deposits, credit and primary banking relationships rather than mainly offering an app connected to somebody else's bank. Revolut has also committed to invest US$500 million in the U.S. over the next few years as it builds the products and operations around that effort.
Conditional OCC approval is a major regulatory step, but it is not permission to open the bank tomorrow. Revolut still needs FDIC approval for deposit insurance, Federal Reserve approvals for its U.S. holding structure and final OCC clearance. The company also has to finish staffing, capitalization, technology, compliance and operational testing before customers can be moved onto the new bank.
Owning a bank also changes the risk Revolut takes on. A partner bank carries much of the regulated balance sheet today. Revolut Bank US would have to manage its own capital, liquidity, credit losses, consumer compliance, BSA and AML controls, cybersecurity, governance and federal examinations.
Lending makes that especially real. A payments app can process money without taking the same credit risk as a bank making personal or business loans. Once Revolut starts lending from its own balance sheet, growth has to be backed by sound underwriting, reserves, collections and enough capital to absorb losses when borrowers struggle.
The company is already building that structure though. Its application calls for a separate U.S. bank board and senior executives responsible for finance, risk, compliance, legal, lending and operations. Revolut says it remains on track for 2027, but the launch date still depends on regulators being satisfied that the bank is ready to operate safely.
Revolut's first Canadian attempt ended very differently. The company launched a limited beta in 2019 and left Canada in 2021 without establishing a domestic bank. The earlier product was much narrower than the banking business Revolut now operates in several markets.
Jan Pilbauer now leads Revolut Canada, and Revolut has described the market as attractive, but there is still no announced launch date or public Canadian bank licence application. A U.S. national bank charter certainly doesn't give Revolut permission to take deposits or operate a bank in Canada.
If Revolut does return, it would arrive as a much larger and more regulated company than the one that left five years ago. It now operates licensed banks in multiple countries, carries a growing lending book and is building local banking operations rather than relying only on cards and foreign exchange. Canada has also changed, with OSFI's streamlined approvals framework giving eligible new entrants a clearer federal application process.
None of that means a Canadian relaunch is close. It does mean the next attempt, if it happens, could look much more like a full digital bank than the limited product Revolut tested here before.
Revolut is now trying to do something large fintechs often avoid for as long as they can it seems. That is to own a regulated bank, the deposits, the lending and more of the customer economics. That can produce more revenue and more control, but it also means the compliance failures, credit losses and funding mistakes belong to Revolut too.
How much more can Revolut earn when it owns the bank behind the app?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
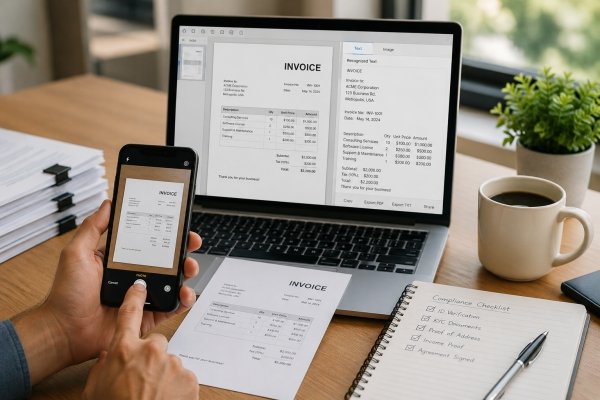
Anyone who has onboarded a client at a fintech startup knows the bottleneck. The product works, the API integration is done, and then someone emails a photo of a passport taken at an angle in bad light, with half the machine-readable zone cut off. Multiply that by fifty applicants a week and your compliance queue turns into a photo-editing job.
Small lenders, brokerages and crypto exchanges all hit the same wall. Identity verification and record-keeping are document-heavy by law, and the documents arrive in whatever format the customer's phone produced.
That is the gap a mobile scanner fills. OKEN, listed on the Play Store under the longer name OKEN - camscanner, pdf scanner and published under the name CAMBYTE Pte. Ltd., is a Productivity app that turns a phone camera into a document scanner with edge detection, OCR text recognition, and export to PDF, JPG, Word or TXT. It also reads QR codes, which matters more than it sounds in a payments context.
The core loop is straightforward. Point the camera at a page, let the app find the borders, and it flattens the perspective into something that looks like it came off a flatbed scanner rather than a kitchen table.
OCR is where the finance use case gets interesting. A scanned invoice or ID page that carries a searchable text layer can be indexed, queried and pulled up during an audit without anyone flipping through image files. A scan without OCR is just a picture of information.
The format range is the practical part for anyone assembling a client file:
The store listing pitches it at students and small business people, accountants, realtors and managers. That is a fair description of who benefits most: teams too small to own scanning hardware but still accountable for the same paper trail as the big institutions.
Phone scanning is fine for capture. It stops being fine at the point where you have thirty scanned pages sitting on a handset and a Windows machine holding your CRM, your case management system, and the shared drive your auditor actually looks at.
That handoff moment is usually why people start looking at OKEN scanner for PC rather than sticking with the phone alone. On a desktop, the app runs inside an Android emulator, and the exported PDFs land somewhere your other software can reach.
Most emulator advice is generic. For a scanner app, only a couple of things really change the experience.
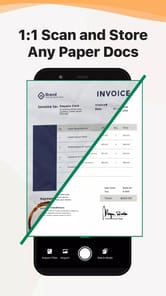
Batch OCR is noticeably more comfortable on a large monitor. Correcting a misread account number in a recognized text layer is tedious on a 6-inch screen and fast with a keyboard.
Treat the app as capture and formatting, not as verification. OKEN produces a clean, readable, searchable document. It does not authenticate an identity document, check it against a sanctions list, or satisfy any regulator on its own.
For internal paperwork, supplier invoices, signed agreements and expense records, that distinction barely matters. For customer identity files it matters a great deal, and the scanner should sit in front of a proper verification provider rather than in place of one.
One caveat worth carrying away: scanned identity documents are among the most sensitive files a small firm will ever hold. If you run the app on a shared office desktop through an emulator, the exported PDFs live in a Windows folder that anyone with access to that machine can open. Decide who that is before the first scan, not after.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 3, 2026 | NCFA Market Interest | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Wealth Investing And Trading
Kraken parent Payward has reportedly delayed its U.S. IPO again, this time to the second quarter of 2027 at the earliest. The company confidentially filed a draft registration statement in November 2025, then put the listing on hold in March as crypto prices, trading volumes and valuations weakened. Payward hasn't confirmed the new 2027 timing, so it remains a reported window rather than a scheduled IPO date.
The delay comes at an interesting point for the business. Payward reported US$508 million in Q2 adjusted revenue, up 17% year over year. Funded accounts rose 42% to 6.6 million, while assets on the platform were US$40 billion. Adjusted EBITDA was much thinner at US$23 million, and total platform transaction volume fell 18% to US$310 billion as crypto spot trading cooled.
Those numbers give Payward a pretty clear reason to wait. Revenue and customers are growing, but the company is still proving how much earnings it can generate when trading activity softens. Going public now would put that question in front of investors every quarter.
Kraken is still central to Payward, but the parent company now earns money from more than crypto spot trades. Asset based and other revenue accounted for 60% of adjusted revenue in Q2, up from 55% a year earlier. Payward also owns NinjaTrader, has added regulated U.S. derivatives through Bitnomial, and expanded into payments and card issuing through Reap.
Those businesses and revenue lines are important when trading slows. Payward's transaction volume fell 18% year over year, yet adjusted revenue still rose 17%. That doesn't make the company immune to crypto cycles, but it does show that the revenue mix is changing.
The acquisitions have also made Payward more complicated. Investors eventually have to decide whether futures, derivatives, payments, tokenized equities and infrastructure services add up to a stronger financial business or simply a larger collection of products. Staying private gives management more time to answer that with operating results.
Payward's recent transactions have valued its equity at about US$20 billion. The company also says it closed an US$800 million private funding round backed by investors including Citadel Securities, Jane Street, Oppenheimer and Tribe Capital.
The capital gives Payward capital and time, but the valuation also raises expectations for an eventual IPO. Public investors will want to see more than account growth. They will be looking at earnings, cash generation, trading volumes and whether the businesses Payward has bought can produce dependable revenue together.
The current quarter gives them both sides of the argument. A record 6.6 million funded accounts and 17% revenue growth are strong. US$23 million of adjusted EBITDA on US$508 million of adjusted revenue leaves much more room to prove that scale can turn into profit.
Payward's xStocks business is expanding beyond Kraken. xStocks distribution already reaches third party exchanges, wallets and blockchain applications, and Payward now says the products have passed US$40 billion in total volume, including more than US$20 billion settled onchain, across more than 200,000 holders.
The company took another step on September 1 when LSEG and Payward announced plans to explore tokenized UK public equities. Subject to regulatory approval, the London Stock Exchange intends to list xStocks on its planned LSE 24 venue in 2027.
If everything takes, that would put Payward beside a traditional exchange operator at the same time its own IPO waits. It is a good example of how far the company has travelled from being known mainly as a crypto exchange.
The biggest question is earnings. Payward can keep adding accounts and products, but public investors will want to see whether those businesses can produce stronger profits when crypto trading is weak. Q2 showed that revenue can keep growing while transaction volume falls. The next step is showing that more of that revenue reaches the bottom line.
The acquisitions also have to work together. NinjaTrader brings traditional futures clients. Bitnomial adds regulated U.S. derivatives. Reap adds payments and card issuing. xStocks adds tokenized equities. Payward Services sells some of the same technology to banks, fintechs and other platforms. If customers start using several of those products together, the company can earn more from each relationship without depending as heavily on one trading market.
Payward Canada is registered as a restricted dealer, giving Kraken regulated access across Canada. xStocks are still unavailable to Canadian retail clients, so Payward's wider product expansion won't automatically arrive here. Canadian access will depend on what regulators approve and which products the company decides to bring north.
Payward has private capital, growing accounts and several businesses still being integrated. It doesn't have to accept a public valuation today if management believes another year of results can support a better one.
There is risk in waiting too. Crypto markets can weaken further, acquisitions can disappoint and the IPO market may not improve on Payward's schedule. A private US$20 billion valuation is only as strong as the earnings and growth the company can eventually show public investors.
Kraken's IPO delay is therefore more than a calendar change. Payward is using the extra time to prove that it can grow into a larger financial platform, make its acquisitions pay off and earn enough outside crypto spot trading to support the valuation it wants when it finally lists.
Can Payward turn product growth into enough profit to support a US$20 billion public valuation?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
On September 3, 2026, Canada's July trade report put two stories beside each other. Exports to the United States fell 6.6%, while exports to countries outside the U.S. rose 7.4% to a record C$25.6 billion. Canada's merchandise trade surplus with the world narrowed from C$4.2 billion in June to C$769 million. Its surplus with the United States fell from C$10.3 billion to C$5.9 billion.
Those numbers now sit inside a much rougher political relationship. On August 22, the United States imposed a 50% tariff on roughly US$20 billion of Canadian exports, while the Government of Canada values the affected goods at C$27.6 billion. Canada has rejected the terms on offer and announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
Canada is still deeply tied to the U.S. economy, but the reaction is no longer confined to government. Buy Canadian sentiment has returned. Companies are reviewing suppliers and customers. Travel choices have changed. More Canadian businesses are looking beyond the U.S. at the same time that Ottawa is asking them to absorb the cost of doing it.
The question running through this story is whether the tariff fight is merely disrupting Canada U.S. trade or helping create commercial relationships that remain different even after the politics cool.
The evolving trade war began with a border argument. Washington said Canada was not doing enough on fentanyl and border security. Ottawa said the scale of the problem did not justify an economy wide tariff and answered with retaliation rather than concession.
Ottawa disputed the premise while tightening the border anyway. Canada argued that the U.S. was imposing an economic penalty far larger than the border problem it cited. At the same time, Ottawa strengthened enforcement, giving the fight an early contradiction that never really disappeared.
North America already has a trade agreement designed to make cross border commerce predictable. The surprise is not that Canada and the U.S. disagree. It is that the disagreement can still produce sweeping tariffs while CUSMA remains in force.
CUSMA then became the shield Canadian companies hoped it would be. A large share of continental trade kept moving under the agreement, offering businesses a degree of protection from the broad tariff threat.
The most politically sensitive sectors did not get the same protection. Steel, aluminum and autos became proof that a trade agreement could survive while the industries most tied to jobs, factories and regional politics still took direct hits.
CUSMA remains in place, but businesses now know that compliance with the agreement does not eliminate every tariff risk. A company can remain inside the North American trade framework and still be exposed to a separate sector fight.
Canada entered the 2026 CUSMA review looking for certainty and left without it. Ottawa wanted companies to know the North American rules would hold for another generation of investment. The review did not deliver that reassurance.
The United States did not give Canada the long runway it wanted. The agreement stayed alive, but companies making plant, supplier and capital decisions measured in years were left with a shorter political horizon.
The agreement remains in force. But the failed long term extension means companies can no longer assume the relationship will simply return to the old operating model after one review.
Then the tariff ceiling moved again. After bilateral talks failed, Washington raised the pressure to levels that made another Canadian response almost unavoidable. The dispute was no longer about whether tariffs would remain. It was about how much economic pain each side was willing to absorb.
Canada chose retaliation over the deal on the table. Ottawa said the U.S. terms would leave Canadian workers and businesses worse off. Canada announced matching counter tariffs on C$27.6 billion of U.S. imports, scheduled to take effect on September 8.
This is where the fight stops looking like a temporary tariff negotiation and starts looking like a choice about economic autonomy. Canada is accepting the risk of another round of costs rather than take terms Ottawa says would leave important industries worse off.
Trump then turned Lake Ontario into part of the dispute. The Lake America order gave Canadians something more visceral than a tariff table to react to. A fight over market access suddenly had a symbol that touched geography, identity and sovereignty.
The symbolism hit a country already primed to push back. The tariff fight had been accompanied by statehood rhetoric and repeated claims that Canada depended too heavily on the United States. The lake renaming made the argument feel less like a dispute over customs schedules and more like a challenge to Canadian identity.
A tariff can feel remote until it affects a price, a contract or a job. Renaming a shared Canadian lake for U.S. federal purposes created a cultural symbol that was easier to understand and harder to separate from the wider sovereignty argument.
Canadian resistance is showing up in everyday choices. Buy Canadian sentiment has strengthened as consumers reconsider groceries, travel, technology, vehicles and other purchases. Businesses are also reviewing where they source products and whether U.S. dependence still looks commercially sensible.
American opinion is much less supportive of the escalation. A Reuters Ipsos poll found 57% of Americans opposed the latest tariffs on Canada and only 20% supported them. The same poll found 63% opposed Lake America and 14% supported it.
Canadian patriotism has many sources, so the tariffs should not be treated as the sole cause. But the observable response to repeated tariff threats, statehood rhetoric and Lake America includes stronger Buy Canadian behaviour, support for retaliation and a more explicit case for economic self reliance.
Some companies are acting on the anger instead of waiting it out. Reuters reported that Chapman's Ice Cream plans to cut U.S. imports by 70% by mid 2027. Other firms are reviewing suppliers, sourcing more at home and looking for customers outside the United States.
Once a supplier is replaced, politics may not put the old relationship back together. New contracts, certifications, logistics routes and internal processes create switching costs. A future agreement could remove a tariff quickly while leaving behind commercial relationships built during the dispute.
This is where a patriotic reaction can become structural economic change. The first purchase may be emotional. The lasting effect depends on whether Canadian and non U.S. alternatives become good enough to keep the customer or supplier relationship after the anger fades.
The July numbers show Canada really is looking elsewhere. Exports outside the United States rose 7.4% to a record C$25.6 billion. Non U.S. destinations accounted for roughly one third of Canadian merchandise exports in July.
America is still too large to replace quickly. Canada's trade surplus with the U.S. fell to C$5.9 billion in July, while Canada ran a C$5.1 billion deficit with countries outside the U.S. More trade elsewhere reduces concentration before it replaces the commercial value of the American market.
The record non U.S. export figure shows diversification was already underway before the August 22 escalation. It does not prove the newest tariffs caused the change. It does show Canada was already finding more business outside the U.S., even while the American market remained too large to replace quickly.
There is also a cost to weakening the North American relationship itself. In a September PBS NewsHour discussion, former U.S. Trade Representative Robert Zoellick argued that the original logic of North American economic integration went well beyond lower tariffs and prices. Combining Canadian, U.S. and Mexican minerals, energy, manufacturing, supply chains and services made all three countries stronger competitors globally. The PBS discussion raises a larger question for both countries: how much competitive strength does North America give up when an integrated economic relationship becomes a zero sum fight?
Every new route creates another bill before it creates resilience. New buyers can require longer shipping, different payment terms, more foreign exchange and more working capital. New suppliers can require deposits, inventory changes and fresh credit checks. The cost arrives before the exporter knows whether the new relationship can match the economics of the old one.
Canada can become less exposed to one market while making individual companies more complicated to finance. Diversification works only if firms have enough liquidity to survive the period between leaving an old relationship and making a new one profitable.
Lenders now have to see tariff risk before the financial statements do. U.S. customer concentration, tariff sensitive inputs, margin exposure and the time needed to replace a buyer can change a borrower's risk within weeks. Historical revenue can therefore look healthy while the economics underneath it are already deteriorating.
Payments, foreign exchange and treasury providers face the opposite problem. More destinations create more currencies, settlement routes, counterparties and cash timing issues. The same diversification that reduces geographic concentration can increase demand for cross border payments, hedging, trade finance, receivables tools and working capital.
Trade policy becomes financial services work once companies start changing customers and suppliers. Credit has to recognize new exposure sooner. Payments have to reach more markets. Treasury teams have to manage more currencies. Working capital has to cover the period before new trade relationships mature.
Markets still assume some of this confrontation eventually fades. Currency forecasts are already looking past the current hostility and pricing a calmer relationship later. Businesses have less freedom to wait for that version of the future.
Businesses cannot wait for that forecast to come true. Carney said on September 1 that the United States must start being serious before talks can resume. At that point no new bilateral negotiations were scheduled. A company choosing a supplier, market or plant location has to make the decision under today's rules.
That is the deeper consequence of the dispute. Governments can reverse tariffs quickly. Companies that have spent months replacing suppliers, winning customers and building payment routes may have less reason to go back. The tariff war could therefore leave a commercial footprint that lasts longer than the tariffs themselves.
Talking Point
Trump's tariff campaign has done more than raise the cost of Canada U.S. trade. It has turned economic dependence into a Canadian political issue, revived Buy Canadian behaviour and pushed companies to look harder for customers and suppliers elsewhere. The unresolved question is whether that response leaves Canada with stronger companies and more durable trade relationships or simply a more expensive way to do business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016