





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Competition | Sep 15, 2025
Image: Freepik/rawpixel.com
On September 15, 2025, Sarah Cardell, Chief Executive of the UK Competition and Markets Authority (CMA), delivered a speech at the BVCA Summit outlining how competition policy can drive investment and scale-ups. This article summarizes the CMA’s takeaways, benchmarks them against Canada’s position, and explores what lessons fintech leaders and policymakers should draw on.
The CMA stressed that long regulatory delays deter investors and can cause promising startups to fail before securing capital. To address this, the CMA introduced new performance indicators to shorten merger review timelines and committed to streamlining processes across its work.
“Delay chills investment and can mean promising startups run out of road.”
Excessive or outdated regulation can create costs and risks that stifle investment and innovation. The CMA promises to act proportionately, weighing costs and benefits carefully, phasing out outdated remedies, and focusing on the issues most relevant to consumers and businesses.
“We will act proportionately and minimise costs wherever we can.”
Uncertainty in regulatory outcomes undermines investor confidence. The CMA is introducing clearer jurisdictional guidance for merger reviews and publishing detailed roadmaps under its new digital markets regime to provide businesses with greater certainty.
“Uncertainty can stall decision-making and weaken business and investor confidence.”
The CMA emphasized the importance of open and direct engagement with stakeholders. It is creating new forums such as the Growth and Investment Council and deploying stakeholder surveys to improve how its policies reflect commercial realities.
“The CMA is more committed than ever to the fundamentals of our role – to promote competition and protect consumers, within an independent regime.”
Measured against the CMA’s framework, below we try to rank how Canada performs for fintech competitiveness and investment.
We can look at the past for data-driven proof that Canadian fintechs face chronic delays that slow capital raising and partnerships. Open banking has missed multiple government deadlines, leaving fintechs and banks without full clarity of the program.
Another example is around payment modernization, particularly the Real Time Rail (RTR) which has also faced repeated setbacks, stalling innovation in faster payments. Let's not forget the creation and rollout of equity crowdfunding rules that took years to harmonize nationally under NI 45-110, meaning startups endured fragmented frameworks for far too long. In an era where global regulators must keep pace with innovation, Canada's slower regulatory pace is a drag on growth.
Overlapping and duplicative rules increase compliance costs disproportionately for startups. Equity crowdfunding portals are a good example. Under National Instrument 45-110, portals must register as restricted dealers, maintain minimum working capital, and comply with know-your-client and suitability requirements similar to investment dealers, even though transaction sizes are capped at $1.5 million per year.
These requirements add legal, audit, and technology costs that are heavy for small portals but don't always provide proportionate consumer protection benefits, since investment limits already restrict retail investor exposure. The result is fewer viable portals, reduced competition, and higher costs for startups seeking to raise capital. Payments firms navigating multiple oversight bodies face similar burdens. Competition Act amendments have broadened investigative powers, but without a clear proportionality test for smaller firms. This creates uncertainty and often deters new entrants.
Canada has stalled on open banking and been inconsistent on payments modernization, leaving both fintechs and banks unsure about what rules to plan around. Licensing and regulatory approaches often lack clear roadmaps, meaning firms cannot anticipate timelines or likely outcomes. This erodes investor confidence at exactly the point when fintechs need greater visibility and confidence support. By contrast, the CMA now publishes roadmaps and consults on jurisdictional thresholds in advance.
Regulators in Canada conduct consultations but feedback loops can be slow and often opaque, discouraging stakeholders from participating. It reminds of a Stephen King quote, "Fool me once, shame on you. Fool me twice, shame on me. Fool me three times, shame on both of us." Stakeholders rarely see how their input affects outcomes.
In fintech licensing and payments reform, firms report long periods of silence, creating uncertainty and wasted preparation costs. Engagement exists but is not structured to produce rapid clarity. The CMA, by contrast, has set up a Growth and Investment Council and targeted outreach to startups, making process improvements measurable and visible.
What further distinguishes the CMA approach is its focus on measurable outcomes. Timelines, KPIs, and stakeholder feedback are built directly into its reform process. In Canada, regulators rarely hold themselves to outcome metrics. Open banking, payments modernization, and fintech licensing all lack clear outcome based benchmarks for success with transparent reporting, leaving startups and investors facing prolonged uncertainty.
Cardell highlighted procurement as a powerful lever for scaling firms. In the UK, public procurement represents £385 billion annually. Used strategically, it can help innovative firms scale into global leaders.
Canada’s Phoenix pay system failure illustrates what happens when procurement excludes startups and fintechs. Instead of relying solely on a single legacy vendor, the government could have piloted payroll fintechs and scaled those that proved reliable. This approach would have reduced project risk, avoided billions in overruns, and nurtured homegrown fintechs with export potential. The Phoenix example demonstrates why procurement should be used to actively build capacity for Canadian innovators, which can be accomplished in several ways.
Government is the largest single purchaser in the economy, and directing even a fraction of that demand toward fintech solutions can create the credibility these firms need to raise capital and expand. For example, the government could launch vendor challenges for small business lending platforms or digital payment systems for rebates, benefits, and tax refunds. Winning firms would gain real contracts that prove their technology works and make it easier to raise more investment. This type of procurement not only meets government requirements but helps Canadian fintechs grow at home and compete abroad.
Too often, fintechs win small pilots but never graduate to meaningful contracts. A staged model, where early pilots can transition into scaled adoption if they meet performance benchmarks, would help promising firms grow into national providers. This escalator effect is critical in financial technology, where credibility with one large client can unlock commercial opportunities globally.
Fintechs often face a Catch-22 where they can't win major contracts without clear regulatory status, yet regulators hesitate to provide clarity until the firm has proven market traction. Procurement could break this cycle by acting as a regulatory bridge. If a fintech wins a vendor challenge for services such as digital identity or payments, the process could be designed to include early regulatory sign-off or tailored supervisory guidance. This would give the fintech and its backers confidence about compliance costs and expectations, while also reassuring the public that safeguards are in place from the start.
Taken together, the above examples could use government procurement as a genuine scale-up escalator. So instead of simply selecting incumbents all the time and concentrate risks into a handful of providers that turn into an oligopoly, government purchasing could become a purposeful tool for nurturing Canadian fintechs into globally competitive firms.
The CMA’s speech discusses competition as a tool for unlocking growth. For Canada’s fintech sector, three lessons stand out.
If Canada embraced the UK's stance on competition and scale-ups, fintechs would move faster from idea to scale, investors would back firms with greater confidence, and procurement would foster globally competitive players.
Competition shouldn't be seen as a hand-brake but rather as the engine for Canadian productivity and growth.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Competition | Aug 28, 2025
On October 8, 2025, the Rotman School of Management will host an in person debate on one of the most contested questions in Canada’s economy: Are Canada’s so called oligopolies standing in the way of a dynamic Canadian economy?
This debate is at the heart of whether concentrated industries in banking, telecom, airlines, and grocery are reducing competition and consumer choice or whether a few large firms are needed to sustain investment in a relatively small market.
Host: Rotman School of Management
Rotman Debate: Are Canada's So-Called "Oligopolies" Holding Us Back?
Date: October 8, 2025
Time/venue: 6:00 PM to 8:00 PM at Desautels Hall
Agenda: Live in-person debate followed by a networking reception
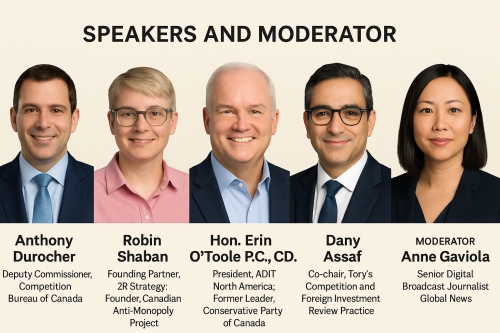
Anthony Durocher, Deputy Commissioner of the Competition Bureau, and Robin Shaban, economist and founder of the Canadian Anti Monopoly Project. They bring a competition policy and inclusive growth lens, pressing the case that concentration stifles productivity and affordability.
They will likely emphasize how concentrated markets in banking, telecom, grocery, and airlines restrict consumer choice, keep prices high, and hurt innovation. Both have deep expertise in competition policy, which will resonate with Canadians worried about affordability, productivity, rising costs, and declining foreign direct investment.
Erin O’Toole, former Leader of the Conservative Party and now President of ADIT North America, and Dany Assaf, co chair of Torys LLP’s competition and foreign investment practice. Their case focuses on the role of scale in driving resilience, capital inflows, and global competitiveness.
Expect them to argue that scale is necessary in Canada’s small market to attract global investment, maintain resilience, and provide stability. O’Toole brings political credibility and public speaking skills, while Assaf brings legal and transactional expertise from landmark competition cases.
The debate will be moderated by Anne Gaviola, senior broadcast journalist at Global News, who has more than 15 years covering Canada’s business and financial sectors.
For the NCFA Canada, this debate could not be more timely. The structure and size of Canada’s markets and levels of competition directly affects opportunities for new entrants in fintech and alternative finance. Concentrated industries can create barriers to entry. With productivity and affordability now central to Canada’s policy agenda, the insights from this debate will be directly relevant for startups, investors, and regulators. This is a ticketed event. Register now to secure your spot.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Research | July 22, 2025
Image: Freepik AI
According to a recent WORKBank audit, a major new study from Stanford's SALT Lab, 41% of Y Combinator-backed AI agent companies are
to tasks that workers have no desire for automation. These 'no go zones' represent tasks that are technically automatable but socially or emotionally rejected by workers. It's a growing disconnect that highlights a fundamental challenge for the future of work.
Should AI companies and investors automate tasks that people do not want or lead to no progress, no matter how advanced these systems are?
The WORKBank database is based on a comprehensive survey of data collected between January and May 2025 from 1,500 U.S. workers across 104 occupations and 844 occupational tasks. Each task is drawn from the U.S. Department of Labor’s O*NET database and evaluated by worker preferences and AI expert assessments. Responses were collected using an audio interface to reflect practical real world task experience.
This structured format asked workers whether they would want a task fully automated by an AI agent, and how much human collaboration they believe is needed to maintain task quality.
To assess the balance between automation and augmentation, the research team created the Human Agency Scale, a 5 level scale from H1 (no human involvement) to H5 (essential human involvement).
The most preferred response across the workforce was H3, an equal partnership between humans and AI agents. This level was dominant in 47 out of 104 occupations, however for 47.5% of tasks, workers wanted more human involvement than experts believed was technically necessary. It's a gap that could evolve into resistance points in high efficiency AI rollouts.
Despite concerns, 46.1% of tasks received a positive rating for automation. Workers were most supportive of AI when it freed up time for more important work (69.4%), reduced repetitive or tedious tasks (46.6%), or improved quality (46.6%).
On the other hand, resistance appeared from fear of losing trust, jobs, or creativity. Among those expressing concerns, 45% cited lack of trust, 23% named job loss, and 16.3% described the loss of a human touch. Arts, Design, and Media was the sector with the lowest interest in automation where only 17.1% of tasks received a positive score.
Researchers compared the WORKBank tasks with descriptions of companies backed by Y Combinator’s public portfolio. The results show a concentration of capital in areas workers are skeptical about.
41% of companies were mapped to tasks in the Low Priority Zone or Automation Red Light Zone, where worker demand is weak or negative, while many tasks in the Automation Green Light Zone and R&D Opportunity Zone where workers want automation remains underfunded (Read: ripe for AI task automation).
The research also looked at how AI is impacting the demand for certain job skills. Tasks that require higher levels of human agency usually involve interpersonal and decision making abilities rather than data analysis or technical information processing.
Comparing skill rankings based on wage data from the U.S. Bureau of Labor Statistics with human agency requirements revealed a trend away from solo technical execution toward organizational coordination, collaboration, and judgment. This suggests a shift in the kinds of competencies that AI will complement rather than replace.
Canada is investing heavily in AI innovation, fintech development, and reskilling strategies for the future economy. The WORKBank research shows that AI innovation must be aligned with worker needs and social context. If Canadian fintechs and investors focus only on technical feasibility without considering how workers feel about automation, they risk building tools that sit unused, untrusted, or even opposed. AI companies and investors must engage the people whose work is being transformed.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 6, 2025
Image: Freepik
Saving up for your dream vacation can feel like an endless journey, especially when you're trying to balance your wanderlust with your daily expenses. However, building a travel fund doesn't have to mean sacrificing all the fun in your life. With a little creativity and discipline, you can steadily grow your savings while still enjoying the things you love.
The first step in building your travel fund is to determine how much money you need to save. Research your destination, considering factors like transportation, accommodations, food, and activities. Once you have a target amount in mind, break it down into smaller, manageable goals. For example, if you're planning a Mexico adventure tour that costs $2,000, aim to save $200 per month for 10 months.
To avoid the temptation of dipping into your travel fund for other expenses, open a dedicated savings account. Many banks offer high-yield savings accounts with competitive interest rates, allowing your money to grow faster. Set up automatic transfers from your checking account to your travel fund each month, so you consistently save without having to think about it.
Look for areas in your budget where you can trim costs without sacrificing too much enjoyment. Instead of eating out every weekend, host potluck dinners with friends or cook meals at home. Swap your cable subscription for a streaming service, or consider cutting the cord altogether. By making small changes to your spending habits, you can free up more money for your travel fund.
Increasing your income is another effective way to build your travel fund faster. Consider taking on a part-time job or starting a side hustle that aligns with your skills and interests. Freelance writing, tutoring, or selling handmade crafts online are just a few examples of ways to earn extra money. Dedicate all or a portion of your additional income to your travel savings.
If you have good credit, signing up for a travel rewards credit card can help you earn points or miles for your everyday purchases. Many cards offer generous sign-up bonuses that can significantly boost your travel fund. Just be sure to pay off your balance in full each month to avoid interest charges, and only spend what you can afford to pay back.
While you're saving for your big trip, don't forget to enjoy smaller, budget-friendly adventures closer to home. Explore nearby state parks, go on weekend camping trips, or attend free community events. These experiences can help satisfy your wanderlust without breaking the bank, and they'll make the wait for your dream vacation more bearable.
Building a travel fund takes time and discipline, so it's essential to stay motivated throughout the process. Create a vision board with images of your dream destination, and place it somewhere you'll see it every day. Share your goals with friends and family who can offer encouragement and accountability. Celebrate each milestone along the way, whether it's reaching a certain savings amount or booking your flights.
By following these strategies, you can steadily grow your travel fund without feeling like you're missing out on life's joys. Remember, the sacrifices you make now will be well worth it when you're finally embarking on your dream vacation, whether it's a Mexico adventure tour or another exciting destination. Stay focused on your goal, and before you know it, you'll be packing your bags and setting off on the adventure of a lifetime.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
DeFi Policy | June 5, 2025
Image: Freepik/rawpixel.com
On June 9, the U.S. Securities and Exchange Commission is hosting a policy roundtable titled “DeFi and the American Spirit” to have an open and structured policy dialogue with decentralized finance developers, innovators, and legal experts alongside SEC legal and regulatory voices. The roundtable is part of the SEC's Crypto Task Force's ongoing series of crypto asset regulation events.
These gatherings are not 'hearings', nor are they 'policy announcements' but rather conversations with people who have actually built defi systems, in fact many who have publicly challenged the SEC's approach. It’s a live forum where ideas about risk, innovation, and policy design can be tested in real time. So in that way, it's a rare and important event for DeFi in the U.S. and fintechs watching from other jurisdictions like Canada.
The speaker lineup is a mix of founders, researchers, lawyers, and advocates who all have somewhat different views on how DeFi should work and be handled from a regulatory and practical perspective.
Erik Voorhees, founder of ShapeShift (and now Venice AI) is known for arguing that decentralized tools and open-source software should not be regulated like traditional financial intermediaries. His participation ensures that the case for user autonomy and protocol neutrality will be represented without compromise.
Michael Mosier, former acting director of FinCEN who founded Arktouros is focused on financial crime and compliance. He's likely to advocate for more robust frameworks for identifying illegal flows through permissionless systems. He'll ensure that AML and systemic risk questions are part of the core conversation.
Rebecca Rettig, general counsel at Jito Labs and formerly with Polygon, brings first-hand experience in understanding protocol development and legal structure, and is well positioned to bring up solutions that don’t rely on full centralization, such as voluntary disclosures or protocol guardrails.
Kevin Werbach, a professor at Wharton, has spent years studying how decentralized systems intersect with regulation. He tends to advocate for layered frameworks that separate software, governance, and commercial activity to provide a way to regulate outcomes without halting innovation.
There are several other panelists including Jill Gunter (Espresso Systems), Peter Van Valkenburgh (Coin Center), Omid Malekan (Columbia Business School), Gabe Shapiro (MetaLeX), and others who will no doubt have ample to contribute in helping the SEC understand as well as framing the policy of decentralized systems.
It’s a great cross-section of people trying to answer the same question from different angles: how should decentralized finance be understood and governed?
Here are some core questions that may come up during the discussions:
At the end of the day, the SEC should be commended for their willingness to engage with key foundational questions in effort to both understand at a deeper level, as well as inform future policy making. Leaps and bounds better than regulate by enforcement under the SEC's ex-Chair, Gary Gensler and a commission that would rather assume that every DeFi project is either a rug-pull or disguised as a securities platform.
If the roundtable opens the door to more flexible or fit-for-purpose regulation, Canadian regulators will face growing calls to follow suit. It also offers Canadian founders a window into how U.S. regulators are thinking, what they are worried about, what they may be willing to tolerate, and where they are open to compromise. It's clear proof that the SEC is finally recognizing that DeFi isn't going away and that series policy design needs inputs from the people building it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Data Research and Strategy | May 25, 2025

Image created by AI, Personas based on real data from 2024 Financial Lives, FCA
Four FCA personas reveal where fintech innovation must go next
On May 16, 2025, the Financial Conduct Authority (FCA) published one of the richest datasets ever on UK consumer financial behaviour, resilience, and preferences called, "Financial Lives 2024 survey". It's an annual snapshot taken ever 2-3 years and offers valuable benchmarks and insights into how financial institutions, fintechs and financial engineers can translate this data into strategy.
There are 18 excel sheets with various tabs covering survey responses for almost 1300 survey questions pertaining to a wide range of topics such as attitudes and product/service ownership of payments, retail banking, consumer investments, general insurance and protection, mortgages, credits and loans, assets and debts, cash savings, advice/guidance and pension. There's also tracker data tables for comparing and analyzing changes over time across 2017, 2020, 2020 and 2024 surveys.
Drawing directly from the FCA 2024 Financial Lives survey results, we created 4 personas that reveal who is underserved, gaps in the ecosystem, and where fintechs, banks, and credit unions should consider focusing on to rebuild trust and relevance.
Amira is a young adult struggling with inconsistent income from various gigs, rising living costs, and a heavy reliance on credit. She is digitally active but financially stretched and uncertain as to who she can trust. Survey data shows:
Fintechs should build real-time tools that show all credit and BNPL use in one place, including spending limits, that help users like Amira avoid taking on more debt than they can handle. Adding clear, user-led budgeting flows into existing BNPL workflows can help bridge shortfalls and help build trust with transparency.
Stella is an older consumer who likes to avoid debt, prefers analog channels, and feels underserved by digitally native services. She values trust and simplicity highly and struggles to access new tools. Survey data shows:
Financial institutions should consider creating hybrid formats that combine print materials with digital access points, such as QR codes linking to audio summaries. ESG and pension tools can be made more accessible with phone helplines and in-branch tutorials to help consumers who lack confidence to gain confidence and fill in comprehension gaps.
Rohan is a confident, digitally native, and actively manages savings, investments, and often finds himself switching providers to maximize value. He expects clarity, ESG transparency, and integrated experiences.
Rohan needs a unified dashboard that lets him integrate his finances across pension, savings, and ESG investments. Fintechs can lead here by offering smart comparison tools that verify impact metrics, automate vendor switching, and offer ESG guidance within the same experience.
John is a middle-aged adult that is juggling aging kids, debt, complex commitments, and low financial resilience. He is time-poor, questions everything, and is stuck with outdated, fragmented financial tools. The survey shows:
Institutions must prioritize credit and debt consolidation tools for this segment by offering personalized paths and support towards financial recovery. Embedding phone or online chat support into their digital journeys can help reduce friction, while demonstrating quick wins to build confidence and encourage engagement.
We've come up with the following table that matches the 4 personas with specific fintech strategies tailored to their behaviours, needs, and gaps, all based on the FCA's 2024 financial lives data, and to support product design, channel strategy, and business model decisions.
| Persona | Product Opportunity | Channel Strategy | Business Model Insight | Ecosystem Gap |
| Amira – Young Borrower | BNPL budgeting + affordability | Mobile-first, embedded in BNPL apps | Freemium with affiliate links to trusted debt tools | Risk-aware BNPL integrations |
| Stella – Conservative Saver | Print-to-digital ESG education | Branches, phone, community agents | Subscription or pay-per-use legacy planning tools | Print-digital pension guidance |
| Rohan – Digital Builder | ESG + switch optimizer dashboard | Self-serve, in-app investing hubs | B2C SaaS with optional robo-advice tier | ESG decision confidence |
| John – Overloaded Middle | Modular savings + credit coach | Web app + human phone fallback | Hybrid subscription + nonprofit partnership model | Blended digital advice models |
Each of the 4 personas created actually represents thousands of real individuals and their financial lives in 2024, caught between fragmented services and changing financial needs.
The profiles above are designed to help fintechs and institutions develop a targeted roadmap based on clearly defined, data-driven groups with targeted solutions, to help provide responsible and more inclusively designed financial products/services for underserved groups in need. A similar survey in Canada would probably produce similar results.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open Finance Policy Development | May 22, 2025
Image: Freepik/rawpixel.com
On May 15, 2025, the Cambridge Centre for Alternative Finance (CCAF) hosted a webinar, “Open Finance in Practice: Implementation, Liability & Monetisation” with experts from Thailand, Rwanda, India, the UK, and Asia-Pacific who shared what's working and what's not, based on their practical experience. Open finance is progressing globally but real world experience shows that it is not just about technology or APIs, and successful implementation depends on clear rules, trusted governance, and strong infrastructure. These insights are especially relevant now as Canada prepares to implement its own open banking system in 2026.
Sanjay Janeja, Open Banking Lead, CCAF:
“Our data shows that regulation-led models support faster implementation and broader data sharing.”
CCAF’s Global Regulatory Innovation Dashboard (GRID) shows that countries with clear regulatory mandates, like Brazil and Australia, have progressed faster than those relying on voluntary participation. India in contrast, moved slowly at first without regulatory mandates. Canada risks similar delays unless its upcoming rules are clear, enforceable, and consistent.
Denise Dias, Regulatory and Supervisory Consultant:
“Governance is the soul of open finance.”
Governance critically defines who sets the rules, allows the accreditation of participants, and resolves disputes. Rwanda is building shared oversight between its financial and telecom regulators. Countries that define this early see smoother adoption. Canada's future governance structure needs to include clear roles for regulators, industry, and consumer protection agencies.
Rafael Mazer, Director, Fair Finance Consulting:
“Consumers should not have to wait for firms to assign blame before they are made whole.”
As more parties exchange financial data, legal clarity is paramount. The UK mandates reimbursement even before liability is settled. Oman and UAE require indemnity insurance for open finance participants. Canada needs to define who is liable, under what conditions, and how disputes will be resolved before open banking go live.
Rafael Mazer:
“This is where the claws come out.”
Camilla Bullock, CEO, Emerging Payments Association Asia:
“You cannot grow the pie if the small players cannot afford a slice.”
Thailand uses free access for consumers and capped pricing for commercial use. Brazil allows a set number of free requests per user. These models keep access open for small fintechs. Canada should consider following suit to avoid anti-competitive pricing that could exclude new entrants.
Pamela Umutesi, Lead for Open Finance, National Bank of Rwanda:
“Let your local context guide how you implement.”
Thailand focused on non financial data first because the infrastructure was already in place. Rwanda’s model prioritizes mobile money. Canada of course is considering its own requirements, including provincial data laws, legacy banking systems, and regional financial access gaps. Bottom line is that a one-size-fits-all model that works abroad will not necessarily work elsewhere.
The table below primarily covers open banking implementations, with some jurisdictions extending toward open finance (Brazil, India, Thailand).
This is an important distinction because open banking generally refers to access to 'bank account data' which is often mandated for regulated institutions. While Open Finance expands beyond banking data to include insurance, investments, pensions, government data, mobile money, and more.
| Country | Pricing Model | Regulatory Status | Governance Approach |
| Brazil | Free access below threshold | Mandated and implemented | Central bank |
| Thailand | Free for consumers; capped for firms | Mandated and being implemented | Bank of Thailand and industry consortium |
| India | Commercial pricing; no fixed rules | Voluntary, evolving | NGO-led (Sahamati); gaining government support |
| Rwanda | Pilot phase; not-for-profit approach | Mandated, not yet implemented | Multi-agency regulator framework |
| UK | Free for regulated APIs | Mandated and implemented (OB only) | Regulators (CMA, then OBIE, now JROC) |
| Australia | Free basic; optional premium | Mandated and implemented | Treasury under Consumer Data Right law |
| EU (PSD2) | Mostly free under PSD2 | Mandated and implemented (OB only) | Regulator; preparing Financial Data Access (FiDA) |
| Singapore | Voluntary pricing; no mandate | Voluntary | MAS; market-driven with government-backed standards |
| Hong Kong | Commercial rates allowed | Voluntary with phased guidance | HKMA; implementation by industry associations |
| Canada | TBD (under consultation) | Mandated, not yet implemented | Department of Finance; FCAC |
Canada has committed to implementing open banking but full rollout isn't expected until 2026. In June 2024, the Department of Finance enacted the Consumer-Driven Banking Act, the legal framework for open banking, and appointed the Financial Consumer Agency of Canada (FCAC) as the authority responsible for implementing, overseeing, and enforcing the framework. Final rules on liability, pricing, and participation are still under development.
Countries that wait too long or rely only on voluntary models are playing catch-up. NCFA supports an open finance framework in Canada that protects consumers, enables competition, and accelerates innovation. Canada should learn from the world's most successful open finance systems, which are defined by clear regulation, fair pricing, and shared governance. As the CCAF’s global tracker and research show, clear rules work. Delay does not.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
