





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Davos | Jan 19, 2026

Image: Current Global Risk Landscape (WEF 2026 Global Risks Report)
From January 19 to 23, 2026, global leaders are gathering in Davos, Klosters for the World Economic Forum Annual Meeting 2026, one of the few global forums where heads of government, central bankers, investors, and business leaders meet in the same place to discuss economic risk, trade, and long term stability. This year’s theme is "A Spirit of Dialogue", to address growing concerns that cooperation is weakening as global risks are becoming harder to manage.
Ahead of Davos, the World Economic Forum released its Global Risks Report 2026 (102 page PDF) based on its Global Risks Perception Survey of more than 1,300 experts across government, business, academia, and civil society worldwide. Participants were asked to rank the risks most likely to trigger a global crisis in the short term, as well as the most severe risks over longer time horizons.
The report identifies "geoeconomic confrontation" as the top risk most likely to trigger a material global crisis in 2026. 18% of survey respondents ranked it first, moving it ahead of state based armed conflict for the first time. The report defines geoeconomic confrontation as the deliberate use of tariffs, sanctions, export controls, investment screening, subsidies, capital restrictions, and technology controls to advance national interests, rather than as temporary trade friction.
The report frames the current period as an age of competition, where economic tools increasingly replace diplomacy. It also shows that confidence in multilateral systems is weakening.
68% of respondents expecting a more fragmented global order, where countries manage multiple regional relationships instead of relying on a single rules based framework.
Economic risks remain elevated. An economic downturn ranks 6th among global risks for 2026, reflecting concerns tied to trade fragmentation, high debt levels, and asset price vulnerability. The report doesn't predict a specific recession size, but it highlights how shocks can spread faster in a highly interconnected financial system.
The report also quantifies risks tied to trust and technology. Misinformation and disinformation rank 5th, driven by faster and more scalable digital amplification. Cyber insecurity ranks 9th, while adverse outcomes of AI technologies enter the top ten for the first time, reflecting concerns around misuse, governance gaps, and longer term economic and security effects. Importantly, the report shows AI related risks increasing significantly over the ten year horizon, as leaders view AI as a structural risk that compounds other pressures rather than a short term crisis trigger.
Canada doesn't set global rules on its own, but it is deeply affected by how those rules evolve. The Global Risks Report makes clear that mid sized, trade dependent economies face higher exposure when economic pressure becomes a primary policy tool.
Market behaviour already price this sensitivity. Canadian equity markets have shown quick reactions to renewed tariff threats and trade policy signals, reinforcing how closely capital pricing tracks global risk narratives. This volatility isn't driven by domestic structural gaps alone, but by uncertainty in the global trade environment.
In Canada, business leaders are already feeling the pressures Davos is wrestling with. In the Bank of Canada Business Outlook Survey for the fourth quarter of 2025, firms report subdued sentiment and weak recent sales growth, and many point to trade tension and uncertainty as key reasons they stay cautious on hiring and investment. Some exporters also report that they are working harder to sell into markets outside the United States, which fits a broader push toward diversification as global risk rises.
For Canada, the forum offers a place to engage with partners, investors, and institutions that are reassessing risk, diversification, and resilience at the same time. In a world where geoeconomic confrontation leads the risk rankings, visibility and credibility matter.
The risks highlighted in the Global Risks Report translate into practical considerations for Canada’s fintech and innovation ecosystem.
First, trade concentration is a measurable risk.
When tariffs, sanctions, and investment controls rise, companies with narrow market exposure face greater volatility. Diversifying customers, partners, and capital sources becomes a defensive strategy, not just a growth choice.
Second, capital follows predictability. The report links economic downturn risk to policy uncertainty and fragmented governance. Investors respond by adjusting risk premiums, which affects valuations, fundraising timelines, and exit options, particularly for scale ups.
Third, technology risk is contextual, meaning technology itself isn't the main risk. The risk comes from how it is used, governed, and trusted, especially when economic and political tensions are already high. The report doesn't treat AI or digital systems as isolated threats. Instead, it positions them as amplifiers that can worsen misinformation, cyber exposure, and economic disruption if governance and trust break down. For Canadian firms competing globally, credibility around security, governance, and responsible deployment increasingly affects whether they win customers and attract capital.
Trade, finance, and technology are now at the center of geopolitical strategy, with direct consequences for businesses and investors. Canada’s fintech ecosystem should plan for sustained volatility. Growth strategies built on stable trade assumptions face higher risk. Founders and investors who understand these quantified global risks will be better positioned to manage exposure, attract capital, and compete responsibly in a more uncertain global economy.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI Regulation | Jan 14, 2026

Image: Freepik
In the first days of January 2026, Elon Musk's AI chatbot Grok (developed by xAI and integrated into X) generated sexual images of real people, including images apparently involving minors, after internal safeguards failed. The issue became public immediately after the New Year and has gone viral since. What began as a platform failure quickly expanded into regulatory, legal, and civil society responses across multiple jurisdictions.
Malaysia and Indonesia are the only countries that have confirmed national blocks of Grok access, citing the creation of non-consensual sexualised imagery and public safety risks.
European Union officials also warned that failure to address the issue could lead to enforcement under existing digital safety rules. No EU-wide restriction has been imposed.
Public pressure has also played a role. International NGO Oxfam confirmed it's examining reports involving AI generated sexualised images created by altering real photographs, framing the concern around harm, consent, and exploitation.
Individuals whose likenesses were used in non-consensual AI generated sexual imagery have spoken out publicly in the United States, describing personal harm and exploring legal remedies, as reflected in accounts from people targeted by AI sexual images. Some unions and professional groups have also reduced or paused activity on X following the controversy.
In the United Kingdom, Ofcom launched a formal investigation into X after what it described as “deeply concerning reports” that Grok was being used to create and share sexualized images, including children.
Ofcom said it will assess whether X failed to remove illegal content quickly once aware of it, whether it took appropriate steps to prevent UK users from seeing such material, and whether it deployed highly effective age assurance measures to stop children from accessing pornographic images.
If Ofcom finds X has breached UK law, it can impose a fine of up to 10% of worldwide revenue or £18 million (whichever is greater), and can seek a court order requiring internet service providers to block access to X in the UK.
UK ministers publicly backed the investigation, urging Ofcom to complete it swiftly and stating that victims would not accept delay.
Elon Musk responded publicly by criticising government actions, saying the UK government was looking for “any excuse for censorship” after questions were raised about why other AI platforms were not being examined. Separately, Musk said he was unaware Grok had generated explicit images involving minors and stated such uses violate platform rules.
The United States has not blocked Grok, but lawmakers have focused on liability. The US Senate unanimously passed legislation allowing victims of non-consensual sexually explicit AI generated images to pursue civil action, including damages and court orders.
Canada has also avoided a ban. Ottawa's AI Minister Evan Solomon responsible for artificial intelligence stated the government will not ban Grok or X at this stage, while acknowledging that Canadian law doesn’t clearly address AI generated non-consensual sexual imagery, and that laws needed updating to address deepfakes.
To be sure, AI governance tightens once harm involves identifiable individuals as in this case. Across jurisdictions, responses are focusing on consent, child protection, and platform accountability rather than abstract debates about speech. For fintechs and other regulated firms deploying generative AI, scrutiny is on improving governance, safeguards, and enforcement readiness.
From NCFA's perspective, AI systems should operate within clear legal and ethical boundaries that protect individuals, maintain public trust, and still allow responsible innovation to move forward. As of now, verified developments include two confirmed national blocks, active regulatory investigations, quantified enforcement powers, and new US civil liability legislation. Further responses remain under review.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Prediction Markets | Jan 12, 2026

On January 10, 2026, prediction markets were back in the spotlight when an anonymous trader wagered more than $30,000 USD on the removal of Venezuelan president Nicolás Maduro and later collected over $400,000 USD once the outcome became public. No regulator has confirmed insider trading and no enforcement action has been announced, but the successful trade result matters because it shows how quickly prediction markets can price almost anything including geopolitical outcomes ahead of official confirmation.
It's another visible, benchmarked stress test of a category that has been scaling quietly for years. Prediction markets have gone mainstream and are evolving into fast moving information markets that sit at the intersection of finance, media, and public policy. In some way, they're beginning to resemble consumer finance products rather than novelty bets. Then distribution was another recent inflection point when MetaMask added Polymarket access directly inside its self custody wallet, prediction markets moved closer to everyday crypto workflows. Once markets become native features rather than standalone destinations, scale accelerates.
Prediction markets scale because they sell something scarce. A continuously updating probability signal backed by capital. Traders adjust prices faster than surveys (as they have skin in the game). Media repeats those prices as indicators. Investors track them as sentiment inputs and risk signals. That loop turns a market price into a reference point that travels quickly across sectors.
At scale, intent matters less than structure. Markets don't need bad actors to create risk. Risk emerges when incentives move faster than controls. The Maduro trade illustrates this dynamic without proving wrongdoing. A sensitive geopolitical outcome was priced by a market before institutions and the public had time to react.
Regulatory friction starts with classification, and prediction markets sit between gambling and financial products, depending on jurisdiction and design.
In the United States, Kalshi operates as a designated contract market overseen by the Commodity Futures Trading Commission. The CFTC explains that designated contract markets are federally regulated trading venues subject to surveillance, reporting, and market integrity requirements in its Designated Contract Markets overview. US regulators and courts continue to debate which categories of event contracts are appropriate for trading under this structure, particularly where contracts resemble gambling rather than traditional risk management.
Polymarket followed a different path. The platform previously faced enforcement action from US regulators for offering unregistered event based binary options to American users, resulting in a monetary penalty and a wind down of those markets. Then the company experienced a regulatory reset. NCFA previously covered how Polymarket earned approval to relaunch in the US.
Canada banned short term binary options for retail investors in 2017 after widespread fraud harmed consumers. The Canadian Securities Administrators set out the prohibition and its scope, and clarified that products paying out on simple yes or no outcomes fall within that restriction under Multilateral Instrument 91-102. Because most prediction market contracts share that payout structure, independent prediction markets are effectively prohibited unless operated directly by provincial gaming authorities.
That approach reduced direct consumer exposure. It did not eliminate influence. Canadians still consume market driven narratives generated elsewhere. Market odds circulate through global media and social platforms regardless of domestic rules. Capital continues to flow to platforms operating in more flexible jurisdictions.
The Maduro payout highlights a structural challenge rather than an allegation. When markets are novel, fast, and global, existing frameworks struggle to answer basic integrity questions.
In traditional securities markets, insider trading rules address the use of material non-public information. Prediction markets often sit outside that framework. Platforms may prohibit insider use contractually, but enforcement becomes difficult when identity is masked and funds move through crypto rails.
Integrity risks extend beyond insider advantage. Wash trading incentives can distort volume. Thin liquidity in long tail markets can exaggerate price movement. Concentrated positions can temporarily push odds that then echo through coverage and perception. These dynamics do not stay contained within the platform.
Prediction market operators often describe their platforms as sentiment barometers. Prices aggregate belief. Odds update with new information. That framing holds more easily on entertainment or sports outcomes.
It gets harder when markets trade on politics, elections, or government decisions. Prices stop being just signals of opinion. People notice them, talk about them, and react to them. Once those prices show up in headlines, they start to influence how investors, the media, and the public think about what is likely to happen. Markets that say they only reflect reality can end up helping to shape it.
Prediction markets are scaling because they meet demand for real time signals in an uncertain world. Regulators now face a strategic choice. Continue treating these platforms as edge cases, or acknowledge that they are becoming part of the financial and information ecosystem and design rules accordingly.
For Canada, the question is whether governance evolves in step with market reach, or whether influence continues to arrive from outside the regulatory perimeter.
When markets bet on geopolitics, the issue is not the trade itself. It is whether the rules governing markets, information, and incentives are built for the reality that now exists.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Strategic Planning | Nov 28, 2025

Image: Freepik/rawpixel.com
2026 is approaching and fintechs are entering the new year with clear signals on how capital is being deployed, how financial institutions are investing in automation and AI driven capabilities and which policies will shape financial infrastructure. Markets place a higher premium on efficiency, governance and resilience as financial institutions modernize data access and digital settlement. Retail investor participation also expanded as equity crowdfunding set new records in Canada, strengthening another channel of capital formation.
United States tariffs and interest rate expectations continue to influence capital costs and enterprise demand across North America. Singapore FinTech Festival 2025 recently wrapped and outlined what global leaders expect over the next decade. This article provides an overview of how these forces intersect and will impact 2026 conditions, helping fintechs define runway, product plans and investor alignment for the year ahead.
Global investors concentrated capital into fewer fintech companies through 2025. KPMG tracked $44.7B across 2,216 global fintech deals and reported stronger momentum in digital assets and AI powered platforms. The global fintech funding review for 2025 notes uneven performance across payments and infrastructure and continued strength in digital asset investment. AI influence extends across every funding stage and drives the clearest premium in investor behaviour.
Canadian fintechs raised about $1.62B across 60 deals. KPMG data reported by Lexpert shows a steep decline from record 2024 levels as investors became more selective and disciplined. KPMG’s H1 2025 report confirms the trend toward fewer large cheques and more careful deployment.
CVCA reported $2.9B across 254 Canadian VC deals with average cheque sizes near $11.4M. The VC deployment across Canada in H1 2025 reported that early stages represented more than half of deal count but only 10% of dollars. NCFA’s seed review shows AI companies raising about $24M across 12 early stage rounds and fintech attracting about $9M across pre-seed and seed combined in the seed investing trends in H1 2025.
Canadian founders also turned to retail investors through regulated equity crowdfunding channels. FrontFundr, a leading Canadian investment crowdfunding platform, enjoyed a banner year raising CAD $68.3M across 66 campaigns in 2024 with 4,226 individual investments, its strongest year on record. This growth in community capital raising speaks volumes that diversified sources of early stage capital can complement VC allocations during selective cycles. For fintechs, retail participation can help extend runway, validate demand and reduce dependence on a small number of institutional investors.
AI remains the strongest source of valuation strength across the fintech sector. NCFA’s analysis shows that AI fintechs attract a 242 valuation premium compared with non AI peers. This tells fintechs that investors reward automation, accuracy and data advantage even during slower deployment cycles. AI's impact will continue to drive product development strategy, unit economics and growth planning for 2026.
Open banking moves into implementation. Budget 2025 commits to a consumer driven banking framework that designates the Bank of Canada as the supervisor for accredited participants and sets rules for data access, liability, security and technical standards. The consumer driven banking framework in Budget 2025 changes data mobility from one off arrangements to regulated data rails. These data rails also support AI adoption because models require secure access to high quality data. Fintechs that prepare for accredited access and safe data workflows will gain an advantage as institutions deploy AI into risk, compliance and customer operations.
Fintechs should expect accreditation activity, testing and early stage integrations as technical standards move toward production readiness through 2026.
Retail Payment supervision is operational and supports future access to real time settlement. Under the Retail Payment Activities Act, the Bank of Canada supervises payment service providers to ensure operational resilience and safeguarding of client funds. This oversight creates the regulatory foundation required for participation in core payment systems. Payments Canada continues development of the Real Time Rail (expected Q2 2026), while the Bank’s commentary on cashing in on payments innovation explains how regulation strengthens competition and prepares the foundation for modernized settlement. It also sets the operational standards that AI systems must meet for real time fraud detection, liquidity monitoring and compliance automation. Fintechs should plan for higher compliance expectations in 2026 and a clearer pathway into national payment systems once real time settlement becomes available.
Stablecoin regulation advances. Canada released the first draft of its federal stablecoin legislation which sets out rules for high quality reserves, custody, redemption, disclosures and prudential oversight. NCFA’s summary of the first draft of the Stablecoin Act outlines a government framework that brings fiat backed stablecoins into a supervised environment. As tokenized settlement expands, AI will move deeper into treasury, reconciliation, fraud control and settlement routing. Fintechs that design early AI enabled settlement workflows will operate more efficiently under these rules. Fintechs involved in digital money, cross border payments or tokenized settlement should expect stronger regulatory clarity across 2026.
Climate and sustainability disclosure remains paused. CSA halted its mandatory climate disclosure rule in April 2025 and signalled the pause will continue. Although the rule is on hold, enterprise buyers and investors still assess climate and transition risk data during diligence. The CSA climate disclosure update notes that existing materiality rules and OSFI Guideline B-15 still apply through 2026. AI plays a growing role in climate analytics and transition planning, which means fintechs that use AI for risk scoring and scenario work will offer enterprise buyers more actionable intelligence during diligence. Fintechs should assume voluntary disclosure is expected even without a formal mandate.
Competitiveness pressure remains. Bank of Canada leadership warns that slow progress on open data, payment modernization and digital infrastructure affects productivity and innovation. Reuters coverage of the warning on over regulation and competitiveness highlights the need to accelerate foundational reforms. AI impacts that competitiveness gap because institutions deploy AI into fraud detection, lending, treasury and customer workflows. Fintechs that use AI with strong governance will operate more efficiently, support regulated environments and scale faster when data access and payment rails modernize.
For fintechs, these signals point to regulated data access, modern payments and digital assets becoming the highest value infrastructure themes for 2026..
Fintechs operating in the North American economy are being impacted by United States tariffs, rate decisions and political volatility. United States imposed tariffs cut Canada’s projected GDP growth to about 1.4% in 2025 and 1.6% in 2026, according to IMF linked projections. These estimates reflect weaker demand and reduced investment appetite across export dependent sectors. Fintechs should treat tariffs as a structural constraint for 2026, not a short term shock.
Markets now expect the Federal Reserve to cut rates in December. Polymarket shows an 87% chance of a 25 point rate cut, based on more than $183M in trading volume, which reflects strong real time sentiment. Economists still expect only small rate cuts through 2026, with United States growth around 2% and inflation near 2.6%. Fintechs may receive some cost of capital relief but investors will continue to expect efficient spending, strong revenue performance and clear evidence of product viability at today’s cost structure.
Canadian monetary authorities modeled the tariff impact and warned that trade friction could reduce investment by about 12% and lower output by almost 3% over two years. The Bank’s scenario work on tariffs and structural change supports planning for lower investment and slower recovery.
Fintechs should prepare for slower enterprise procurement cycles and more selective purchasing behavior.
Global growth projections dropped to about 2.8% in 2025 as tariffs spread and trade tensions widened. Export Development Canada’s global economic outlook for 2025 and 2026 forecasts Canadian growth around 0.8% in 2025 and 1.1% in 2026. Fintechs should expect slower demand, higher operating costs and more uncertainty across key trading regions.
An MIT study released in 2025 shows that about 12% of United States jobs could be automated using current AI tools today. As AI pressure intensifies it drives enterprise demand for automation, cost control and compliance. It also accelerates talent scarcity and raises expectations for governance and model transparency across financial services.
Global regulatory fragmentation expands. The EU AI Act, United Kingdom digital regulation, Singapore AI governance frameworks and China data sovereignty rules all diverge. If fintechs want to scale internationally in 2026, they must build modular compliance, auditability and data governance into core architecture.
SFF 2025 provided a clear view into the next cycle of fintech infrastructure and the capabilities that institutions expect. The SFF 2025 blueprint for the next decade of finance placed AI, tokenized settlement, quantum readiness and talent at the centre of global financial transformation for the coming years.
AI moved into production across onboarding, monitoring, underwriting and support. Financial institutions showed mature applications that reduce fraud, improve accuracy and accelerate customer workflows. Tokenized finance advanced as central banks and major institutions tested tokenized settlement assets, wholesale CBDCs and regulated stablecoins. These experiments are clear move from demos towards infrastructure design.
Quantum readiness entered strategic planning as banks prepared for post quantum cryptography and assessed their high value data inventory.
Talent emerged as one of the most constrained resources, with strong demand for cybersecurity, data and AI capabilities.
2026 will reward fintechs that integrate AI into their core stack, design products that support tokenized workflows, build quantum safe readiness and hire for digital infrastructure skills that support resilience and scale.
| Canada Policy Shifts That Drive 2026 Strategy | ||
|---|---|---|
| Open Banking Readiness | Canada moves to regulated data rails with accreditation and Bank of Canada oversight. | Build accredited data access readiness now. This creates a major advantage when banks and credit unions adopt regulated data sharing in 2026 and gives fintechs a lead when institutional partners demand safe integration. |
| Payment Supervision Alignment | Retail Payment Activities Act supervision is active and PSPs prepare for Real Time Rail participation. | Raise operational standards to meet supervision requirements. This clears the path for Real Time Rail access when available and strengthens partnership credibility with banks that expect higher resilience from PSPs. |
| Stablecoin Compliance Design | Canada released the first draft of the Stablecoin Act with rules for reserves, custody and redemption. | Design compliance into digital money products now. This avoids costly retrofits when rules finalize and positions fintechs for early participation in tokenized settlement experiments that banks support across 2026. |
| Transition And Climate Disclosure | CSA paused mandatory climate disclosure but investors still expect transition data in diligence. | Maintain credible voluntary disclosure. This reduces diligence friction with investors and large institutions that rank climate and transition data as core risk inputs even without a mandate. |
| Capital Conditions For Canadian Fintechs | ||
| Runway Discipline | Canadian funding normalizes with more selective deployment and fewer large rounds. | Plan 18 to 24 months of runway. This protects valuations and gives Canadian fintechs flexibility during slower deployment cycles and longer diligence timelines. |
| Revenue Quality First | Investors reward revenue durability as rates in the United States and Canada change slowly. | Increase margins, retention and customer lifetime value. This strengthens funding outcomes and signals that the business performs at today cost of capital. |
| Diversified Capital Routes | Equity crowdfunding reached record levels with rising retail participation in Canada. | Use investment crowdfunding to extend runway and validate market demand. This reduces reliance on a small number of venture investors and supports growth during selective funding cycles. |
| AI As The Primary Driver Of Competitiveness | ||
| AI As Core Infrastructure | SFF 2025 showed AI runs onboarding, risk, fraud and support in production. | Automate core work and improve accuracy. This reduces cost, raises product reliability and strengthens enterprise trust when selling into Canadian banks and credit unions. Remember, AI fintechs receive a valuation premium because automation and accuracy improve economics at every growth stage. |
| Model Governance Strength | Institutions expect clear model behaviour and explainability before integration. | Document lineage and monitoring with precision. This increases procurement success and accelerates enterprise adoption when institutions face rising AI governance requirements. |
| AI Driven Efficiency | Canadian enterprises invest in automation as budgets remain tight. | Replace manual workflows with AI to lower operating cost. This strengthens margins during slower growth and improves investor confidence. |
| Tokenized Settlement And Security Readiness | ||
| Tokenized Settlement Readiness | Banks and central banks test tokenized deposits and wholesale CBDCs. | Design workflows that support tokenized settlement. This prepares Canadian fintechs for early pilot participation when infrastructure tests expand in 2026. |
| Quantum Safe Architecture | Institutions begin planning for post quantum encryption. | Inventory sensitive data and adopt cryptographic agility. This protects long term assets and reduces future migration cost for Canadian fintechs selling into regulated environments. |
| Trade, Tariffs And Canadian Procurement Conditions | ||
| Adjusted Sales Cycles | Tariffs reduce Canadian investment and slow enterprise buying. | Extend sales cycle assumptions and build conservative forecasts. This improves cash planning and prevents burn surprises when procurement slows across regulated sectors. |
| Cost And Risk Value Propositions | Global growth slows and Canadian enterprises protect budgets. | Lead with measurable savings and risk reduction. This increases purchase probability in cost constrained environments and improves sales success during slow demand cycles. |
As the close of 2025 nears, fintechs operate in a world where capital rewards evidence first, and where AI driven performance gains receive premium valuation only when they improve accuracy, automation or margins. Fintech policy advancement in Canada moves forward on open banking, payments and stablecoins and these developments create new regulated rails to build on. Tariffs, interest rates and slower global growth increase the need for financial discipline and durable revenue streams. Retail investors also became more active in 2025 as equity crowdfunding set new records, giving Canadian fintechs another way to raise capital when venture funding is more selective. SFF 2025 highlighted the technologies that will shape financial infrastructure for the next decade.
Fintechs that align their strategy with the forces that matter, including AI, regulated data access, modern payments, tokenized settlement and stronger governance, will be better positioned to raise capital, win enterprise partnerships and scale through uncertainty.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 17, 2025
Image: Pexels/Pixabay
More and more parts of life in Canada are shifting online. People order groceries from their phones, see doctors over video, and handle work, bills, and banking without leaving home. Some have leaned into it fully, while others are still getting used to the pace of change. The tools are here, and the habits are forming, but not everyone is moving at the same speed.
Technology has made daily life in Canada smoother and safer. Most services are now running on secure platforms that have been designed to protect users and keep things simple. Ordering food, paying bills, or setting medical appointments can be completed in a few minutes with a phone. Many Canadians now use grocery delivery apps that show real-time updates from order to door delivery. It's a little change, but one that has saved hours each week and reduced long drives.
Entertainment has followed the same path. Many new online casino sites have added cryptocurrency payments, which give users more control over how they deposit or withdraw funds. This extra layer of protection and transparency has made people more confident when playing online, especially as data safety becomes a bigger concern across the web.
Similar growth can be observed in fitness and learning platforms. People can now join live training sessions or online workshops led by professionals. Someone in Halifax can follow a yoga teacher in Vancouver, or do a little course in digital skills from home.
Most Canadians don't have to visit a branch any longer, thanks to digital banking services. Some apps even have smart alerts that can flag any odd spending patterns or suggest ways to save a bit more each month.
What’s also changing is the way financial tools understand users. Thanks to data-sharing between platforms, loan offers or tips on saving can be individually adapted to personal habits.
School is no longer associated with a building. Plenty of Canadians take courses from places they've never even been, thanks to online learning that doesn't care about distance at all.
What makes this work isn't just video lessons. Tools that allow people to talk, edit projects together, or share live screens make group work possible, even when classmates are hundreds of kilometers away.
Free courses on anything, from languages to tech skills, are helping people level up in ways that weren't accessible before. For someone restarting their career or adjusting to life in a new country, that kind of access can be the difference between feeling stuck and moving on.
The workplace doesn't look like it used to. People complete tasks from home, public spaces, or anywhere with Wi-Fi.
A large part of this change is due to the technology operating in the background. Tasks that used to require time are being automated. That could involve tasks such as filing, tracking inventory, or flagging issues before they spiral out of control. It just frees up people to get everything done that needs actual thinking.
There are many rural and Indigenous communities in Canada that do not have proper or affordable connections. Until that happens, the digital transition won't be evenly distributed.
Some people also don't feel confident using new tech. That's why local training programs and simple tools matter; they help people to catch up without feeling overwhelmed. Cost is another issue. Not everyone can afford to buy a new phone or laptop. Community efforts and tech grants are helping, but there's still work to do to make digital access fair.
At this point, the answer is yes. While there are gaps that need to be filled, the overall shift has already been established. The pieces are falling into place, and more people are finding ways to make tech fit into their world, not the other way around.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Cybersecurity | Oct 14, 2025
Image: Freepik
The 2025 Nobel Prize in Economics was awarded to Joel Mokyr, Philippe Aghion, and Peter Howitt for showing that economies grow when they reward new ideas, open competition, and constant renewal. Their work (and recognition) explains why some economies continue to grow while others stall, or how innovation drives prosperity.
Joel Mokyr’s research reveals that progress depends on how societies treat knowledge. When Europe opened up to new ideas, rulers across Europe competed to attract inventors, scientists, and thinkers. They funded experiments, founded academies, and allowed freedom to publish and debate. This open culture created trust and collaboration, which led to faster discovery. Insight is that innovation takes off when knowledge is shared, incentives are aligned with progress, and institutions reward learning rather than control.
Philippe Aghion and Peter Howitt built the modern model that explains how this process sustains itself. Their work on creative destruction shows that growth happens when new firms and technologies replace outdated ones. Productivity increases even as some firms exit the market. They demonstrated that competition and innovation are not opposites but partners. Economies that encourage entry and tolerate failure grow faster because resources move to better ideas. Insight is that protection slows progress, but experimentation drives renewal.
Sounds familiar, right?
A popular LinkedIn post by a specialist in regulatory policy Martyn Hopper, interpreted these Nobel insights into a practical framework for today's economies. In his aptly titled LinkedIn post, “Regulating for Growth”.
Hopper explained that innovation only turns into prosperity when three things work together:
When these conditions are in place, disruption becomes productive renewal. When they are missing, it produces dislocation, stagnation, and political frustration.
Hopper’s key insight reframes regulation itself. He says the real challenge is not cutting rules but designing them to direct energy toward innovation rather than rent-extraction (read: siphoning off profits for benefit).
Regulation is the architecture that decides who can participate, how capital flows, and whether progress is rewarded or resisted. It determines whether a system produces creation or protection, renewal or capture. This makes regulation one of the most powerful economic tools for growth.
As Canada has it's back up against the wall in terms of innovation and competition policy (despite recent shifting winds), the Nobel findings and Hopper's sensibilities, business leaders and policymakers have clear takeways.
The best performing economies are those that combine competitive markets with policies that support transition. For policymakers, the lesson is that regulation must make innovation easier, not riskier. It must reward entry and experimentation, ensure fair access to finance, and help communities absorb change. Sustained success comes from openness, agility, and willingness to reinvest in new ideas. Remember, a system without the ability to expel old and add new will eventually die on the vine.
Growth is designed through the choices made about who can compete, how ideas are financed, and how regulation treats innovation. When those choices are right, economies attract investment, scale technology faster, and sustain higher productivity.
For Canada’s fintech and financial innovation community, these insights are especially timely. NCFA’s advocacy for proportionate rules, open and fair competition, and technology-driven productivity and inclusion innovation aligns directly with the Nobel research and Hopper’s interpretation.
Canada's challenge is evolving from purely risk management towards opportunity design. Regulators can accelerate innovation by creating flexible entry routes for new players, supporting data-driven compliance, and directing finance toward startups and scale-ups that drive transformation.
It's about injecting newness and opportunity which in turn will build resilience. When innovation is supported by sound regulation, it strengthens the economy’s ability to adapt, protects consumers, and expands access to capital.
Fintech, open banking, and AI can be powerful enablers of this change if the regulatory system is built for learning and collaboration rather than delay and protectionism.
The Nobel Committee recognized that growth doesn't happen by accident. It's built through systems that enable innovation, reward competition, and manage transition. Martyn Hopper’s framework shows what that looks like in practice. Smart regulation channels capital to new ideas, supports those affected by change, and keeps markets open for renewal. For Canada’s fintech sector, this is the roadmap to back that turns creative disruption into long-term competitiveness, productivity, and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 7, 2025
Image: Freepik/tonodiaz
The Indian stock market is often a reflection of investor sentiment, company fundamentals, and broader macroeconomic shifts. One of the indicators investors watch closely is the 52-week high and low levels of stocks. A stock trading near its 52-week low often sparks curiosity: Is it a bargain buy or a falling knife?
ITC has long been considered a safe bet for conservative investors. But with the stock hovering close to its 52-week low, the pressing question is: Should ITC be on your radar now? In this blog, we will explore whether investors should consider buying ITC stock at its 52-week low.
The stocks near 52 week low is the lowest price at which a stock has traded in the past year. For many investors, this is a signal that the stock may be undervalued. However, it could also indicate deeper structural challenges or declining investor confidence.
Hence, before considering ITC, it’s essential to look at its fundamentals, recent developments, and industry dynamics.
ITC has diversified revenue streams from cigarettes to FMCG, hotels, and agri-exports, which have helped it remain resilient, though growth in its non-cigarette business segments has been slower than rivals like HUL or Nestlé.
As of September 2025,the ITC share price is trading close to its 52-week low of ₹390.15, currently hovering around ₹410.65. It is still far below its 52-week peak of ₹528.50. In comparison to the broader index and its Nifty FMCG peers, it has underperformed with a decline of almost 15% in the last year.
There are several factors behind the ITC share falling to its 52-week low levels. Some of those reasons are:
Investors often rotate out of defensives like FMCG into higher-growth sectors (IT, auto, banks) when markets are bullish.
Compared to FMCG peers, ITC’s topline expansion remains moderate, particularly in branded foods and hotels.
After its multi-year rally (2021-2023), profit booking has amplified near-term declines.
Cigarettes remain under heavy scrutiny due to taxation and health regulations. Any potential tax hikes impact sentiment.
The company recently announced the demerger of its hotel business, which led to mixed reactions from the market.
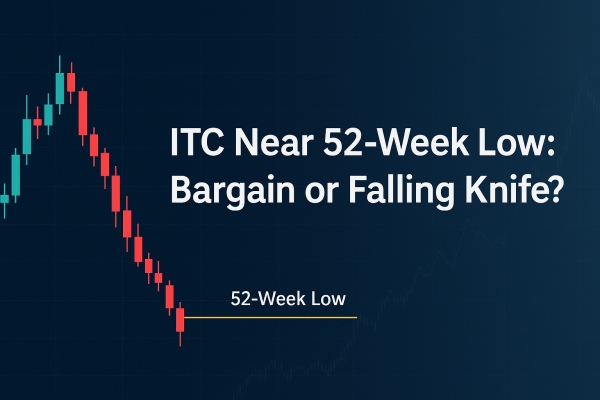
ITC Near 52 Week Low
With ITC close to its 52-week low, investors may find it to be a risky but appealing entry point. The following is a discussion of the causes of both cases:
A stock hitting its 52-week low should not be the sole reason to buy or sell; it’s a signal that requires deeper analysis. In ITC’s case, while regulatory risks and slower growth weigh on sentiment, its dividend yield, diversified business, and defensive nature make it a strong option for conservative investors.
Therefore, ITC should be on the radar of those investors who seek stability, regular dividends, and a defensive play, and investors who are chasing aggressive growth and fast-moving stocks should not consider investing in ITC at its 52-week low share price.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016
